
 Smart Home Controller Market | 2026-2036
Smart Home Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Controller Market Insights
The EU Green Deal and attendant national building performance standards is consolidating demand around controllers with native energy optimization and carbon reporting capabilities. Johnson Controls leverages its building automation heritage to anchor premium commercial-to-residential crossover deployments. Schneider Electric sustains competitive position through deep backward integration into power management silicon and enclosure manufacturing. Amazon competes on voice-first interaction density, while Apple differentiates through privacy-centric local processing architectures that reduce cloud dependency.
A smart home controller functions as the central coordination node for residential IoT ecosystems, typically incorporating multiprotocol radio arrays, edge computing capacity, and API mediation layers to unify disparate device fleets under single automation logic. These systems execute scene orchestration, conditional rule processing, and remote access tunneling for security, climate, lighting, and entertainment subsystems. Voice Assistants and Smart Hubs represent the dominant product type pairing, with hub hardware capturing the bulk of unit margin while voice interfaces drive ecosystem lock-in and recurring service attachment. Wi-Fi and Zigbee together constitute the prevailing technology stack, though Zigbee is gaining ground in retrofit scenarios where mesh reliability outperforms congested 2.4 GHz spectrums.
FCC Part 15 emissions compliance governs radio-equipped controllers in the United States, while CE marking and the EU Cybersecurity Act establish baseline product safety and data protection thresholds for European market access. China's MIIT issues compulsory certification for wireless equipment under SRRC and CMIIT regimes, creating non-tariff barriers that favor domestic hub manufacturers. Stakeholders must monitor evolving interoperability mandates from standards bodies and national regulators, as fragmented protocol governance threatens to segment addressable markets and force redundant SKU strategies across jurisdictions.
Market Dynamics
Protocol fragmentation is forcing controller manufacturers to engineer multiprotocol silicon stacks that bridge Zigbee, Thread, and proprietary ecosystems simultaneously, raising R&D burn rates while compressing time-to-market windows.
Growth Catalysts
- EU Green Deal building retrofits:National efficiency mandates in Germany, France, and Italy require connected energy management infrastructure, driving hub procurement for carbon reporting compliance.
- MIIT interoperability standards:China's compulsory certification regime under SRRC and CMIIT is consolidating domestic supply chains around unified gateway architectures.
- Multifamily portfolio centralization:Residential property managers are deploying unified controller systems across apartment buildings to reduce per-unit maintenance overhead.
Market Restraints
- Silicon supply concentration:Radio chipset fabrication concentrates in Taiwan and South Korea, exposing hub manufacturers to geopolitical disruption and allocation constraints.
- FCC Part 15 testing costs:Radio emissions certification for the United States market adds six-figure fixed costs per SKU, disadvantaging smaller hardware entrants.
- Wi-Fi spectrum congestion:Dense urban 2.4 GHz interference degrades reliability in retrofit installations, limiting addressable apartment stock.
Strategic Opportunities
- Matter protocol convergence:The unified connectivity standard is collapsing ecosystem silos, enabling cross-brand automation that reduces consumer switching friction.
- Edge AI processing:On-device inference chips are enabling local voice recognition and scene prediction without cloud dependency, appealing to privacy-sensitive households.
- Utility demand response programs:State-level grid flexibility incentives in California and Texas are attaching recurring revenue streams to thermostat and load controller integration.
Industry Challenges
- Firmware security maintenance:Long hardware lifecycles require sustained patching against evolving CVE disclosures, straining OEM software engineering capacity.
- Legacy system integration:Proprietary building automation protocols in existing commercial-to-residential conversions demand costly protocol gateway development.
- Interoperability testing complexity:Certification against multiple ecosystem certification programs (Works with Alexa, HomeKit, Google Home) extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Controller Market |
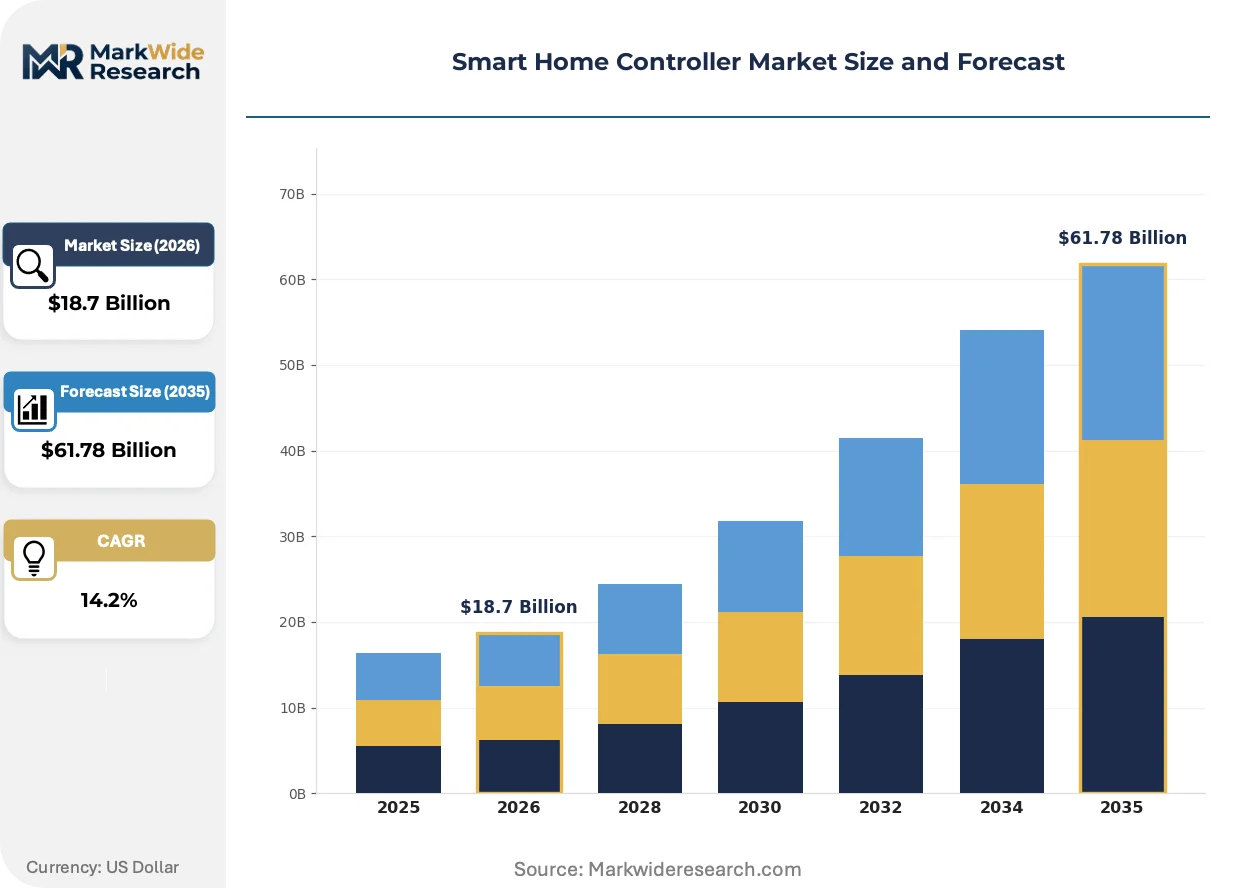
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Hubs, Voice Assistants, Mobile Apps, Remote Controls Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Homeowners, Renters, Property Managers, Contractors Integration Level: Full Integration, Limited Integration, Standalone, DIY |
| Companies Covered | Johnson Controls, Schneider Electric, Honeywell International, Amazon, Apple, Siemens, ASSA ABLOY, Samsung Electronics, Resideo Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Controller Market Trends and Innovations
Edge computing architectures are redistributing automation intelligence from cloud servers to local controller hardware, reducing latency and addressing data sovereignty concerns. This shift is compressing the traditional hub-to-cloud hierarchy.
Thread radio modules with built-in mesh networking stacks are automating device onboarding and self-healing topology management. Multifamily developers in Texas and Florida are specifying Thread-native controllers for new construction to eliminate truck rolls for connectivity troubleshooting. The technology is automating infrastructure deployment that previously required specialized technician labor.
The EU Cybersecurity Act and attendant CE marking requirements for IoT products are mandating vulnerability disclosure processes and secure-by-design hardware architectures. Manufacturers targeting European households must now embed hardware security modules and attestation capabilities from initial silicon design. Commercial-grade controller vendors with existing cybersecurity certifications are extending product lines downward into residential segments.
Subscription unbundling is separating hardware margins from recurring service revenue. Property technology platforms are white-labeling controller hardware while monetizing tenant-facing mobile applications and energy optimization analytics separately. This pattern is most visible in Germany and the Netherlands where rental housing platforms aggregate sufficient unit density to justify custom software development.
Smart Home Controller Market Segmentation
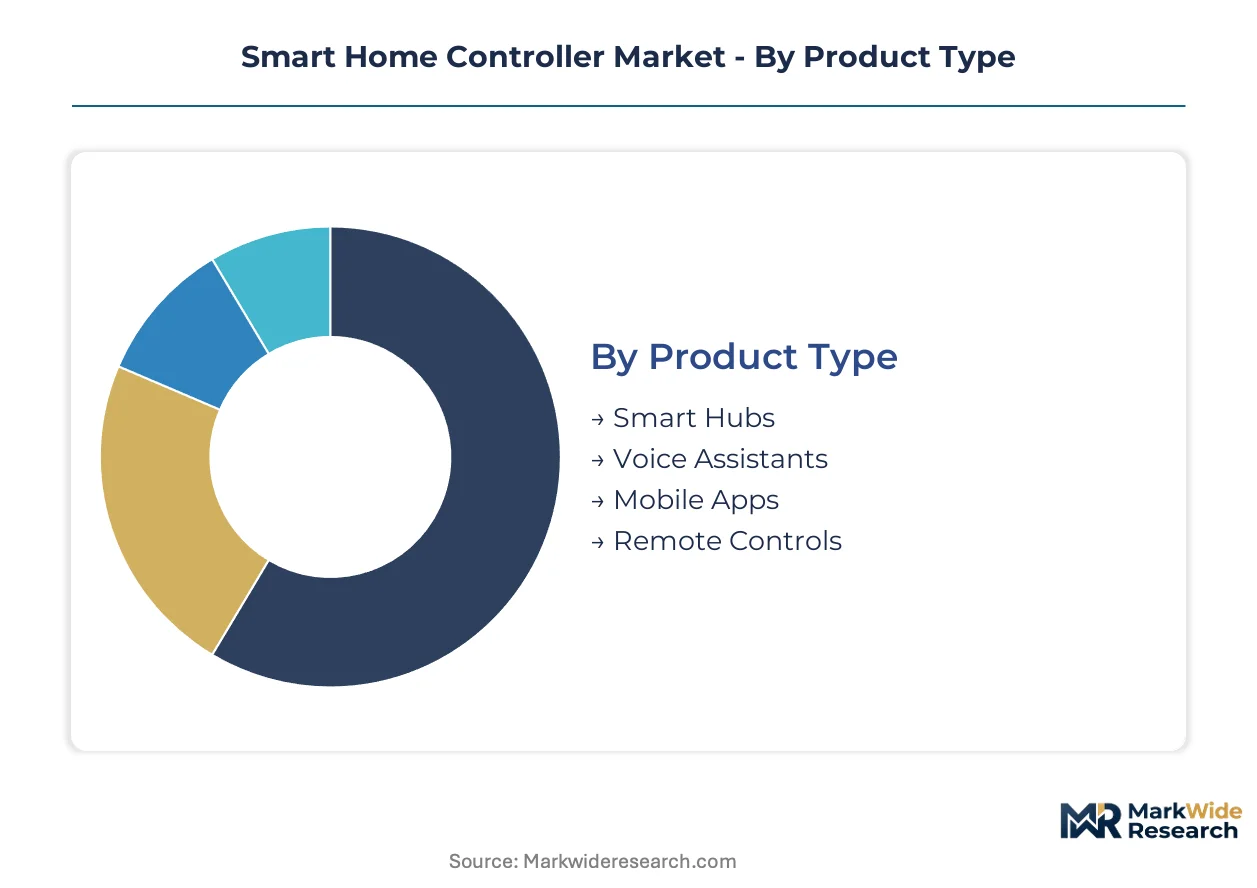
Smart home controller purchasing decisions hinge on protocol compatibility, installation complexity, and ecosystem lock-in risk. Segmentation reveals how hardware margins concentrate in hub infrastructure while voice interfaces and mobile software capture recurring service attachment.
Product Type:
Buyers prioritize ecosystem coherence and upgrade pathways when selecting controller form factors.
- Smart Hubs:Centralized multiprotocol hardware incorporating Zigbee, Thread, and Wi-Fi radios with local edge processing. Demand clusters in Germany and the Netherlands where rental housing platforms specify hub-native energy analytics for carbon compliance.
- Voice Assistants:Far-field microphone arrays with cloud-connected natural language processing. Households in Texas and Florida favor these for hands-free scene control, though privacy concerns are accelerating on-device inference adoption.
- Mobile Apps:Smartphone-based control interfaces requiring no dedicated hardware. Contractors in multifamily new construction specify these for cost-sensitive budget tiers.
- Remote Controls:Physical button interfaces with infrared and RF transmission for legacy appliance integration. Aging homeowner demographics in Japan sustain demand for tactile operation.
Volume sits with Smart Hubs; growth tilts toward Voice Assistants.
Technology:
Radio protocol selection determines mesh reliability, power consumption, and certification cost exposure.
- Wi-Fi:Ubiquitous 2.4 GHz and 5 GHz connectivity leveraging existing residential infrastructure. Dense urban deployments in China face spectrum congestion that degrades thermostat and camera responsiveness.
- Zigbee:Low-power mesh networking with self-healing topology. Retrofit installations across Italy and France specify Zigbee for building efficiency retrofits where concrete construction attenuates Wi-Fi signals.
- Z-Wave:Sub-GHz proprietary mesh with mandated interoperability testing. North American security system installers favor Z-Wave for alarm panel integration and FCC Part 15 compliance predictability.
- Bluetooth:Point-to-point and mesh variants for proximity-based device commissioning. Smart lock manufacturers in South Korea embed Bluetooth for smartphone key sharing without hub dependency.
Deployment scale favors Wi-Fi; retrofit reliability is climbing fastest with Zigbee.
End User:
Customer type dictates procurement channel, support burden, and lifetime value calculation.
- Homeowners:Individual purchasers seeking permanent installation with customization depth. German single-family households drive premium controller sales with native solar and heat pump integration requirements.
- Renters:Transient residents prioritizing non-invasive installation and portability. Dutch rental platforms aggregate renter demand for white-label controller subscriptions.
- Property Managers:Portfolio-scale buyers standardizing across multifamily units. Texas and Florida developers specify Thread-native systems to eliminate connectivity truck rolls.
- Contractors:Installation professionals bundling controllers with electrical and HVAC work. Italian retrofit specialists procure CE-marked hubs with pre-configured energy reporting for EPC compliance.
Revenue concentration rests with Property Managers; fastest expansion is occurring among Renters.
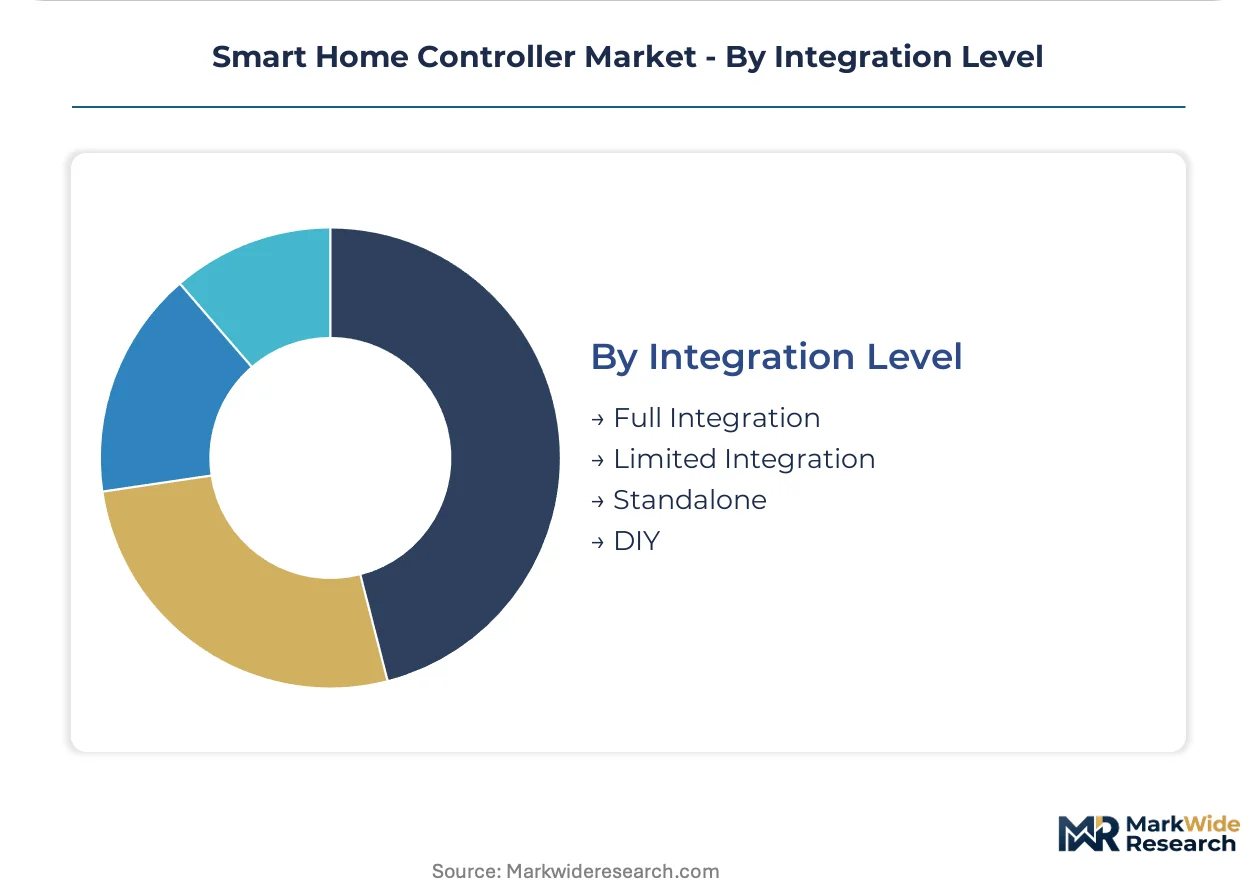
Integration Level:
Installation sophistication determines margin structure and customer acquisition cost.
- Full Integration:Whole-home automation with centralized programming and professional monitoring. High-net-worth households in Switzerland specify these for estate-wide security and climate orchestration.
- Limited Integration:Subsystem-specific control for lighting or climate only. French apartment renovators select these for phased smart home upgrades under constrained budgets.
- Standalone:Single-device controllers without ecosystem expansion capability. Japanese seniors purchase infrared remotes for air conditioner operation without smartphone dependency.
- DIY:Self-installed kits with app-guided commissioning and community support forums. Tech-forward homeowners in California favor these for Matter protocol experimentation.
Margin capture concentrates in Full Integration; volume expansion is strongest in DIY.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller fabrication concentrates in Taiwan and South Korea, while consumption clusters in Germany, China, and the United States where building efficiency mandates and smart city investments drive procurement volumes.
United States
Multifamily developers in Texas and Florida specify Thread-native controllers to eliminate connectivity truck rolls for new construction. FCC Part 15 emissions compliance adds six-figure fixed costs per SKU, filtering smaller hardware entrants from the market. Silicon Valley clusters anchor voice-first ecosystem development, with Amazon and Apple anchoring competitive positioning through differentiated interaction architectures.
Germany
Rental housing platforms aggregate sufficient unit density to justify white-label controller subscriptions with separate energy analytics monetization. The EU Green Deal and national building efficiency mandates require connected infrastructure for carbon reporting compliance. Bavarian industrial automation heritage feeds commercial-to-residential crossover deployments from established building technology vendors.
China
Massive smart city investments drive hub and gateway procurement at scale across municipal infrastructure projects. MIIT standards for IoT interoperability under SRRC and CMIIT regimes consolidate domestic supply chains around unified gateway architectures. Shenzhen and Shanghai clusters concentrate hardware manufacturing with backward integration into radio module production.
France
Apartment renovators select limited-integration controllers for phased smart home upgrades under constrained budgets. CE marking and the EU Cybersecurity Act establish baseline product safety and data protection thresholds for market access. The Île-de-France region anchors demand for native energy optimization capabilities in commercial-to-residential conversions.
Italy
Retrofit specialists procure CE-marked hubs with pre-configured energy reporting for Energy Performance Certificate compliance. Concrete construction in urban centers attenuates Wi-Fi signals, driving Zigbee specification for mesh reliability. Lombardy and Veneto clusters concentrate contractor networks bundling controllers with electrical and HVAC installation work.
Smart Home Controller Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with building automation heritage. Tiering separates premium commercial-to-residential crossover vendors from mass-market consumer electronics platforms and specialized security system integrators. Three archetypes dominate: building technology incumbents leveraging certification depth, consumer ecosystem platforms competing on voice interaction density, and silicon-integrated power management specialists. M&A activity concentrates on protocol gateway capabilities and edge AI silicon, while geographic expansion targets EU Green Deal retrofit corridors and Chinese smart city procurement channels.
Within the building technology tier, Johnson Controls and Schneider Electric exemplify archetypes anchored in commercial automation heritage with residential extension strategies. Amazon occupies a position representing voice-first ecosystem lock-in models, while Apple exemplifies privacy-centric local processing differentiation. Samsung Electronics and Siemens sit within diversified conglomerate structures spanning component fabrication through system integration. ASSA ABLOY, Resideo Technologies, and Honeywell International represent security-system-origin specialists extending into broader home automation portfolios.
| Leading Market Players |
|---|
| Johnson Controls |
| Schneider Electric |
| Honeywell International |
| Amazon |
| Apple |
| Siemens |
| ASSA ABLOY |
| Samsung Electronics |
| Resideo Technologies |
| Others |
Pricing and Supply Chain Analysis
Multifamily property managers in Texas and Florida anchor volume procurement, compressing hub hardware margins while elevating recurring SaaS analytics tiers as the primary value capture mechanism. Their portfolio-scale purchasing power forces OEMs toward three-tier pricing structure across premium, standard, and economy levels, with certification depth determining tier placement.
Pricing Analysis
Margin tightening in hub hardware reflects silicon allocation constraints from Taiwan and South Korea foundries. Pricing stratifies across premium, standard, and economy tiers based on CE marking tier and after-sales service bundling. Cost compression accelerates in Wi-Fi-native controllers as Zigbee mesh reliability commands modest premiums. DIY installers in California exhibit highest price sensitivity; Swiss estate integrators show lowest.
Supply Chain Analysis
Dual-sourcing mandates from German rental platforms and Chinese municipal procurement require qualified secondary suppliers for radio modules and edge processors. Fabrication concentrates in Taiwan, South Korea, and Shenzhen clusters. Controller production draws from ARM-based SoCs, multiband RF front-ends, and flash memory. Single-source vulnerability in advanced node silicon threatens allocation. Distribution runs through building technology distributors and direct OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Cybersecurity Act and attendant CE marking requirements erect a cost-of-compliance barrier that favors incumbent building technology vendors with existing certification infrastructure. New entrants face six-figure fixed testing costs per SKU that filter speculative hardware plays.
For Market Incumbents: Hedge against Matter protocol commoditization by deepening backward integration into power management silicon and enclosure manufacturing. Acquire edge AI inference specialists to defend premium positioning against voice-first platform erosion. Prioritize firmware security engineering capacity to sustain long-lifecycle patching obligations. For New Entrants and Emerging Players: Begin with white-label hub supply to Dutch and German rental housing platforms, where aggregated unit density justifies custom energy analytics development. Target DIY segments in California for Matter protocol experimentation with minimal certification burden. Lead with mobile app-first control interfaces to bypass hardware margin compression. For Investors and Strategic Acquirers: Distressed-cycle entries favor commercial-grade controller vendors with existing cybersecurity certifications extending downward into residential segments. Long-term viability centers on recurring service attachment rates rather than hardware shipment volumes. Watch utility demand response program enrollment in California and Texas as inflection signal for thermostat and load controller integration value.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-brand interoperability collapses ecosystem silos and reduces consumer switching friction. |
| Edge AI Silicon Acquisition | On-device inference enables local voice recognition without cloud dependency for privacy-sensitive households. |
| Utility Partnership Development | Grid flexibility programs in California and Texas attach recurring revenue to thermostat integration. |
| Firmware Security Engineering Expansion | Sustained CVE patching capacity defends against long hardware lifecycle vulnerability exposure. |
| Thread-Native Controller Specification | Multifamily developers in Texas and Florida eliminate truck rolls through self-healing mesh topology. |
Research Methodology
Document review covered FCC Part 15 filings, CE marking directives, MIIT SRRC certifications, and hyperscaler IoT platform disclosures, complemented by interviews with building automation engineering directors, multifamily property technology procurement leads, smart home platform product managers, and radio module supply chain specialists. Secondary validation drew from customs trade data, EPC compliance databases, and smart city investment trackers. Bottom-up unit shipment estimates triangulated against top-down addressable housing stock calculations.
Segment-level outputs across product type, radio protocol, end-user archetype, and integration complexity dimensions were generated through the projection horizon. CAGRs derived from fitted growth curves against historical smart home device adoption patterns and building retrofit mandate timelines. Key inputs included MIIT procurement volume disclosures, EU Green Deal retrofit corridor funding allocations, and utility demand response program enrollment trajectories.
Protocol fragmentation resolution, silicon allocation disruption, and cybersecurity certification timeline delays are the dominant revision risks. Deviation in MIIT standard enforcement stringency would shift the Chinese procurement outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Japan Coal Market
Others
Global ESD Protection Devices Market
Others
United States Printed Signage Market
Others
Embedded Computer Market
Others
Europe Flow Battery Market
Others
Kuwait Retail Market
Others
Bamboo Straws Market
Others
Italy Feed Additives Market
Others
Over the Top Devices and Services Market
Others
Construction Fabrics Market
Others
Japan Automotive LED Lighting Market
Others
DIY Smart Home Market
Others
Convenience Stores Market
Others
Process Spectroscopy Market
Others
Global Cigarette Packaging Market
Others
Convertible Shipper Display Market