
 Digital Mortgage Software Market | 2026-2036
Digital Mortgage Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Mortgage Software Market Analysis
SO 27001 certification is reorganizing competitive dynamics in digital mortgage software by establishing information security management as a prerequisite for enterprise procurement. ICE Mortgage Technology (Encompass) anchors its position through deep integration with GSE submission pathways and correspondent lending workflows. Finastra (Mortgagebot) leverages its banking software heritage to sustain cross-sell momentum into credit union and community bank channels. MeridianLink Mortgage differentiates through API-first architecture that supports embedded lending partnerships beyond traditional mortgage origination.
Digital mortgage software encompasses cloud-native and on-premise platforms that automate loan origination, underwriting, closing, and secondary market delivery through rules engines, e-signature orchestration, and real-time compliance checking against investor and regulatory guidelines. Loan origination systems dominate current spending as lenders replace aging point solutions with unified platforms that collapse origination timelines from 45 days to under 20 days. Cloud-based deployment represents the fastest-expanding segment, though on-premise configurations persist among tier-one banks with bespoke risk management frameworks and data residency requirements. Mortgage processing software captures concentrated margin pools where robotic process automation reduces manual document verification costs by substantial multiples.
The US Consumer Financial Protection Bureau, FHA, and Fannie Mae collectively shape product roadmaps through mandatory disclosure timing, quality control sampling rates, and data delivery standards that software must embed natively. The European Banking Authority's digital operational resilience framework and GDPR data handling rules extend compliance obligations for vendors serving EU lenders. Stakeholders must monitor how open banking mandates and real-time payment infrastructure in key markets will force recalibration of closing fund disbursement workflows and borrower authentication protocols.
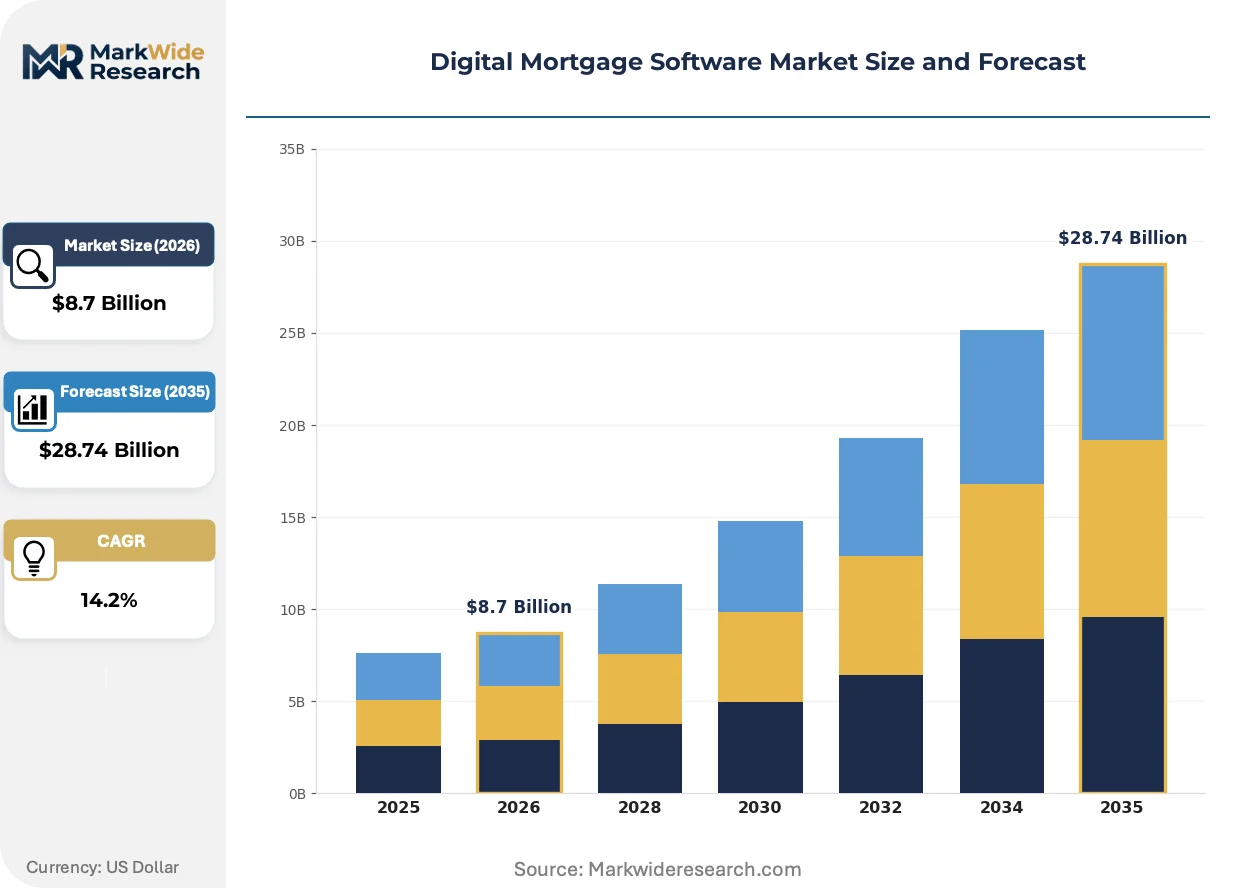
Market Dynamics
ISO 27001 certification is restructuring procurement criteria as lenders demand auditable information security management systems before contract execution. Cloud-native architectures are displacing legacy mainframe installations across tier-two and tier-three lending institutions.
Growth Catalysts
- CFPB Servicing Rule Updates:The US Consumer Financial Protection Bureau's revised mortgage servicing regulations mandate enhanced loss mitigation workflows. Lenders must upgrade software to automate borrower communication timelines and escrow analysis.
- Credit Union Modernization:Cooperative financial institutions are replacing 1990s-era core banking modules with unified origination platforms. This segment now drives disproportionate new license growth.
- API-First Architecture:Open banking standards are enabling embedded lending partnerships. Software vendors with robust integration layers capture revenue from non-traditional mortgage distribution channels.
Market Restraints
- Implementation Cost Concentration:Full platform replacements require 18-24 month deployment cycles. Mid-size lenders face capital allocation constraints against competing technology priorities.
- Data Residency Requirements:Tier-one banks with bespoke risk frameworks maintain on-premise configurations. Cloud migration stalls where supervisory authorities mandate physical data location verification.
- Legacy System Entrenchment:Proprietary document management systems from the 2000s resist standard API connectivity. Custom integration work inflates total cost of ownership by substantial multiples.
Strategic Opportunities
- Secondary Market Automation:Investor data delivery standards from Fannie Mae and Freddie Mac create openings for specialized compliance modules. Vendors can unbundle quality control sampling and delivery workflow tools.
- EU Digital Operational Resilience:The European Banking Authority's DORA framework extends vendor oversight requirements. Software providers with pre-certified operational continuity architectures gain first-mover positioning.
- Mobile-First Borrower Experience:Smartphone-native application interfaces are displacing web-portal submissions. Lenders targeting first-time homebuyers prioritize platforms with native iOS and Android document capture.
Industry Challenges
- Specialized Talent Scarcity:Mortgage technology implementation requires hybrid expertise in regulatory compliance and cloud architecture. Competition from fintech verticals compresses available hiring pools.
- Multi-System Integration Complexity:Lenders operate average of seven distinct point solutions across origination-to-servicing lifecycle. API orchestration failures at handoff points generate operational risk and borrower friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Mortgage Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loan Origination System, Document Management Software, Mortgage Processing Software, Risk Management Tools Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Banks, Credit Unions, Mortgage Brokers, Financial Institutions Integration Level: API Integration, Middleware Solutions, Standalone Platforms, Third-Party Services |
| Companies Covered | Calyx Point, Zeitro, Wildnet Edge, LeewayHertz, Tuvoc, ICE Mortgage Technology (Encompass), MeridianLink Mortgage, Zco Corporation, Finastra (Mortgagebot), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Mortgage Software Market Emerging Trajectories
Artificial intelligence is penetrating document classification and income verification workflows. Regulatory technology modules are hardening against evolving disclosure timing requirements. Borrower authentication protocols are shifting toward biometric and device-based identity confirmation.
Machine learning-based document intelligence is decomposing traditional manual verification steps in loan underwriting. Credit unions and community banks are adopting these tools at accelerated pace to match larger competitors' cycle times. The technology is decomposing the 45-day origination timeline into sub-20-day execution windows, compressing vendor competitive differentiation around speed metrics.
The US Consumer Financial Protection Bureau's updated mortgage servicing rules are mandating specific loss mitigation notification sequences. Software vendors must embed these timing requirements directly into workflow engines rather than configuring them as customizable parameters. Servicing platforms serving US lenders are responding by hard-coding compliance checkpoints that cannot be bypassed by user override.
Buyer decision criteria are elevating information security certification above feature parity in vendor selection. RFP processes now require ISO 27001 attestation before functional evaluation begins. This pattern is most visible among US regional banks with $10-50 billion asset bases, where procurement committees include chief risk officers in technology acquisition votes.
Digital Mortgage Software Market Segmentation
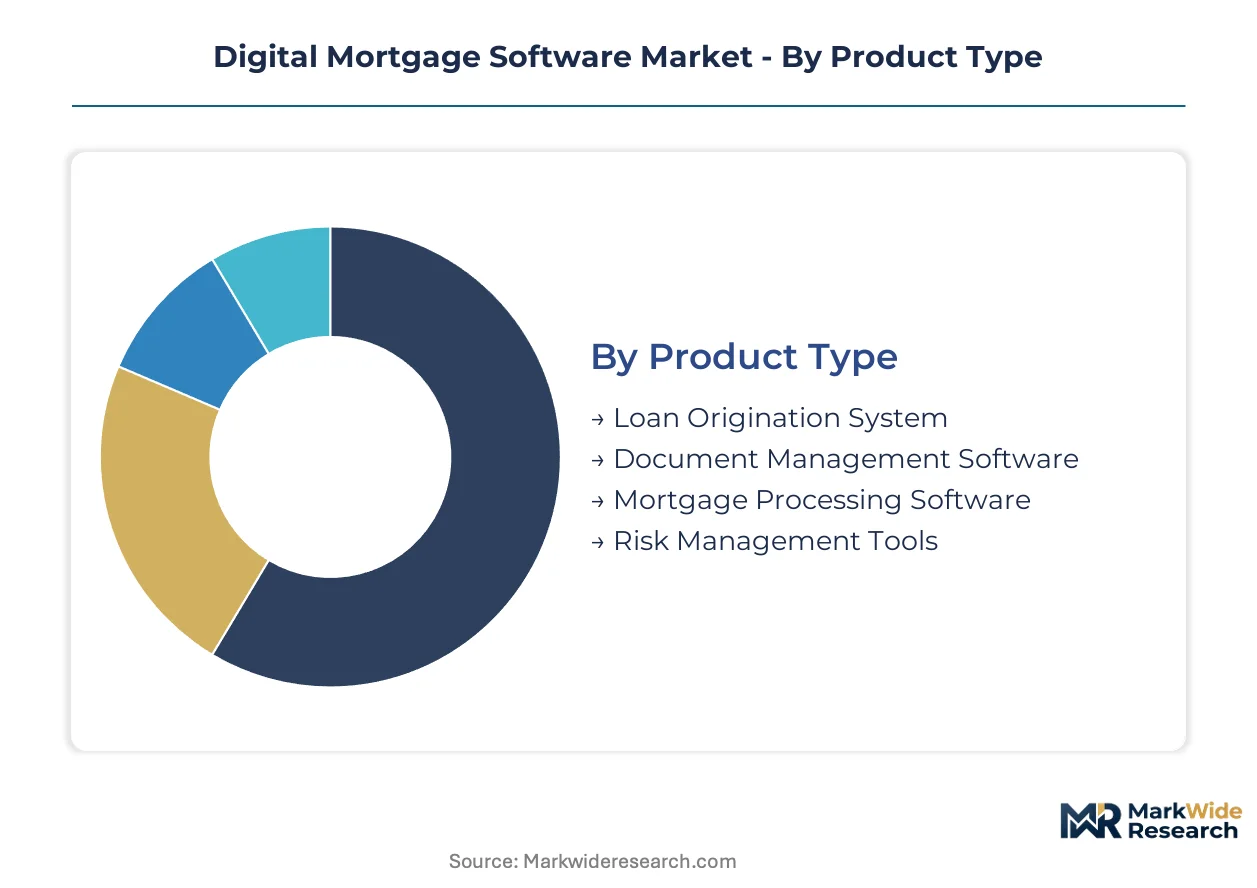
Segmentation reveals how procurement patterns diverge between institutional buyers with legacy infrastructure constraints and agile competitors pursuing cloud-native speed advantages. Lenders select software architectures based on regulatory jurisdiction, balance sheet scale, and secondary market integration requirements.
Product Type:
Domestic procurement concentrates in loan origination and processing modules, while export-led demand favors risk management tools serving multinational banking conglomerates.
- Loan Origination System:Unified platforms automate borrower intake, underwriting workflows, and disclosure generation through embedded rules engines. US regional banks and credit unions drive replacement demand as they retire 1990s-era point solutions. These systems anchor vendor revenue through multi-year implementation contracts and ongoing compliance update subscriptions.
- Document Management Software:Cloud repositories with optical character recognition and audit trail capabilities replace paper-based collateral files. European lenders under GDPR pressure prioritize these tools for data retention and subject access request automation. The segment faces margin compression from standalone e-signature vendors unbundling core functionality.
- Mortgage Processing Software:Robotic process automation modules reduce manual verification costs in income and asset validation workflows.
- Risk Management Tools:Predictive analytics platforms model prepayment speeds, default probabilities, and concentration limits for portfolio managers.
Loan origination systems hold the largest share; momentum sits with mortgage processing software.
Deployment:
Cost tier stratification separates enterprise buyers with captive data centers from mid-market lenders seeking operational expenditure flexibility.
- Cloud-Based:Multi-tenant architectures with automatic regulatory patch deployment serve credit unions and community banks lacking internal IT capacity. The US Consumer Financial Protection Bureau's disclosure timing updates propagate instantly without on-site technician visits. Vendors capture recurring revenue through per-loan pricing models that scale with origination volume.
- SaaS:Browser-native interfaces with mobile document capture prioritize first-time homebuyer experience over feature depth. Mortgage brokers and correspondent lenders adopt these tools for rapid deployment without capital expenditure approval cycles. API marketplaces extend functionality through verified third-party integrations.
- On-Premise:Tier-one banks with bespoke risk frameworks maintain physical control over borrower data and custom algorithm configurations.
- Hybrid:Split architectures keep sensitive underwriting data on-site while outsourcing borrower-facing portals to cloud infrastructure.
Cloud-based deployment holds the largest share; momentum sits with SaaS delivery models.
End User:
Customer type determines feature prioritization, with deposit-taking institutions requiring core banking integration and non-bank lenders emphasizing speed-to-close metrics.
- Banks:Full-service institutions demand end-to-end platforms spanning retail, commercial, and correspondent lending channels. Their procurement committees include chief risk officers who mandate ISO 27001 certification before functional evaluation. Implementation timelines stretch 18-24 months due to legacy system interdependencies.
- Credit Unions:Cooperative financial institutions modernize at accelerated pace to compete with larger lenders on borrower experience. Their vendor selection emphasizes member service integration and community-specific product configurations. This segment now drives disproportionate new license growth industry-wide.
- Mortgage Brokers:Intermediary lenders prioritize wholesale platform connectivity and rapid investor delivery capabilities.
- Financial Institutions:Insurance companies and investment firms entering mortgage origination seek modular tools for specific workflow segments.
Banks hold the largest share; momentum sits with credit unions.
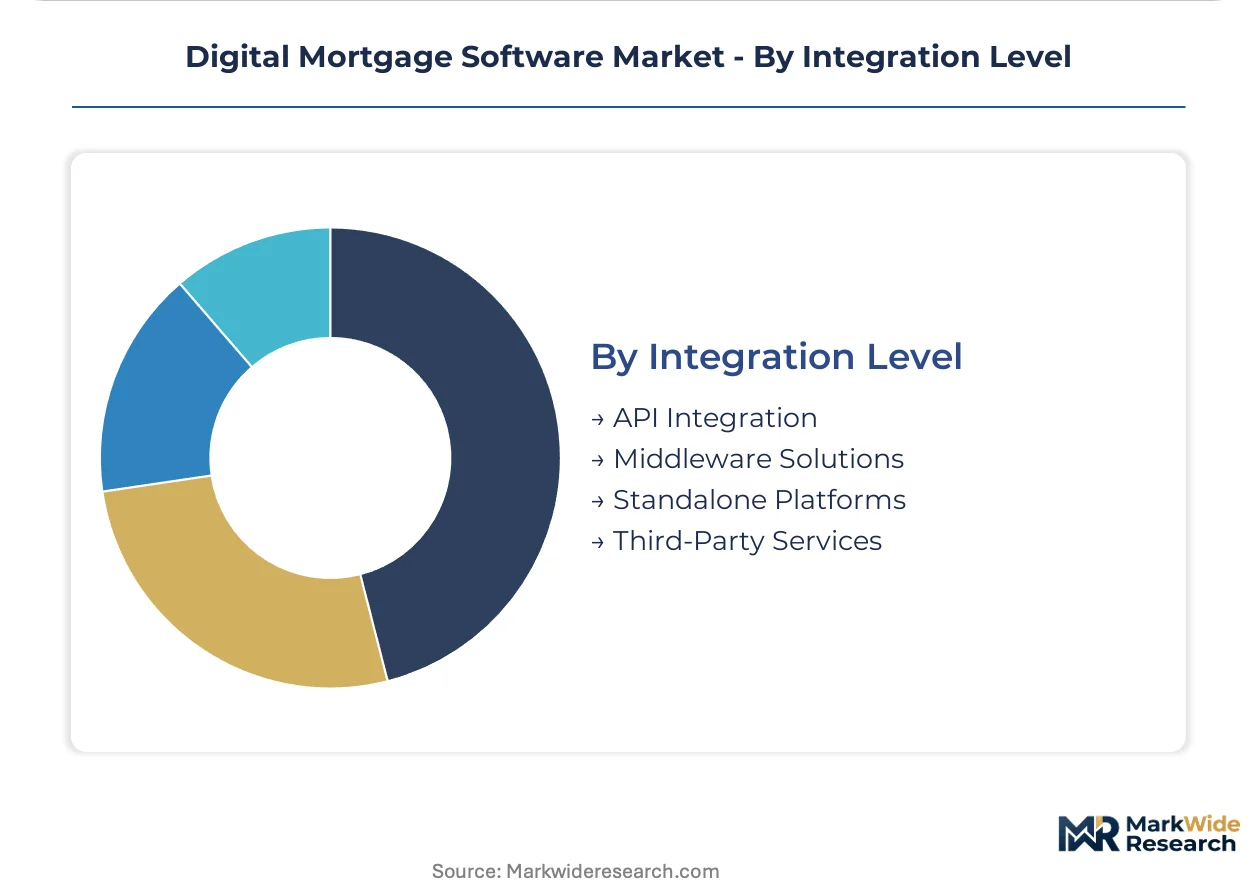
Integration Level:
Maturity curves separate early adopters with embedded lending architectures from institutions maintaining decade-old middleware configurations.
- API Integration:RESTful interfaces enable real-time data exchange between origination platforms, credit bureaus, valuation services, and investor portals. Fintech partnerships and embedded lending arrangements require these capabilities for white-label mortgage products. Vendors with robust integration layers capture revenue from non-traditional distribution channels.
- Standalone Platforms:All-in-one systems appeal to lenders seeking to collapse multiple point solutions into unified vendor relationships. These configurations reduce API orchestration failures at handoff points between origination lifecycle stages. Mid-size lenders favor this approach to constrain total cost of ownership.
- Middleware Solutions:Enterprise service buses translate between proprietary data formats in heterogeneous technology environments.
- Third-Party Services:Managed integration providers handle custom connectivity work for lenders lacking internal development resources.
Standalone platforms hold the largest share; momentum sits with API integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' ACH network and correspondent banking infrastructure underwrite its dominance in digital mortgage software demand. Regulatory complexity and lender digitization timelines outpace other national markets. Cloud data center clusters in Northern Virginia and Oregon anchor vendor service delivery for North American lenders.
United States
The CFPB's updated mortgage servicing rules mandate enhanced loss mitigation workflows that drive software replacement cycles. FHA and Fannie Mae data delivery standards shape product roadmaps through mandatory disclosure timing requirements. Texas and Florida credit unions are modernizing legacy systems at accelerated pace to compete with larger lenders on borrower experience.
United Kingdom
Open banking mandates and real-time payment infrastructure force recalibration of closing fund disbursement workflows. The FCA's operational resilience requirements extend vendor oversight obligations for software serving UK lenders. London's fintech cluster anchors embedded lending partnerships that demand API-first mortgage platforms.
Germany
Sparkassen and cooperative banks pursue digitization to defend market share against direct mortgage banks. BaFin's outsourcing guidelines impose strict continuity requirements on cloud-deployed lending software. Frankfurt's banking concentration drives demand for risk management tools serving portfolio managers across the Mittelstand.
Canada
Credit union modernization mirrors US cooperative patterns with concentrated replacement of 1990s-era core modules. OSFI's technology risk management guidelines shape procurement criteria for tier-one banks maintaining hybrid architectures. Toronto-Waterloo corridor fintech activity generates embedded lending demand for white-label mortgage products.
Australia
APRA's CPS 230 operational risk standards elevate information security certification in lender procurement processes. Open banking regime implementation forces authentication protocol upgrades across origination platforms. Sydney and Melbourne mortgage broker networks prioritize rapid deployment tools without capital expenditure approval cycles.
Digital Mortgage Software Market Vendor Landscape
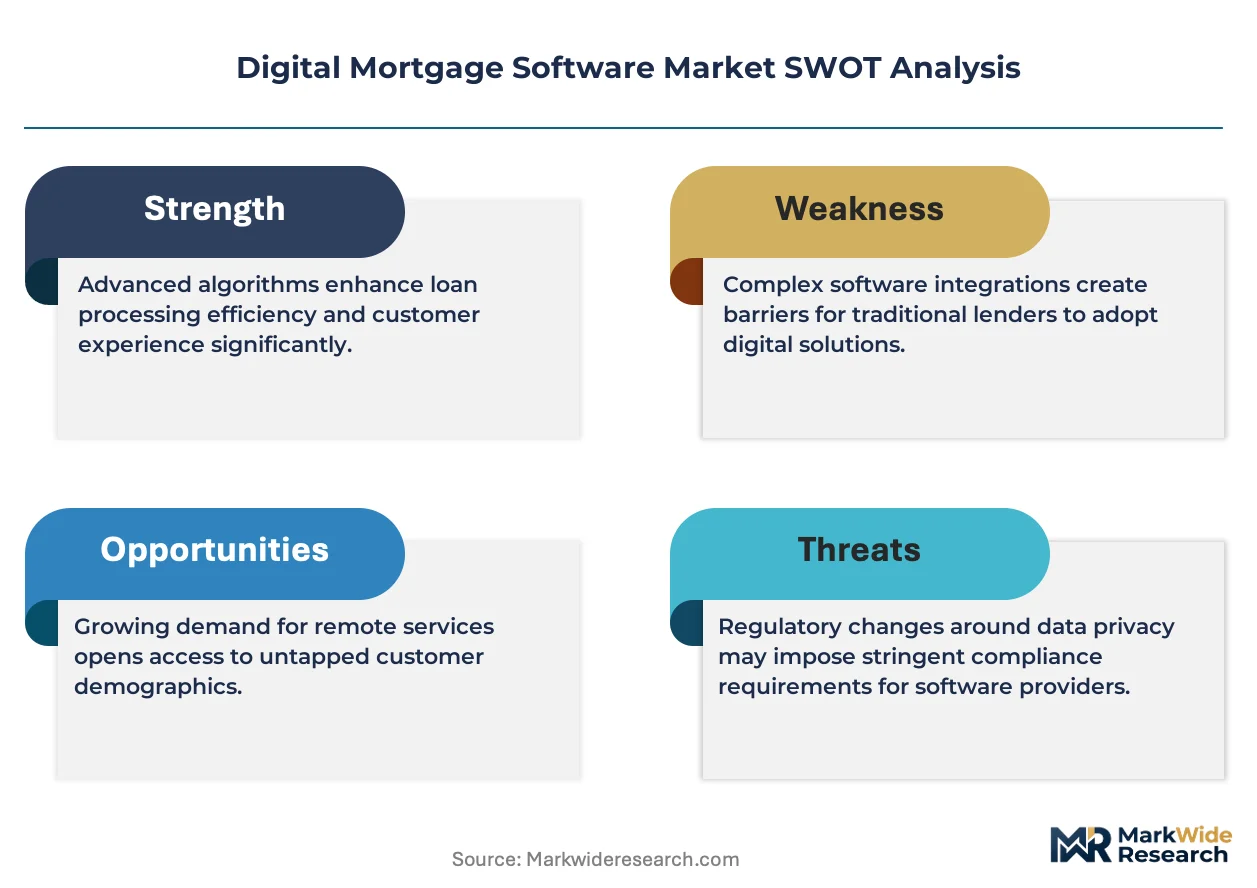
Listed leaders compete with private specialists across deployment model and integration depth dimensions. The vendor base stratifies between cloud-native entrants and legacy platform incumbents with correspondent lending heritage. Three archetypes dominate: banking software conglomerates with cross-sell momentum, pure-play mortgage specialists with GSE integration depth, and API-first platforms enabling embedded lending partnerships. Competitive moves concentrate on ISO 27001 certification races and vertical capability acquisitions.
Within the banking software tier, Finastra exemplifies cross-sell momentum from core banking relationships into mortgage channels. ICE Mortgage Technology anchors the specialist segment through Encompass platform recognition among US correspondent lenders. MeridianLink occupies the API-first position, representing the architectural shift toward embedded lending partnerships beyond traditional origination. These three patterns illustrate how procurement criteria are elevating information security certification and integration flexibility above legacy feature parity.
| Leading Market Players |
|---|
| Calyx Point |
| Zeitro |
| Wildnet Edge |
| LeewayHertz |
| Tuvoc |
| ICE Mortgage Technology (Encompass) |
| MeridianLink Mortgage |
| Zco Corporation |
| Finastra (Mortgagebot) |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at cloud data centers in Northern Virginia and Oregon shapes vendor cost structures and price floors across deployment tiers. Tier-one banks with captive data centers extract scale advantages that compress margins for mid-market SaaS providers serving credit unions and community banks. This scale asymmetry forces pricing stratification across enterprise, mid-market, and entry-level segments.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with per-loan pricing models scaling from entry-level credit union deployments to enterprise correspondent lending platforms. Price differentiation rests on ISO 27001 certification status and customization depth for legacy core banking integration. Cost compression in the mid-market tier intensifies because robotic process automation vendors unbundle document management functionality. Credit unions exhibit highest price sensitivity due to capital allocation constraints against competing technology priorities, while tier-one banks prioritize risk framework compatibility over unit economics.
Supply Chain Analysis
Inbound logistics costs for specialized server hardware and GPU clusters serving AI-enabled underwriting modules have stabilized following pandemic-era semiconductor shortages. Software development labor concentrates in the United States, India, and Poland, with regulatory compliance expertise anchored in US and UK financial centers. The supply chain draws from cloud infrastructure providers, specialized fintech talent pools, and third-party API connectivity vendors. Single-source vulnerability sits with hyperscaler cloud platforms that host multi-tenant mortgage origination architectures. Distribution runs through direct enterprise sales teams, banking software channel partners, and API marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital mortgage software market exhibits cyclical recovery characteristics as credit union modernization waves and CFPB compliance deadlines synchronize replacement demand. Interest rate volatility and origination volume fluctuations create procurement timing windows that favor vendors with flexible deployment models.
For Market Incumbents: Fortify correspondent lending integration depth against API-first challengers by embedding GSE submission pathways as non-replicable workflow checkpoints. Invest in ISO 27001 certification maintenance as procurement committees elevate information security attestation above feature parity. Capacity addition in credit union-centric service delivery addresses the segment driving disproportionate new license growth.
For New Entrants and Emerging Players: Embedded lending partnership enablement represents a service-layer gap where legacy platform incumbents under-serve fintech distribution channels. Target mortgage broker networks and correspondent lenders with rapid-deployment SaaS tools that bypass capital expenditure approval cycles. White-label API architectures penetrate fastest among non-bank lenders seeking modular origination capabilities without core banking integration complexity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with per-loan pricing models and automatic regulatory patch subscriptions that embed compliance updates into base contracts. Long-term viability favors platforms with pre-certified operational continuity architectures aligned to EU DORA and US CFPB servicing rule evolution. Monitor credit union technology budget acceleration as an inflection indicator for mid-market SaaS expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Investment | CFPB-mandated procurement criteria now require attestation before functional vendor evaluation begins. |
| API-First Architecture Development | Open banking standards enable embedded lending partnerships beyond traditional mortgage origination channels. |
| Credit Union Channel Expansion | Cooperative financial institutions drive disproportionate new license growth through legacy system replacement. |
| Robotic Process Automation Integration | Machine learning document intelligence compresses origination timelines from 45 days to sub-20-day execution. |
| EU DORA Compliance Pre-Certification | European Banking Authority operational resilience frameworks extend vendor oversight obligations for software providers. |
Methodological Framework
Desk research of SEC filings from banking software vendors, CFPB regulatory guidance documents, and credit union technology survey data preceded structured interviews with chief technology officers at regional banks, mortgage operations executives at correspondent lenders, and procurement leads at credit union service organizations. Primary fieldwork with integration specialists and API platform engineers validated deployment model adoption patterns. Secondary sources included GSE data delivery standard publications, European Banking Authority framework documentation, and cloud infrastructure hyperscaler financial disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from vendor revenue disclosures and lending volume correlations.
Variance decomposition across product type, deployment model, end-user category, and integration complexity dimensions anchored the analytical framework over the projection horizon. CAGRs derived from origination volume elasticity models, regulatory compliance spending correlations, and cloud adoption S-curve penetration rates. Industry-specific forecast inputs incorporated CFPB servicing rule implementation timelines and credit union core banking replacement cycle data.
Forecasts assume regulatory continuity in US CFPB, FHA, and GSE regimes alongside EU DORA and GDPR enforcement patterns; material policy shifts would require re-modeling. Technology risk includes generative AI disruption of document verification workflows and open banking mandate acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Retail Media Networks Market
Others
Lepidolite Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
5G Edge Computing Market
Others
Europe Legal Services Market
Others
Hotel Wardrobe Market
Others
Europe Virtual Reality Gaming Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Heavy Duty Vacuum Bottle Market
Others
Global Food Fiber Market
Others
Smart Home Gateways Market
Others
Nutricosmetics Market
Others
Reinforcement Geosynthetics Market
Others
PCB Laminate Market
Others
Dried Egg Market
Others
Augmented Reality in BFSI Market