
 Europe Indoor LBS Market | 2026-2036
Europe Indoor LBS Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Indoor LBS Market Intelligence
The EU AI Act is restructuring the cost-of-entry calculus for indoor location service providers by mandating algorithmic transparency and risk classification for automated positioning systems. Quuppa leverages its ultra-wideband angle-of-arrival technology to sustain sub-meter accuracy without relying on personally identifiable signal data. Cisco Systems anchors enterprise-grade deployments through its Meraki Wi-Fi infrastructure with embedded BLE beacon management.
Indoor location-based services comprise positioning, navigation, and analytics systems that operate within enclosed environments using radio frequency signals, inertial measurement units, and sensor fusion algorithms achieving one-to-three-meter accuracy under typical conditions. These systems enable real-time spatial intelligence for asset tracking, wayfinding, and contextual engagement in environments where satellite-based GNSS signals degrade or fail. Bluetooth beacon infrastructure dominates current European deployments due to low power requirements and native integration with smartphone ecosystems, while Wi-Fi-based fingerprinting retains share in legacy enterprise environments where access point density already exists. Location analytics services capture expanding margin pools as retailers and venue operators demand footfall pattern recognition and dwell-time optimization beyond basic navigation.
GDPR enforcement by national data protection authorities across EU member states restricts raw location data retention and mandates explicit consent frameworks, directly shaping product architecture and vendor liability exposure. The EU Green Deal building renovation targets indirectly stimulate indoor LBS adoption by requiring smart building certifications that incorporate occupancy-based energy management. Stakeholders must monitor evolving interpretations of automated decision-making under the AI Act as positioning algorithms migrate from deterministic to machine-learning-based inference models.
Market Dynamics
The EU AI Act is reclassifying indoor positioning algorithms as high-risk automated decision-making systems, forcing vendors to reconstruct data pipelines around explainable inference models and documented risk management protocols.
Growth Catalysts
- EU Green Deal building mandates:Smart building certifications requiring occupancy-based energy management are mandating indoor positioning infrastructure across commercial real estate in France and Germany.
- Proximity marketing adoption:French and German retailers are deploying Bluetooth beacon networks to enable real-time contextual engagement and footfall analytics in dense urban shopping districts.
- Ultra-wideband sensor fusion:Sub-meter accuracy requirements in healthcare and logistics environments are accelerating angle-of-arrival deployments that bypass Wi-Fi fingerprinting limitations.
Market Restraints
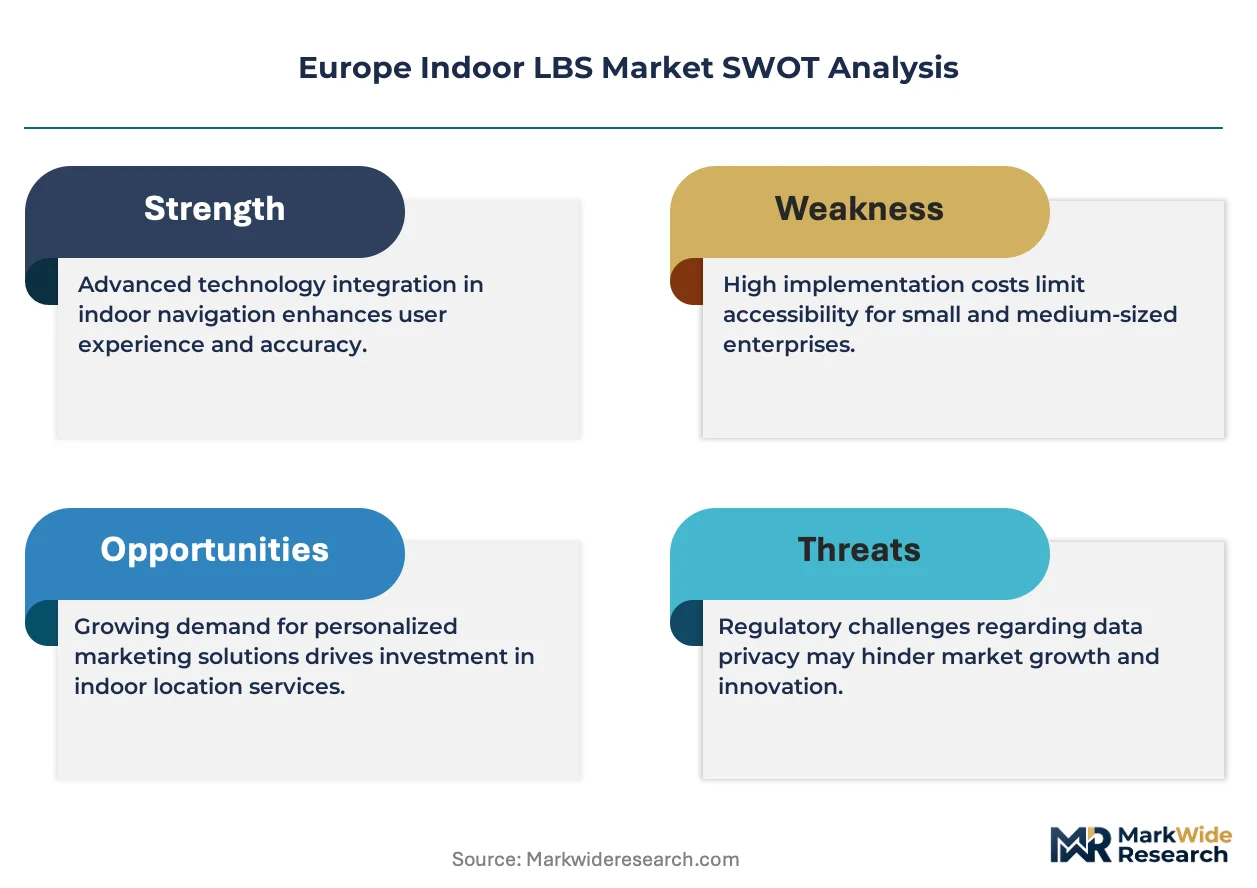
- GDPR consent friction:National data protection authorities in Germany and France enforce explicit opt-in frameworks that degrade location data capture rates and complicate analytics monetization.
- Legacy Wi-Fi infrastructure lock-in:Enterprise environments with existing access point density face sunk-cost resistance to parallel BLE beacon deployments despite superior accuracy.
- Algorithmic transparency costs:EU AI Act compliance requires documentation and risk classification expenditures that disproportionately burden mid-scale venue operators.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Denmark exhibit low indoor LBS penetration relative to building stock modernization rates, creating first-mover positioning for integrated smart building vendors.
- Healthcare wayfinding convergence:Hospital networks in the United Kingdom are unifying patient navigation with asset tracking and staff safety systems under single-platform procurement.
- CSRD reporting tailwinds:Corporate Sustainability Reporting Directive mandates for granular occupancy and energy data are converting passive building owners into active indoor analytics buyers.
Industry Challenges
- Machine learning talent scarcity:Vendors struggle to recruit engineers capable of building explainable positioning models that satisfy EU AI Act documentation requirements.
- Interoperability fragmentation:Proprietary beacon protocols and non-standard API implementations force costly integration workarounds for multi-vendor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Indoor LBS Market |
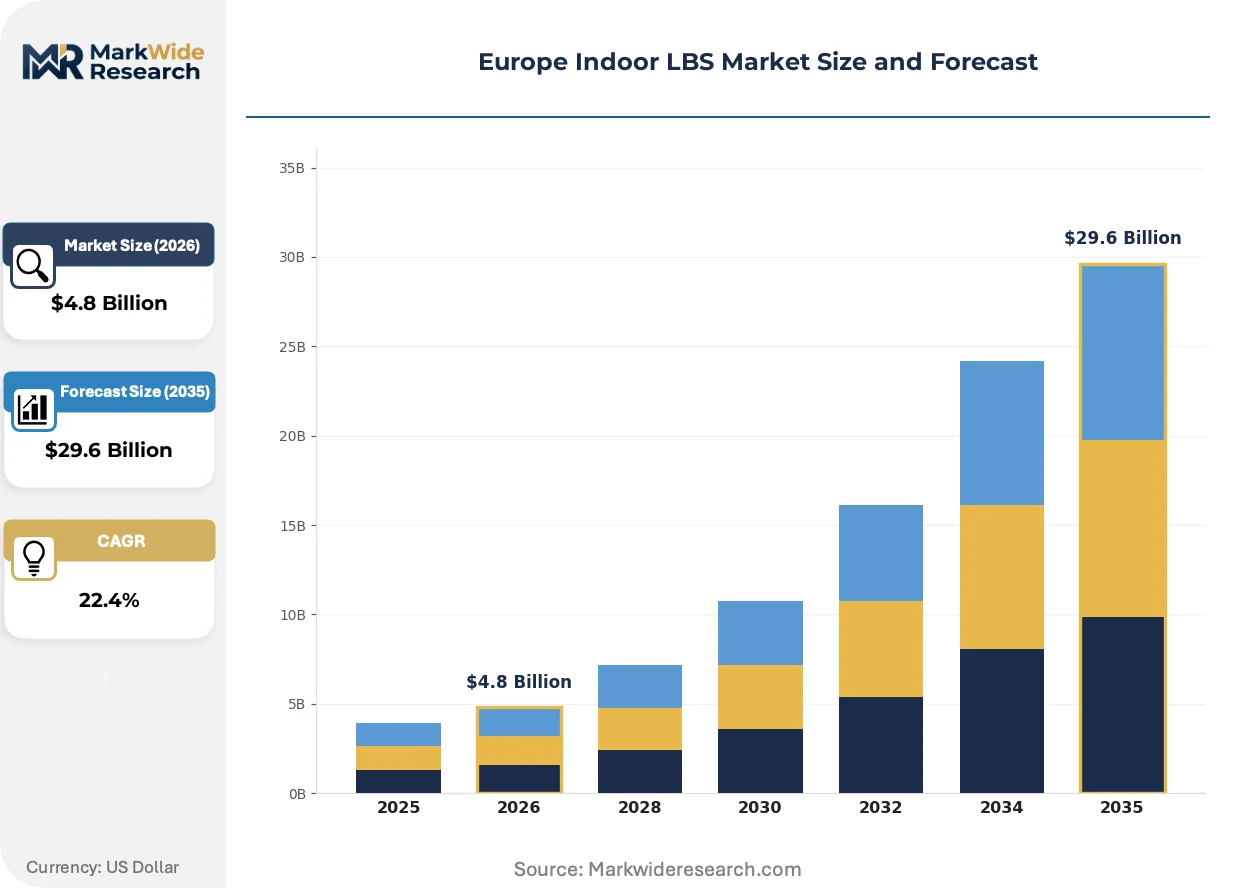
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $29.6 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Bluetooth, RFID, Ultrasound Application: Retail, Healthcare, Transportation, Venue Management End User: Smartphones, Wearable Devices, Tablets, IoT Devices Service Type: Navigation Services, Asset Tracking, Location Analytics, Proximity Marketing |
| Companies Covered | Quuppa, Google, Cisco Systems, Qualcomm Technologies, IndoorAtlas, HERE Technologies, Zebra Technologies, CommScope, Ubisense, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Indoor LBS Market Strategic Shifts & Innovations
Algorithmic positioning is migrating from deterministic triangulation to probabilistic machine-learning inference, compressing accuracy variance while expanding the operational contexts where indoor navigation achieves commercial viability.
Sensor fusion architectures are unifying ultra-wideband angle-of-arrival, inertial measurement units, and BLE signal strength into single-chip modules that reduce hardware complexity. Automotive suppliers entering the European market are adopting these unified platforms for indoor parking navigation at scale. The consolidation is compressing vendor margins on standalone beacon hardware while expanding addressable market volume.
GDPR enforcement by CNIL in France and BfDI in Germany is mandating data minimization and purpose limitation for location analytics, forcing platform redesigns around ephemeral processing and on-device inference. Retail analytics providers are responding with edge-computing architectures that retain raw signal data for milliseconds rather than centralized storage. The regulatory pressure is most acute in French luxury retail, where brand sensitivity to privacy litigation exceeds technical upgrade costs.
Buyer procurement in German commercial real estate is rotating from capital expenditure hardware purchases to subscription-based location-as-a-service contracts that bundle installation, maintenance, and algorithm updates. Facility management firms are displacing traditional AV integrators as the primary contracting channel. This shift is most visible in Frankfurt and Munich office developments targeting DGNB sustainability certification.
Europe Indoor LBS Market Segmentation
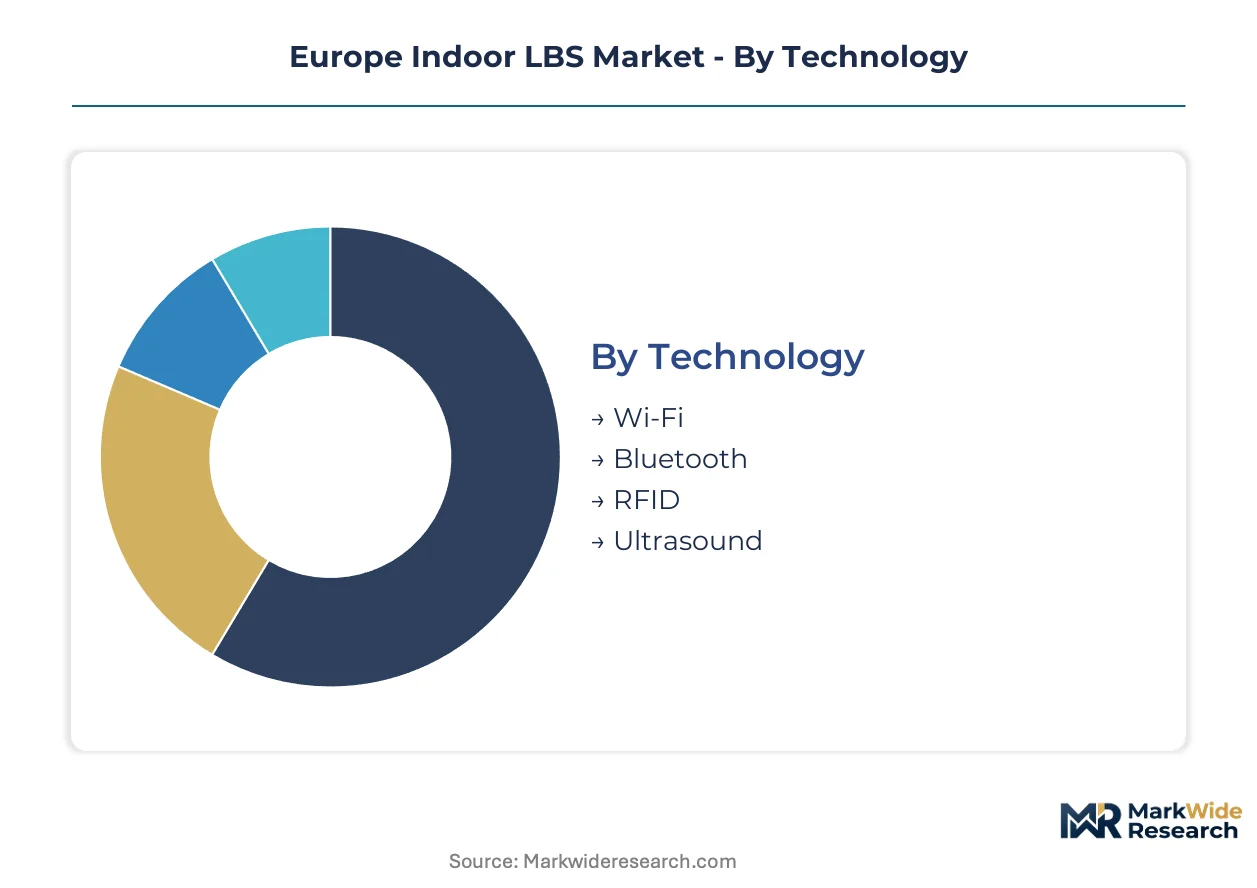
Technology integration depth determines competitive positioning across European indoor LBS deployments. Standalone positioning systems compete against embedded sensor fusion architectures that bundle multiple signal modalities into unified platforms.
Technology:
Integration depth varies sharply—Wi-Fi and Bluetooth dominate embedded multi-sensor deployments, while ultrasound and RFID remain largely standalone for specialized use cases.
- Wi-Fi:Fingerprinting algorithms leverage existing enterprise access point density for coarse-grained positioning without incremental hardware spend. German commercial real estate operators prioritize Wi-Fi-first architectures to satisfy DGNB sustainability certification requirements while minimizing capital deployment.
- Bluetooth:Low-energy beacon networks deliver native smartphone compatibility and sub-three-meter accuracy through received signal strength indicator triangulation. French luxury retail chains in Paris and Lyon deploy dense BLE mesh networks to enable proximity marketing campaigns that comply with CNIL consent frameworks.
- RFID:Passive tag systems provide zone-level asset identification in logistics and healthcare environments where meter-scale precision exceeds operational requirements.
- Ultrasound:Time-of-flight positioning achieves centimeter accuracy in controlled industrial settings but requires dedicated receiver infrastructure absent from consumer devices.
Volume placements concentrate in Bluetooth; the faster expansion belongs to Wi-Fi as building automation convergence accelerates.
Application:
Cost tier stratification separates high-investment healthcare deployments from lean retail pilots that prioritize rapid payback periods.
- Retail:Proximity marketing and footfall analytics drive beacon infrastructure investment across urban shopping districts. French and German retailers deploy location-aware engagement platforms to bridge online-offline customer journey data while navigating GDPR purpose limitation constraints.
- Healthcare:Wayfinding convergence unifies patient navigation, asset tracking, and staff duress alerting under single-platform procurement. United Kingdom hospital networks mandate sub-meter accuracy for emergency response coordination, accelerating ultra-wideband adoption.
- Transportation:Indoor parking navigation and multimodal transit hubs deploy sensor fusion for seamless last-mile connectivity.
- Venue Management:Stadiums and exhibition centers leverage crowd flow optimization to satisfy safety regulations and maximize concession revenue per visitor.
Margin capture concentrates in Healthcare; Retail exhibits the steepest expansion trajectory as CSRD reporting mandates convert passive owners into analytics buyers.
End User:
Device category maturity shapes data pipeline architecture—smartphones enable ephemeral processing while IoT endpoints demand persistent connectivity.
- Smartphones:Native BLE and Wi-Fi radios position smartphones as the dominant signal source for consumer-facing navigation services. GDPR-compliant on-device inference architectures process raw beacon data locally before transmitting anonymized trajectory summaries.
- Wearable Devices:Smartwatches and industrial safety bands extend positioning to hands-free operational contexts in logistics and healthcare.
- Tablets:Fixed kiosk deployments in museums and corporate campuses provide assisted wayfinding for visitors without personal device compatibility.
- IoT Devices:Sensor-equipped assets and environmental monitors require continuous positioning for automated workflow orchestration.
Smartphone deployments dominate current volume; IoT endpoints are climbing the fastest as building automation convergence deepens.
Service Type:
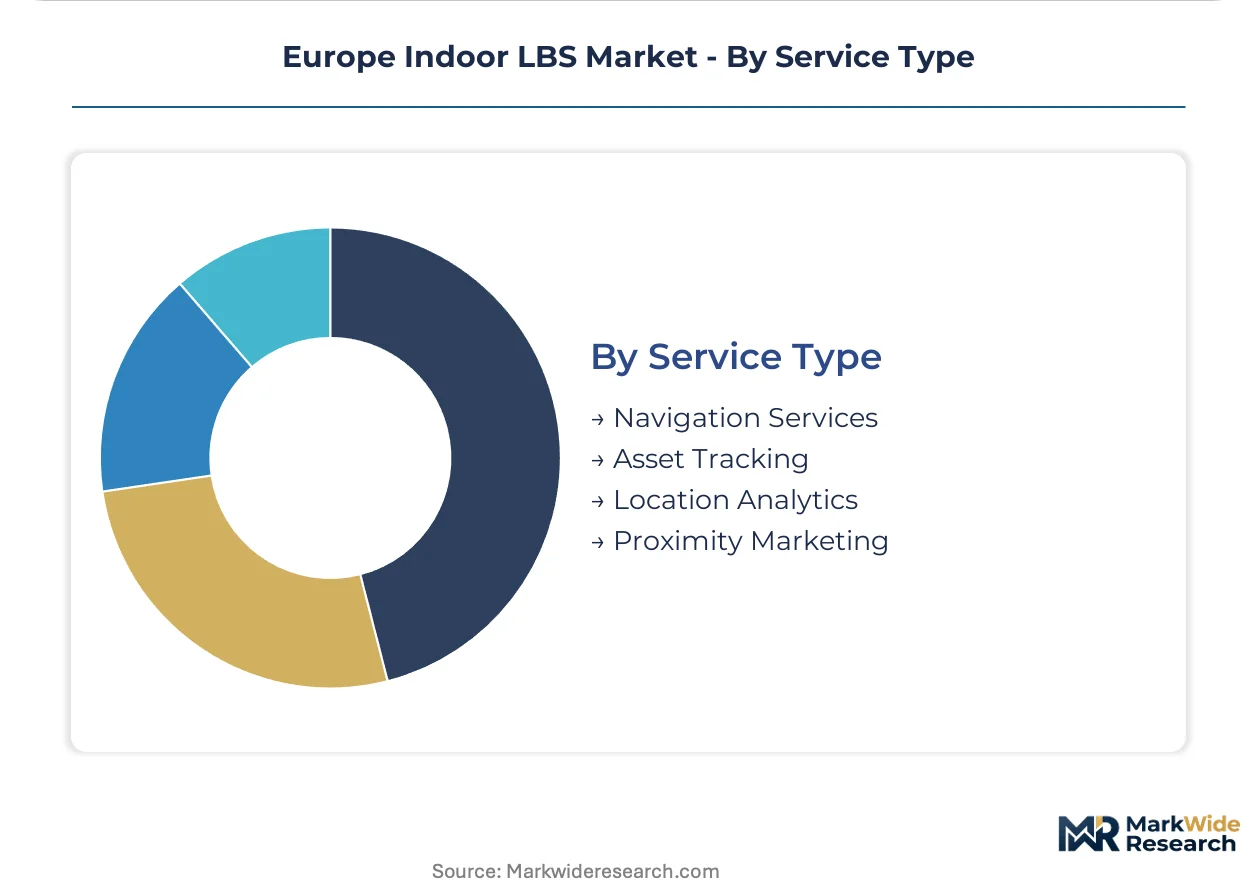
Customer type stratification separates enterprise procurement of integrated platforms from venue-operator purchases of point solutions.
- Navigation Services:Turn-by-turn wayfinding and point-of-interest discovery anchor consumer-facing mobile applications. German airport operators bundle indoor navigation with retail loyalty programs to extend dwell time in concession zones.
- Asset Tracking:Real-time location systems monitor high-value equipment and inventory across healthcare and industrial environments. United Kingdom NHS trusts deploy unified tracking platforms to reduce equipment search time and optimize capital utilization rates.
- Location Analytics:Aggregated footfall pattern recognition and dwell-time optimization generate recurring revenue streams for platform vendors. GDPR enforcement by BfDI mandates ephemeral processing architectures that complicate longitudinal dataset construction.
- Proximity Marketing:Contextual engagement triggers based on spatial proximity drive retail media monetization. French CNIL consent requirements enforce explicit opt-in frameworks that degrade capture rates relative to less regulated markets.
Navigation Services hold the largest installed base; Location Analytics is gaining share fastest as CSRD energy reporting mandates expand addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise zones in Frankfurt and Munich concentrate German smart building investment, while Île-de-France tax incentives accelerate French retail technology deployment. Nordic sustainability mandates and UK healthcare procurement create differentiated sub-regional demand profiles across the continent.
Germany
DGNB sustainability certification requirements mandate occupancy-based energy management in commercial real estate developments. BfDI enforcement of GDPR consent frameworks restricts raw location data retention periods for analytics providers. Frankfurt and Munich office developments anchor demand for subscription-based location-as-a-service contracts replacing capital expenditure hardware purchases.
France
Luxury retail chains in Paris and Lyon deploy dense Bluetooth beacon networks for proximity marketing campaigns. CNIL mandates explicit opt-in frameworks that degrade location data capture rates relative to neighboring markets. Auvergne-Rhône-Alpes manufacturing clusters adopt ultra-wideband asset tracking for precision logistics operations in pharmaceutical distribution centers.
United Kingdom
NHS trusts mandate unified wayfinding platforms combining patient navigation, equipment tracking, and staff duress alerting. MHRA medical device regulations influence procurement standards for hospital-grade positioning accuracy. London hospital networks accelerate ultra-wideband adoption for emergency response coordination requiring sub-meter precision.
Sweden
Smart building modernization rates outpace current indoor LBS penetration, creating first-mover positioning for integrated platform vendors. The country's national data protection authority enforces GDPR purpose limitation for location analytics. Stockholm commercial developments incorporate sensor fusion architectures for occupancy-based climate control and energy reporting.
Netherlands
Randstad logistics hubs deploy RFID zone-level asset identification for inventory management where meter-scale precision exceeds operational requirements. Dutch building codes for energy efficiency stimulate demand for occupancy detection systems. Eindhoven technology clusters anchor research partnerships between semiconductor firms and positioning algorithm developers.
Europe Indoor LBS Market Key Industry Players
Finnish and US technology providers anchor the premium accuracy tier; German infrastructure specialists hold enterprise integration positions. The vendor base organizes around three strategic archetypes: ultra-wideband precision technology developers, Wi-Fi infrastructure incumbents with embedded beacon management, and cloud-native platform operators. Competitive dynamics center on technology licensing partnerships and vertical integration into sensor fusion hardware.
Within the precision positioning tier, Quuppa exemplifies angle-of-arrival specialization for sub-meter accuracy requirements. Cisco Systems occupies the enterprise infrastructure integration position through its Meraki Wi-Fi platform with embedded BLE management. Google represents the cloud-native archetype with smartphone ecosystem leverage for consumer-facing navigation services. HERE Technologies anchors mapping and location platform consolidation across automotive and venue management applications.
| Leading Market Players |
|---|
| Quuppa |
| Cisco Systems |
| Qualcomm Technologies |
| IndoorAtlas |
| HERE Technologies |
| Zebra Technologies |
| CommScope |
| Ubisense |
| Others |
Cost & Logistics Intelligence
Ultra-wideband chipset costs cascade through hardware tiers, compressing margins on standalone beacon manufacturers while elevating subscription-based location-as-a-service premiums for German facility management firms bundling installation and algorithm updates.
Pricing Analysis
Short lead-time premiums attach to angle-of-arrival sensor modules for United Kingdom hospital emergency response systems, while spot inventory discounts emerge for legacy Wi-Fi fingerprinting deployments in French commercial real estate. Subscription-SaaS tiered pricing dominates as facility management firms displace AV integrators in Frankfurt and Munich, with differentiation resting on DGNB certification integration and GDPR-compliant ephemeral processing architectures. Cost compression in mid-scale BLE beacon hardware intensifies as automotive suppliers enter indoor parking navigation with unified sensor fusion platforms. German commercial real estate operators exhibit highest price sensitivity due to sunk-cost resistance; United Kingdom NHS trusts show lowest sensitivity given sub-meter accuracy mandates for staff duress alerting.
Supply Chain Analysis
Regional distribution centers in Eindhoven and Stockholm anchor hub-and-spoke patterns for Nordic smart building deployments, with secondary nodes in Frankfurt serving German DGNB-certified developments. Semiconductor fabrication concentrates in Taiwan, South Korea, and the Netherlands for UWB and BLE chipsets. Raw material dependencies span rare earth elements for magnetometer components, silicon wafers for RF front-ends, and lithium-ion cells for beacon power management. Single-source vulnerability in angle-of-arrival DSP processors creates procurement risk for sub-meter accuracy vendors. Distribution runs through facility management contracting channels displacing traditional systems integrators across European commercial real estate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indoor LBS vendors face a vertical-integration race as sensor fusion architectures compress standalone hardware margins, with control over positioning algorithm IP and edge-computing deployment becoming the decisive downstream lever.
For Market Incumbents: Deploy explainable machine-learning model documentation capabilities to preempt EU AI Act risk classification penalties for automated positioning systems. Consolidate around integrated sensor fusion platforms combining UWB angle-of-arrival with BLE and inertial measurement units to displace standalone beacon vendors. Counter cloud-native entrants by anchoring enterprise relationships through Meraki-style Wi-Fi infrastructure with embedded beacon management.
For New Entrants and Emerging Players: Capture underpenetrated Swedish and Danish smart building modernization demand where facility management procurement channels remain uncommitted to incumbent platforms. Target healthcare wayfinding convergence in United Kingdom hospital networks unifying patient navigation with asset tracking under single-platform procurement. Pursue location-as-a-service subscription models with CSRD energy reporting bundling to bypass capital expenditure barriers in German commercial real estate.
For Investors and Strategic Acquirers: BfDI enforcement actions against analytics providers with non-compliant data retention architectures are the leading indicator that GDPR-compliant ephemeral processing capabilities will command acquisition premiums. Position for five-to-ten-year consolidation around vendors with certified edge-computing deployments and healthcare procurement relationships. Monitor CNIL consent framework litigation against French luxury retail chains as signal for privacy-compliant platform valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Unifies UWB, BLE, and IMU into single-chip modules that reduce hardware complexity for automotive parking navigation. |
| GDPR-Compliant Edge Architecture | Enables millisecond raw signal retention that satisfies BfDI and CNIL enforcement without degrading analytics utility. |
| Healthcare Wayfinding Convergence | Combines patient navigation, equipment tracking, and staff duress alerting under NHS single-platform procurement mandates. |
| Location-as-a-Service Subscription | Converts German facility management firms from capital expenditure buyers to recurring revenue relationships. |
| CSRD Reporting Bundle | Links occupancy-based energy data to Corporate Sustainability Reporting Directive compliance for passive building owners. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with smart building facility managers, hospital biomedical engineers, BLE beacon procurement leads, positioning algorithm developers, and CNIL compliance officers. Secondary sources encompassed EU AI Act implementation guidance, BfDI enforcement decisions, DGNB certification databases, NHS procurement frameworks, and Eindhoven semiconductor cluster production disclosures. Bottom-up deployment tracking across French retail chains and German commercial real estate converged with top-down market sizing.
Data-stream reconciliation across hardware shipment volumes, subscription contract values, and algorithm licensing fees informed analytical framework construction across the projection horizon. Segmentation dimensions encompassed technology integration depth, application cost tier, end-user device category, and service type procurement pattern. CAGRs derived from slope analysis of deployment trajectories in United Kingdom hospital networks and Nordic smart building modernization rates, calibrated against EU Green Deal building mandate implementation schedules.
The model holds under sustained GDPR enforcement and EU AI Act risk classification implementation; deviation in regulatory interpretation timelines or semiconductor supply normalization would shift trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Digital Bass Processor Market
Others
Industrial Air Purifiers Market
Others
Smart Home Controller Market
Others
Rotary Dial Machine Market
Others
Wearable Brain Devices Market
Others
Astrology Market
Others
Residential Electrical Conduit Market
Others
Global Radar Systems Market
Others
South America Automotive LED Lighting Market
Others
Blockchain in BFSI Market
Others
Smart Home As a Service Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Traditional PC Market
Others
Asia-Pacific Intercom Devices Market
Others
Massive Machine Type Communication in Healthcare Market
Others
Global Alpha Cypermethrin Market