
 Heavy Duty Traps Market | 2026-2036
Heavy Duty Traps Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Traps Market Analytics
China is fragmenting as domestic metalworking clusters scale galvanized steel output for trap mechanisms. Duke Traps leverages backward integration into wire-forming operations to secure coil supply. Tru Catch Traps sustains R&D intensity through welded mesh automation at its Nebraska facility. Bridger Traps anchors western North American distribution through dealer networks concentrated in Montana and Alberta.
Heavy duty traps are reinforced steel or polymer enclosures engineered to capture or eliminate vertebrate pests, typically featuring spring mechanisms rated for animals exceeding fifteen kilograms and corrosion-resistant coatings for extended field deployment. Their primary industrial purpose centers on protecting stored commodities, livestock infrastructure, and food processing environments from wildlife intrusion and rodent contamination. Mechanical traps lead product type revenue due to institutional procurement preferences for non-chemical intervention, while smart traps within the technology dimension represent the fastest-growing margin pool as telemetry-enabled monitoring reduces service visit frequency. Agricultural sectors dominate end user demand through seasonal bulk purchasing tied to harvest cycles, whereas commercial properties generate steadier replacement revenue.
EPA regulates chemical trap active ingredients under FIFRA, requiring efficacy data submissions that extend registration timelines and favor incumbents with established dossiers. USDA APHIS coordinates wildlife damage management protocols that specify trap performance standards for federal land contracts, creating specification barriers for uncertified suppliers. Stakeholders must monitor state-level trapping law preemption debates, as municipal bans on certain trap types in Colorado and California threaten to fragment compliance requirements beyond federal baselines.
Market Dynamics
EPA registration timelines for chemical trap formulations are compressing product development cycles and favoring incumbents with established dossiers, while galvanized steel supply fragmentation in China reshapes component sourcing economics for mechanical trap manufacturers.
Growth Catalysts
- Integrated Pest Management Protocols:Agricultural sectors across the United States Corn Belt mandate non-chemical intervention methods, institutionalizing mechanical trap procurement into seasonal bulk purchasing tied to harvest cycles.
- USDA APHIS Performance Standards:Federal wildlife damage management contracts specify trap certification requirements, creating specification barriers that filter uncertified suppliers from federal land opportunities.
- Telemetry-Enabled Monitoring:Smart trap adoption reduces service visit frequency for commercial property managers, expanding margin pools through subscription-based remote monitoring revenue streams.
Market Restraints
- Galvanized Steel Price Volatility:Coil supply concentration among domestic Chinese metalworking clusters exposes trap mechanism producers to input cost swings and export duty uncertainties.
- FIFRA Registration Friction:EPA efficacy data submission requirements extend chemical trap approval timelines beyond eighteen months, freezing formulation innovation for new market entrants.
- Municipal Trap Bans:Colorado and California municipalities are preempting state trapping laws with local prohibitions on certain trap types, fragmenting compliance requirements beyond federal baselines.
Strategic Opportunities
- Grain Storage Protection Mandates:United States Corn Belt regulatory intensification around stored commodity contamination creates specification-driven replacement cycles for legacy trap installations.
- Welded Mesh Automation:Convergence of robotic welding with corrosion-resistant coating technologies enables throughput scaling for high-volume trap producers serving agricultural distributors.
- Dealer Network Consolidation:Western North American distribution through Montana and Alberta dealer concentrations offers acquisition targets for manufacturers seeking geographic density in livestock protection markets.
Industry Challenges
- Certification Timeline Compression:USDA APHIS trap performance testing queues are extending beyond twelve months, delaying federal contract eligibility for product line extensions.
- Weld Quality Skill Scarcity:Automated mesh production requires technicians capable of calibrating robotic systems for spring mechanism tolerances, a competency gap in rural manufacturing labor pools.
- Legacy Inventory Integration:Telemetry retrofit kits for existing mechanical trap fleets face firmware compatibility failures with decade-old spring housing designs, complicating upgrade paths for institutional buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Traps Market |
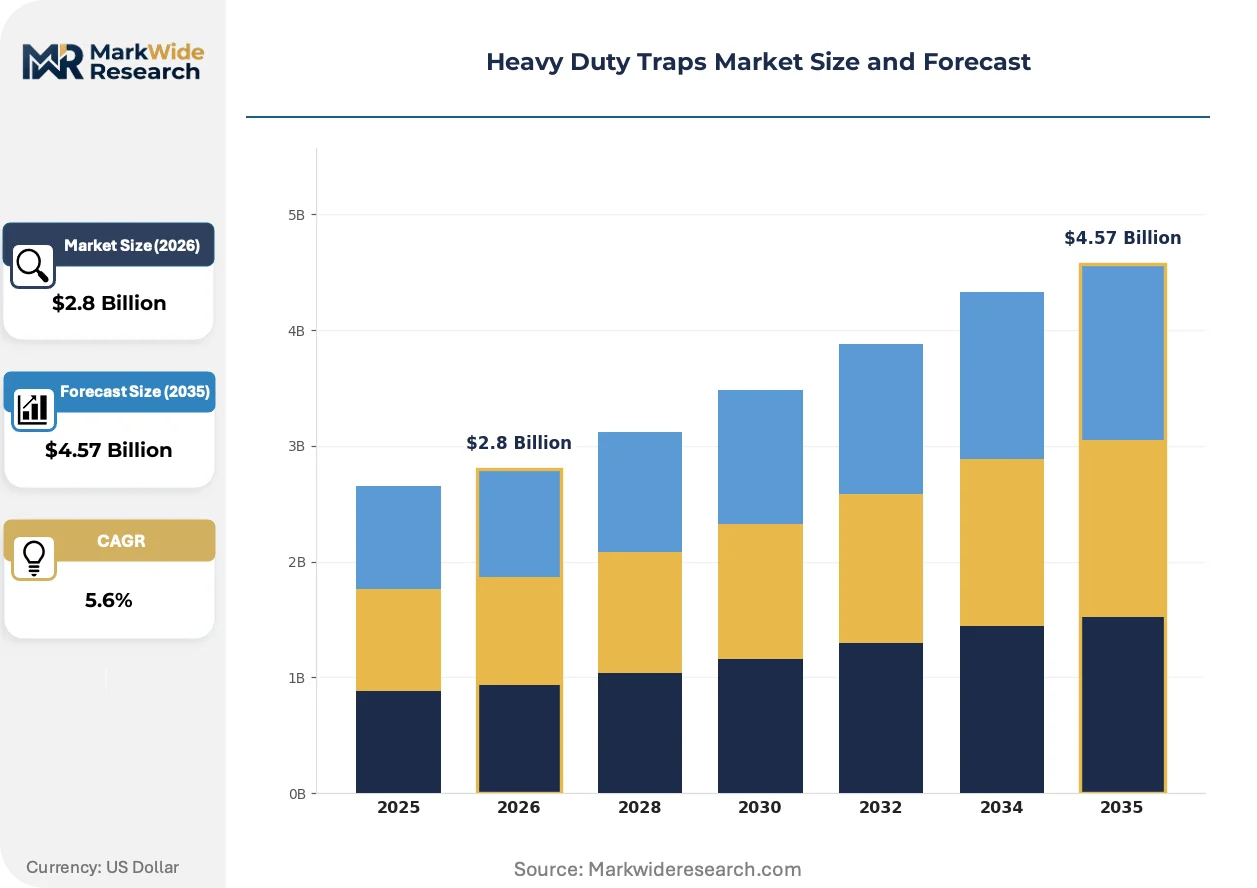
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
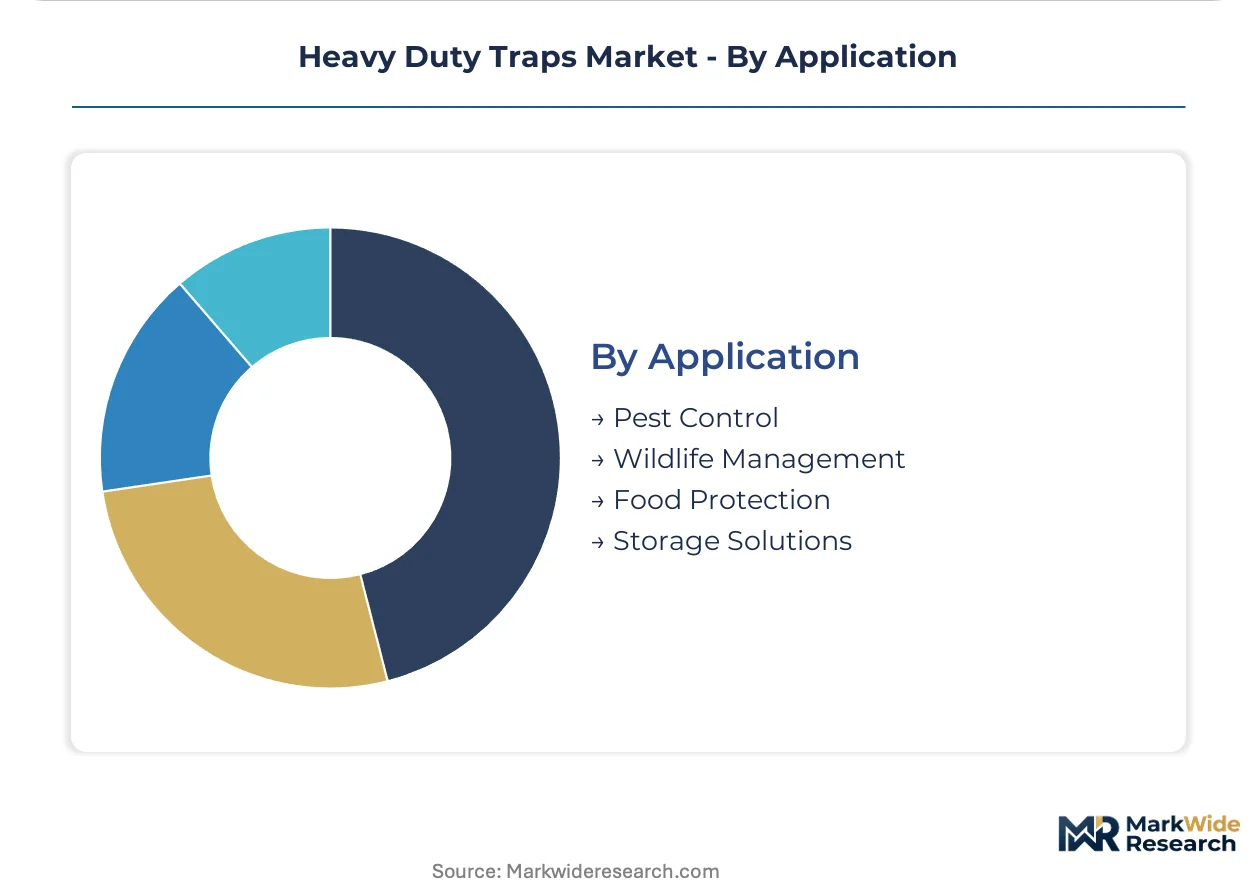
| Segmentation | Product Type: Mechanical Traps, Chemical Traps, Electronic Traps, Live Traps End User: Residential Users, Commercial Properties, Industrial Facilities, Agricultural Sectors Technology: Smart Traps, Traditional Traps, Eco-friendly Solutions, Conventional Traps Application: Pest Control, Wildlife Management, Food Protection, Storage Solutions |
| Companies Covered | Tru Catch Traps, Duke Traps, Bridger Traps, Tomahawk Live Trap, Safeguard Traps, Hebei Liebang Metal Products, ADC Traps, Harris Traps, LB Traps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Traps Market Evolving Landscape
Mechanical trap architectures are yielding to sensor-embedded alternatives, while regulatory preemption battles and procurement centralization reshape how buyers evaluate total cost of ownership across chemical and non-chemical intervention categories.
Cellular-enabled trap monitors are rendering obsolete scheduled service visit models that dominated commercial pest control economics for decades. Property management firms operating multi-site food processing facilities are deploying these devices at accelerating rates. The shift compresses recurring revenue recognition from labor-based contracts to hardware-plus-data subscription structures.
EPA FIFRA registration requirements for chemical trap active ingredients are extending development timelines and consolidating formulation innovation among dossier-rich incumbents. The industrial consequence is a product development freeze for novel chemical attractants, pushing R&D investment toward mechanical and electronic trap architectures. Agricultural procurement offices are responding by tightening mechanical trap specifications in integrated pest management protocols.
Seasonal bulk purchasing tied to harvest cycles is compressing switching costs for agricultural buyers evaluating trap suppliers. Grain elevator operators and cooperative storage facilities are consolidating vendor lists to three approved suppliers, displacing fragmented local distributor relationships. This concentration is most visible across Iowa, Illinois, and Nebraska procurement offices managing federal crop insurance compliance requirements.
Heavy Duty Traps Market Segmentation
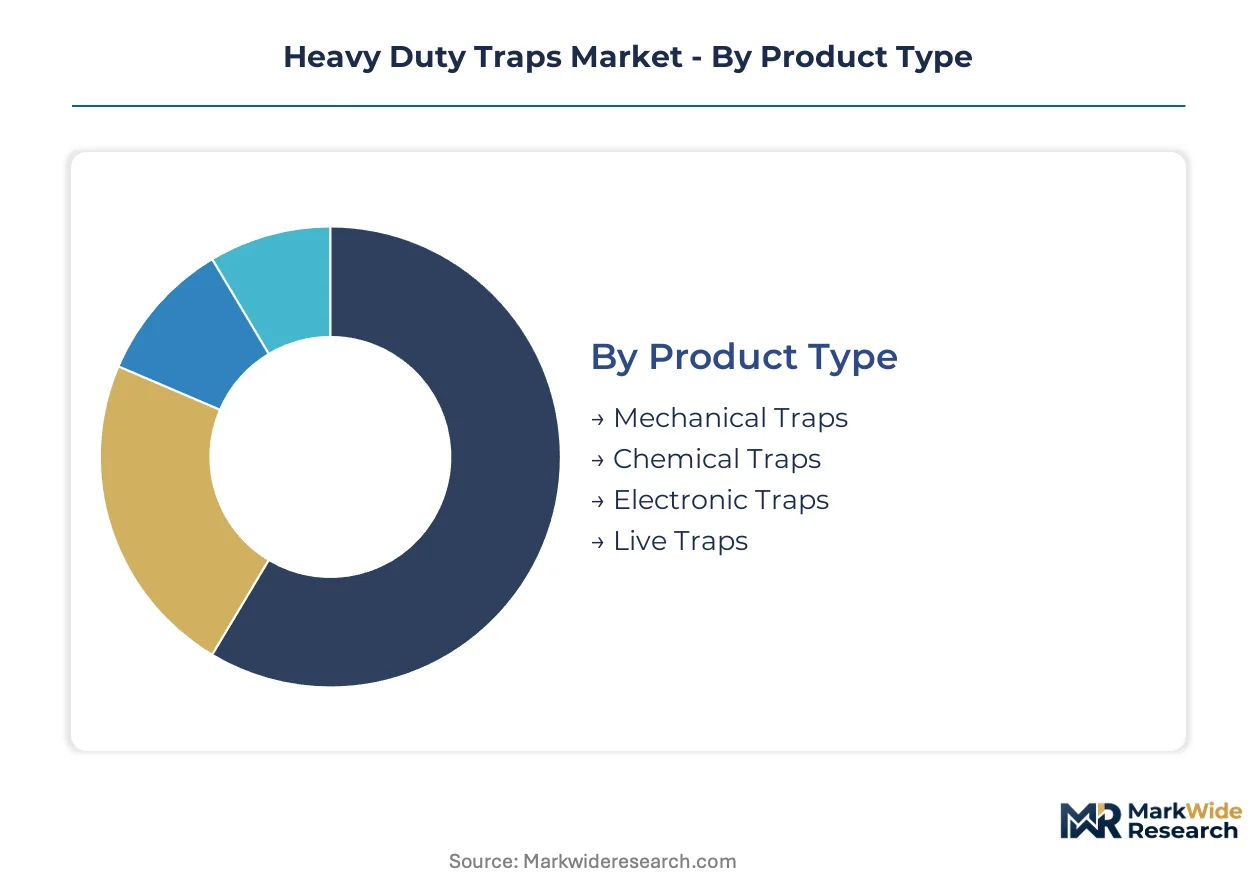
Segmentation in heavy duty traps reveals how procurement authority, regulatory jurisdiction, and technology readiness diverge across buyer types. Agricultural buyers prioritize mechanical reliability under USDA APHIS specifications, while commercial property managers optimize for labor reduction through telemetry integration.
Product Type:
Cost tier stratification separates institutional buyers seeking total cost of ownership advantages from price-sensitive residential channels.
- Mechanical Traps:Spring-loaded steel enclosures rated for animals exceeding fifteen kilograms feature corrosion-resistant galvanized coatings. United States Corn Belt grain elevators mandate these for federal crop insurance compliance, with seasonal bulk purchasing compressing vendor lists to three approved suppliers.
- Chemical Traps:Formulations containing EPA-registered active ingredients under FIFRA require efficacy dossiers extending approval timelines beyond eighteen months. EPA registration friction favors incumbents with established dossiers while freezing innovation for new entrants.
- Electronic Traps:Battery-powered kill mechanisms deliver instantaneous dispatch with reduced handling risk.
- Live Traps:Welded mesh enclosures enable non-lethal capture for relocation protocols.
Mechanical Traps hold installed capacity. Electronic Traps is rotating up the share rankings.
End User:
Customer type determines specification stringency, with federally regulated channels imposing certification barriers that filter uncertified suppliers.
- Agricultural Sectors:Seasonal procurement tied to harvest cycles drives consolidated vendor relationships across Iowa, Illinois, and Nebraska cooperative storage facilities. Integrated pest management protocols institutionalize non-chemical intervention methods, tightening mechanical trap specifications.
- Commercial Properties:Multi-site food processing facilities deploy cellular-enabled monitors at accelerating rates, compressing revenue recognition from labor-based contracts to hardware-plus-subscription structures.
- Industrial Facilities:Manufacturing plants with zero-pest tolerance policies specify trap performance under third-party audit requirements.
- Residential Users:Price-sensitive demand concentrates through retail channels with minimal regulatory overlay.
Agricultural Sectors command specification authority. Commercial Properties is climbing the fastest.
Technology:
Maturity stage separates legacy mechanical architectures from emerging telemetry-enabled alternatives reshaping service economics.
- Smart Traps:Cellular-enabled monitors with remote status reporting eliminate scheduled service visits. Commercial property managers operating distributed food processing sites adopt these for labor cost reduction, expanding margin pools through subscription revenue.
- Traditional Traps:Unmodified spring mechanisms without electronic components dominate federal land contracts under USDA APHIS performance standards. Certification queues extending beyond twelve months delay eligibility for product line extensions.
- Eco-friendly Solutions:Biodegradable materials and non-toxic attractants address municipal sustainability mandates.
- Conventional Traps:Standard mechanical designs without connectivity features serve price-sensitive replacement cycles.
Traditional Traps anchors federal procurement. Smart Traps is gaining share fastest.
Application:
Volume concentration tracks commodity storage infrastructure and livestock protection mandates across regulated geographies.
- Food Protection:Grain storage protection mandates in the United States Corn Belt create specification-driven replacement cycles for legacy installations. Regulatory intensification around stored commodity contamination tightens compliance requirements.
- Storage Solutions:Elevator operators and cooperative facilities consolidate vendor relationships to three approved suppliers, displacing fragmented local distributor networks under federal crop insurance requirements.
- Pest Control:Urban and suburban rodent management programs specify trap performance under municipal health codes.
- Wildlife Management:Federal land contracts under USDA APHIS coordinate damage management protocols with trap certification requirements.
Storage Solutions holds procurement volume. Food Protection is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA APHIS performance standards anchor North American procurement, while EPA FIFRA registrations govern chemical formulation deployment. Agricultural storage mandates in the Corn Belt and municipal trap bans in Colorado and California create divergent compliance environments.
United States
Grain elevator operators across Iowa, Illinois, and Nebraska consolidate vendor lists to three approved suppliers under federal crop insurance requirements. EPA FIFRA registration timelines extending beyond eighteen months freeze novel chemical attractant development. Duke Traps leverages backward integration into wire-forming operations at its domestic facilities to secure coil supply against price volatility.
Canada
Livestock protection demand concentrates in Alberta and Saskatchewan ranching corridors where predator management protocols specify trap certification. Health Canada PMRA regulates chemical trap formulations through efficacy review processes parallel to EPA systems. Tru Catch Traps sustains R&D intensity through welded mesh automation at its Nebraska facility serving cross-border distribution.
China
Domestic metalworking clusters in Hebei Province scale galvanized steel output for trap mechanism components. The country's national environmental regulator enforces corrosion-resistance standards for exported agricultural equipment. Hebei Liebang Metal Products exemplifies regional fabrication capacity serving international supply chains.
Germany
Industrial food processing facilities specify trap performance under third-party audit requirements aligned with EU hygiene regulations. ECHA REACH compliance for chemical trap coatings adds documentation burdens to import channels. Bavarian manufacturing clusters produce precision spring mechanisms for premium mechanical trap tiers.
Australia
Grain storage infrastructure across New South Wales and Victoria drives seasonal procurement tied to wheat and barley harvest cycles. The country's national agricultural regulator coordinates wildlife damage management protocols with trap performance standards. Local fabrication shops concentrate in regional centers serving pastoral protection mandates.
Heavy Duty Traps Market Competitive Landscape
Capability concentration sits with specialty fabricators commanding USDA APHIS certification queues; scale advantage sits with diversified metalworking operations serving agricultural distributor networks. The vendor base separates into three tiers: premium-tier specialists with federal contract eligibility, mid-tier regional fabricators with dealer network density, and commodity producers competing on coil-input economics. Strategic moves center on welded mesh automation for throughput scaling and dealer network consolidation in livestock protection corridors.
Among North American specialists, Tru Catch Traps, Duke Traps, and Bridger Traps occupy positions across the capability-scale spectrum. Tru Catch Traps exemplifies the automation-invested tier with captive production infrastructure. Duke Traps represents backward-integrated supply security. Bridger Traps anchors western distribution density through Montana and Alberta dealer concentrations. These three named entities illustrate how geographic positioning and production control differentiate competitive standing.
| Leading Market Players |
|---|
| Tru Catch Traps |
| Duke Traps |
| Bridger Traps |
| Tomahawk Live Trap |
| Safeguard Traps |
| Hebei Liebang Metal Products |
| ADC Traps |
| Harris Traps |
| LB Traps |
| Others |
Value Network & Pricing Analysis
The Shanghai-Los Angeles container corridor's freight volatility compresses margin structures for mechanical trap manufacturers sourcing galvanized coil from Hebei Province while amplifying price spreads between USDA-certified premium tiers and uncertified commodity imports. This logistics chokepoint concentrates procurement power among backward-integrated domestic producers capable of absorbing coil cost swings through captive wire-forming operations.
Pricing Analysis
Price spreads between certified and uncertified trap tiers widen as EPA registration timelines extend beyond eighteen months, freezing formulation innovation and consolidating premium positioning among dossier-rich incumbents. Pricing stratifies across USDA APHIS-certified premium tiers, standard mechanical specifications for Corn Belt grain elevators, and economy imports serving price-sensitive residential channels. Cost compression in the economy tier intensifies because Hebei metalworking clusters flood export markets with galvanized components. Agricultural buyers operating federal crop insurance-compliant facilities demonstrate lowest price sensitivity due to specification mandates, while residential retail channels exhibit highest elasticity.
Supply Chain Analysis
Galvanized steel coil feeds from Hebei Province metalworking clusters, with secondary sourcing from South Korean and Turkish mills serving as swing supply. Spring mechanism components draw from Bavarian precision manufacturing and domestic Chinese wire-forming operations. Single-source vulnerability concentrates in Hebei coil supply exposed to export duty uncertainties and environmental enforcement shutdowns. Distribution runs through agricultural distributor networks concentrated in Iowa, Illinois, and Nebraska, with western livestock corridors served through Montana and Alberta dealer concentrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to harvest-cycle procurement patterns, with grain storage protection mandates intensifying replacement demand across Corn Belt cooperative facilities.
For Market Incumbents: Build certification moats by compressing USDA APHIS testing queue times through dedicated laboratory partnerships, defending against emerging smart trap entrants with telemetry-enabled product line extensions. Prioritize backward integration into wire-forming operations to neutralize Hebei coil price volatility threatening margin structures. For New Entrants and Emerging Players: Western Canadian livestock protection corridors offer underpenetrated white space where predator management protocols specify trap performance without incumbent dealer density. Target Alberta and Saskatchewan ranching operations through direct veterinary channel partnerships, bypassing established Montana distribution networks. Cellular-enabled monitoring subscriptions present the most penetrable technology segment for capital-light market entry. For Investors and Strategic Acquirers: Welded mesh automation specialists with USDA APHIS certification eligibility represent priority acquisition archetypes, capturing margin expansion from agricultural procurement consolidation. Long-term viability centers on subscription revenue migration in commercial property segments. Watch municipal trap ban preemption battles in Colorado and California as regulatory inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire-Forming | Duke Traps secures coil supply against Hebei export duty volatility through captive production. |
| Welded Mesh Automation Scale-Up | Tru Catch Traps expands throughput for Corn Belt seasonal procurement surges at its Nebraska facility. |
| Telemetry-Enabled Product Launch | Smart trap architectures shift commercial property revenue from labor contracts to hardware-plus-subscription structures. |
| Dealer Network Consolidation | Montana and Alberta concentrations offer geographic density in western livestock protection markets. |
| USDA APHIS Certification Investment | Federal contract eligibility filters uncertified competitors from grain elevator specification mandates. |
Research Methodology
Cross-validation between distributor procurement records and EPA FIFRA registration databases anchors the qualitative findings in observable transaction patterns. Primary interviews with grain elevator operators, agricultural cooperative procurement managers, wildlife damage control officers, and trap fabrication plant engineers combine with secondary validation through USDA APHIS performance standard filings, customs trade data for galvanized steel coil imports, and state-level trapping law preemption tracking. Bottom-up vendor shipment analysis triangulates against top-down agricultural storage capacity estimates.
Calibration against historical harvest-cycle procurement patterns and federal crop insurance compliance rates shapes the analytical framework across the projection horizon. Segmentation dimensions model product type tiers, end-user regulatory environments, technology maturity stages, and geographic procurement authority clusters. CAGRs derive from installed base replacement cycles, telemetry adoption curves in commercial properties, and municipal regulatory trajectory scenarios. Industry-specific inputs include galvanized steel price indices and USDA APHIS certification queue duration trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cellular-enabled monitoring specialists or Hebei export duty policy shifts would shift outcomes. Cross-checking against agricultural cooperative procurement budget disclosures and EPA registration timeline updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
UK Cat Food Market
Others
Vacuum Evaporators Market
Others
Asia-Pacific Military 4D Printing Market
Others
Delumper Market
Others
Server Market
Others
Aircraft Cameras Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Solar Animal Repellent Market
Others
Global Multi-Access Edge Computing Market
Others
Middle East and Africa Induced Pluripotent Stem Cells (Ipscs) Market
Others
Asia-Pacific Telecom Transformers Market
Others
Versatile Video Coding Market
Others
Industrial Air Pollution Control Solutions Market
Others
Managed Testing Services Market
Others
Smart TV Platforms Market
Others
Fresh Durian Market