
 Drain Cleaners Market | 2026-2036
Drain Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Drain Cleaners Market Analysis
Project finance for municipal wastewater infrastructure is narrowing the competitive field for industrial-grade drain cleaner suppliers. Procter & Gamble leverages its retail distribution density to sustain shelf dominance in household liquid formulations. Reckitt Benckiser Group PLC anchors professional channel relationships with commercial maintenance contractors. Henkel AG & Co. KGaA differentiates through enzymatic technology leadership in European institutional markets.
Drain cleaners are chemical or biological formulations designed to dissolve or dislodge organic matter, grease, and mineral deposits from piping systems, typically containing sodium hydroxide, sulfuric acid, or bacterial cultures with pH extremes ranging from 0.5 to 14. Their primary purpose is restoring flow capacity in residential, commercial, and municipal drainage networks without mechanical excavation. Liquid formulations command the largest revenue share due to consumer familiarity and immediate availability, while enzymatic and biological segments attract premium positioning as municipalities restrict caustic discharge. The residential end-user segment remains volume-dominant though commercial and industrial accounts yield higher per-unit margins through bulk supply contracts.
EPA Clean Water Act discharge standards and OSHA workplace chemical exposure limits shape product formulation decisions and labeling requirements across the United States. State-level restrictions on phosphorus content and volatile organic compounds further fragment compliance obligations for multi-market suppliers. Stakeholders must monitor regulatory divergence between federal baseline rules and accelerating state-level chemical disclosure mandates to anticipate reformulation costs and market access barriers.
Market Dynamics
Municipal procurement departments are consolidating vendor relationships as EPA wastewater discharge rules tighten, forcing suppliers to choose between reformulating caustic chemistries or exiting the institutional channel entirely.
Growth Catalysts
- EPA Clean Water Act enforcement:Municipal sewer maintenance departments face escalating penalties for corrosive discharge, accelerating enzymatic cleaner procurement cycles across the United States.
- Aging underground infrastructure:Century-old pipe networks in northeastern US cities require recurring chemical treatment rather than capital replacement, generating predictable demand.
- Enzymatic biotechnology:Bacterial culture formulations now match caustic performance on organic blockages while satisfying workplace safety protocols, opening institutional contracts previously closed to biological suppliers.
Market Restraints
- Caustic soda price volatility:Sodium hydroxide feedstock costs fluctuate with chlor-alkali plant utilization rates, compressing margins for legacy alkaline formulation producers.
- Concentrated retail distribution:Mass-market shelf space in the United States is controlled by three consumer goods conglomerates, blocking mid-tier brands from national household penetration.
- Technical performance ceiling:Enzymatic cleaners require 8-24 hour dwell times to dissolve hair and grease, limiting adoption in emergency plumbing scenarios where immediate flow restoration is mandatory.
Strategic Opportunities
- Commercial maintenance contractors:Facility management outsourcing trends create bundled service contracts where chemical supply is embedded in fixed-price agreements, locking in multi-year revenue.
- Phosphorus-free mandates:State-level restrictions in Maryland and Illinois on phosphorus content in cleaning products create first-mover advantage for reformulated compliant formulations.
- Subscription replenishment models:Direct-to-consumer channels bypass retail slotting fees while capturing recurring revenue from residential preventive maintenance routines.
Industry Challenges
- Formulation chemist scarcity:Expertise in pH-stable enzyme encapsulation is concentrated among a handful of biotechnology specialists, inflating R&D compensation costs.
- OSHA HazCom compliance timelines:Revised chemical labeling requirements demand 18-month packaging changeover cycles, straining working capital for SKU-heavy portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drain Cleaners Market |
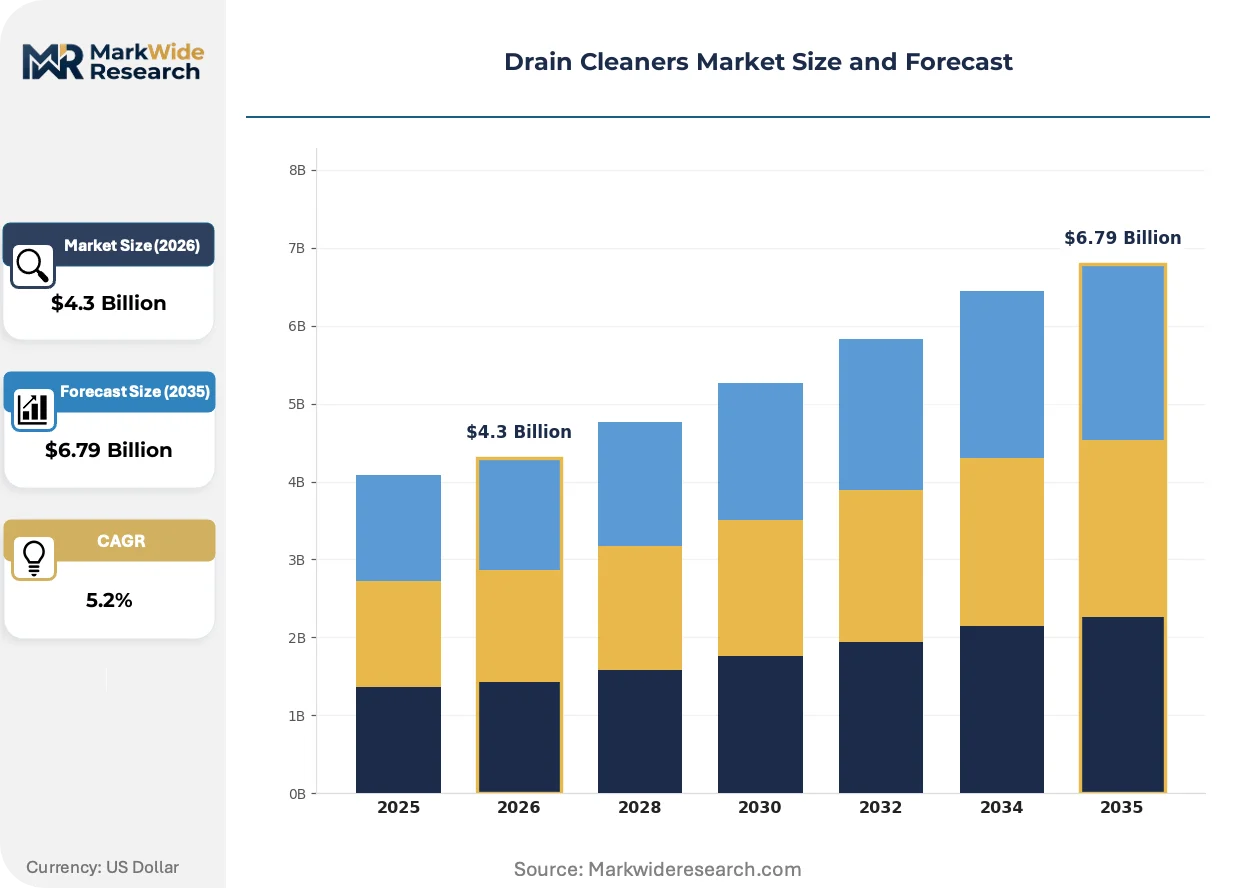
| Market Size in 2026 | $4.3 Billion |
| Market Size in 2035 | $6.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Gel, Powder, Tablet End User: Residential, Commercial, Industrial, Municipal Application: Kitchen, Bathroom, Sewage, Stormwater Formulation: Acidic, Alkaline, Enzymatic, Biological |
| Companies Covered | Procter & Gamble, Reckitt Benckiser Group PLC, S. C. Johnson & Son, Inc., Comstar International, PurposeBuilt Brands, The Clorox Company, Henkel AG & Co. KGaA, 3X Chemistry, Zep Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drain Cleaners Market Emerging Trajectories
Formulation chemistry is bifurcating into two incompatible paths: ultra-caustic emergency solutions versus slow-acting biological maintenance systems, with procurement departments now forced to dual-source rather than standardize.
Bio-enzymatic concentrate technology is collapsing the distinction between professional-grade and consumer-grade performance. These shelf-stable bacterial suspensions activate upon dilution, matching industrial caustic potency on organic matter without pipe corrosion. Commercial janitorial services in Texas and Florida are adopting concentrated enzymatic systems for grease trap maintenance, eliminating monthly pump-out costs. The technology is collapsing emergency service call frequency by enabling preventive dosing schedules that keep drains flowing rather than clearing blockages after failure.
REACH authorization requirements for sulfuric acid drain cleaners are tightening formulation standards across European institutional markets. The European Chemicals Agency's 2024 restriction proposal on high-concentration acidic cleaners forces manufacturers to register alternative chemistries or withdraw professional-grade products. German and Dutch municipal procurement offices are preemptively excluding sulfuric acid formulations from tender specifications, redirecting specification authority toward enzymatic and mechanical alternatives.
Facility managers are unbundling chemical supply from mechanical service contracts, reversing two decades of integrated vendor relationships. Large commercial real estate operators in California now separate drain maintenance into chemical procurement (bid separately) and hydro-jetting services (retained by incumbent plumbers). This procurement fragmentation is most advanced in Class A office buildings over 500,000 square feet, where sustainability scorecards favor discrete tracking of chemical usage volumes.
Drain Cleaners Market Segmentation
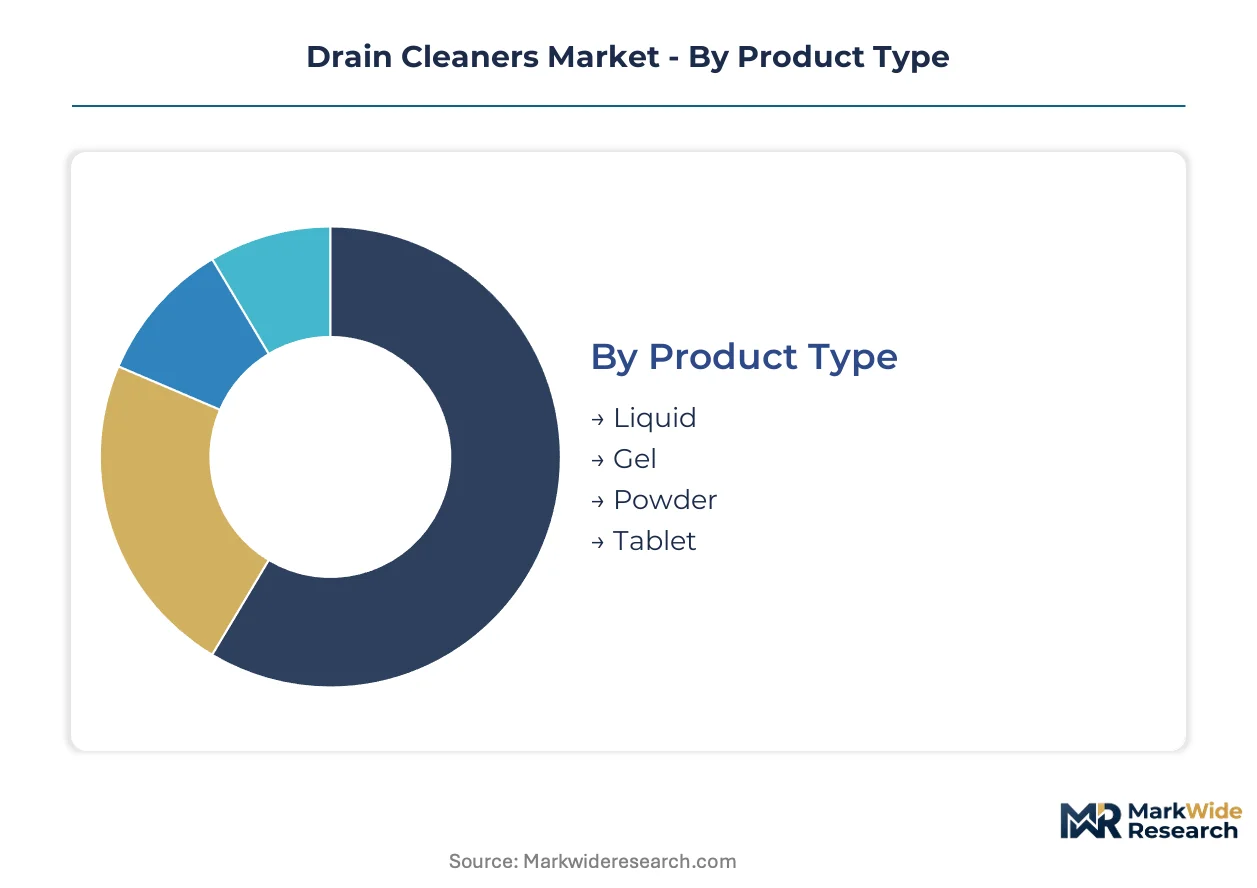
Drain cleaner procurement patterns diverge sharply across use environments, with formulation chemistry and physical form determining regulatory compliance, application method, and margin structure. Segmentation clarity enables suppliers to align R&D investment with channel-specific performance requirements and compliance obligations.
Product Type:
Physical form dictates shelf positioning, dosing precision, and emergency response capability across residential and institutional channels.
- Liquid:Pourable aqueous or solvent-based solutions dominate retail shelf space due to consumer familiarity and immediate pour-and-wait application. United States hardware stores and mass merchants allocate prime shelf positioning to liquid alkaline formulations, though enzymatic liquids are gaining placement in coastal states with stricter discharge regulations.
- Gel:Viscous cling formulations adhere to vertical pipe walls, extending contact time with grease accumulations in kitchen drain applications. Commercial kitchen operators in California and Florida specify gel products for grease trap maintenance, where dwell time determines dissolution efficiency on fatty acid deposits.
- Powder:Granular sodium hydroxide or sulfuric acid compounds activate upon water contact, generating exothermic reactions that accelerate organic decomposition. Industrial maintenance departments in Texas petrochemical facilities stock powder formulations for high-volume sewer line treatment, where transportation economics favor concentrated dry chemistry.
- Tablet:Slow-dissolving compressed formulations enable preventive maintenance dosing in residential garbage disposals and commercial floor drains. Subscription replenishment services in the Northeast United States are standardizing on enzymatic tablets for monthly preventive schedules, locking in recurring revenue through automated delivery.
Liquid holds installed capacity. Gel is rotating up the share rankings.
End User:
Customer type determines volume scale, price sensitivity, and the balance between emergency response and preventive maintenance procurement patterns.
- Residential:Individual households purchase small-format retail products for reactive clog clearing, with enzymatic brands capturing preventive maintenance routines through direct-to-consumer channels. EPA Safer Choice certification increasingly influences shelf selection in states with active environmental health campaigns.
- Commercial:Restaurants, hotels, and retail facilities require scheduled grease trap and drain line maintenance to comply with local sewer use ordinances. Facility management contractors in Illinois and Maryland are consolidating chemical supply into bundled service agreements, embedding drain cleaner procurement within fixed-price maintenance contracts.
- Industrial:Manufacturing plants and food processing facilities generate high-volume organic waste streams demanding industrial-grade formulations. OSHA Process Safety Management requirements constrain caustic chemistry selection in chemical processing corridors along the Gulf Coast, where sulfuric acid storage triggers heightened regulatory scrutiny.
- Municipal:City sewer departments procure bulk treatments for collection system maintenance and infiltration control. EPA consent decrees in northeastern cities are accelerating enzymatic cleaner adoption as municipalities face escalating penalties for corrosive discharge into receiving waters.
Residential commands absolute volume. Municipal is climbing the fastest as infrastructure age forces recurring treatment cycles.
Application:
Drain location determines blockage composition, pipe material compatibility, and the regulatory environment governing discharge.
- Kitchen:Grease, fat, and food particle accumulations require formulations effective against lipids and proteins. Enzymatic lipase formulations are displacing caustic soda in commercial kitchen specifications across the United States, where grease trap pretreatment regulations restrict alkaline discharge.
- Bathroom:Hair and soap scum blockages in lavatory and shower drains demand chemistry effective against keratin and calcium stearate. Acidic formulations retain dominance in residential bathroom applications, though hair-dissolving enzymatic alternatives are penetrating premium retail channels.
- Sewage:Municipal collection systems and building sanitary sewers handle mixed organic waste streams requiring high-volume treatment capacity. Bacterial culture formulations are expanding specification share in combined sewer overflow mitigation programs, where biofilm maintenance reduces emergency bypass events.
- Stormwater:Drainage systems handling rainfall runoff require sediment and debris clearing with minimal environmental impact. Phosphorus-free mandates in Maryland and Illinois are excluding traditional formulations from municipal stormwater maintenance contracts, redirecting procurement toward enzymatic and mechanical alternatives.
Kitchen applications anchor formulation R&D investment. Stormwater is gaining specification authority as green infrastructure procurement expands.
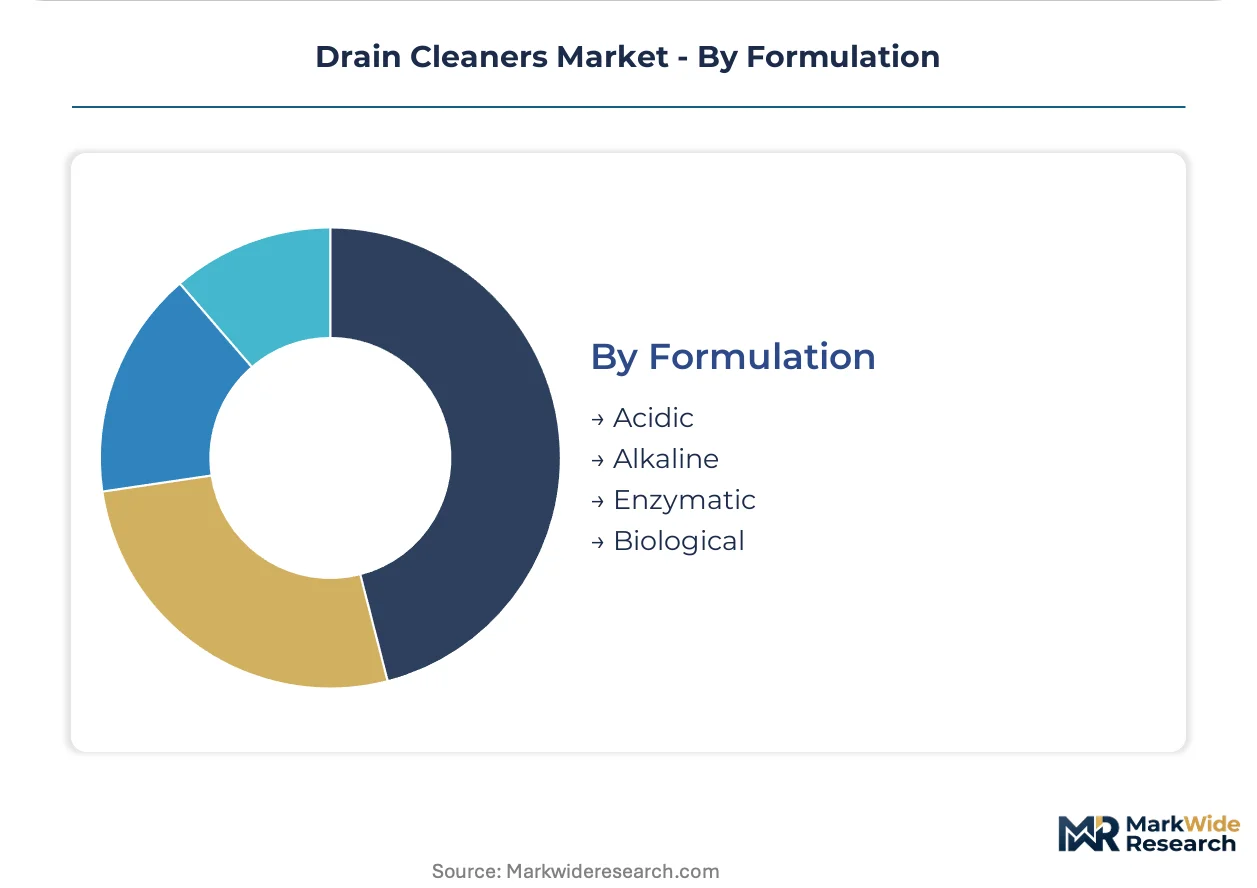
Formulation:
Chemistry type determines performance speed, material compatibility, workplace safety profile, and regulatory compliance burden.
- Acidic:Sulfuric acid and hydrochloric acid formulations dissolve mineral deposits and organic matter through aggressive proton donation. REACH authorization pressures in Europe and EPA discharge scrutiny in the United States are constraining specification opportunities, though emergency response applications retain demand for immediate flow restoration.
- Alkaline:Sodium hydroxide-based chemistry saponifies grease and hydrolyzes proteins through high-pH environments. Chlor-alkali feedstock volatility is compressing margins for legacy producers, while OSHA HazCom labeling requirements demand 18-month packaging changeover investments.
- Enzymatic:Stabilized bacterial enzyme suspensions catalyze organic decomposition without pipe corrosion or toxic discharge. pH-stable encapsulation expertise concentrates among biotechnology specialists, inflating R&D compensation costs while opening institutional contracts previously closed to biological suppliers.
- Biological:Live bacterial cultures establish persistent biofilm colonies that continuously digest organic waste streams. Commercial janitorial services in Texas and Florida are adopting concentrated biological systems for grease trap maintenance, eliminating monthly pump-out costs through preventive dosing schedules.
Alkaline formulations hold installed capacity. Enzymatic is expanding most quickly as discharge regulations tighten across multiple jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement departments dominate demand in aging infrastructure corridors, while commercial facility managers drive specification shifts toward enzymatic formulations in discharge-regulated zones.
United States
Northeastern cities with century-old sewer systems require recurring chemical treatment cycles rather than capital replacement. EPA consent decrees in cities like Pittsburgh and Cleveland accelerate enzymatic cleaner procurement as municipalities face escalating penalties for corrosive discharge. Commercial janitorial services in Texas and Florida are adopting concentrated enzymatic systems for grease trap maintenance.
Germany
REACH authorization requirements for sulfuric acid drain cleaners are tightening formulation standards across institutional markets. The European Chemicals Agency's restriction proposal on high-concentration acidic cleaners forces manufacturers to register alternative chemistries. German municipal procurement offices in the Ruhr region are preemptively excluding sulfuric acid formulations from tender specifications.
China
Rapid urbanization and expanding municipal sewer networks generate demand for industrial-grade maintenance chemicals. The Ministry of Ecology and Environment's wastewater discharge standards are tightening enforcement in coastal provinces. Manufacturing clusters in Jiangsu and Zhejiang provinces are adopting biological treatment systems to comply with stricter effluent regulations.
India
Expanding urban infrastructure and aging colonial-era drainage systems in major metros drive maintenance chemical demand. The Central Pollution Control Board's sewage treatment standards are pressuring municipalities to upgrade collection system maintenance practices. Municipal corporations in Maharashtra and Tamil Nadu are piloting enzymatic treatment programs in high-density urban corridors.
Brazil
Informal housing settlements and expanding commercial districts create fragmented demand for both emergency and preventive drain maintenance. State environmental agencies in São Paulo and Rio de Janeiro are tightening industrial discharge monitoring. Commercial facility operators in southeastern industrial zones are consolidating chemical supply into bundled service contracts.
Drain Cleaners Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Mass-market retail shelf space concentrates among consumer goods conglomerates with established distribution density, while institutional channels fragment across regional chemical suppliers and biotechnology specialists. Three archetypes dominate: retail shelf-space controllers, professional channel relationship holders, and enzymatic technology specialists. Competitive moves center on portfolio diversification into enzymatic formulations and strategic partnerships with facility management contractors.
Within the retail-dominant tier, Procter & Gamble and Reckitt Benckiser Group PLC exemplify channel-controlling archetypes with established mass-market penetration. Henkel AG & Co. KGaA occupies a position representing enzymatic technology leadership in European institutional markets. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Procter & Gamble |
| Reckitt Benckiser Group PLC |
| S. C. Johnson & Son, Inc. |
| Comstar International |
| PurposeBuilt Brands |
| The Clorox Company |
| Henkel AG & Co. KGaA |
| 3X Chemistry |
| Zep Inc. |
| Others |
Supply Flow & Price Mechanics
Gulf Coast petrochemical corridor freight costs shape competitive positioning across the drain cleaner value chain, concentrating margin pressure on alkaline formulation producers while enabling enzymatic specialists to command premium positioning through differentiated supply economics.
Pricing Analysis
Cost-plus contracts indexed to chlor-alkali plant utilization rates dominate industrial-grade alkaline procurement, tethering municipal buyers to sodium hydroxide feedstock volatility. Three-tier pricing structure across premium enzymatic, standard alkaline, and economy private-label tiers separates EPA Safer Choice-certified formulations from commodity caustic chemistry. Pricing pressure stems from concentrated retail shelf space controlled by consumer goods conglomerates, compressing mid-tier brand margins. Residential households exhibit highest price sensitivity through private-label substitution, while municipal procurement departments prioritize discharge compliance over unit cost.
Supply Chain Analysis
Upstream sodium hydroxide production concentrates in Louisiana and Texas chlor-alkali corridors, with sulfuric acid sourcing anchored in Florida phosphate processing clusters. Formulation chemistry draws from chlor-alkali co-products, bacterial culture fermentation facilities, and specialty enzyme encapsulation suppliers. Single-source vulnerability runs through Gulf Coast petrochemical infrastructure exposed to hurricane disruption. Distribution runs through mass-market retail slotting, janitorial supply wholesalers, and direct municipal tender channels with divergent working capital requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal procurement consolidation is shifting buyer power toward institutional channels, fragmenting legacy retail-centric competitive dynamics and forcing suppliers to choose between reformulation investments or channel exit.
For Market Incumbents: Build regulatory compliance moats through EPA Safer Choice certification and state-level phosphorus-free formulation registration. Incumbents should secure multi-year municipal maintenance contracts before enzymatic technology commoditizes, while acquiring bacterial culture fermentation capacity to offset chlor-alkali feedstock volatility. Alkaline formulation margin compression from sodium hydroxide price swings demands backward integration into enzyme encapsulation R&D.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription channels bypassing retail slotting fee barriers, targeting preventive maintenance routines in Northeast US households with aging infrastructure. White-space opportunity concentrates in stormwater phosphorus-free mandates across Maryland and Illinois municipal contracts. Go-to-market positioning should anchor on EPA discharge compliance cost avoidance rather than performance parity with caustic chemistry.
For Investors and Strategic Acquirers: Enzymatic biotechnology specialists with pH-stable encapsulation expertise represent priority acquisition targets, given formulation chemist scarcity and R&D compensation inflation. Long-term viability favors suppliers with dual alkaline-enzymatic portfolios capable of serving both emergency response and preventive maintenance procurement patterns. Signal to monitor: EPA consent decree acceleration in additional northeastern cities forcing municipal enzymatic adoption timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Production | Captures margin from bacterial culture fermentation while reducing chlor-alkali feedstock dependency. |
| EPA Safer Choice Certification Investment | Unlocks municipal procurement specifications in discharge-regulated northeastern corridors. |
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees while locking recurring revenue from preventive maintenance households. |
| Phosphorus-Free Formulation Registration | Secures first-mover positioning in Maryland and Illinois state-mandated procurement channels. |
| Long-Term Municipal Maintenance Contract | Embeds chemical supply within bundled facility management agreements spanning multi-year horizons. |
Methodological Framework
Cross-validation between municipal procurement officer interviews and customs trade data anchors the qualitative findings on supply concentration. Primary fieldwork engaged plant managers at chlor-alkali facilities, janitorial supply distributors, EPA regional enforcement officers, and facility management contractors across Texas, Florida, and northeastern states. Secondary validation drew from EPA consent decree filings, state-level phosphorus restriction registers, ACC chemical trade flow reports, and SEC 10-K disclosures from consumer goods conglomerates. Bottom-up channel volume estimates were triangulated against top-down chemical production capacity assessments.
Calibration against historical enzymatic adoption curves in European REACH-regulated markets informed the projection framework. Segmentation modeling spanned formulation chemistry, physical form, end-user type, and application environment across the analysis window. CAGRs were derived from installed base treatment cycle frequencies and municipal infrastructure age distributions. Forecast inputs incorporated chlor-alkali plant utilization rate correlations and EPA enforcement budget allocation patterns.
Stress conditions across sodium hydroxide price volatility bands, EPA consent decree acceleration scenarios, and retail shelf consolidation outcomes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding enzymatic performance parity achievement timelines and state-level regulatory harmonization progress. Cross-checking against European ECHA restriction implementation trajectories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Water Purifier Market
Household Items
North America Water Purifier Market
Household Items
Trash Can Market
Household Items
Wipes Market
Household Items
Global Nap Pod Market
Household Items
United States Barbeque Grill Market
Household Items
Disposable Napkins Market
Household Items
Luxury Massage Chair Market
Household Items
India Digital Showers Market
Household Items
Cutlery Market
Household Items
India Cookware Market
Household Items
Collapsible Water Bottle Market
Household Items
Gas Hobs Market
Household Items
Mirror Holder Market
Household Items
Germany Digital Showers Market
Household Items
Leaf Blower Market