
 North America Water Purifier Market | 2026-2036
North America Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
North America Water Purifier Market Outlook
Modular point-of-use configurations is rebalancing buyer choice across the North America Water Purifier Market as households unbundle whole-house systems into layered under-sink and countertop units. Pentair leverages its captive filtration media production to anchor margin control in the point-of-entry segment. Culligan International Company competes through dealer-network density in the US Midwest and Ontario corridor. A.O. Smith Corporation differentiates via R&D intensity in tankless reverse osmosis designs.
A water purifier is a treatment device engineered to reduce contaminants—particulate, chemical, and microbiological—through physical barriers, adsorption media, or ultraviolet irradiation, typically achieving NSF/ANSI Standard 53 or 58 certification for specific pollutant reduction. Its primary commercial purpose is to deliver potable water that meets or exceeds jurisdictional safety thresholds for residential, commercial, and industrial end users. Reverse osmosis systems occupy the premium tier of the product type landscape due to membrane replacement revenue and higher installed margins. Point-of-use installation dominates residential volume while point-of-entry systems capture commercial and municipal retrofit projects. Online retail channels are displacing specialty stores for replacement cartridge sales, though whole-house systems still move through direct sales and contractor networks.
The US EPA enforces National Primary Drinking Water Regulations that mandate maximum contaminant levels, directly shaping product certification requirements and filter replacement cadences across the market. Health Canada and PMRA coordinate on allowable treatment chemical residuals, creating cross-border standardization pressure for manufacturers serving both markets. The NSF/ANSI joint standards framework governs performance claims verification, functioning as a de facto market access gate. Stakeholders must monitor evolving PFAS and microplastics regulatory thresholds to anticipate filtration technology pivots and certification investment cycles.
Market Dynamics
The EPA's revised National Primary Drinking Water Regulations for PFAS contamination are compressing replacement cycles and forcing technology upgrades across residential and commercial installations. Municipal water quality variability in Sun Belt states is accelerating household migration from pitcher filters to under-sink reverse osmosis systems.
Growth Catalysts
- PFAS regulatory mandates:The EPA's enforceable maximum contaminant levels for per- and polyfluoroalkyl substances are compelling municipal utilities and households to deploy certified filtration systems ahead of compliance deadlines.
- Aging infrastructure replacement:Texas and Florida suburban developments are retrofitting reverse osmosis units as lead service line inventories and treatment plant capacity constraints strain municipal delivery reliability.
- Membrane technology maturation:Thin-film composite polyamide membranes are achieving higher rejection rates at lower operating pressures, reducing energy consumption and expanding residential feasibility.
Market Restraints
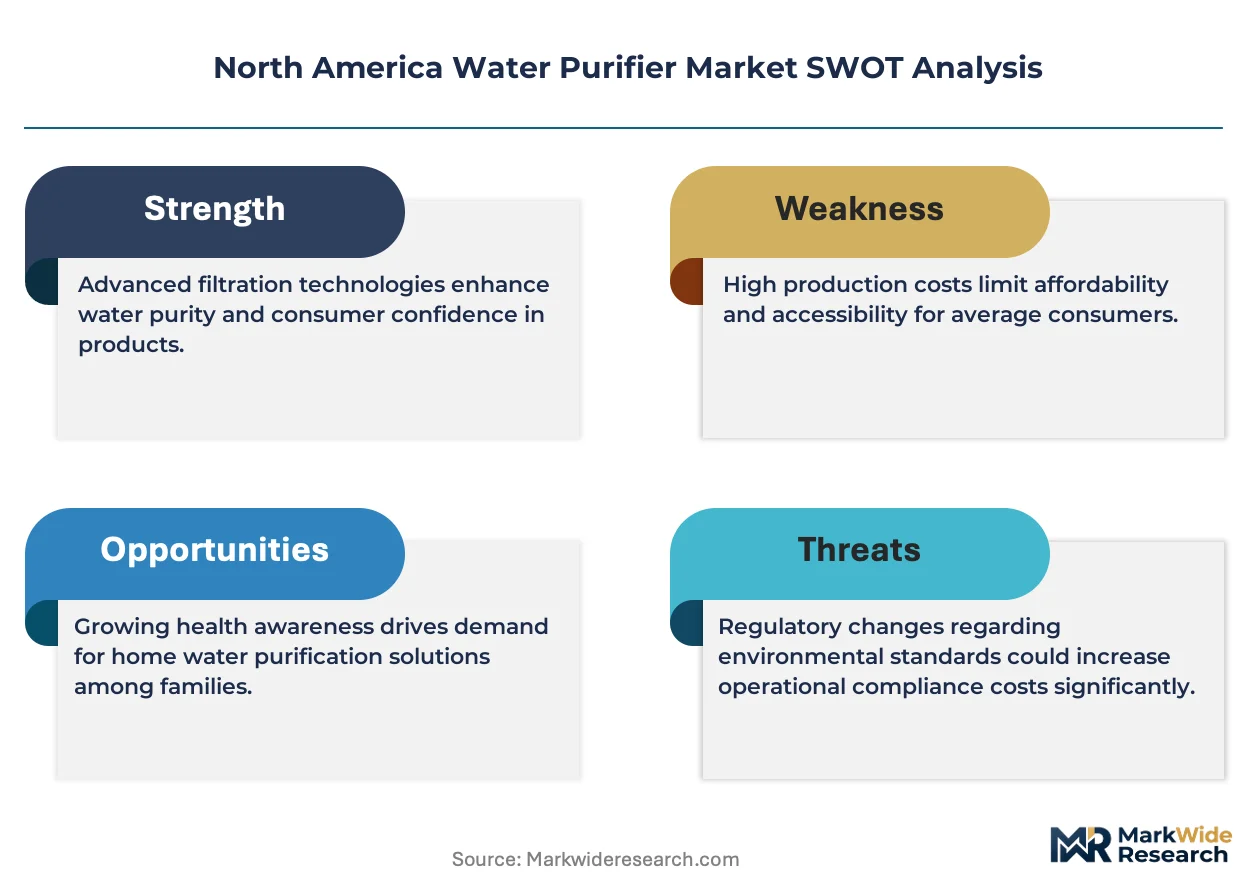
- Replacement cartridge cost volatility:Activated carbon block and ion exchange resin prices fluctuate with petroleum feedstock and specialty chemical supply chains, compressing recurring revenue margins for dealers.
- Point-of-entry system concentration:Commercial and whole-house installations depend on certified plumbing contractors concentrated in metropolitan corridors, limiting rural market penetration.
- Reverse osmosis wastewater ratio:Traditional systems reject three to four gallons per purified gallon, creating friction in drought-prone western states with municipal water use restrictions.
Strategic Opportunities
- Underpenetrated Canadian provinces:Manitoba and Saskatchewan rural communities with private well dependence present untapped demand for NSF/ANSI 53-certified point-of-use systems.
- UV-LED convergence with filtration:Mercury-free ultraviolet disinfection modules are integrating with carbon block stages to address microbiological concerns without chemical residuals.
- Direct-to-consumer cartridge subscriptions:Online channels are capturing replacement filter volume from specialty retailers through predictive consumption algorithms and automated replenishment.
Industry Challenges
- NSF/ANSI certification timeline compression:Emerging contaminant test protocols for microplastics and PFAS subclasses are extending laboratory validation cycles and delaying product launches.
- Installation labor scarcity:Certified water treatment specialists are concentrated in legacy dealer networks, constraining scaling for tankless reverse osmosis rollouts requiring plumbing modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Water Purifier Market |
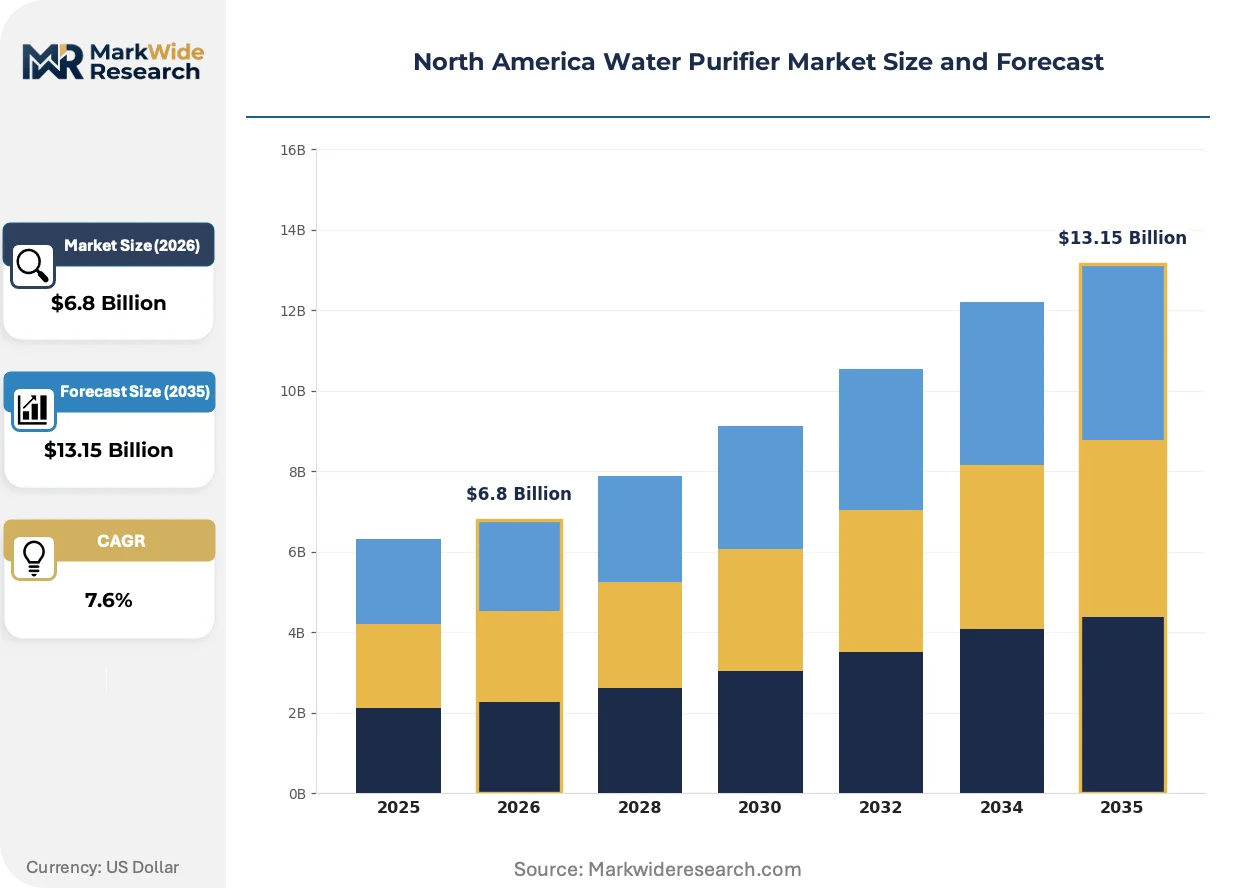
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Reverse Osmosis, Ultraviolet, Gravity-Based End User: Residential, Commercial, Industrial, Municipal Installation Type: Point of Use, Point of Entry, Under Sink, Whole House Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Pentair, Unilever, 3M, EcoWater Systems, Coway, A.O. Smith Corporation, LG Electronics, Brita, Culligan International Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Water Purifier Market Strategic Shifts
Modular system architectures are fragmenting the traditional whole-house versus point-of-use dichotomy, enabling households to layer filtration stages across multiple consumption points. Technology convergence and regulatory precision are compressing product development cycles while expanding performance verification requirements.
Tankless reverse osmosis designs are eliminating storage tank contamination risks and reducing under-sink footprint. Suburban households in high-growth Sun Belt counties are adopting these configurations at accelerated pace. This technology is integrating with smart faucet interfaces and filter life monitoring to enable predictive maintenance and reduce premature cartridge replacement.
The EPA's National Primary Drinking Water Regulations for PFAS are mandating enforceable limits for six specific compounds by 2029. Water treatment OEMs are accelerating membrane and activated carbon formulation pivots to achieve certified reduction claims. Point-of-use residential systems in contaminated groundwater zones are experiencing the steepest compliance-driven upgrade demand.
Replacement filter procurement is migrating from hardware stores to manufacturer-direct subscriptions and Amazon marketplace storefronts. Specialty retailers are losing cartridge volume to automated replenishment models that lock in multi-year customer lifetime value. This channel rotation is most advanced in California and Texas metropolitan statistical areas with high e-commerce penetration and younger homeowner demographics.
North America Water Purifier Market Segmentation
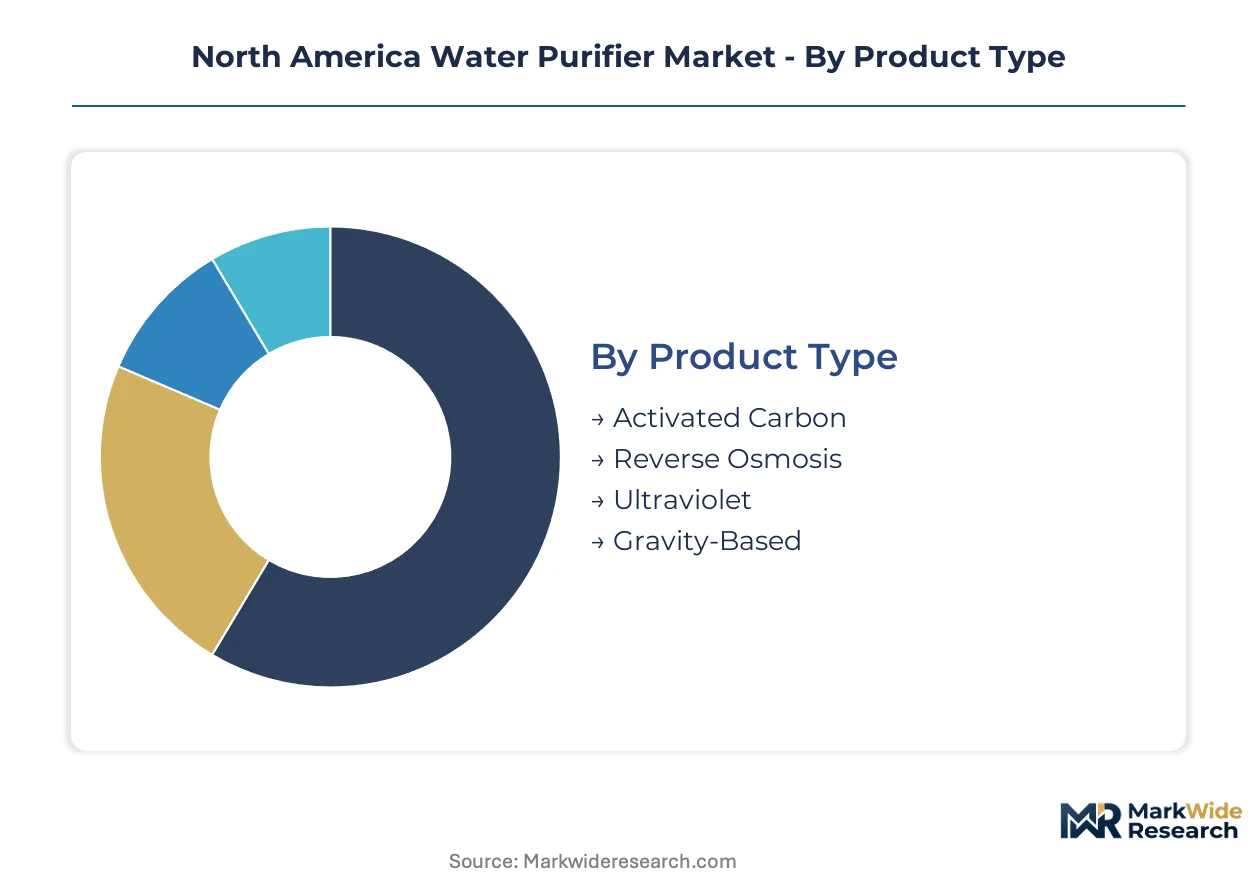
Water purifier purchasing decisions fragment across technical performance tiers, installation complexity, and regulatory compliance requirements. Buyers trade off upfront capital against certification depth and replacement economics. Segmentation reveals where margin concentrates versus where volume flows.
Product Type:
Customization versus standardization splits sharply across this category, with certified multi-stage systems commanding premium positioning against commodity gravity alternatives.
- Reverse Osmosis:Thin-film composite polyamide membranes achieve NSF/ANSI 58 certification for dissolved solids reduction. Sun Belt suburban households in Texas and Florida are retrofitting these as municipal PFAS advisories accelerate upgrade cycles from pitcher filters.
- Activated Carbon:Block and granular configurations adsorb chlorine, VOCs, and organic compounds through surface area binding. Point-of-use residential installations in Canadian provinces with private well dependence favor carbon pre-filtration for taste and odor remediation ahead of tighter membrane stages.
- Ultraviolet:Low-pressure mercury or UV-LED chambers deliver 254nm irradiation for microbiological inactivation without chemical residuals. Systems integrate downstream of particulate filtration to prevent shadowing.
- Gravity-Based:Ceramic candle and activated carbon gravity filters operate without plumbing or electricity. Camping supply channels and emergency preparedness segments sustain this lowest-cost tier.
Leading the category by volume: Activated Carbon. Expanding most quickly: Reverse Osmosis.
End User:
Cost tier stratification separates specification-intensive municipal procurement from price-sensitive residential replacement cycles.
- Residential:Single-family and multi-unit dwellings drive cartridge replacement frequency through consumption-based degradation. Under-sink reverse osmosis installations in Arizona and Nevada are climbing fastest as drought restrictions intensify water quality scrutiny.
- Commercial:Foodservice, healthcare, and office installations require NSF/ANSI 53 certification for lead and cyst reduction. Restaurants in California metropolitan corridors face health department inspection mandates for certified filtration.
- Industrial:Manufacturing process water and boiler feed applications demand pre-treatment systems with documented performance guarantees. Semiconductor fabrication in Oregon and Arizona purchases high-purity reverse osmosis with deionization polishing.
- Municipal:Water treatment plant retrofits and distribution system upgrades respond to EPA enforceable contaminant limits. Small utilities in Michigan and Wisconsin are prioritizing PFAS removal ahead of compliance deadlines.
Residential commands absolute unit volume. Municipal projects carry the steepest per-installation value.
Installation Type:
Application context dictates whether filtration concentrates at single taps or distributes across building plumbing.
- Point of Use:Countertop and faucet-mounted units serve specific consumption points without plumbing modification. Online retail channels are capturing replacement filter subscriptions for these configurations in Texas and California.
- Point of Entry:Whole-building systems treat water at the service line entry for comprehensive protection. Commercial installations in Ontario and Quebec require certified plumbing contractor involvement.
- Under Sink:Dedicated cold-water taps and inline refrigerator connections hide filtration from counter space. Tankless reverse osmosis designs are eliminating storage contamination risks in Florida new construction.
- Whole House:Central softening and filtration combinations address hardness plus particulate and chemical reduction. Rural properties on private wells in Manitoba and Saskatchewan specify these for comprehensive treatment.
Point of Use dominates residential transaction counts. Point of Entry captures commercial margin.
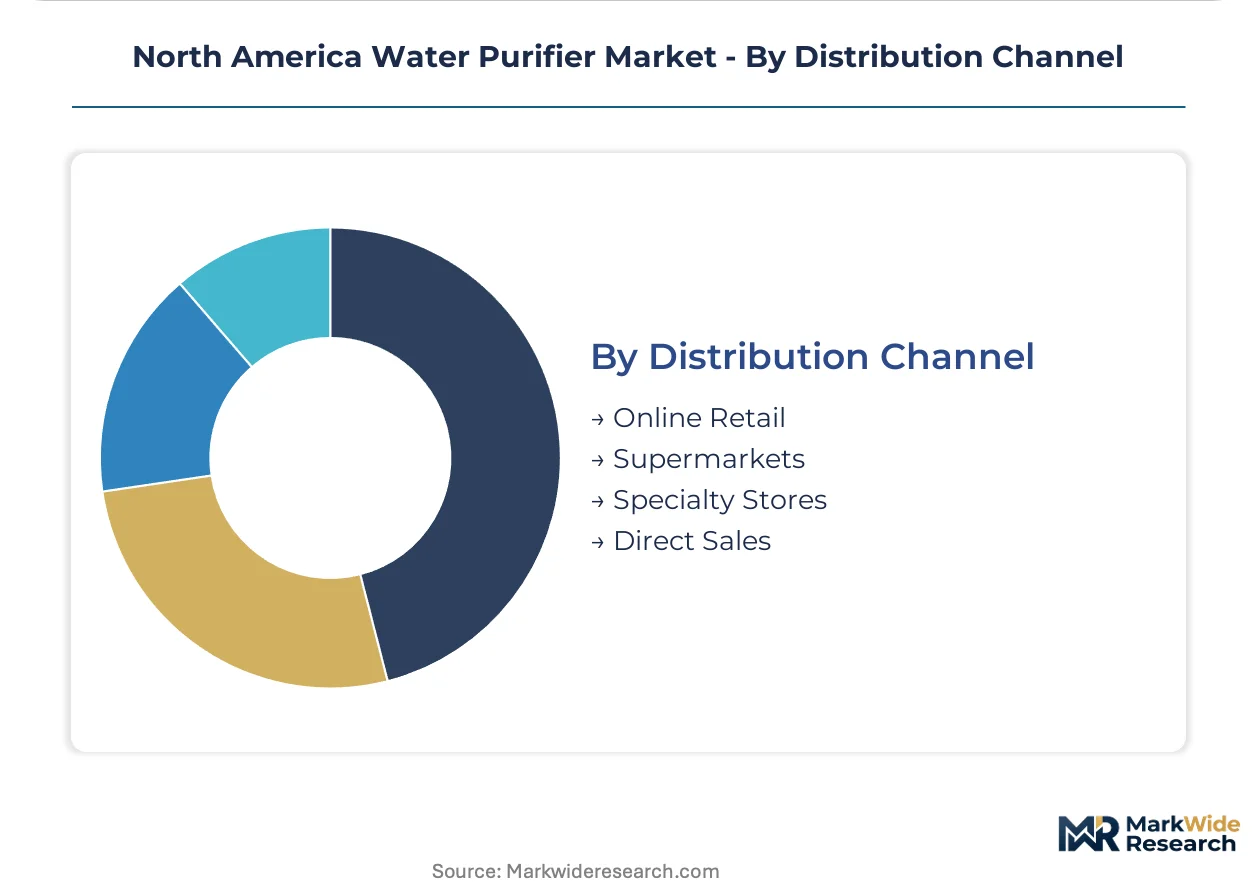
Distribution Channel:
Customer type and purchase occasion separate automated replenishment from high-consideration installation sales.
- Online Retail:Amazon marketplace and manufacturer-direct storefronts capture replacement cartridge volume through predictive algorithms. Younger homeowner demographics in metropolitan statistical areas show highest e-commerce penetration.
- Supermarkets:Mass merchandisers move pitcher filters and faucet-mount units through seasonal promotions and impulse placement. Big-box retailers in the US Midwest stock seasonal inventory ahead of spring home improvement cycles.
- Specialty Stores:Dedicated water treatment dealers provide specification consultation and certified installation. These channels retain whole-house system sales requiring plumbing contractor coordination.
- Direct Sales:Manufacturer-employed representatives and dealer networks handle commercial and municipal procurement with extended payment terms. Pentair and Culligan leverage this channel for point-of-entry project bids.
Online Retail is gaining share fastest for consumables. Direct Sales retains project complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Opportunity Zones program and Canadian provincial infrastructure funds are concentrating manufacturing and distribution capacity near border logistics corridors serving water treatment equipment deployment.
United States
Texas and Florida suburban households are retrofitting under-sink reverse osmosis units as municipal PFAS advisories accelerate upgrade cycles from basic pitcher filters. The EPA's revised National Primary Drinking Water Regulations mandate enforceable maximum contaminant levels for six PFAS compounds by 2029. The Dallas-Fort Worth metroplex anchors dealer-network density for point-of-entry system installations serving rapid suburban expansion.
Canada
Manitoba and Saskatchewan rural communities with private well dependence present untapped demand for NSF/ANSI 53-certified point-of-use systems. Health Canada and PMRA coordinate on allowable treatment chemical residuals, creating cross-border standardization pressure for manufacturers. The Ontario-Quebec corridor retains specialty dealer concentration for whole-house system sales requiring certified plumbing contractor involvement.
Mexico
Northern border states experience cross-border equipment flows as US manufacturers establish maquiladora assembly for reverse osmosis membrane housings and activated carbon block production. The country's national water commission implements potable water quality standards that elevate certification requirements for imported filtration equipment. The Monterrey metropolitan area concentrates industrial water treatment procurement for manufacturing process water applications.
North America Water Purifier Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: diversified industrial conglomerates with captive filtration media production, established water treatment specialists leveraging dealer-network density, and consumer electronics brands extending into smart filtration interfaces. M&A activity concentrates on membrane technology acquisitions and regional dealer network consolidation. Geographic expansion into underpenetrated Canadian provinces represents the dominant competitive move alongside portfolio diversification into tankless reverse osmosis configurations.
Among diversified industrial conglomerates, 3M and Pentair occupy positions anchoring upstream control over activated carbon block and specialty membrane production. A.O. Smith Corporation exemplifies the specialist archetype through R&D intensity in tankless reverse osmosis designs. These three companies represent distinct competitive vectors: materials science integration, captive supply chain control, and product-level innovation focus.
| Leading Market Players |
|---|
| Pentair |
| Unilever |
| 3M |
| EcoWater Systems |
| Coway |
| A.O. Smith Corporation |
| LG Electronics |
| Brita |
| Culligan International Company |
| Others |
Value Chain & Pricing Dynamics
EPA-mandated PFAS certification upgrades are forcing manufacturers to absorb extended laboratory validation timelines and reformulation costs, compressing margins on legacy carbon block systems while creating pricing power for membrane suppliers with pre-certified NSF/ANSI 58 portfolios.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to tankless reverse osmosis units for new construction projects in Florida and Texas, while spot inventory of replacement cartridges clears at discounted rates through Amazon marketplace storefronts. Three-tier pricing structure across premium certified systems, standard dealer-installed units, and economy pitcher filters anchors the market. Pricing pressure stems from petroleum feedstock volatility in activated carbon block production, squeezing recurring revenue margins. Residential households exhibit highest price sensitivity, while municipal procurement offices prioritize certification depth over unit cost.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Toronto anchor hub-and-spoke patterns serving Sun Belt suburban expansion and Ontario-Quebec whole-house installations. Manufacturing concentrates in the United States, Mexico, and China for membrane housings, activated carbon block production, and UV-LED module assembly. Raw material dependencies include thin-film composite polyamide, petroleum-derived carbon feedstock, and specialty ion exchange resins. Tariff exposure on Chinese-sourced electronic control boards creates single-source vulnerability for smart filtration interfaces. Distribution runs through certified plumbing contractor networks for point-of-entry systems and direct-to-consumer channels for cartridge replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Water Purifier Market sits in a technology-transition phase as tankless reverse osmosis designs displace storage-tank configurations across suburban new construction.
For Market Incumbents: Hedge against membrane commoditization by locking in captive activated carbon block production and securing exclusive dealer-network density in Texas and Florida corridors. Defensive moves center on NSF/ANSI certification pre-positioning for emerging microplastics test protocols and backward integration into specialty resin formulation to offset petroleum feedstock volatility. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting replacement cartridge volume in California and Texas metropolitan statistical areas with high e-commerce penetration. White-space targets include Manitoba and Saskatchewan rural well-water households lacking certified point-of-use options, plus UV-LED convergence products addressing microbiological concerns without mercury disposal liabilities. For Investors and Strategic Acquirers: The window for entry favors membrane technology specialists with validated PFAS reduction claims ahead of EPA compliance deadlines. Long-term viability rests on consolidation of regional dealer networks serving commercial point-of-entry procurement. Watch for Health Canada-EPA regulatory harmonization announcements as inflection indicators for cross-border standardization plays.| Strategic Initiative | Industry Significance |
|---|---|
| Tankless Reverse Osmosis Platform Launch | Eliminates storage contamination risks in Florida new construction while reducing under-sink footprint. |
| PFAS Certification Pre-Investment | Positions portfolios ahead of EPA enforceable maximum contaminant levels for six compounds. |
| Dealer Network Consolidation | Captures commercial point-of-entry margin concentrated in Ontario-Quebec plumbing contractor relationships. |
| Direct-to-Consumer Subscription Buildout | Locks multi-year customer lifetime value through automated cartridge replenishment algorithms. |
| UV-LED Module Integration | Addresses microbiological concerns without chemical residuals or mercury disposal compliance. |
Study Parameters
Independent corroboration across primary interviews with water treatment OEM product managers, certified plumbing contractor network heads, municipal utility procurement officers, and specialty dealer principals, combined with secondary validation of EPA enforcement guidance documents, Health Canada advisories, NSF/ANSI test protocol revisions, and customs trade data on filtration media imports, underwrites the qualitative findings. Bottom-up triangulation of point-of-use installation counts and top-down reconciliation against residential construction permitting data anchor the quantitative framework.
Comparable-period anchoring to historical replacement cycle data and municipal compliance investment waves structures the forecast window across the analysis window. Modeled segmentation dimensions span product type, installation configuration, end-user category, and distribution channel, with regulatory compliance tier as an industry-specific overlay. CAGRs derive from trend extrapolation of certification-driven upgrade velocity and membrane technology maturation curves, incorporating drought restriction intensity indices and PFAS contamination mapping as forecast inputs.
Regulatory timeline acceleration, feedstock price volatility, and certification protocol extensions are the dominant revision risks to the outlook. Forecasts reflect documented assumptions on compliance deadline adherence and technology substitution elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
China Cookware Market
Household Items
Water Purifier Market
Household Items
Permanent Marker Market
Household Items
Neck Pillows Market
Household Items
India Non-Stick Cookware Market
Household Items
Bladeless Neck Fan Market
Household Items
Cups and Pots Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Portable Air Humidifier and Dehumidifier Market
Household Items
Portable Steam Cleaners Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Cookware Market
Household Items
Insulated Drinkware Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Flatware Market
Household Items
Pet Fur Remover Market