
 Trash Can Market | 2026-2036
Trash Can Market Size, Share, and Industry Trends Forecast 2026-2036
Trash Can Market Analysis
Modular sensor-battery units bundled with premium stainless steel housings is rebalancing buyer choice toward upgradeable systems over disposable replacements. Simplehuman leverages in-house production of precision-fit liners to sustain margin control across direct-to-consumer channels. Rubbermaid dominates institutional procurement through scale manufacturing of standardized commercial-grade containers. iTouchless competes on motion-sensor reliability, positioning its product line for hospitality and healthcare contracts.
A trash can is a rigid receptacle engineered from stamped steel, injection-molded polypropylene, or rotationally molded HDPE, designed to contain solid waste with capacities ranging from under ten liters for residential desks to over 360 liters for industrial roll-out applications. Its primary commercial purpose is to enable sanitary waste segregation, odor containment, and compliant disposal workflows across residential, commercial, and public environments. Stainless steel residential products command the highest margin pools due to aesthetic premiums and durability expectations in urban households. Plastic commercial SKUs lead volume through low unit costs and color-coded recycling compliance. Motion sensor feature sets represent the fastest-growing configuration as facilities managers prioritize touchless hygiene protocols.
EPA waste characterization standards shape material specifications for municipal procurement in the United States. REACH and RoHS frameworks in Europe restrict hazardous substance content in metal finishes and electronic sensor components. ISO 9001 quality management certifications function as baseline market access requirements for export-oriented manufacturers. Stakeholders must monitor evolving extended producer responsibility mandates that will dictate recyclability quotas and end-of-life collection obligations.
Market Dynamics
Sensor-battery modularization is compressing replacement cycles and forcing incumbents to pivot from disposable hardware to upgradeable platforms, redistributing margin pools toward software-enabled service contracts.
Growth Catalysts
- EU Green Deal mandates:Single-use plastic directives and extended producer responsibility frameworks accelerate demand for recycled-content receptacles in municipal procurement across Germany, France, and the Netherlands.
- Touchless hygiene protocols:Healthcare and hospitality facilities managers prioritize motion-sensor configurations to reduce pathogen transmission risks in high-traffic environments.
- Smart city infrastructure budgets:Urban centers in the United States and South Korea deploy fill-level sensors and route-optimization software to reduce collection fleet operating costs.
Market Restraints
- Stainless steel input volatility:Nickel and chromium price swings compress margin stability for premium residential product lines dependent on aesthetic metal finishes.
- Sensor component concentration:LiDAR and ultrasonic module supply clusters in Taiwan and South Korea create vulnerability for motion-enabled SKU production schedules.
- REACH substance restrictions:ECHA limitations on hexavalent chromium in metal coatings force reformulation of legacy commercial-grade surface treatments.
Strategic Opportunities
- India urban sanitation expansion:Smart Cities Mission funding creates procurement windows for sensor-equipped public waste infrastructure in tier-1 and tier-2 municipalities.
- Subscription liner services:Direct-to-consumer channels enable recurring revenue attachment to precision-fit consumables, decoupling growth from unit sales velocity.
- Carbon accounting convergence:CSRD disclosure requirements position receptacle manufacturers to bundle embodied-carbon tracking with municipal fleet management software.
Industry Challenges
- Embedded systems integration:Facilities managers face complexity unifying proprietary sensor protocols with legacy building management networks in multi-vendor environments.
- IP fragmentation in motion-detection:Patent thickets around ultrasonic and infrared sensing technologies create licensing friction for mid-tier manufacturers entering the touchless segment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trash Can Market |
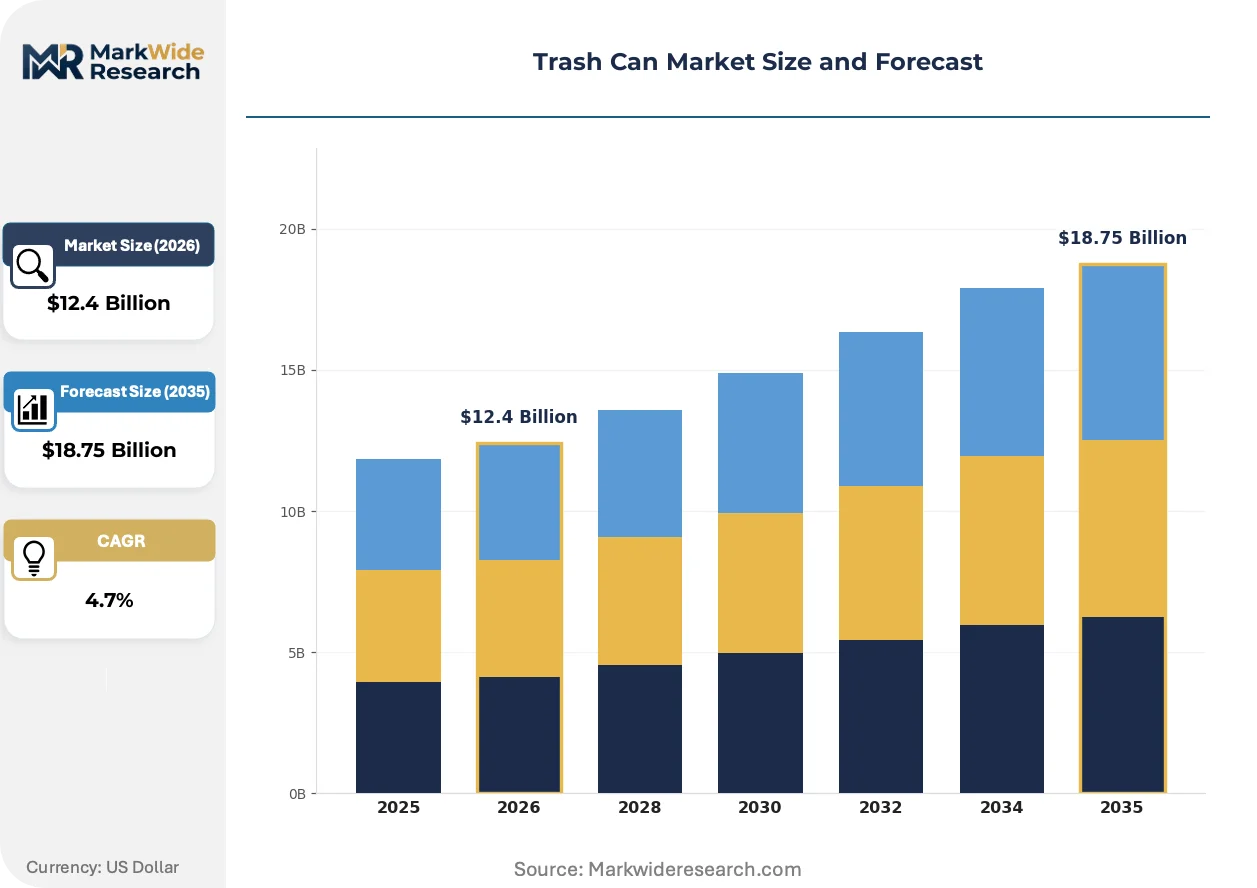
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Household, Commercial, Industrial, Outdoor Material: Plastic, Metal, Wood, Stainless Steel Feature: Motion Sensor, Foot Pedal, Recycling, Compactor End User: Residential, Hospitality, Healthcare, Educational |
| Companies Covered | Ninestars, ARONKASEI, Simplehuman, ZKH, Richell, iTouchless, Sterilite, Joseph Joseph, Rubbermaid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trash Can Market Emerging Trajectories
Active materials and connectivity layers are redefining the trash can from passive container to data-generating node, compressing the boundary between hardware procurement and facilities software.
Photovoltaic-integrated sensor housings are electrifying the power architecture of outdoor public bins, eliminating battery replacement labor for municipal operators. German cities including Hamburg and Munich pilot solar-augmented units in pedestrian zones with limited grid access. The technology is electrifying vendor R&D roadmaps toward energy-autonomous product platforms that reduce total cost of ownership across decade-long deployment cycles.
EPA waste characterization standards are tightening material traceability requirements for containers procured under federal environmental justice grants. Municipal buyers must now document recycled content percentages and end-of-life recyclability pathways. Commercial-grade plastic SKUs face the steepest compliance burden, driving specification shifts toward stamped steel alternatives with established scrap recovery infrastructure.
Buying committees in healthcare and hospitality verticals now unbundle after-sales service from initial hardware procurement, awarding multi-year sensor calibration and liner replenishment contracts to specialized third-party operators. Traditional manufacturers face margin compression as facility management conglomerates capture recurring revenue streams. The United States exhibits the most advanced unbundling, with hospital systems in Texas and Florida leading contract restructuring toward outcome-based waste diversion metrics.
Trash Can Market Segmentation
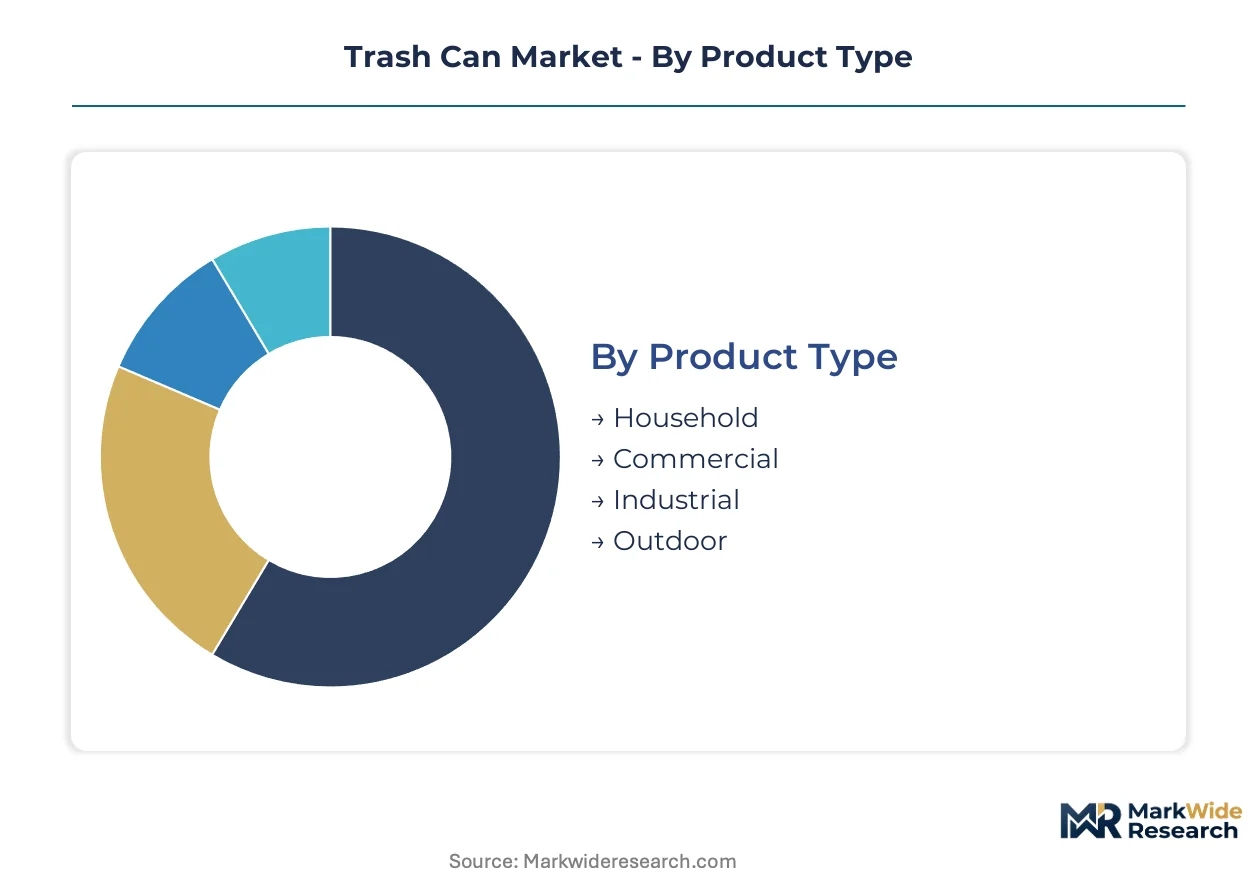
Trash can procurement decisions diverge sharply across use environments, with material specifications and feature sets calibrated to hygiene protocols, durability demands, and regulatory compliance. Understanding segment boundaries clarifies where margin pools concentrate versus where volume scales.
Product Type:
Application environment dictates capacity requirements, mobility features, and replacement cadence.
- Household:Residential units prioritize aesthetic integration with kitchen cabinetry and odor-sealing lid mechanisms. Urban households in Germany and South Korea drive specification toward slim-profile designs for high-density apartments.
- Commercial:Office and retail deployments emphasize standardized dimensions for uniform placement and color-coded streams for recycling compliance. Corporate facilities managers in the United States negotiate multi-year service bundles covering hardware, liners, and sensor maintenance.
- Industrial:Heavy-gauge steel construction withstands forklift impact and chemical exposure in manufacturing floors. Roll-out configurations dominate warehousing and logistics hubs requiring frequent repositioning.
- Outdoor:Weather-resistant housings with vandal-proof fastenings serve municipal pedestrian zones and parks. Hamburg and Munich pilot solar-augmented sensor units in grid-limited locations.
Commercial leads on scale; Outdoor leads on momentum.
Material:
Input cost volatility and end-of-life recyclability shape sourcing strategies across price tiers.
- Plastic:Injection-molded polypropylene and rotationally molded HDPE deliver lowest unit costs for high-volume commercial procurement. EPA waste characterization standards now mandate recycled content documentation for federal environmental justice grant recipients.
- Metal:Stamped steel alternatives benefit from established scrap recovery infrastructure as traceability requirements tighten. REACH restrictions on hexavalent chromium in surface coatings force reformulation of legacy finishes.
- Wood:Limited to premium residential and hospitality segments where natural aesthetic commands price premiums. Moisture resistance treatments limit deployment in high-humidity environments.
- Stainless Steel:Nickel and chromium alloy grades define the premium residential tier with durability expectations exceeding fifteen years. Nickel price swings compress margin stability for manufacturers dependent on aesthetic metal finishes.
Plastic dominates unit volume; Stainless Steel captures value concentration.
Feature:
Technology integration separates commodity containers from service-enabled platforms.
- Motion Sensor:Ultrasonic and infrared modules enable touchless operation for healthcare and hospitality hygiene protocols. LiDAR component supply clusters in Taiwan and South Korea create production schedule vulnerability.
- Foot Pedal:Mechanical lift mechanisms offer reliable hands-free operation without battery dependency. Cost-conscious commercial buyers favor this configuration where sensor maintenance infrastructure is absent.
- Recycling:Multi-stream internal compartments support source-segregation mandates under EU Green Deal directives. German cities mandate smart bin deployment for commercial district compliance.
- Compactor:Motorized compression reduces collection frequency for high-volume waste generators. Hospital systems in Texas and Florida specify compactor units for operating theater waste streams.
Motion Sensor expands most quickly; Foot Pedal retains cost-sensitive share.
End User:
Procurement authority and compliance burden vary dramatically across institutional structures.
- Residential:Direct-to-consumer channels enable subscription liner attachment and upgradeable sensor module sales. Simplehuman leverages precision-fit consumables to sustain margin control outside wholesale.
- Hospitality:Hotel chains standardize on motion-sensor configurations to signal hygiene commitment to guests. Brand consistency requirements favor single-source national contracts.
- Healthcare:Infection control protocols drive touchless specification and dedicated medical waste stream isolation. Facilities managers unbundle after-sales service from initial hardware procurement.
- Educational:K-12 and university procurement operates through centralized district contracts with extended payment terms. Budget constraints favor plastic commercial-grade SKUs over premium metal alternatives.
Residential anchors volume; Healthcare commands specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale waste container manufacturing first scaled in post-war Germany and the United States, where municipal sanitation modernization created sustained demand for standardized receptacles. Those two markets remain reference points for procurement specifications worldwide.
Germany
Municipal mandates in Hamburg and Munich require smart bin deployment across commercial districts, driving sensor-equipped procurement volumes. REACH restrictions on hexavalent chromium in metal coatings force surface treatment reformulation for legacy commercial-grade finishes. Bavaria's precision metalworking clusters supply stamped steel housings to premium residential product lines.
United States
EPA waste characterization standards tighten material traceability for containers procured under federal environmental justice grants. Healthcare systems in Texas and Florida unbundle after-sales service contracts toward outcome-based waste diversion metrics. The Southeast's logistics hubs concentrate industrial roll-out container demand from warehousing operators.
China
Smart Cities Mission funding in tier-1 and tier-2 municipalities creates procurement windows for sensor-equipped public waste infrastructure. GB standards for municipal sanitation equipment shape domestic manufacturing specifications. Yangtze River Delta fabricators dominate injection-molded polypropylene output for commercial-grade volume production.
South Korea
Urban centers deploy fill-level sensors and route-optimization software to reduce collection fleet operating costs. MFDS-equivalent municipal technology standards accelerate touchless hygiene protocol adoption in hospitality and healthcare facilities. Seoul Capital Area concentration drives premium residential demand for slim-profile designs in high-density apartments.
India
Smart Cities Mission funding creates procurement windows for sensor-equipped public waste infrastructure in tier-1 and tier-2 municipalities. BIS standards for municipal sanitation equipment shape domestic manufacturing specifications. Maharashtra's industrial corridors concentrate commercial-grade plastic SKU production for educational and institutional contracts.
Trash Can Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material sophistication and sensor integration depth. The vendor base organizes into three tiers: stainless steel specialists commanding aesthetic premiums, scale manufacturers of standardized commercial containers, and sensor-technology integrators competing on hygiene protocol compliance. Strategic moves concentrate on backward integration into precision-fit consumables and geographic expansion through municipal procurement frameworks.
Within the premium residential tier, Simplehuman exemplifies margin control through in-house production of precision-fit liners across direct-to-consumer channels. Rubbermaid anchors the scale-driven institutional segment through standardized commercial-grade container manufacturing. iTouchless occupies a position within the sensor-technology vector, competing on motion-sensor reliability for hospitality and healthcare contract eligibility. ZKH represents Chinese manufacturing scale in commercial-grade volume production.
| Leading Market Players |
|---|
| Ninestars |
| ARONKASEI |
| Simplehuman |
| ZKH |
| Richell |
| iTouchless |
| Sterilite |
| Joseph Joseph |
| Rubbermaid |
| Others |
Supply Flow & Price Mechanics
Sensor-battery modularization is compressing replacement cycles while simultaneously redistributing margin pools toward software-enabled service contracts, forcing manufacturers to recalibrate cost structures around upgradeable platforms rather than disposable hardware economics. This production-method transition concentrates pricing power among vendors with captive liner supply and firmware development capabilities while squeezing commodity producers dependent on unit turnover velocity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates stainless steel residential specialists from injection-molded commercial volume players and unbranded economy imports. Price differentiation hinges on ISO 9001 certification status and precision-fit consumable bundling. Cost compression in the premium tier is intensifying as nickel price volatility erodes margin stability for aesthetic metal finishes. Educational procurement committees exhibit highest price sensitivity; healthcare facilities managers show lowest sensitivity due to infection-control specification mandates.
Supply Chain Analysis
LiDAR and ultrasonic module supply rests on Taiwanese and South Korean specialty electronics producers, creating single-source vulnerability for motion-enabled SKU production schedules. Stamped steel feedstock draws from Bavarian precision metalworking clusters and Yangtze River Delta fabricators, while injection-molded polypropylene hinges on petrochemical complexes in the US Gulf Coast and Northeast Asia. Distribution runs through institutional procurement frameworks, direct-to-consumer channels, and big-box retail with diverging margin structures. Tariff exposure on Chinese-manufactured commercial-grade containers creates procurement uncertainty for US municipal buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trash can market functions as a stable compounder underpinned by extended producer responsibility mandates that lock in replacement demand across decade-long municipal contract cycles.
For Market Incumbents: Anchor market position through backward integration into precision-fit liner production and sensor firmware development, defending against margin erosion from facilities management conglomerates capturing recurring service revenue. Incumbents should prioritize ISO 9001 certification maintenance and REACH-compliant surface treatment reformulation to preserve EU municipal procurement eligibility. For New Entrants and Emerging Players: Photovoltaic-integrated sensor housings offer a technology-first wedge into outdoor public infrastructure segments where energy-autonomous operation commands specification premiums. Target India's tier-2 municipalities under Smart Cities Mission funding, where sensor-equipped deployment lags tier-1 saturation. Pursue white-label manufacturing partnerships with Yangtze River Delta fabricators to bypass capital-intensive scale requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among commercial-grade plastic manufacturers facing EPA recycled-content documentation burdens and margin compression from stainless steel substitution. Long-term viability favors vendors with software-enabled service contract attachment and municipal procurement framework access. Watch ECHA substance restriction expansion as inflection indicator for reformulation cost shocks and competitive displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liner Production | Captive supply of precision-fit consumables sustains margin control outside wholesale channels. |
| Sensor Firmware Platform Development | Software-enabled service contracts decouple revenue growth from hardware replacement velocity. |
| REACH-Compliant Surface Treatment Reformulation | ECHA hexavalent chromium restrictions force coating chemistry shifts for EU market access. |
| Photovoltaic Sensor Housing Integration | Solar-augmented units eliminate battery replacement labor for municipal operators in Hamburg and Munich. |
| Smart Cities Mission Partnership Structuring | India tier-1 and tier-2 procurement windows create geographic expansion pathways for sensor-equipped infrastructure. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal procurement officers, facilities management executives, commercial-grade container plant managers, and sensor technology integrators with secondary validation against EPA waste characterization standards, ECHA REACH substance restriction databases, EU Green Deal directive texts, and municipal sanitation equipment procurement records. Bottom-up SKU-level volume builds triangulated against top-down macroeconomic demand drivers.
Segment-weighting across product type, material grade, feature configuration, and end-user vertical shaped analytical framework construction throughout the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking procurement pipeline assessment, with specific inputs including stainless steel alloy price indices, LiDAR component supply lead times, and municipal smart infrastructure budget allocations.
The model holds under stable regulatory enforcement of extended producer responsibility frameworks; deviation in ECHA substance restriction scope or nickel price volatility extremes would shift volume and value trajectories. A small set of named triggers warrants ongoing watch: REACH reformulation cost pass-through, Taiwan sensor module supply disruption, and India Smart Cities Mission funding continuity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
US Soap Dispenser Market
Household Items
Global Nap Pod Market
Household Items
Insulated Tumblers Market
Household Items
Titanium Thermos Cup Market
Household Items
Water Purifier Market
Household Items
Wet Wipes and Toilet Paper Market
Household Items
India Air Purifier Market
Household Items
Plastic Bathtub Market
Household Items
Shower Heads and Systems Market
Household Items
Crash Mat Market
Household Items
Washing Machine Cleaner Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Snow Blower Market
Household Items
Command Hooks Market
Household Items
Electric Mop Market
Household Items
China Digital Showers Market