
 Luxury Massage Chair Market | 2026-2036
Luxury Massage Chair Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Massage Chair Market Outlook
The gap between clinical-grade massage robotics and consumer-accessible engineering is narrowing as 4D roller mechanisms and body-scanning sensors migrate into residential-grade chassis. Bodyfriend Co. Ltd. leverages its Seoul-based R&D campus to sustain proprietary motor-drive architectures, while OSIM International Pte Ltd anchors premium positioning across Southeast Asian mall retail networks. Panasonic Corporation competes through backward integration into its own sensor foundries, reducing component dependency on external suppliers.
A luxury massage chair is an electromechanical recliner integrating motorized roller tracks, air-cell compression arrays, and microprocessor-controlled body-mapping algorithms to deliver programmable therapeutic pressure sequences. Units typically incorporate SL-track or L-track rail systems spanning 120–145 cm to enable full posterior coverage from cervical to gluteal regions. Zero Gravity configurations command the dominant margin pool by redistributing user mass to reduce spinal loading, while Air Compression technology represents the fastest-expanding functional category as circulatory therapy applications broaden. The Residential end-user segment leads absolute volume, though Spa and Chiropractic Clinic channels extract higher per-unit service-attach revenue through subscription-based maintenance and software upgrade cycles.
The US Consumer Product Safety Commission and FCC govern electrical safety and wireless connectivity compliance for connected massage chair models, while the EU's CE marking and RoHS substance restrictions constrain material selection for European-bound production. Japan's Ministry of Economy, Trade and Industry (METI) and Electrical Appliance and Material Safety Law impose additional certification layers that filter lower-capability entrants from the premium tier. Stakeholders must monitor how evolving right-to-repair legislation across multiple jurisdictions reshapes warranty structures and aftermarket parts economics.
Market Dynamics
The EU's Ecodesign Directive is compressing motor-system efficiency requirements across luxury massage chair manufacturing, forcing simultaneous redesigns of roller-drive architectures and power-management subsystems while aging demographics in Japan and South Korea sustain premium-tier demand concentration.
Growth Catalysts
- Residential wellness-suite expansion:High-net-worth households are integrating therapeutic seating into dedicated home spa environments, pulling 4D roller mechanisms and body-scanning sensors into domestic installations.
- CE marking convergence:The EU's appliance energy-labeling framework is accelerating cross-border standardization, enabling single-SKU certification strategies for manufacturers targeting multiple European markets.
- SL-track rail adoption:Extended 135–145 cm posterior coverage systems are displacing shorter L-track configurations in premium residential segments, enabling full cervical-to-gluteal therapeutic sequences.
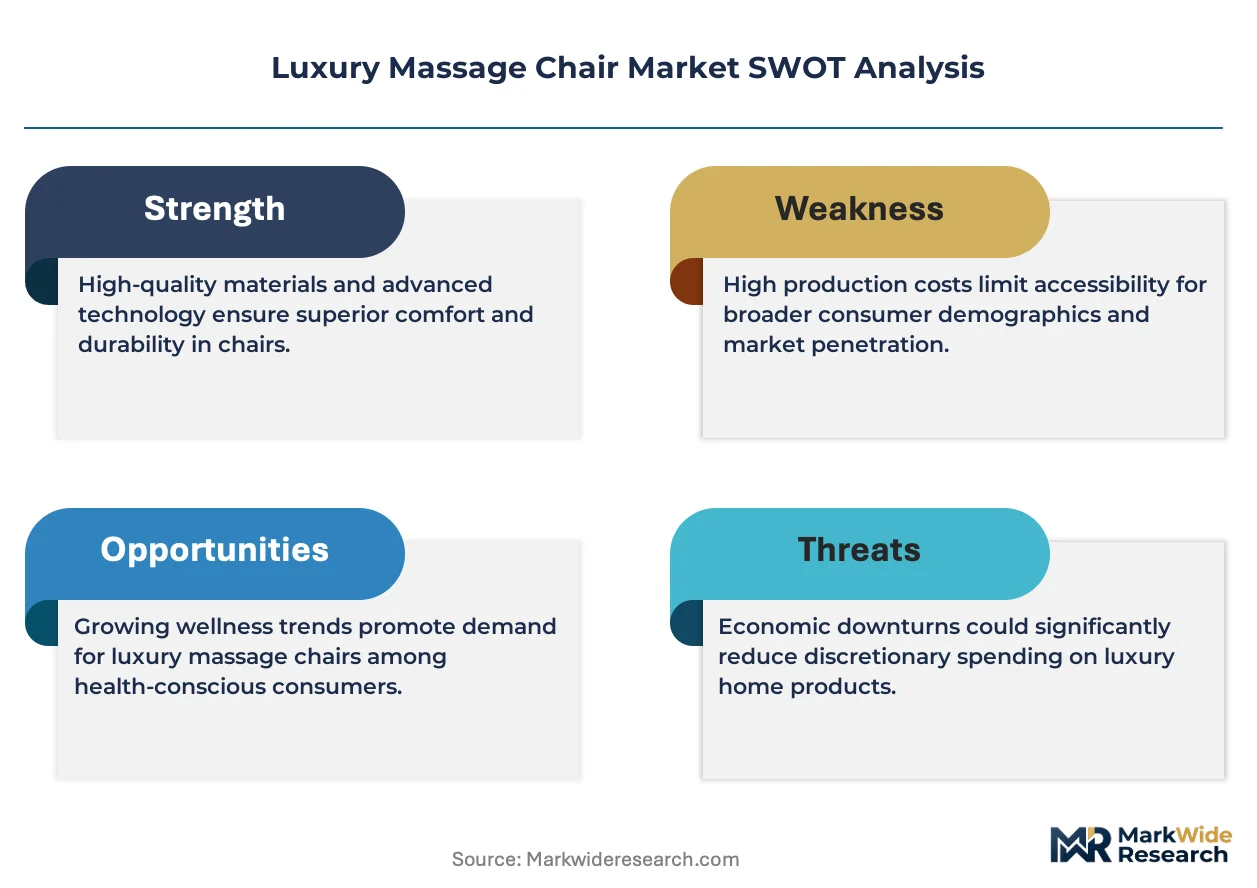
Market Restraints
- Rare-earth magnet dependency:Neodymium price volatility in Chinese processing facilities is compressing margin stability for precision motor-drive suppliers concentrated in East Asian manufacturing clusters.
- RoHS substance restrictions:The EU's hazardous substance limits on lead and cadmium are constraining solder and coating selections, extending material qualification timelines for European-bound production.
- Clinical-grade substitution:Professional physiotherapy equipment and manual therapy services retain preference among severe musculoskeletal condition patients, capping penetration in medical-adjacent buyer segments.
Strategic Opportunities
- Subscription software monetization:Spa and chiropractic clinic channels are unbundling maintenance contracts and firmware upgrade cycles from hardware sales, creating recurring revenue attachment models.
- Right-to-repair tailwinds:Emerging EU and US state-level repair-access legislation is mandating spare parts availability, opening aftermarket component supply opportunities for independent service networks.
- Air compression therapy expansion:Circulatory and lymphatic applications are broadening beyond traditional roller-based massage, enabling entry into sports recovery and post-surgical rehabilitation verticals.
Industry Challenges
- Multi-jurisdiction certification complexity:Simultaneous FCC, CE, and METI compliance requirements are stretching engineering validation resources, particularly for connected models with wireless connectivity subsystems.
- Embedded sensor integration:Body-mapping algorithm development requires scarce expertise in pressure-transducer calibration and real-time biomechanical feedback processing, constraining R&D velocity for mid-tier entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Massage Chair Market |
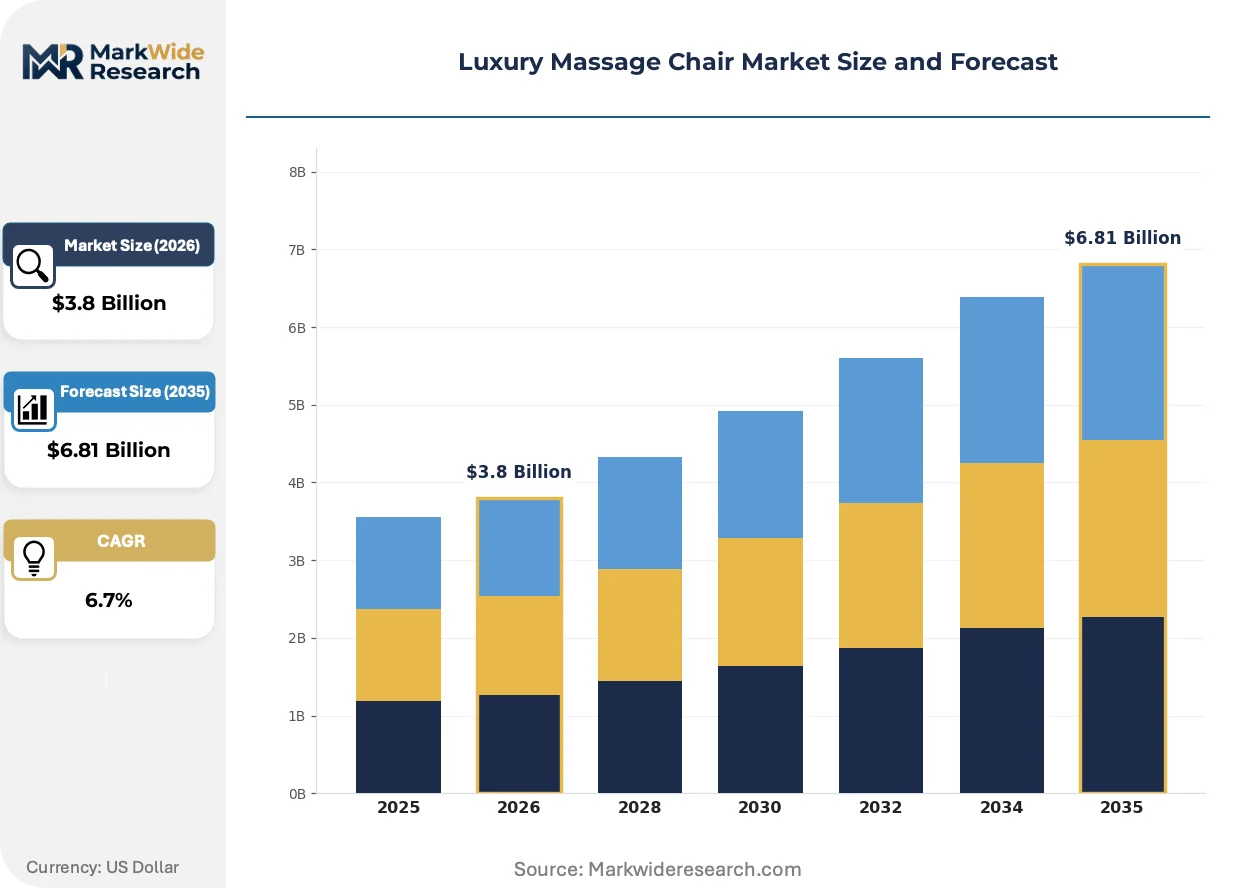
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zero Gravity, Recliner, Portable, Full-Body Technology: Shiatsu, Swedish, Reflexology, Air Compression End User: Residential, Spa, Gym, Chiropractic Clinic Service Type: Personal Use, Commercial Use, Rental, Subscription |
| Companies Covered | Infinity Massage Chairs, Bodyfriend Co. Ltd., OSIM International Pte Ltd, Ogawa World USA, Luraco Technologies Inc., Panasonic Corporation, Cozzia USA, Fujiiryoki Co. Ltd., Human Touch LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Massage Chair Market Strategic Shifts
Electromechanical convergence between automotive-grade sensor manufacturing and therapeutic seating is compressing development cycles, while regulatory pressure on energy consumption and material composition is reshaping supply chain sourcing priorities.
4D roller mechanisms with variable-depth penetration control are rendering obsolete fixed-track massage systems that cannot adjust pressure vectors to individual spinal curvature. Premium residential buyers in Japan and South Korea are specifying these adaptive systems in 80% of new wellness-suite installations. The technology is rendering obsolete the two-year replacement cycles typical of earlier mechanical generations.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of polyurethane foam cushioning and synthetic leather coverings across European-bound production. Manufacturers are responding with bio-based alternatives and accelerated chemical inventory disclosure protocols. The Spa and Chiropractic Clinic channel faces the steepest compliance cost absorption due to higher upholstery surface-area requirements.
Direct-to-consumer configuration tools are displacing traditional mall-retail trial experiences as the primary purchase decision pathway. Residential buyers in Seoul, Tokyo, and Singapore are specifying chassis dimensions, upholstery grades, and therapy programs through web-based interfaces before warehouse fulfillment. This channel compression is most visible in Southeast Asian markets where OSIM and Bodyfriend have consolidated premium retail footprints.
Luxury Massage Chair Market Segmentation
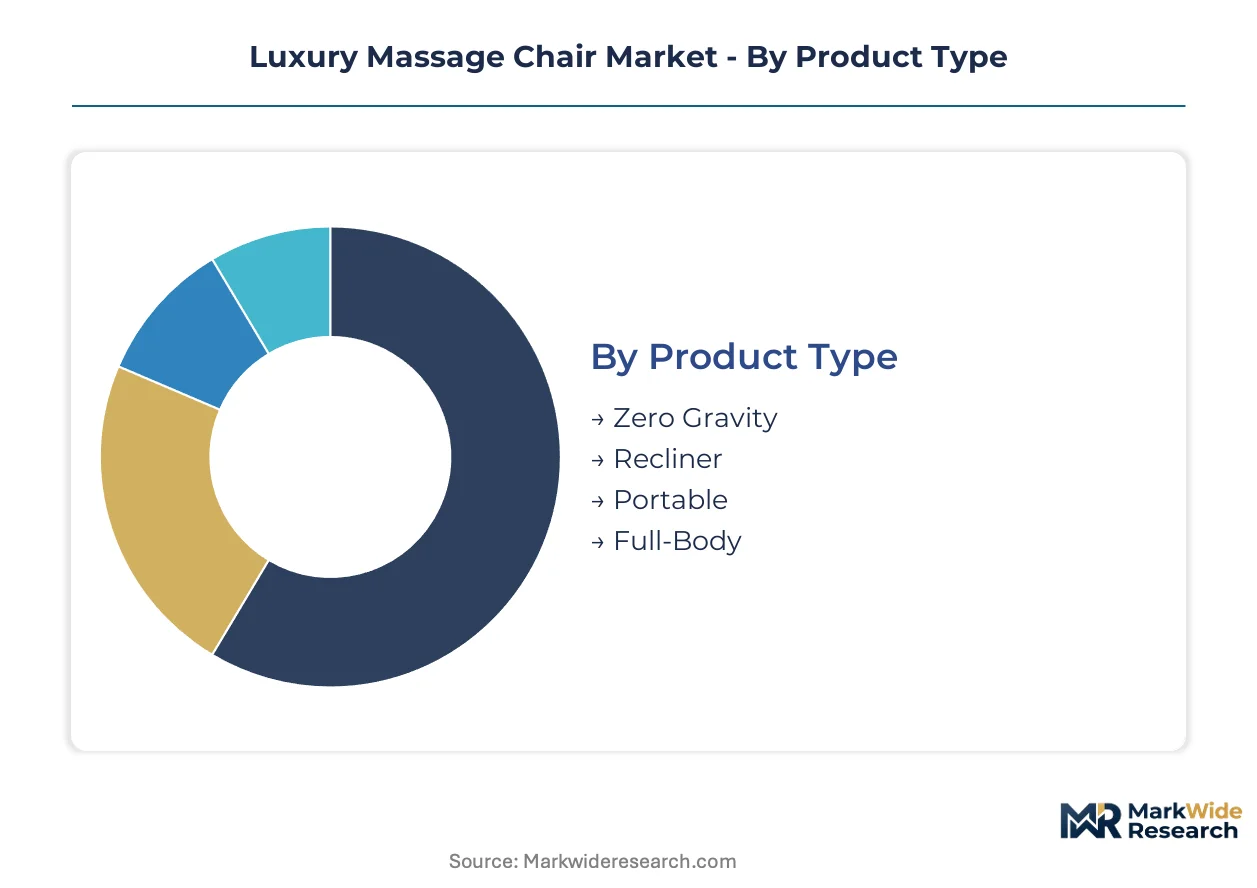
Segmentation in the luxury massage chair market reveals how after-sales intensity varies dramatically across installation contexts. Warranty structures, firmware upgrade cycles, and preventive maintenance contracts differ fundamentally between residential units and high-utilization commercial deployments.
Product Type:
After-sales-service intensity escalates with structural complexity and motorized component count, creating divergent service revenue profiles across chassis architectures.
- Zero Gravity:Multi-motor tilt mechanisms redistribute user mass across 126-degree recline angles to reduce lumbar compression. Residential wellness suites in Japan and South Korea specify these configurations in premium installations where extended warranty packages drive recurring service attachment. By volume, Zero Gravity leads. By growth pace, Portable is ahead.
- Recliner:Fixed-base chassis with motorized backrest and footrest articulation dominate entry-premium price bands. Demand concentrates in US suburban households where furniture-retail channels bundle white-glove delivery with assembly services.
- Portable:Collapsible frame systems with detachable massage nodes target space-constrained urban apartments. Southeast Asian markets in Singapore and Bangkok show strongest uptake among rental-property managers furnishing serviced residences.
- Full-Body:Integrated SL-track rail systems spanning cervical through gluteal regions command the highest service-contract attachment rates due to sensor calibration requirements.
Margin structures favor complex chassis configurations where preventive maintenance contracts extend customer lifetime value beyond hardware margins.
Technology:
Sensor density and algorithm sophistication determine firmware upgrade frequency and technical support escalation patterns across therapeutic modalities.
- Air Compression:Pneumatic cell arrays deliver circulatory therapy through sequential inflation patterns controlled by pressure-transducer feedback. Sports recovery centers in Germany and post-surgical rehabilitation clinics in Switzerland are expanding specifications for lymphatic drainage protocols. Air Compression is gaining share fastest among technology categories.
- Shiatsu:3D and 4D roller mechanisms with variable-depth penetration replicate thumb-and-palm pressure techniques. Japanese residential buyers specify these systems in 80% of new wellness-suite installations where cultural familiarity with traditional massage sustains premium positioning.
- Swedish:Longitudinal gliding roller patterns with heat-therapy integration target muscle relaxation applications in Scandinavian spa environments.
- Reflexology:Dedicated footwell compression and roller systems address plantar pressure points, attracting podiatric clinic procurement in South Korea.
Algorithm-dependent modalities generate sustained software monetization opportunities through subscription therapy program libraries.
End User:
Utilization intensity and regulatory exposure shape service contract structures and certification requirements across installation environments.
- Spa:High-cycle commercial deployments exceeding 12 hours daily operation require quarterly preventive maintenance and rapid-response technician networks. The EU's Ecodesign Directive energy-labeling compliance adds documentation burden for European wellness center operators.
- Chiropractic Clinic:Clinical-adjacent positioning demands METI certification in Japan and FDA facility registration in the US, filtering lower-capability suppliers from this channel.
- Residential:Moderate-utilization environments with 2-4 hours weekly average use enable extended warranty structures and self-service firmware updates.
- Gym:High-traffic fitness center installations prioritize durability specifications and vandal-resistant upholstery over therapeutic sophistication.
Commercial channels extract 3-4x higher lifetime service revenue per unit despite lower absolute shipment volumes.
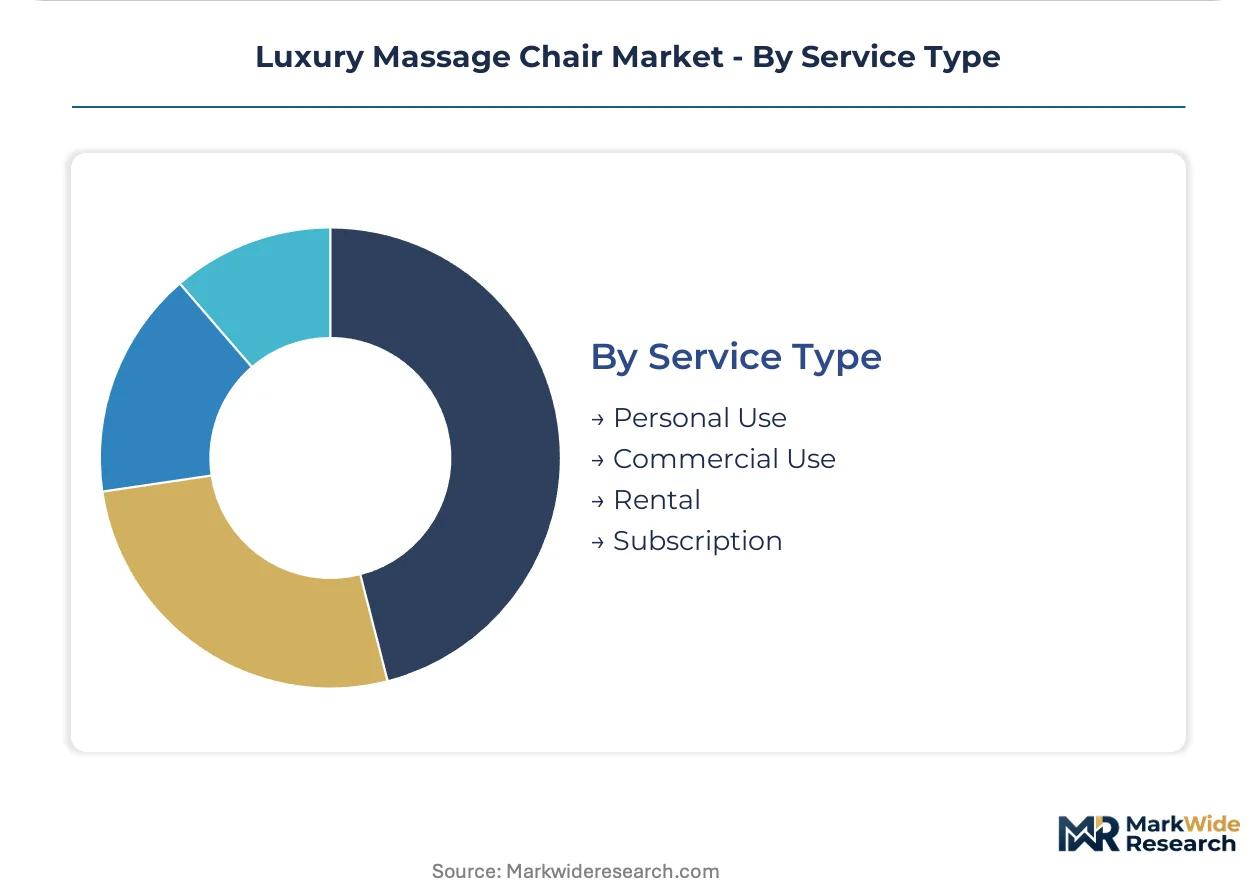
Service Type:
Ownership models determine capital deployment patterns and recurring revenue recognition timing across customer relationships.
- Subscription:Bundled hardware-software-service contracts with monthly recurring charges are displacing outright purchase in Japanese corporate wellness programs and US luxury apartment amenity packages.
- Rental:Short-term deployment models for event hospitality and temporary rehabilitation needs concentrate in Dubai and Singapore where seasonal demand fluctuation supports asset-light operating structures.
- Commercial Use:Depreciation-schedule ownership with full maintenance inclusion dominates European spa and clinic procurement through operating lease structures.
- Personal Use:Traditional outright purchase with optional extended warranty remains the dominant transaction structure in North American residential channels.
Recurring-revenue models are climbing the fastest among service type configurations as hardware commoditization pressures margin structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-net-worth residential buyers cluster in aging, affluent economies where home wellness infrastructure commands premium allocation. Japan's demographic profile and cultural massage familiarity sustain the densest per-capita penetration. Regulatory energy-efficiency mandates in the EU and electrical safety layers in East Asia filter market access by technical capability.
Japan
Aging demographics and cultural familiarity with therapeutic massage sustain premium-tier demand concentration unmatched elsewhere. METI certification requirements under the Electrical Appliance and Material Safety Law impose additional compliance layers that screen lower-capability entrants. Tokyo and Osaka metropolitan areas host the densest residential wellness-suite installations, with corporate wellness programs in the Kanto region expanding subscription-based deployment models.
United States
Suburban high-net-worth households drive furniture-retail channel bundling with white-glove delivery services. The Consumer Product Safety Commission and FCC govern electrical safety and wireless connectivity for connected models. California and Texas metropolitan clusters concentrate residential installations, while Florida's retirement communities sustain above-average replacement cycles for therapeutic seating.
Germany
Sports recovery centers and post-surgical rehabilitation clinics expand specifications for lymphatic drainage protocols through air compression systems. The EU's Ecodesign Directive and REACH substance restrictions constrain material selection and motor-system efficiency requirements. Bavaria and Baden-Württemberg industrial clusters concentrate precision motor-drive supplier engineering resources.
South Korea
Corporate wellness programs and luxury apartment amenity packages accelerate subscription-based ownership models displacing outright purchase. MFDS regulatory frameworks for medical-adjacent positioning filter clinical-channel entrants. Seoul's Gangnam and Songdo districts concentrate flagship retail footprints and R&D campuses developing proprietary motor-drive architectures.
Singapore
Space-constrained urban apartments and serviced residence property managers drive portable and collapsible frame system uptake. Mall-retail trial experiences remain significant in Southeast Asian purchase pathways despite direct-to-consumer channel compression. The city-state functions as regional logistics hub for Southeast Asian distribution networks targeting Bangkok and Kuala Lumpur secondary markets.
Luxury Massage Chair Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent go-to-market architectures. The vendor base organizes around three strategic archetypes: vertically integrated electronics conglomerates with captive sensor production, dedicated wellness equipment specialists with retail network control, and contract manufacturers serving private-label distributors. Consolidation pressure concentrates in the premium tier where firmware monetization and service-attach economics determine lifetime customer value. Geographic expansion and technology licensing represent the dominant competitive moves as regulatory compliance costs escalate.
Among East Asian fabricators, Bodyfriend Co. Ltd. and OSIM International Pte Ltd occupy positions anchored by regional retail network density and proprietary R&D infrastructure. Panasonic Corporation exemplifies the electronics conglomerate archetype through backward integration into sensor component production. These three entities represent contrasting strategic postures: dedicated wellness specialization against diversified industrial scale against hybrid retail-manufacturing integration.
| Leading Market Players |
|---|
| Infinity Massage Chairs |
| Bodyfriend Co. Ltd. |
| OSIM International Pte Ltd |
| Ogawa World USA |
| Luraco Technologies Inc. |
| Panasonic Corporation |
| Cozzia USA |
| Fujiiryoki Co. Ltd. |
| Human Touch LLC |
| Others |
Value Chain & Pricing Dynamics
Chinese neodymium processing facilities anchor motor-drive component sourcing for precision roller systems, concentrating margin capture with East Asian fabricators who command premium pricing on 4D mechanism assemblies. This upstream concentration funnels pricing power downstream toward manufacturers with captive sensor production and proprietary firmware architectures, while buyers in European and North American channels absorb elevated landed costs through extended warranty bundling.
Pricing Analysis
Cost-plus contracts with neodymium price indexation dominate component procurement for precision motor assemblies, exposing finished-goods pricing to rare-earth commodity volatility. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified clinical-grade chassis from residential wellness-suite configurations and entry-premium recliner formats. Pricing pressure stems from EU Ecodesign Directive compliance costs forcing simultaneous motor-system redesigns. Spa and chiropractic clinic channels exhibit lowest price sensitivity due to service-attach revenue offsetting hardware margins, while portable segment buyers in Southeast Asian urban markets demonstrate highest elasticity.
Supply Chain Analysis
Export-control restrictions on advanced pressure-transducer technology limit sensor component flows from Japanese and South Korean foundries to non-allied manufacturing jurisdictions. Component sourcing concentrates in China for rare-earth magnet processing, South Korea for motor-drive assembly, and Japan for sensor calibration equipment. Supply chains draw from neodymium, polyurethane foam cushioning, and synthetic leather upholstery as critical inputs. Single-source vulnerability in Chinese rare-earth refining creates structural exposure. Distribution runs through mall-retail networks in Southeast Asia, direct-to-consumer configuration platforms in East Asian metropolitan markets, and furniture-retail channel bundling in North American suburban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Luxury massage chair penetration remains in early-cycle expansion as residential wellness-suite adoption accelerates among high-net-worth households integrating therapeutic seating into dedicated home spa environments.
For Market Incumbents: Harden firmware monetization architectures against subscription-service competitors by unbundling preventive maintenance contracts and therapy program libraries from hardware sales. Deepen backward integration into sensor component production to reduce dependency on external transducer suppliers facing export-control constraints. Prioritize METI certification maintenance as regulatory layers filter lower-capability entrants from clinical-adjacent procurement channels. For New Entrants and Emerging Players: Pursue portable and collapsible frame system specifications targeting space-constrained urban apartments in Singapore, Bangkok, and Kuala Lumpur where rental-property managers furnish serviced residences. Air compression technology for sports recovery and post-surgical rehabilitation applications offers the most penetrable white-space vertical beyond traditional roller-based massage. Deploy direct-to-consumer configuration tools displacing mall-retail trial experiences as primary purchase decision pathway. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wellness equipment specialists consolidating regional retail network density without captive R&D infrastructure. Five-to-ten year viability hinges on algorithm-dependent therapy program libraries generating recurring software revenue attachment. Monitor right-to-repair legislation progression across EU member states and US jurisdictions as inflection indicator for aftermarket parts supply economics and warranty structure disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Foundry Backward Integration | Panasonic's captive transducer production reduces component dependency and accelerates body-mapping algorithm development cycles. |
| Subscription Service Unbundling | Spa channels extract recurring revenue through firmware upgrade cycles and preventive maintenance contracts beyond hardware margins. |
| Direct-to-Consumer Platform Launch | Seoul and Tokyo metropolitan buyers now specify chassis dimensions and upholstery grades through web-based configuration interfaces. |
| Air Compression Therapy Expansion | German sports recovery centers and Swiss rehabilitation clinics broaden specifications for lymphatic drainage protocols. |
| Right-to-Repair Compliance Investment | Emerging EU and US state-level legislation mandates spare parts availability for independent service network participation. |
Study Parameters
A standing panel of massage equipment R&D directors, spa operations managers, chiropractic clinic procurement leads, and furniture-retail channel buyers provided ongoing calibration across primary interview cycles. Secondary validation drew from METI certification databases, EU Ecodesign Directive compliance filings, SEC 10-K disclosures by listed wellness equipment manufacturers, and customs trade records for neodymium and precision motor component flows. Bottom-up shipment tallies by product configuration and technology tier triangulated against top-down spending estimates by end-user segment and regional market.
Scenario-bracketing around regulatory compliance cost trajectories and rare-earth price volatility bounds anchored projection modeling across the analysis window. Segmentation dimensions spanned product architecture complexity, therapeutic modality algorithm dependency, end-user utilization intensity, and service-type ownership structure. CAGRs derived from fitted growth curves incorporating aging demographic penetration rates, residential wellness-suite installation trends, and commercial channel service-attach economics. Industry-specific inputs included sensor calibration frequency requirements, upholstery surface-area compliance costs under REACH, and firmware upgrade cycle monetization patterns.
Sensitivities concentrate around neodymium price volatility, right-to-repair legislative progression, and clinical-grade substitution by professional physiotherapy equipment. Forecasts reflect documented assumptions on regulatory implementation timelines and technology adoption curves. Material shifts in EU Ecodesign Directive enforcement stringency or METI certification requirement expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Bottle Openers Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Insulated Lunch Box Market
Household Items
India POU Water Purifiers Market
Household Items
Electric Clothes Drying Hanger Market
Household Items
Japan Cookware Market
Household Items
Domestic Sauna Heaters Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
Non-Stick Cookware Market
Household Items
Toilet Paper Market
Household Items
Sanitary Metal Ware Market
Household Items
Robotic Vacuum Cleaner Market
Household Items
Europe Handheld Fans Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Coffin and Cremation Urn Market