
 Organic Sanitary Napkin Market | 2026-2036
Organic Sanitary Napkin Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Sanitary Napkin Market Analytics
Specialty shops and health stores is tilting toward direct-to-consumer subscription models as digital-first brands capture repeat purchases. Rael Inc. leverages Korean manufacturing partnerships to sustain premium positioning across Asian and North American markets. Natracare anchors European distribution through pharmacy chains and zero-waste retail cooperatives. Corman SpA differentiates via Italian-made organic cotton sourcing and medical-grade certification standards.
Organic sanitary napkins comprise absorbent hygiene products constructed from certified organic cotton, plant-based bioplastics, and chlorine-free wood pulp without synthetic fragrances or petrochemical-based superabsorbent polymers. These products serve menstruating individuals seeking reduced chemical exposure and minimized environmental impact from disposable hygiene waste. The organic cotton segment leads absolute volume due to established agricultural supply chains and consumer familiarity with natural fiber claims. Chlorine-free processing commands margin premiums as manufacturers highlight dioxin elimination and reduced waterway contamination. Biodegradable backsheet films represent the fastest-growing technical subcategory as composting infrastructure expands in urban municipalities.
FDA oversight of feminine hygiene products as medical devices shapes labeling requirements and adverse event reporting obligations for US market participants. ECHA REACH compliance and EU MDR traceability mandates drive reformulation investments among European suppliers while India's BIS certification and FSSAI-adjacent quality benchmarks create formal market entry barriers. Stakeholders must monitor evolving state-level extended producer responsibility laws and compostability certification schemes that will determine which material platforms achieve scalable retail placement.
Market Dynamics
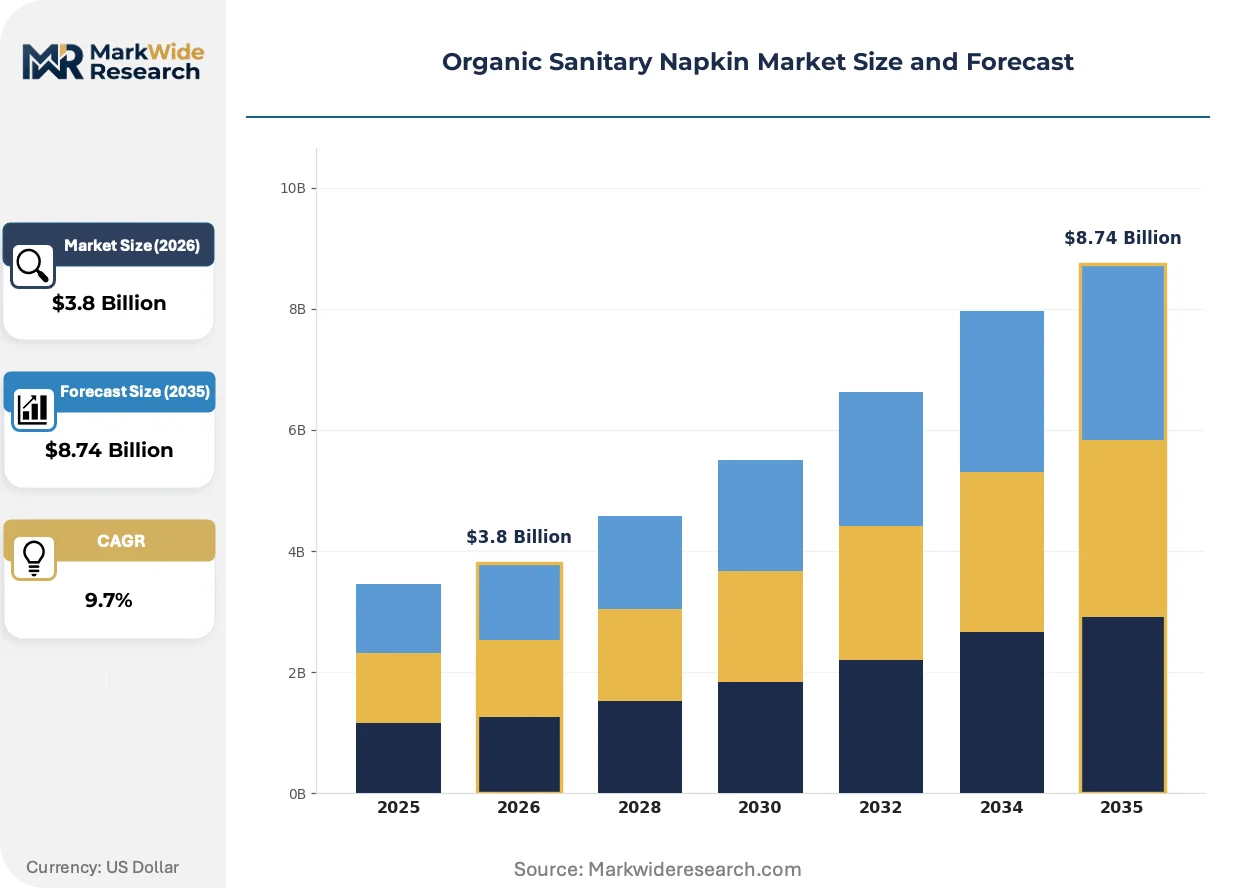
The organic sanitary napkin market is reconfiguring around composting infrastructure buildouts in urban municipalities, which determines which material platforms achieve scalable retail placement and which biodegradable backsheet films capture volume premiums.
Growth Catalysts
- EPA and FDA safety standards:Stricter federal oversight of feminine hygiene products as medical devices accelerates reformulation toward chlorine-free processing and dioxin elimination claims.
- India's PLI scheme incentives:Production-linked incentive programs for domestic organic cotton manufacturing reduce import dependency and localize supply chains for South Asian distribution.
- Composting infrastructure expansion:Municipal biowaste processing facilities in Germany, Netherlands, and California enable certified biodegradable products to command shelf space in zero-waste retail cooperatives.
Market Restraints
- Organic cotton input cost volatility:Weather-dependent agricultural yields and certified acreage constraints create margin pressure for manufacturers without backward integration into farming operations.
- ECHA REACH compliance costs:European chemical registration and traceability mandates impose documentation burdens that disproportionately affect small-scale producers entering EU markets.
- Petrochemical superabsorbent polymer substitution:Conventional SAP materials retain cost and performance advantages in high-absorbency segments, limiting organic penetration in overnight and heavy-flow categories.
Strategic Opportunities
- Subscription direct-to-consumer channels:Digital-first brands bypass pharmacy and supermarket slotting fees while capturing recurring revenue through personalized cycle-tracking apps.
- EU Green Deal procurement mandates:Public sector purchasing guidelines for sustainable hygiene products create institutional demand channels across municipal health services and educational institutions.
- Plant-based bioplastic convergence:Integration of polylactic acid backsheet films with organic cotton cores enables full-product compostability certifications that differentiate premium positioning.
Industry Challenges
- BIS certification timeline compression:India's quality benchmarking process for feminine hygiene products creates extended market entry delays for new domestic manufacturers seeking formal approval.
- Extended producer responsibility compliance:Evolving state-level EPR laws in California, Washington, and New York require packaging redesign and end-of-life take-back systems that strain operational infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Sanitary Napkin Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable, Eco-Friendly, Chlorine-Free, Organic Cotton End User: Adult Women, Teenage Girls, Health-Conscious Consumers, Eco-Conscious Consumers Distribution Channel: Online Retailers, Health Stores, Supermarkets, Specialty Shops Price Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | Apropos, Azah Sanitary Pads, Corman SpA, COTTON HIGH TECH SL, Hannah Health One Inc., Rael Inc., The Honest Co. Inc., Saathi Eco Innovations India Pvt. Ltd., Natracare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Sanitary Napkin Market Evolving Landscape
Material science advances and regulatory disclosure mandates are compressing the competitive window for conventional formulations while opening premium positioning for certified organic alternatives with verifiable supply chain transparency.
Plant-based bioplastic backsheet films derived from corn starch and sugarcane bagasse are replacing petroleum-derived polyethylene layers in premium product tiers. European pharmacy chains and North American zero-waste retailers have adopted these materials as shelf-entry requirements. Conventional plastic-backed napkins are rendering obsolete in urban markets with active composting programs.
EU MDR traceability mandates now require lot-level documentation for absorbent hygiene products sold as medical devices. Manufacturers must maintain supplier qualification records and adverse event reporting systems. Small European producers face consolidation pressure while larger suppliers invest in ERP system upgrades to satisfy notified body audits.
Cycle-tracking application integration is reshaping how consumers discover and replenish organic napkin purchases. Subscription algorithms predict usage patterns and automate delivery timing, displacing emergency pharmacy purchases. This behavioral shift concentrates most visibly among millennial and Gen-Z demographics in South Korea, Germany, and coastal US metropolitan markets.
Organic Sanitary Napkin Market Segmentation
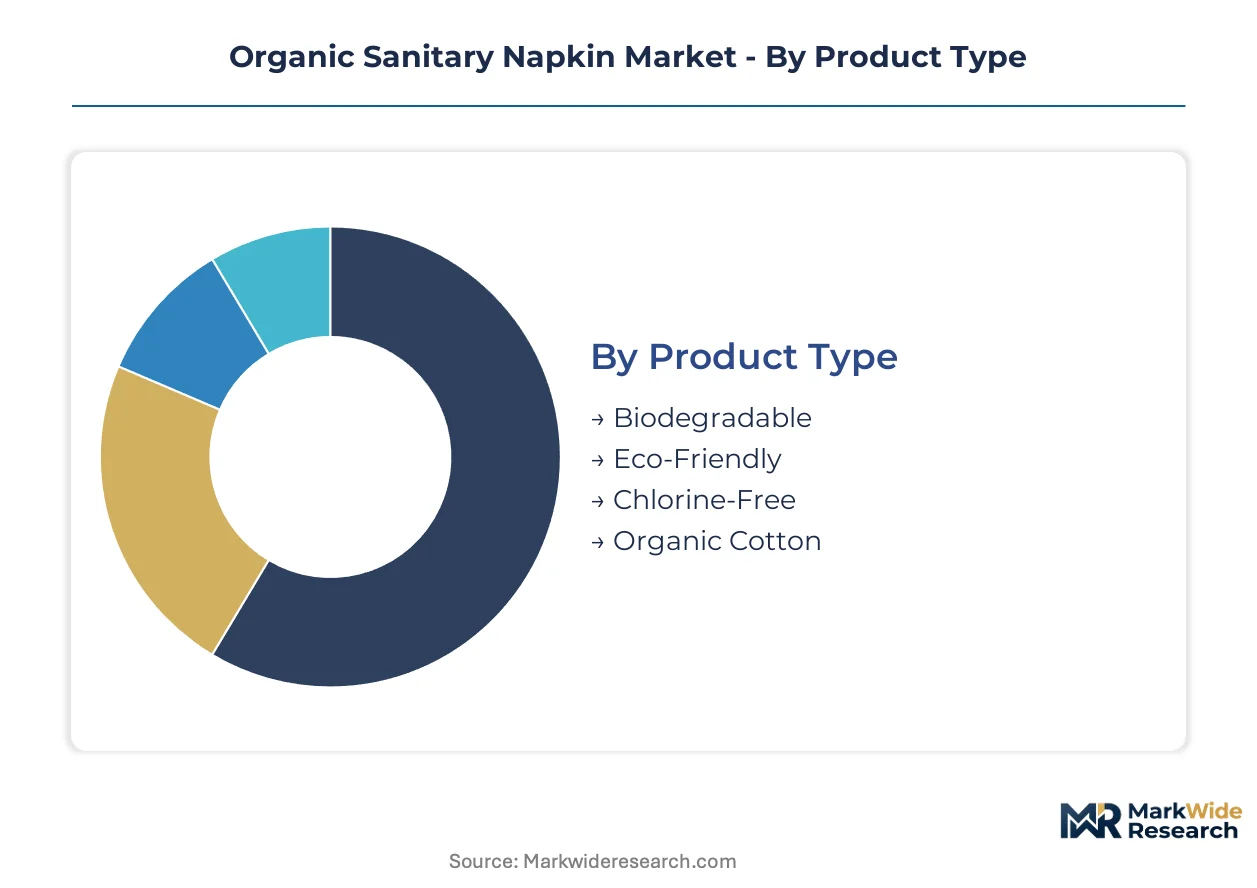
Segmentation in organic sanitary napkins reveals how material certifications, user life stages, and channel economics create distinct competitive arenas. Manufacturers must align formulation investments with the specific compliance and margin requirements of each slice.
Product Type:
Cycle times vary dramatically across material platforms, with compostable certifications driving the fastest inventory turnover in urban zero-waste retail while conventional organic cotton maintains slower, steadier replenishment through pharmacy chains.
- Organic Cotton:Certified fiber cores sourced from agricultural cooperatives dominate current volume through established supply chains and consumer familiarity with natural fiber claims. Demand concentrates in India where BIS certification and PLI scheme incentives accelerate domestic manufacturing localization.
- Chlorine-Free:Processing methods eliminating dioxin formation command margin premiums in European pharmacy chains and North American health stores. German and Dutch municipalities with active composting programs favor these products for shelf placement.
- Biodegradable:Full-product compostability certifications enable entry into zero-waste retail cooperatives across California and the Netherlands.
- Eco-Friendly:Broader environmental claims without specific certifications serve price-sensitive segments through supermarket distribution.
Organic cotton dominates installed base. Chlorine-free processing is where expansion concentrates.
End User:
User life stage determines both performance requirements and channel access, with teenage segments showing highest price elasticity and health-conscious demographics driving subscription adoption.
- Adult Women:Heavy-flow and overnight performance needs sustain premium positioning through pharmacy and specialty retail. Demand clusters in South Korean and German metropolitan markets where cycle-tracking app integration enables subscription automation.
- Health-Conscious Consumers:Chemical exposure reduction priorities drive FDA and EPA compliance scrutiny and chlorine-free formulation preferences. Coastal US cities and European urban centers show highest per-capita spending.
- Teenage Girls:First-product trial occasions and school-based distribution create distinct packaging and education requirements.
- Eco-Conscious Consumers:Composting infrastructure access determines purchase willingness and brand loyalty in municipalities with biowaste processing.
Adult women represent the largest addressable population. Health-conscious consumers are climbing the fastest.
Distribution Channel:
Channel selection determines margin structure and customer data access, with digital-native platforms capturing recurring revenue while physical retail sustains trial and emergency purchase occasions.
- Online Retailers:Direct-to-consumer subscription models bypass slotting fees and capture usage pattern data through integrated cycle-tracking applications. South Korean and coastal US markets show highest digital penetration.
- Specialty Shops:Curated zero-waste and natural product retailers require compostability certifications and supply chain transparency documentation.
- Health Stores:Pharmacy chain placement demands medical-grade certification standards and adverse event reporting systems under EU MDR and FDA frameworks.
- Supermarkets:Mass retail placement competes on price point with limited shelf space for premium organic positioning.
Health stores anchor premium volume. Online retailers are gaining share fastest.
Price Tier:
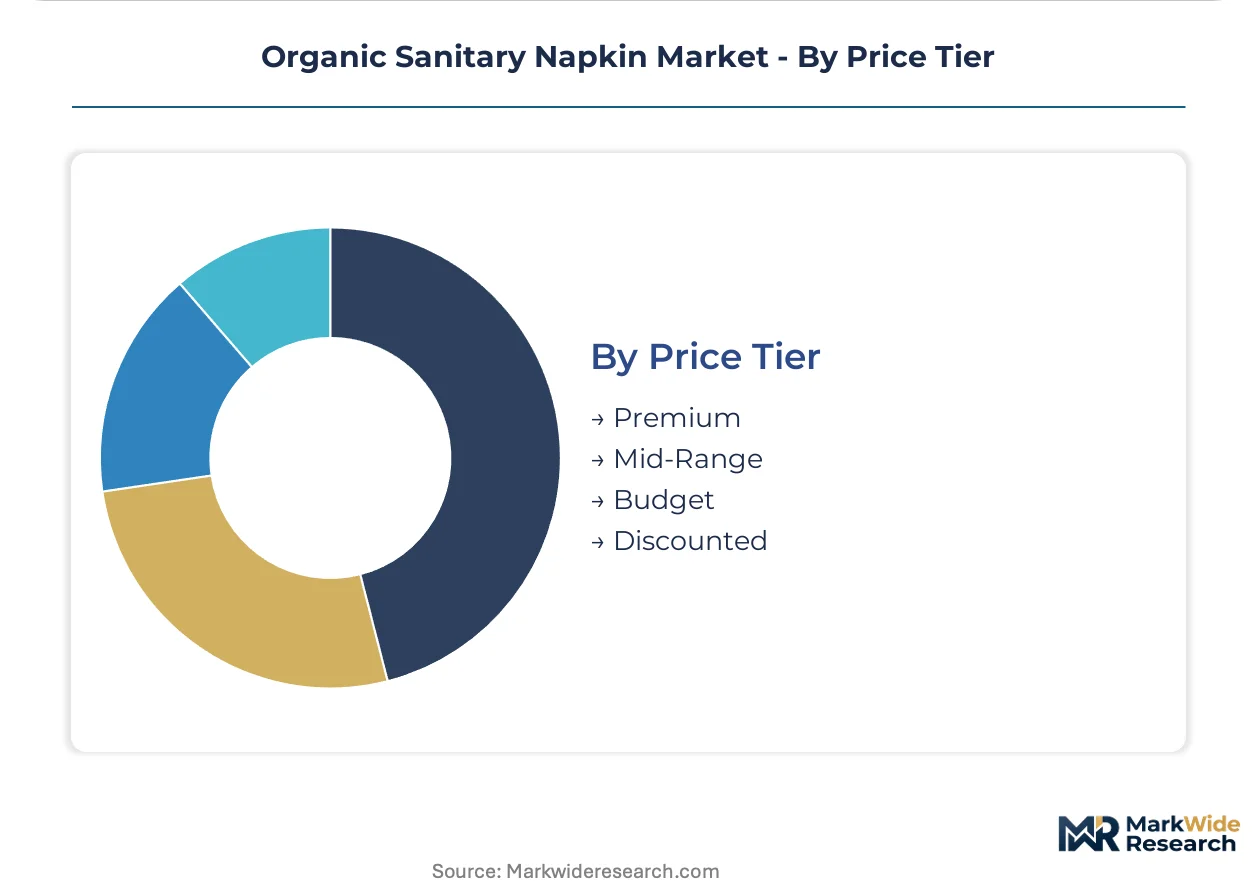
Pricing stratification reflects certification depth and material cost structure, with medical-grade and compostable products commanding substantial premiums over basic organic claims.
- Premium:Full certifications including organic cotton sourcing, chlorine-free processing, and biodegradable backsheet films target health-conscious and eco-conscious segments through specialty and pharmacy channels.
- Mid-Range:Selective certification combinations balance cost and positioning for mainstream health store distribution.
- Budget:Basic organic cotton claims without processing certifications compete in supermarket and value-oriented online platforms.
- Discounted:Promotional pricing and trial-size formats drive first purchase conversion in subscription models and retail entry.
Premium tier captures the highest margin per unit. Mid-range is where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme incentives and BIS certification requirements are accelerating domestic organic cotton manufacturing while reshaping competitive access across South Asian distribution networks.
United States
FDA oversight of feminine hygiene products as medical devices drives reformulation investments toward chlorine-free processing standards. EPA safety guidelines for dioxin elimination claims create labeling compliance burdens that favor established manufacturers with adverse event reporting systems. Coastal metropolitan clusters in California and New York show highest subscription adoption through cycle-tracking app integration.
Germany
Municipal biowaste processing infrastructure enables certified biodegradable products to capture shelf space in zero-waste retail cooperatives. ECHA REACH compliance mandates impose documentation requirements that consolidate supplier qualification systems among larger producers. The Rhine-Ruhr industrial corridor hosts concentrated distribution logistics serving pharmacy chains across Benelux markets.
India
Production-linked incentive programs reduce import dependency for organic cotton fiber while BIS certification timelines create extended market entry barriers for new domestic manufacturers. Health-conscious consumers in Maharashtra and Karnataka drive demand through specialty retail channels. Gujarat's textile processing clusters are localizing absorbent core manufacturing for regional brands.
South Korea
MFDS medical device classification for feminine hygiene products shapes quality benchmarking and adverse event reporting obligations. Digital-first subscription models achieve highest penetration in Seoul metropolitan markets through integrated cycle-tracking applications. Korean manufacturing partnerships sustain premium positioning for brands targeting North American and Asian export channels.
Netherlands
Advanced composting infrastructure in Amsterdam and Rotterdam municipalities enables full-product compostability certifications to command retail placement in zero-waste cooperatives. EU Green Deal procurement guidelines for sustainable hygiene products create institutional demand through municipal health services. The Randstad logistics hub concentrates European distribution for biodegradable backsheet film suppliers.
Organic Sanitary Napkin Market Competitive Landscape
On the supply side, the industry is moderately fragmented with tiered specialization across material platforms and certification depths. Mid-scale manufacturers with backward integration into organic cotton farming operations compete against digital-native brands leveraging subscription economics. Two strategic archetypes dominate: certified organic specialists with medical-grade compliance systems, and direct-to-consumer platforms with cycle-tracking app integration. Competitive moves concentrate on geographic licensing partnerships for compostability certifications and capacity expansion in Indian PLI scheme zones.
Within the certified organic specialist tier, Corman SpA and Natracare exemplify European manufacturers with established pharmacy chain distribution and medical-grade certification standards under EU MDR frameworks. Rael Inc. occupies a position among digitally native brands leveraging Korean manufacturing partnerships for premium positioning across Asian and North American markets. Saathi Eco Innovations India Pvt. Ltd. represents the domestic manufacturing archetype capitalizing on BIS certification and PLI scheme incentives to localize supply chains for South Asian distribution.
| Leading Market Players |
|---|
| Apropos |
| Azah Sanitary Pads |
| Corman SpA |
| COTTON HIGH TECH SL |
| Hannah Health One Inc. |
| Rael Inc. |
| The Honest Co. Inc. |
| Saathi Eco Innovations India Pvt. Ltd. |
| Natracare |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr logistics corridor's freight cost dynamics amplify supply concentration effects in European organic sanitary napkin distribution, compressing margins for non-integrated manufacturers while enabling certified producers to sustain price premiums across pharmacy and zero-waste retail channels.
Pricing Analysis
Certification level creates the primary spread between premium and economy positioning in organic sanitary napkins. A three-tier pricing structure across premium, standard, and economy levels dominates, with FDA-grade and EU MDR medical device certifications commanding substantial premiums over basic organic cotton claims. Price differentiation stems from chlorine-free processing depth and biodegradable backsheet film integration. Pricing pressure intensifies in budget tiers as Indian PLI scheme incentives expand domestic manufacturing capacity and compress import parity pricing. Teenage and first-time buyer segments exhibit highest price sensitivity, while health-conscious consumers in coastal US and German metropolitan markets demonstrate lowest elasticity.
Supply Chain Analysis
Tariff exposure between India and Bangladesh dominates supply chain risk calculations for organic cotton fiber sourcing. Manufacturing concentrates in India, South Korea, and Italy, with Gujarat's textile clusters and Korean contract manufacturing facilities anchoring volume production. Raw material dependencies center on certified organic cotton acreage, plant-based bioplastic resins, and chlorine-free wood pulp supply. Single-source vulnerability in certified organic cotton farming operations creates exposure to weather-driven yield volatility. Distribution runs through pharmacy chain procurement systems in Europe, direct-to-consumer subscription platforms in North America, and specialty retail cooperatives in composting-enabled municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment services and cycle-tracking application integration represent the fastest-expanding recurring-revenue layer in organic sanitary napkins, outpacing hardware margin capture and reshaping customer lifetime value calculations across digital-native brands.
For Market Incumbents: Entrench pharmacy chain relationships through EU MDR compliance investments and adverse event reporting system upgrades that smaller competitors cannot replicate. Backward integration into certified organic cotton farming operations in India secures input cost stability against weather-driven volatility. Defensive patent positioning around biodegradable backsheet film formulations limits substitute material encroachment from conventional petrochemical suppliers. For New Entrants and Emerging Players: Municipal health service procurement in EU Green Deal jurisdictions represents the most penetrable entry point for certified biodegradable product lines with institutional purchasing mandates. India's BIS certification backlog creates white-space opportunities for domestic manufacturers with expedited approval timelines. A direct-to-consumer launch anchored in Seoul or California metropolitan markets leverages cycle-tracking app integration to bypass established pharmacy distribution gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with medical-grade certification infrastructure and compostability verification systems already operational. Long-term viability across a five-to-ten year window rests on regulatory disclosure mandate compliance rather than formulation innovation alone. Acquisition targets should demonstrate ERP system compatibility with EU MDR traceability requirements. The signal to watch is municipal composting infrastructure buildout velocity in California, Netherlands, and German urban clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Backsheet Certification | Compostability verification unlocks zero-waste retail placement in Amsterdam and Rotterdam cooperatives. |
| Backward Integration into Organic Cotton | Gujarat farming operations reduce exposure to certified acreage constraints and input cost volatility. |
| Direct-to-Consumer Subscription Launch | Cycle-tracking app integration captures recurring revenue and displaces emergency pharmacy purchases. |
| EU MDR Compliance Investment | Medical device classification enables pharmacy chain shelf access across German and Benelux markets. |
| PLI Scheme Capacity Expansion | Domestic Indian manufacturing localizes supply chains for South Asian distribution networks. |
Research Methodology
A standing panel of brand managers at organic hygiene manufacturers, category buyers at pharmacy chains, supply planners at bioplastic resin suppliers, and certification auditors at BIS and EU notified bodies provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from FDA medical device registration databases, ECHA REACH substance filings, Indian PLI scheme disbursement records, and municipal composting infrastructure development reports. Bottom-up demand modeling across end-user segments triangulated against top-down value chain analysis.
Scenario-bracketing framed the analytical approach across the projection horizon, with optimistic, baseline, and stress-case assumptions tested for organic cotton yield volatility, regulatory timeline compression, and subscription adoption elasticity. Segmentation dimensions modeled included material platform type, certification depth tier, distribution channel economics, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to normalized baseline volumes. Industry-specific forecast inputs incorporated composting facility commissioning schedules and EU Green Deal procurement guideline implementation trajectories.
Stress conditions across certified organic cotton price bands, BIS approval timeline distributions, and municipal biowaste processing capacity buildouts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory disclosure mandate evolution and consumer willingness-to-pay for compostability certifications. Material shifts in FDA medical device reclassification timelines or extended producer responsibility law implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Safety Products
Booster Car Seats Market
Baby Safety Products
Japan Adult Diaper Market
Baby Safety Products
BRICS Disposable Hygiene Products Market
Baby Safety Products
Reusable/Washable Hygiene Products Market
Baby Safety Products
Baby Gate Market
Baby Safety Products
North America Adult Diaper Market
Baby Safety Products
Baby Safety Products Market
Baby Safety Products
Global Feminine Protection Market
Baby Safety Products
India Pant Type Adult Diaper Market
Baby Safety Products
United States Away from Home Tissue and Hygiene Market
Baby Safety Products
Baby Safety Seats Market
Baby Safety Products
Panty Liner Market
Baby Safety Products
Forward Facing Type Child Safety Seats Market
Baby Safety Products
Reusable Sanitary Pads Market
Baby Safety Products
North America Baby Monitors Market
Baby Safety Products
Global Baby Cleaning Products Market