
 Cutlery Market | 2026-2036
Cutlery Market Size, Share, and Industry Trends Forecast 2026-2036
Cutlery Market Analysis
The cutlery market is pivoting on a widening gap between heirloom-grade forged blades and mass-produced stamped flatware destined for institutional food service. Zwilling J.A. Henckels leverages its Solingen forging heritage to command premium positioning in chef-grade knife sets. Wüsthof sustains family-owned craftsmanship credibility while competing across both professional and household channels. Victorinox anchors its cutlery division with Swiss Army brand recognition and precision-ground stainless steel expertise.
Cutlery encompasses hand-held implements for food preparation and consumption, typically manufactured from corrosion-resistant stainless steel alloys containing chromium content of 10.5 percent or higher to prevent oxidation during repeated washing cycles. These tools serve commercial kitchens, household dining rooms, and field catering operations where edge retention, balance, and sanitation compliance determine operational efficiency. Stainless steel knives dominate professional kitchen procurement due to hardness ratings between 54 and 62 HRC that balance durability against sharpening frequency. Plastic and bamboo alternatives capture institutional contracts where single-use sanitation protocols override lifecycle cost considerations. Specialty tools including oyster shuckers, grapefruit spoons, and cheese knives occupy concentrated margin pools within gourmet retail channels.
The U.S. Food and Drug Administration governs food-contact surface safety under 21 CFR 175.300, while the EU REACH regulation restricts nickel migration rates in metal alloys contacting acidic foods. Germany's KBA does not regulate cutlery directly, but CE marking requirements under the EU General Product Safety Directive shape market access for imported flatware. Stakeholders must monitor alloy substitution trends as regulators tighten heavy-metal thresholds and hospitality buyers demand material traceability documentation.
Market Dynamics
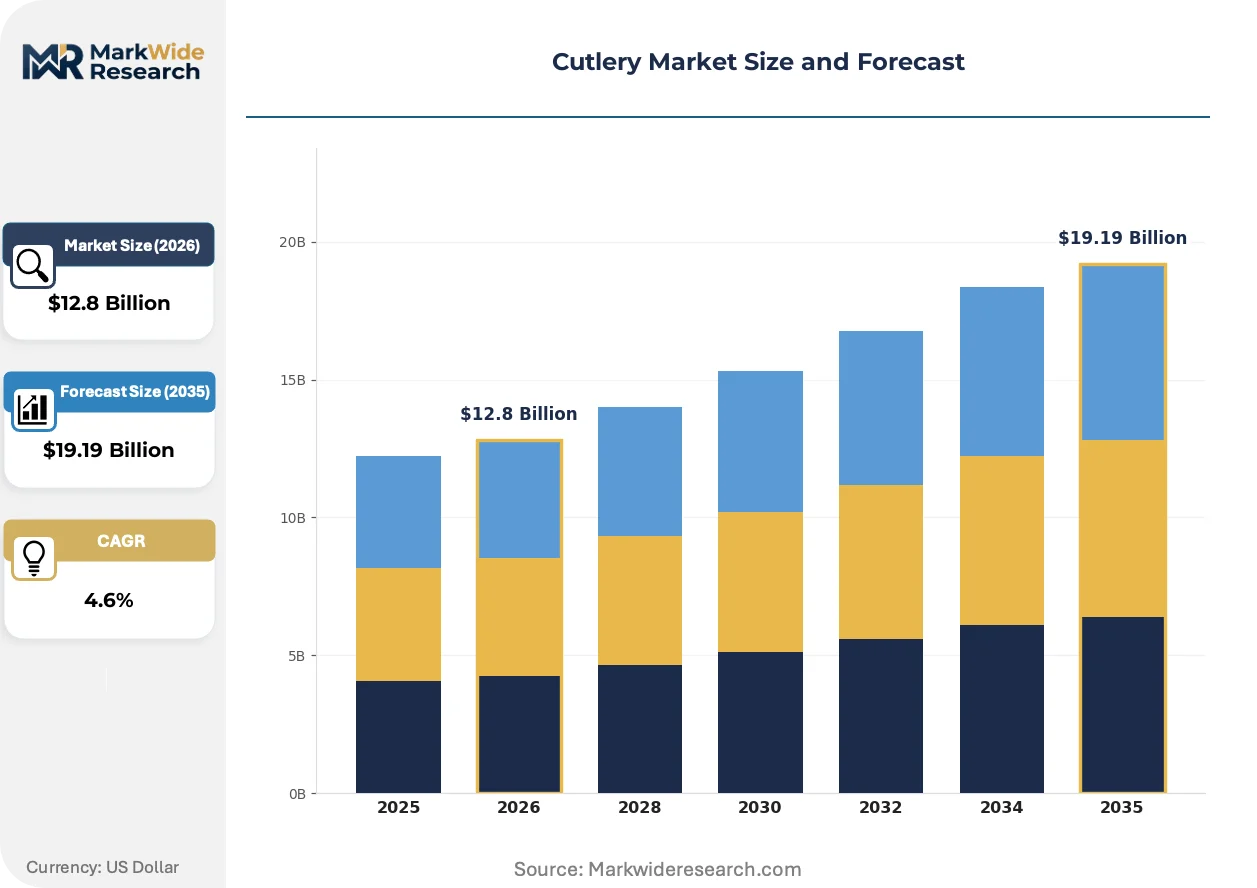
REACH nickel-release thresholds are forcing alloy reformulation across European supply chains while full-service dining recovery in North America and Europe pulls stainless steel flatware demand upward.
Growth Catalysts
- EU REACH compliance mandates:Tightened nickel migration limits for metal alloys contacting acidic foods are accelerating certified alloy adoption across German and French manufacturing clusters.
- Hospitality procurement expansion:Full-service dining recovery across the United States and United Kingdom is expanding stainless steel flatware orders from institutional food service distributors.
- Solingen blade heritage:Germany's concentrated forging expertise anchors premium chef-grade knife exports to professional kitchens seeking hardness ratings above 58 HRC.
Market Restraints
- Alloy input cost volatility:Chromium and nickel price fluctuations squeeze margin structures for mid-tier stamped flatware producers dependent on commodity stainless steel grades.
- Single-use plastic substitution:Institutional contracts in healthcare and airline catering increasingly specify disposable bamboo or compostable polymer alternatives over lifecycle cost considerations.
- Supply concentration risk:Forged blade production clusters heavily in Solingen and Seki, Japan, creating geographic vulnerability to localized energy or labor disruptions.
Strategic Opportunities
- Material traceability documentation:ECHA's SCIP database requirements for SVHC substances are creating first-mover advantage for suppliers with blockchain-verified alloy sourcing.
- Specialty tool margin pools:Oyster shuckers, cheese knives, and grapefruit spoons occupy concentrated premium retail channels underserved by mass-market flatware catalogs.
- Direct-to-chef distribution:Bypassing traditional hospitality distributors through culinary school partnerships and restaurant group procurement alliances.
Industry Challenges
- Master smith skill scarcity:Solingen's aging forging workforce lacks replacement pipeline for hand-hammered blade techniques required in premium chef-grade production.
- CE marking timeline compression:EU General Product Safety Directive documentation requirements delay market entry for Asian manufacturers lacking in-house compliance teams.
- Legacy ERP integration:Material traceability systems require expensive middleware to connect with decades-old inventory management platforms at established flatware distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutlery Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knives, Forks, Spoons, Specialty Tools Material: Stainless Steel, Plastic, Wood, Bamboo End User: Households, Restaurants, Catering Services, Food Trucks Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Zwilling J.A. Henckels, Wüsthof, Victorinox, WMF, Oneida, Cutco Corporation, Robert Welch, Christofle, Georg Jensen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutlery Market Emerging Trajectories
Powder metallurgy is overtaking traditional forging in high-performance blade production. Regulatory documentation requirements are reshaping supplier-buyer data exchange protocols. Procurement consolidation among hospitality groups is compressing vendor qualification cycles.
Powder metallurgy is overtaking conventional forging for premium chef knives by enabling superior carbide distribution and edge retention. Professional kitchen buyers in the United States and Germany are specifying PM-produced blades at accelerating rates. This materials shift is compressing the performance gap between mid-tier and heirloom-grade manufacturers.
EU REACH SCIP database obligations are mandating detailed substance-of-concern disclosure across metal cutlery supply chains. Manufacturers must now document SVHC content above 0.1% weight-by-weight for every article entering European distribution. German importers are responding by requiring upstream alloy certificates before contract execution.
Group purchasing organizations in hospitality are consolidating flatware procurement across multi-property restaurant chains and hotel portfolios. Traditional broadline distributors are losing share to direct manufacturer relationships with procurement teams at corporate headquarters. This concentration is most visible in the United Kingdom and United States where franchise and chain dining density is highest.
Cutlery Market Segmentation
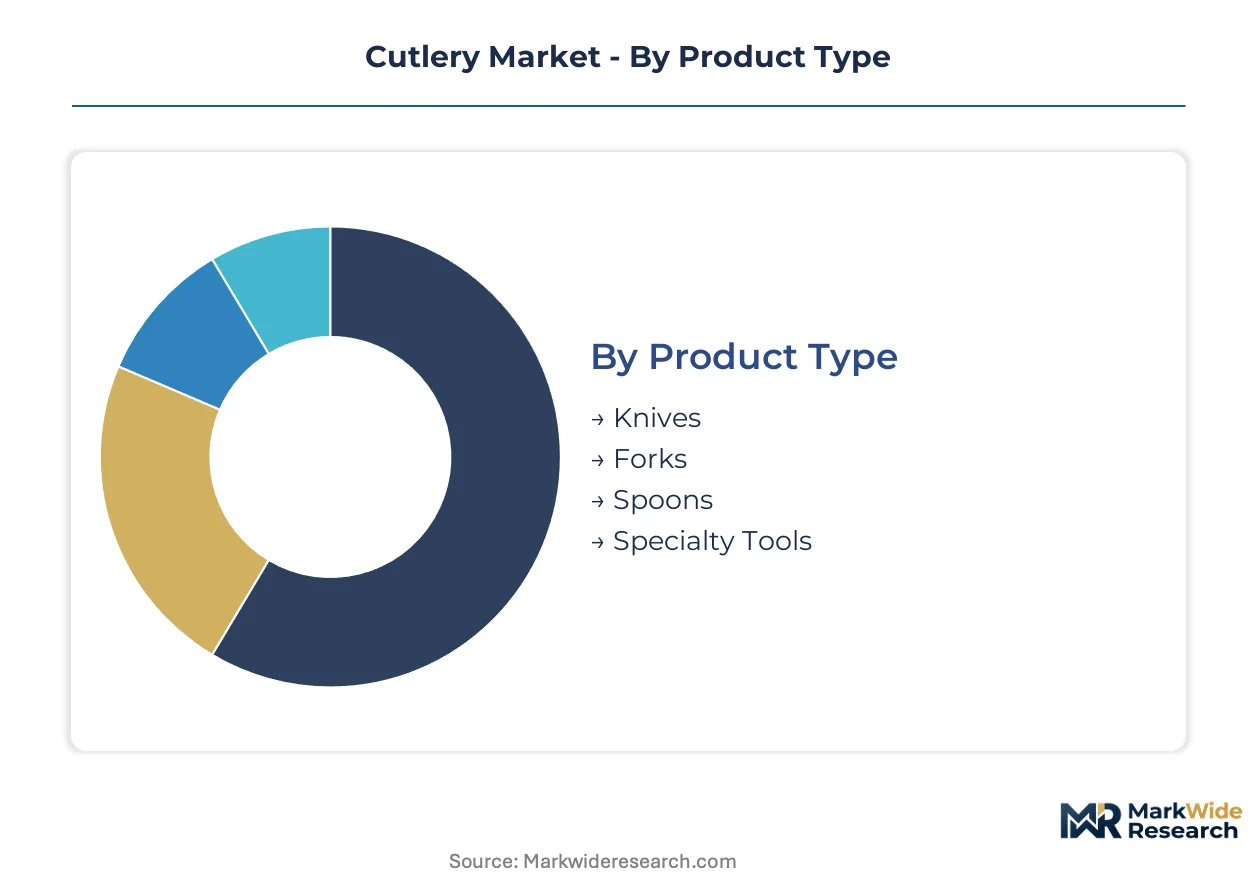
Cutlery procurement decisions split across performance specifications, regulatory compliance burdens, and operational scale requirements. Each segmentation axis reveals distinct margin structures and vendor qualification thresholds that reshape competitive positioning across manufacturing clusters.
Product Type:
Blade geometry and edge retention specifications define the technology hierarchy across implement categories, with hardness ratings and forging methods creating clear performance tiers.
- Knives:Forged blades from Solingen and Seki command premium positioning through hardness ratings of 58-62 HRC and hand-hammered grain structure. Professional kitchen procurement in Germany and the United States specifies these for edge retention under commercial sharpening protocols.
- Forks:Tine geometry and neck strength determine institutional acceptance, with four-tine dinner forks dominating full-service dining recovery across the United Kingdom and France. REACH-compliant nickel-release certification is becoming mandatory for contract qualification.
- Spoons:Bowl depth and handle balance vary by service application, from bouillon spoons to serving ladles.
- Specialty Tools:Oyster shuckers, grapefruit spoons, and cheese knives occupy concentrated margin pools in gourmet retail channels underserved by mass-market catalogs.
Mature deployment sits with knives and forks. Newer deployment is concentrated in specialty tools as culinary tourism and experiential dining expand.
Material:
Corrosion resistance and food-contact safety regulations drive alloy selection, with compliance documentation now required across European supply chains.
- Stainless Steel:Chromium content of 10.5 percent or higher prevents oxidation during repeated washing cycles. German manufacturers are reformulating alloys to meet tightened REACH nickel-release thresholds for acidic food contact.
- Plastic:Single-use polymer implements capture healthcare and airline catering contracts where sanitation protocols override lifecycle cost considerations. Compostable alternatives are displacing conventional petroleum-based grades in Scandinavian institutional procurement.
- Wood:Hardwood handles and disposable utensils serve field catering and outdoor hospitality segments with biodegradability requirements.
- Bamboo:Rapid-renewable fiber substitutes are expanding in fast-casual and grab-and-go formats across California and British Columbia regulatory environments.
Volume leadership belongs to stainless steel. Steepest expansion trajectory is concentrated in bamboo as single-use bans proliferate across municipal jurisdictions.
End User:
Operational scale and replacement frequency determine procurement channel preferences, with enterprise buyers demanding material traceability documentation.
- Households:Replacement-driven purchases favor mid-tier stamped flatware through supermarket and online channels, with heirloom-grade forged sets occupying gift and bridal registry occasions.
- Restaurants:Full-service dining recovery in the United States and United Kingdom is pulling stainless steel flatware orders upward, with group purchasing organizations consolidating vendor relationships.
- Catering Services:High-turnover operations balance acquisition cost against loss rates, often specifying mid-grade stainless steel or disposable alternatives for off-premise events.
- Food Trucks:Space-constrained mobile operations prioritize multi-function tools and compact storage, creating demand for specialized utensil sets with integrated holders.
Contract concentration is heaviest with restaurants. Emerging volume is concentrating in food trucks as urban mobile dining formats expand.
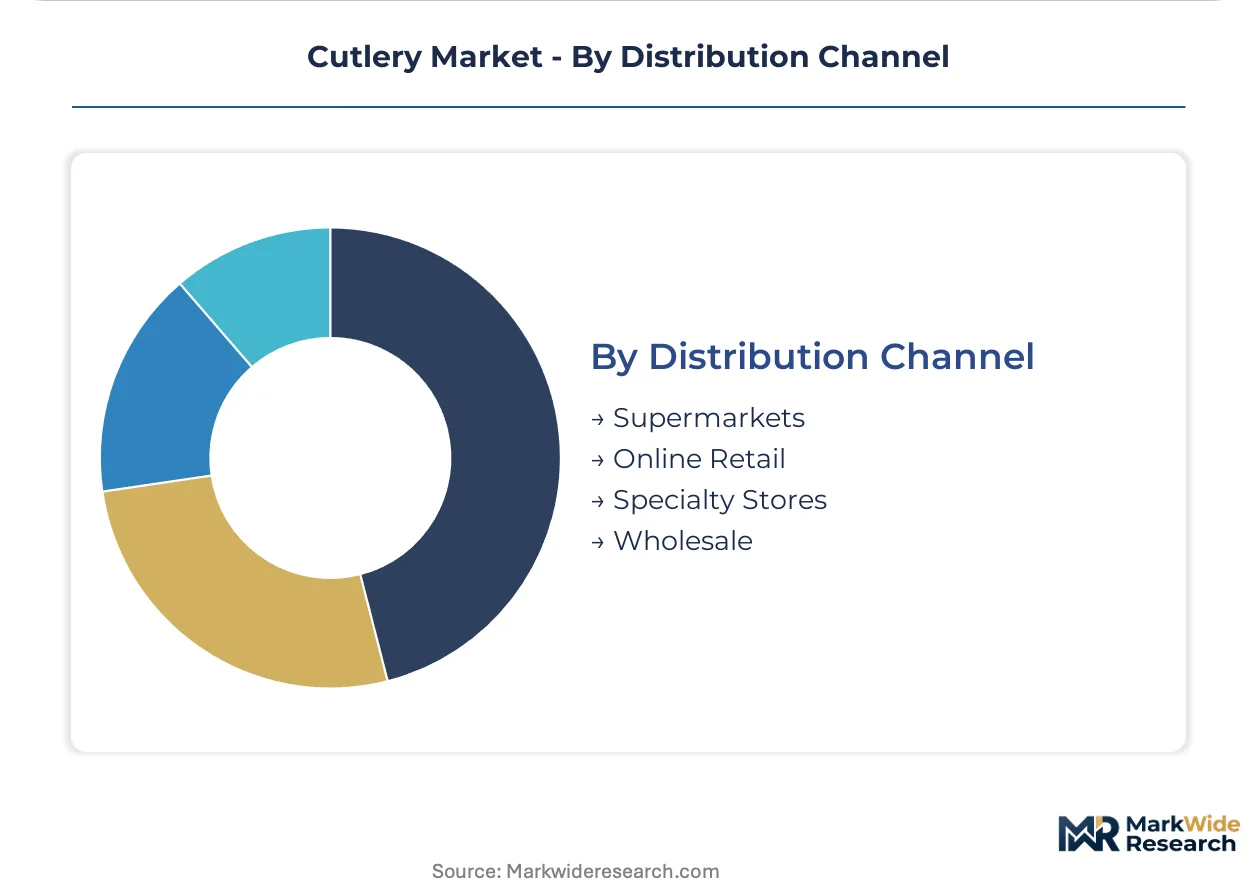
Distribution Channel:
Channel selection reflects buyer sophistication and order scale, with hospitality procurement teams bypassing traditional intermediaries.
- Supermarkets:Mass-market flatware and replacement pieces serve household impulse and planned replacement purchases, with seasonal promotional cycles driving volume spikes.
- Online Retail:Direct-to-consumer platforms enable chef-grade knife discovery outside traditional geographic markets, with review-driven demand concentrating in German and Japanese heritage brands.
- Specialty Stores:Gourmet retailers and kitchen supply boutiques capture premium gift occasions and professional trade, offering in-person edge testing and handle balance evaluation.
- Wholesale:Broadline distributors serve institutional contracts with volume pricing and consolidated logistics, though hospitality group purchasing organizations are compressing their role.
Established volume flows through wholesale. Channel shift is accelerating toward online retail as procurement teams at multi-property chains centralize vendor qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solingen anchors premium blade production with centuries of forging heritage concentrated in this North Rhine-Westphalia city. The report tracks demand patterns across five countries where hospitality recovery and regulatory tightening reshape procurement.
Germany
Full-service dining recovery in Berlin and Munich drives stainless steel flatware orders from institutional distributors. ECHA's REACH mandates tightened nickel-release thresholds for acidic food contact, forcing alloy reformulation across supply chains. Solingen's blade-making cluster sustains premium chef-grade knife exports through hardness ratings above 58 HRC.
United States
Group purchasing organizations in Chicago and New York consolidate flatware procurement across multi-property restaurant chains. FDA's 21 CFR 175.300 governs food-contact surface safety for imported metal alloys. California's municipal single-use bans accelerate bamboo alternative adoption in fast-casual formats.
United Kingdom
Hospitality procurement teams in London expand stainless steel orders as full-service dining recovers post-pandemic. CE marking under the EU General Product Safety Directive shapes market access for Asian flatware imports. Sheffield's historical cutlery heritage now hosts specialized sharpening services and blade restoration workshops.
France
Parisian restaurant groups demand material traceability documentation under ECHA's SCIP database requirements for SVHC substances. ANSM monitors food-contact material safety alongside EU-wide REACH compliance. Thiers retains concentrated knife manufacturing expertise serving professional kitchen channels.
Japan
Seki's blade-making tradition competes with Solingen for professional kitchen share in export markets. METI oversees industrial standards alignment with international food-contact regulations. Osaka-based distributors consolidate procurement for regional hospitality chains seeking hardness-optimized forged products.
Cutlery Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where forging heritage commands premium positioning. The market fragments between heirloom-grade artisans and mass-market stamped flatware suppliers. Three archetypes dominate: Solingen-forged heritage brands, Swiss precision manufacturers, and North American direct-to-consumer specialists. Competitive moves concentrate on direct chef distribution partnerships and material traceability certification.
Within the heritage-forged tier, Zwilling J.A. Henckels and Wüsthof exemplify family-owned craftsmanship credibility competing across professional and household channels. Victorinox occupies a position bridging Swiss Army brand recognition with precision-ground stainless steel expertise. These three represent distinct geographic anchoring strategies—German forging heritage versus Swiss precision engineering—while competing for chef-grade procurement specifications.
| Leading Market Players |
|---|
| Zwilling J.A. Henckels |
| Wüsthof |
| Victorinox |
| WMF |
| Oneida |
| Cutco Corporation |
| Robert Welch |
| Christofle |
| Georg Jensen |
| Others |
Supply Flow & Price Mechanics
Hospitality group purchasing organizations concentrate procurement authority at corporate headquarters, compressing vendor relationships into volume-based contract structures that reward certified alloy documentation and penalize mid-tier suppliers lacking REACH compliance infrastructure.
Pricing Analysis
Edge retention performance under commercial sharpening protocols anchors value-based pricing for chef-grade forged blades from Solingen and Seki. Pricing stratifies across premium heritage-forged tiers, mid-grade stamped flatware, and economy-grade institutional disposables. Cost compression in mid-tier stainless steel flatware intensifies because chromium and nickel input volatility squeezes margin structures for producers dependent on commodity alloy grades. Institutional food service buyers exhibit highest price sensitivity, while professional kitchen procurement teams prioritize hardness ratings and traceability certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Solingen's concentrated forging workforce for hand-hammered blade techniques and Seki's precision-ground production clusters. Manufacturing gravity centers on Germany, Japan, and China for finished cutlery, with raw material supply drawing from Indonesian nickel mines, South African chromium deposits, and Chinese stainless steel mills. Tariff exposure on alloy imports into the European Union creates margin pressure for Asian manufacturers lacking in-house compliance documentation. Distribution runs through broadline hospitality distributors, though direct manufacturer relationships with restaurant group procurement teams are displacing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master smith skill scarcity in Solingen constrains premium forged blade output, propping pricing power for heritage manufacturers with established training pipelines.
For Market Incumbents: Hedge against alloy input volatility through long-term supply agreements with certified nickel and chromium producers. Secure REACH documentation infrastructure ahead of ECHA's tightened SVHC thresholds. Vertical integration into alloy formulation capabilities defends margin position against commodity price swings. For New Entrants and Emerging Players: Direct-to-chef digital platforms bypass entrenched distributor relationships and enable discovery outside traditional geographic markets. Specialty tool categories—oyster shuckers, cheese knives, grapefruit spoons—present the most penetrable white-space with concentrated margin pools underserved by mass-market catalogs. Culinary school partnership programs offer a low-friction go-to-market angle for building professional kitchen credibility. For Investors and Strategic Acquirers: The window for entry favors material traceability specialists with blockchain-verified alloy sourcing infrastructure. Long-term viability hinges on regulatory compliance capability as ECHA documentation requirements expand. Watch for SCIP database adoption velocity as the inflection signal separating compliant suppliers from market-excluded laggards.| Strategic Initiative | Industry Significance |
|---|---|
| Material Traceability Certification | Blockchain-verified alloy sourcing creates first-mover advantage under ECHA SCIP database mandates. |
| Direct-to-Chef Distribution Launch | Culinary school partnerships bypass traditional hospitality distributors and build professional credibility. |
| Powder Metallurgy Capacity Expansion | PM-produced blades compress performance gaps between mid-tier and heirloom-grade manufacturers. |
| Specialty Tool Portfolio Extension | Oyster shuckers and cheese knives occupy concentrated margin pools in gourmet retail channels. |
| REACH Compliance Infrastructure Investment | In-house alloy certification teams accelerate market entry timelines for European distribution. |
Methodological Framework
Independent corroboration across hospitality procurement directors, alloy metallurgists at German manufacturing clusters, and regulatory affairs specialists at ECHA underwrites the qualitative findings. Primary fieldwork engaged flatware distributors in Chicago and London, professional chefs in Berlin and New York, and compliance officers at French and German importers. Secondary validation drew from customs trade databases, SEC filings of listed housewares companies, FDA 21 CFR guidance documents, and ECHA SVHC candidate list publications. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments.
Rate-of-change decomposition across product type, material grade, end-user operational scale, and distribution channel structure shaped the analytical framework. Segmentation modeling captured hardness specification tiers, REACH compliance status, and hospitality procurement consolidation patterns. CAGRs were derived from elasticity-adjusted demand projections and input cost trajectory assumptions. Alloy price volatility indices and hospitality employment recovery metrics served as industry-specific forecast inputs across the projection horizon.
The model holds under sustained hospitality recovery and stable regulatory enforcement timelines; deviation in nickel price spikes or ECHA threshold acceleration would shift volume and value trajectories. Forecasts reflect documented assumptions about procurement consolidation velocity and master smith workforce replacement rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Japan Digital Showers Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Wipes Market
Household Items
Barbecue Grill Market
Household Items
Kuwait Gas Hobs Market
Household Items
Global Tableware Market
Household Items
Household Scales Market
Household Items
Massage Pillow Market
Household Items
Multi Pocket Holders Market
Household Items
Shower Caddies Market
Household Items
Brush Cover Market
Household Items
Cat Hair Remover Market
Household Items
Laundry Dryer Sheets and Bars Market
Household Items
Home Use Air Purifiers Market
Household Items
Global Laptop Tables Market