
 Disposable Napkins Market | 2026-2036
Disposable Napkins Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Napkins Market Outlook
Asian pulp producers is shifting capacity toward bleached softwood kraft grades suited for food-contact napkin lines. Kimberly-Clark Corporation leverages integrated forestry assets across the southeastern United States to sustain raw material security. Essity anchors European demand through specialized away-from-home dispensing systems. Procter & Gamble competes in premium household tiers with reinforced quilted constructions.
Disposable napkins are single-use absorbent sheets manufactured from wood pulp, recycled fibers, or synthetic blends, typically measuring 15–40 cm per side and engineered for moisture retention and surface debris removal in food service and sanitation settings. Paper napkins dominate food service channels due to cost efficiency and compostability, while cloth-like disposable linen captures event catering margins through elevated tactile performance. Online retail represents the fastest-growing distribution channel as institutional buyers consolidate procurement through B2B platforms.
The U.S. FDA governs food-contact substance compliance under 21 CFR, while the EU REACH framework restricts chemical additives in pulp processing. Indonesia's national standards body enforces local content rules on imported sanitary papers. Stakeholders must monitor evolving compostability certifications and regional pulp cost volatility to align capacity investments with shifting procurement criteria.
Market Dynamics
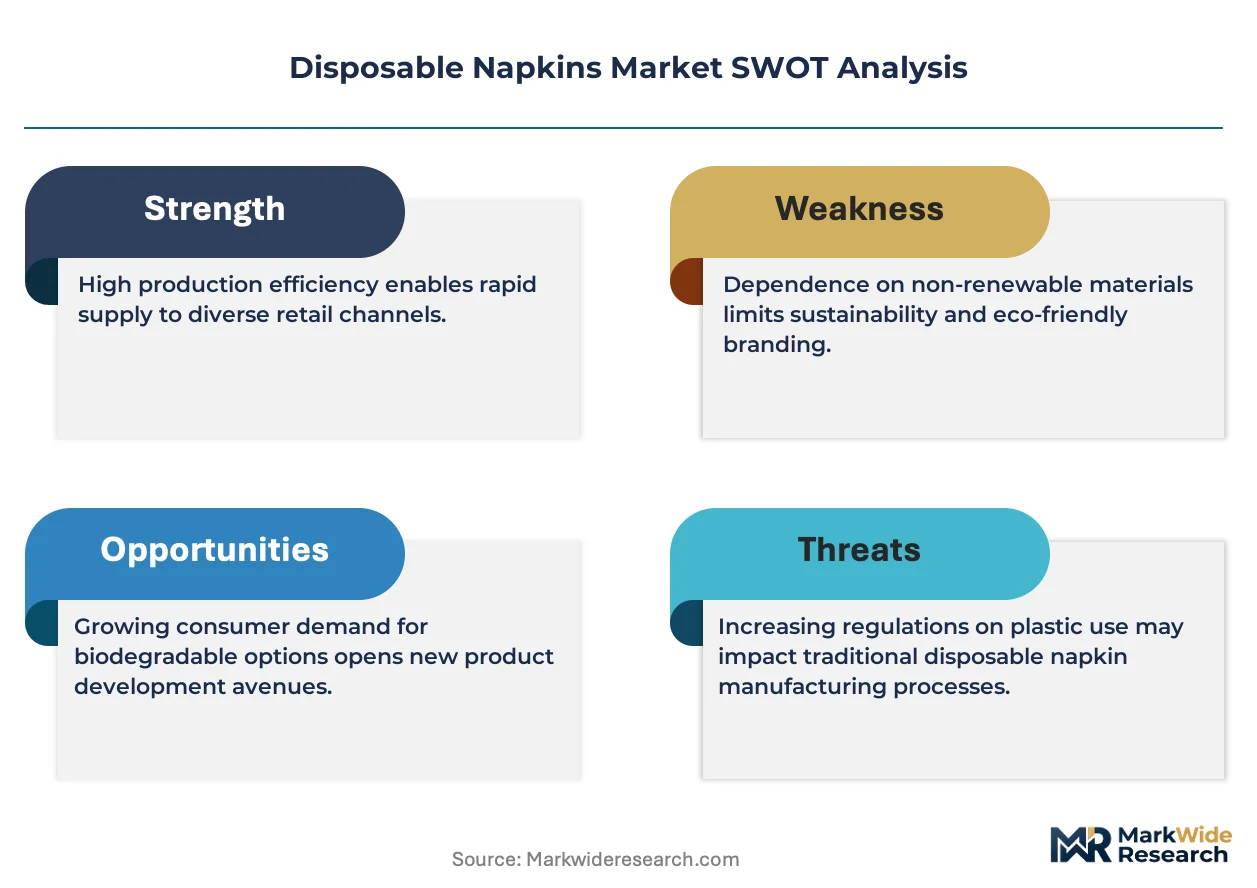
The EU Single-Use Plastics Directive is forcing material transitions across European food service channels, while Asian pulp cost volatility and Indonesian urban food service expansion create divergent regional pressure points.
Growth Catalysts
- EU REACH Framework:Chemical additive restrictions in pulp processing accelerate demand for certified compostable grades, pulling converters toward bleached softwood kraft specifications.
- Quick-service restaurant expansion:Southeast Asian fast-casual chains drive volume adoption of compostable paper napkins through standardized procurement mandates.
- Urban corridor densification:Indonesia's Jakarta-Bandung food service belt concentrates institutional buyers, creating scale efficiencies for regional distributors.
Market Restraints
- Softwood pulp concentration:Brazilian and Scandinavian suppliers control premium bleached kraft supply, exposing converters to freight-driven cost spikes.
- Plastic-linen substitution:Reusable cloth systems capture high-margin event catering contracts, compressing disposable volumes in premium segments.
- Indonesian local content rules:BSN enforcement on imported sanitary papers creates compliance friction for foreign manufacturers seeking market entry.
Strategic Opportunities
- B2B platform consolidation:Institutional buyers in Indonesia are migrating procurement to specialized digital marketplaces, enabling direct manufacturer relationships.
- Compostability certification convergence:Alignment between EU OK Compost and US BPI standards creates unified product qualification for dual-market suppliers.
- Dispensing system integration:Away-from-home operators seek combined napkin-dispenser-waste solutions, opening bundled service contracts.
Industry Challenges
- Pulp chemistry expertise gap:Food-contact compliance under 21 CFR requires specialized regulatory affairs capacity that mid-tier converters struggle to staff.
- Composting infrastructure mismatch:Certified biodegradable napkins face disposal pathway gaps where municipal composting remains underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Napkins Market |
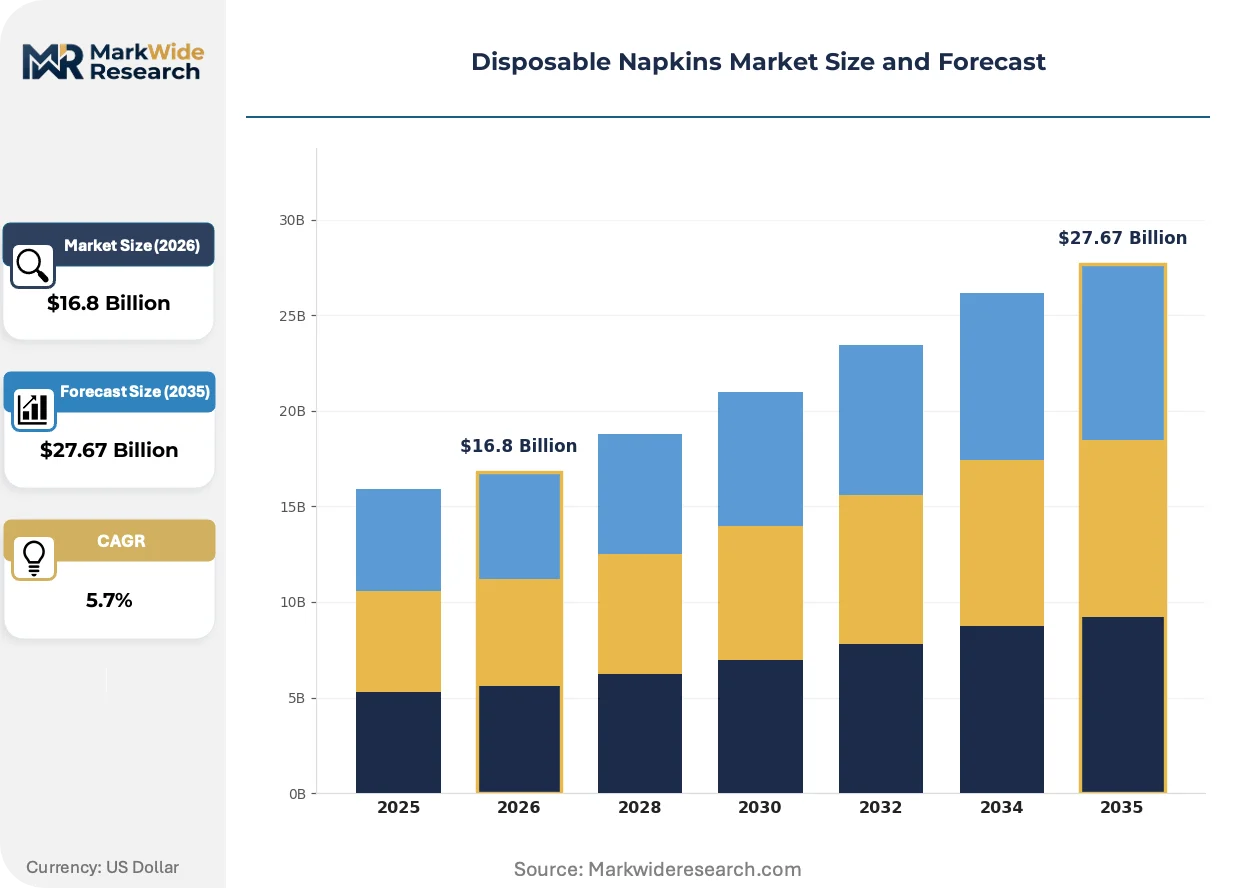
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Napkins, Cloth Napkins, Plastic Napkins, Disposable Linen End User: Restaurants, Cafés, Households, Caterers Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesalers Application: Food Service, Events, Household Use, Industrial Use |
| Companies Covered | Kao Corporation, Edgewell Personal Care Company, Kimberly-Clark Corporation, Ontex, Johnson & Johnson, Procter & Gamble, Hengan International Group, Essity, Unicharm Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Napkins Market Strategic Shifts
Automation and regulatory stringency are compressing production economics while reshaping buyer-supplier relationships across food service channels.
Vision-guided robotic sorting is automating quality control in napkin folding and packaging lines. Tier-one converters in North America and Europe deploy these systems to reduce labor dependency in 24-hour operations. This compression of unit labor costs is automating the viability of regional production against Asian imports in mid-volume segments.
REACH chemical restrictions continue tightening allowable processing aids in pulp bleaching sequences. The framework's Annex XVII updates force converters to validate alternative chemistries through extended migration testing. European away-from-home suppliers absorb the longest certification timelines, delaying product launches by 8-14 months against historical benchmarks.
Consolidated procurement through specialized B2B platforms is replacing fragmented distributor relationships among Indonesian hotel and restaurant chains. These buyers now specify compostability tiers and dispensing compatibility upfront, shifting negotiation leverage toward manufacturers with integrated certification documentation. The Jakarta-Bandung corridor exhibits the most advanced platform adoption, with procurement directors centralizing spend across multi-location operations.
Disposable Napkins Market Segmentation
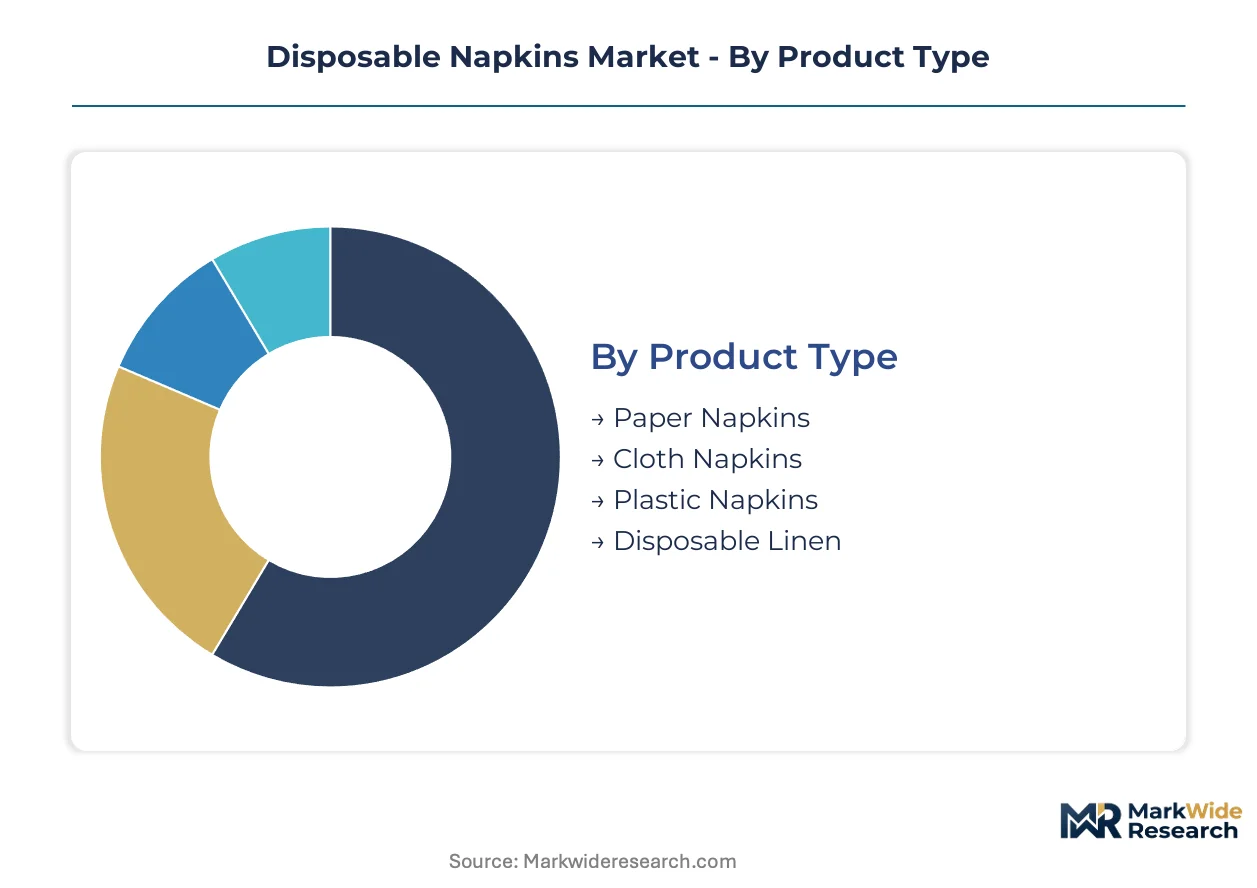
Segmentation in disposable napkins reveals how material chemistry, procurement channel, and end-use specification create divergent margin profiles. Buyers prioritize compostability certification in food service, tactile performance in events, and unit economics in household consumption. Each segment demands distinct supply chain configurations and regulatory compliance pathways.
Product Type:
Pulp sourcing geography and bleaching chemistry differentiate manufacturing economics across material categories.
- Paper Napkins:Bleached softwood kraft construction delivers food-contact compliance under FDA 21 CFR and EU REACH frameworks. Quick-service restaurants across Indonesia's Jakarta-Bandung corridor specify these for standardized procurement mandates.
- Cloth Napkins:Woven cotton or polyester blends provide elevated tactile performance for premium dining establishments. Reusable cloth systems capture high-margin event catering contracts in European markets, compressing disposable volumes in this segment.
- Plastic Napkins:Polypropylene or polyethylene bases face regulatory pressure from EU Single-Use Plastics Directive restrictions. Demand concentrates in price-sensitive emerging markets with limited composting infrastructure.
- Disposable Linen:Airlaid nonwoven structures mimic textile hand-feel for upscale hospitality applications. Southeast Asian resort chains specify these for guest experience differentiation.
Today's leader: Paper Napkins. Tomorrow's challenger: Disposable Linen.
End User:
Volume scale and specification stringency separate institutional buyers from fragmented consumer demand.
- Restaurants:Full-service and fast-casual chains drive bulk procurement through B2B platforms. Indonesian urban food service corridors concentrate purchasing power among multi-location operators.
- Cafés:Smaller format establishments prioritize dispensing system compatibility and countertop footprint. European away-from-home suppliers anchor demand through specialized dispenser-integrated solutions.
- Households:Premium quilted constructions compete on shelf appeal in retail channels. Procter & Gamble targets this segment with reinforced moisture retention features.
- Caterers:Event specialists balance cost control against presentation requirements. Cloth-like disposables capture margins in wedding and corporate segments.
Institutional buyers command pricing leverage. Household purchasers drive brand premiumization.
Distribution Channel:
Channel selection determines certification documentation requirements and logistics cost allocation.
- Online Retail:B2B marketplaces enable direct manufacturer relationships for Indonesian hotel and restaurant chains. Procurement directors centralize spend across multi-location operations through specialized platforms.
- Supermarkets:Mass retail placement demands consumer packaging compliance and promotional slotting fees. Kimberly-Clark leverages integrated forestry assets to sustain shelf presence economics.
- Convenience Stores:Small-format retail captures impulse household purchases in dense urban corridors. Limited SKU breadth favors economy-tier paper specifications.
- Wholesalers:Traditional distributor networks retain relevance in fragmented food service markets. Local content rules in Indonesia create compliance friction for foreign manufacturers accessing this channel.
Platform consolidation accelerates fastest in online retail. Wholesalers defend position through relationship depth.
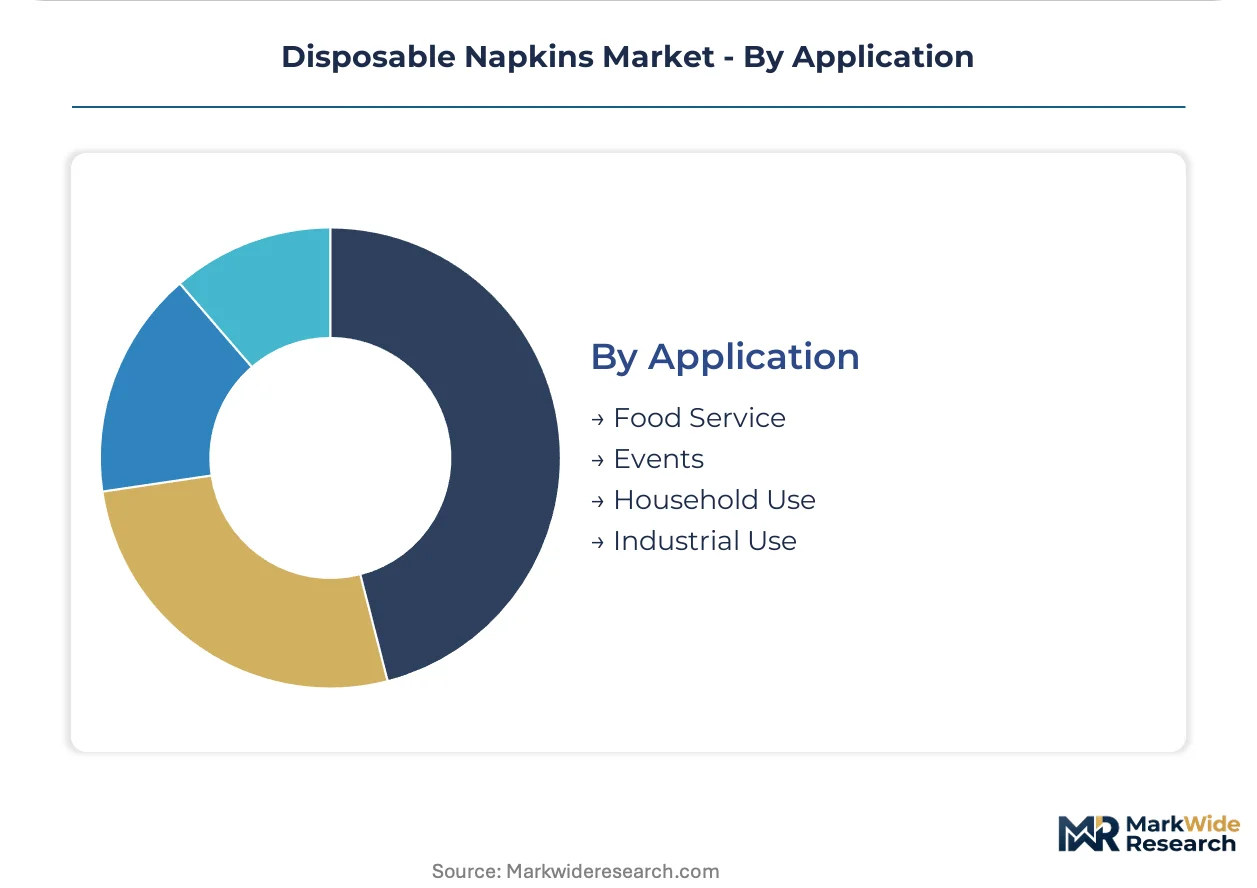
Application:
Use-case severity dictates absorbency engineering and disposal pathway requirements.
- Food Service:Grease resistance and food-contact certification dominate technical specifications. EU REACH chemical additive restrictions accelerate converter migration toward validated alternative chemistries.
- Events:Aesthetic presentation and single-use convenience override unit cost sensitivity. Disposable linen gains share in premium catering through tactile performance differentiation.
- Household Use:Everyday cleaning tasks drive volume demand for economy-tier products. Compostability certification matters less where municipal composting infrastructure remains underdeveloped.
- Industrial Use:Heavy-duty absorbency for manufacturing and maintenance applications. Specifications diverge from food-contact standards toward OSHA-compliant material safety.
Food Service anchors volume scale. Events command margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's urban food service corridors outpace German institutional procurement volumes, while U.S. pulp cost volatility diverges from Southeast Asian supply chain dynamics.
Indonesia
Quick-service restaurant chains along the Jakarta-Bandung corridor drive compostable napkin adoption through centralized procurement mandates. BSN enforces local content rules on imported sanitary papers, creating compliance friction for foreign manufacturers. The Surabaya-Malang food service belt concentrates multi-location operator demand, enabling scale efficiencies for regional distributors.
United States
Integrated forestry assets across the southeastern states sustain raw material security for bleached softwood kraft production. FDA governs food-contact substance compliance under 21 CFR, requiring specialized regulatory affairs capacity. The Carolinas-Virginia pulp corridor anchors domestic manufacturing against Asian import competition.
Germany
EU REACH chemical additive restrictions accelerate converter migration toward validated alternative chemistries in pulp bleaching. The EU Single-Use Plastics Directive forces material transitions across food service channels. The Rhine-Ruhr industrial cluster hosts specialized away-from-home dispensing system manufacturers.
Japan
Premium household tiers absorb reinforced quilted constructions with moisture retention features. METI standards shape product safety and quality benchmarks for domestic consumption. The Kansai manufacturing belt around Osaka concentrates airlaid nonwoven production for upscale hospitality applications.
Brazil
Eucalyptus pulp supply concentration exposes converters to freight-driven cost spikes in bleached kraft grades. ANVISA regulates food-contact materials for domestic and export markets. The São Paulo state industrial corridor hosts tissue converting operations serving Latin American distribution networks.
Disposable Napkins Market Competitive Environment
North American producers anchor one tier; European specialists hold certification-intensive positions in away-from-home systems. The vendor base separates into three strategic archetypes: integrated forestry-pulp converters, regional dispensing solution providers, and premium household brand operators. Capacity expansion and compostability certification convergence represent the dominant competitive vectors.
Among U.S.-based integrated operators, Kimberly-Clark Corporation occupies a position exemplifying captive pulp supply advantages. Swedish-based Essity represents the European away-from-home archetype through specialized dispensing system integration. Japanese fabricators including Kao Corporation and Unicharm Corporation exemplify premium-tier household positioning with reinforced construction technologies.
| Leading Market Players |
|---|
| Kao Corporation |
| Edgewell Personal Care Company |
| Kimberly-Clark Corporation |
| Ontex |
| Johnson & Johnson |
| Procter & Gamble |
| Hengan International Group |
| Essity |
| Unicharm Corporation |
| Others |
Value Chain & Pricing Dynamics
EU REACH chemical additive restrictions gate qualified supply for bleached softwood kraft grades and reserve premium-tier pricing access to converters with validated alternative chemistries and extended migration testing documentation.
Pricing Analysis
Capacity additions in Southeast Asian pulp markets are reshaping price floors for economy-tier paper napkins while premium grades retain margin insulation through compostability certification. Three-tier pricing structure across premium, standard, and economy levels separates certified food-contact grades from industrial-use specifications and price-sensitive bulk procurement. Pricing pressure stems from Brazilian and Scandinavian softwood pulp freight volatility transmitting into converter cost bases. Quick-service restaurant chains exhibit highest price sensitivity through centralized volume tenders, while upscale hospitality buyers absorb premiums for dispensing-integrated solutions.
Supply Chain Analysis
Bleached softwood kraft supply rests on Brazilian eucalyptus plantations, Scandinavian pulp mills, and southeastern U.S. integrated forestry assets. Raw material dependencies span wood chip supply contracts, chlorine-free bleaching chemicals, and food-contact compliant process aids. Single-source vulnerability concentrates in premium kraft grades where Brazilian and Nordic suppliers control merchant market availability. Distribution runs through B2B procurement platforms for Indonesian institutional buyers and traditional wholesaler networks for fragmented food service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where compostability certification convergence between EU OK Compost and US BPI standards pulls procurement specifications toward premium-grade suppliers with integrated documentation capabilities.
For Market Incumbents: Anchor raw material security through captive forestry assets or long-term offtake agreements with Brazilian eucalyptus suppliers to insulate against freight-driven cost spikes. Defend market position by accelerating dispensing system integration capabilities that lock in away-from-home operator contracts through bundled service models. Prioritize regulatory affairs capacity investment to navigate FDA 21 CFR compliance timelines that mid-tier converters struggle to staff. For New Entrants and Emerging Players: The price-point gap between premium compostable grades and economy-tier imports creates white-space opportunity for mid-market converters with regional pulp partnerships. Target Indonesia's Surabaya-Malang food service belt where BSN local content rules disadvantage foreign manufacturers but create entry paths for domestic production partnerships. Pursue go-to-market positioning through specialized B2B platforms that consolidate procurement for multi-location restaurant chains seeking direct manufacturer relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional dispensing solution providers because platform consolidation among Indonesian institutional buyers shifts negotiation leverage toward integrated certification documentation holders. Long-term viability favors converters with backward integration into pulp supply or forward integration into dispensing system manufacturing. Watch composting infrastructure build-out rates in Southeast Asian urban corridors as the inflection indicator for certified biodegradable grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Compostability Certification Investment | EU REACH Annex XVII updates force 8-14 month validation timelines that certified converters exploit for pricing power. |
| Backward Integration into Pulp Supply | Kimberly-Clark's southeastern U.S. forestry assets demonstrate raw material security against Asian import competition. |
| Dispensing System Integration | Essity's away-from-home bundled solutions lock in operator contracts through combined napkin-dispenser-waste service models. |
| B2B Platform Direct Access | Indonesian procurement directors migrating spend to specialized digital marketplaces enable manufacturer bypass of traditional distributors. |
| Regional Production Footprint | Jakarta-Bandung corridor concentration allows compliance with BSN local content rules while serving urban food service demand. |
Study Parameters
Multiple input streams — pulp procurement directors at converting operations, regulatory affairs specialists navigating FDA and REACH frameworks, and B2B platform operators serving Indonesian institutional buyers — were reconciled against secondary validation from customs trade data, SEC filings of integrated forestry operators, and compostability certification registries. Primary fieldwork captured procurement mandate specifications from quick-service restaurant chains and away-from-home dispensing system deployments. Bottom-up volume modeling triangulated against top-down macroeconomic absorption rates.
Historical volume trajectories cross-referenced against panel input from pulp cost forecasters and food service procurement directors shaped the analytical framework across the analysis window. Segmentation dimensions modeled include material chemistry tiers, end-use specification stringency, distribution channel structure, and regional regulatory cluster alignment. CAGRs derived from elasticity-adjusted demand projections incorporating pulp cost volatility transmission and certification adoption curves.
Caveats apply where municipal composting infrastructure deployment rates or EU REACH Annex XVII enforcement intensity could materially shift the outlook for certified biodegradable grade demand. A small set of named triggers — Indonesian BSN rule amendments, Brazilian pulp export tariff adjustments, and EU Single-Use Plastics Directive scope expansions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Folded Tissues Market
Household Items
GCC Gas Hobs Market
Household Items
Replacement Sheets Market
Household Items
Remote Control Holder Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Paper Towel Dispenser Market
Household Items
Thermos Bottle Market
Household Items
Toilet Cistern Blocks Market
Household Items
Electric Hedge Trimmer Market
Household Items
Global Wet Vacuum Cleaner Market
Household Items
US Coin-Operated Commercial Laundry Market
Household Items
Mosquito Trap Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Portable Steamers Market
Household Items
Home Use Air Purifiers Market