
 United States Barbeque Grill Market | 2026-2036
United States Barbeque Grill Market Size, Share, and Industry Trends Forecast 2026-2036
United States Barbeque Grill Market Outlook
Buyer concentration among residential outdoor cooking enthusiasts is hardening as suburban homeowners consolidate spending around premium, multi-functional grill platforms. Weber Inc. anchors the premium gas segment through durable stainless-steel construction and extensive dealer networks. Traeger Grills differentiates in pellet-fueled smart cooking, leveraging Wi-Fi-enabled temperature control to capture digitally native consumers. Blackstone Products dominates flat-top griddle configurations, extending beyond traditional grilling into breakfast and stir-fry applications.
A barbeque grill is a thermally insulated cooking appliance employing direct or indirect radiant heat, typically operating at temperatures between 250°F and 700°F depending on fuel source and burner configuration, designed for outdoor preparation of proteins, vegetables, and smoked goods. Gas grills command the largest revenue pool due to convenience and speed, though pellet grills represent the fastest-expanding category as wood-fired flavor and automated feed systems attract enthusiast buyers. Stainless steel remains the dominant material specification for frame and cooking surface construction, while smart technology integration—Bluetooth thermometers, app-controlled ignition, and automated pellet augers—commands margin premiums across all product tiers.
The Consumer Product Safety Commission enforces stability and thermal safety standards, while the EPA regulates volatile organic compound emissions from charcoal lighter fluids and wood pellet combustion. State fire codes in California and Texas impose additional clearance and ventilation requirements that influence built-in and freestanding design specifications. Stakeholders must monitor evolving propane cylinder regulations and emerging electrification incentives that could reshape fuel-type demand in municipal markets with clean-air mandates.
Market Dynamics
Smart connectivity integration and infrared burner technology are compressing replacement cycles among suburban homeowners, while the EPA's volatile organic compound regulations on charcoal lighter fluids accelerate fuel-type migration toward gas and pellet systems.
Growth Catalysts
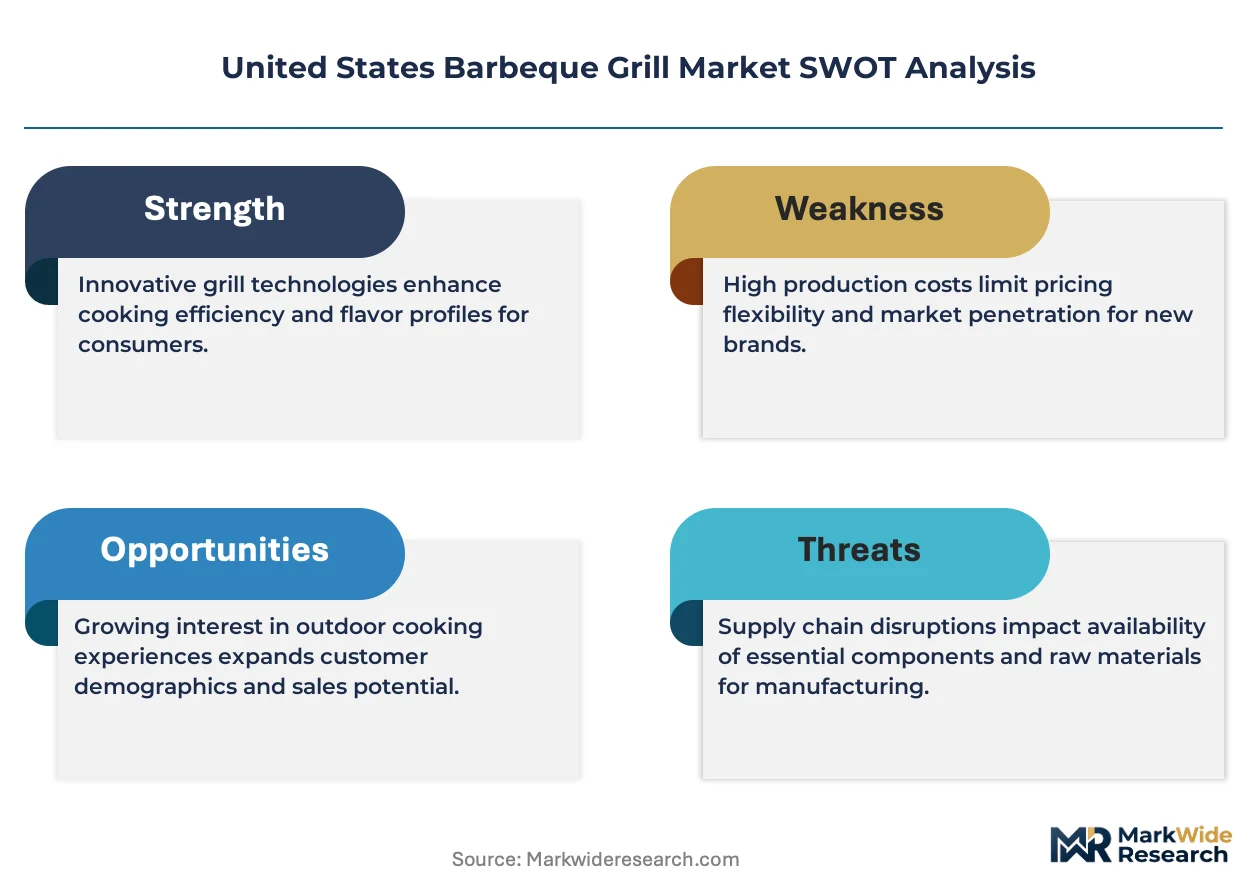
- Texas Climate Advantage:Year-round outdoor cooking viability in the Gulf Coast and Southwest sustains consistent demand for premium grill platforms and patio infrastructure investments.
- EPA Emissions Standards:Tighter volatile organic compound limits on charcoal lighter fluids push consumers toward cleaner-burning propane and wood pellet alternatives with automated ignition.
- Infrared Burner Technology:Ceramic infrared elements delivering 700°F+ searing temperatures attract enthusiast buyers seeking restaurant-quality crust formation on residential equipment.
Market Restraints
- Stainless Steel Input Volatility:Nickel and chromium price swings in commodity markets compress margins for domestic manufacturers reliant on 304-grade construction materials.
- Propane Cylinder Supply Concentration:Regional bottlenecks in cylinder recertification and exchange infrastructure limit rural market penetration beyond major metropolitan distribution hubs.
- California Fire Code Friction:Municipal clearance mandates for built-in installations add $800-$2,400 in contractor costs, suppressing freestanding-to-built-in upgrade conversion rates.
Strategic Opportunities
- Florida Retirement Migration:Empty-nest relocations to the Sunshine State generate first-time premium grill purchases among downsizing homeowners establishing new outdoor kitchens.
- Electrification Incentives:Municipal clean-air mandates in California and Pacific Northwest cities position electric infrared platforms for subsidy capture and zoning compliance.
- Wi-Fi Pellet Convergence:Integration of automated auger systems with smartphone temperature monitoring creates subscription-ready service layers around wood pellet fuel replenishment.
Industry Challenges
- Welding Certification Bottlenecks:Shortages of AWS-certified TIG welders for 304-grade stainless construction extend production lead times for premium gas grill manufacturers.
- Smart Firmware Fragmentation:Proprietary app ecosystems from Traeger, Weber, and emerging entrants create integration complexity for retailers managing multi-brand inventory and consumer support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Barbeque Grill Market |
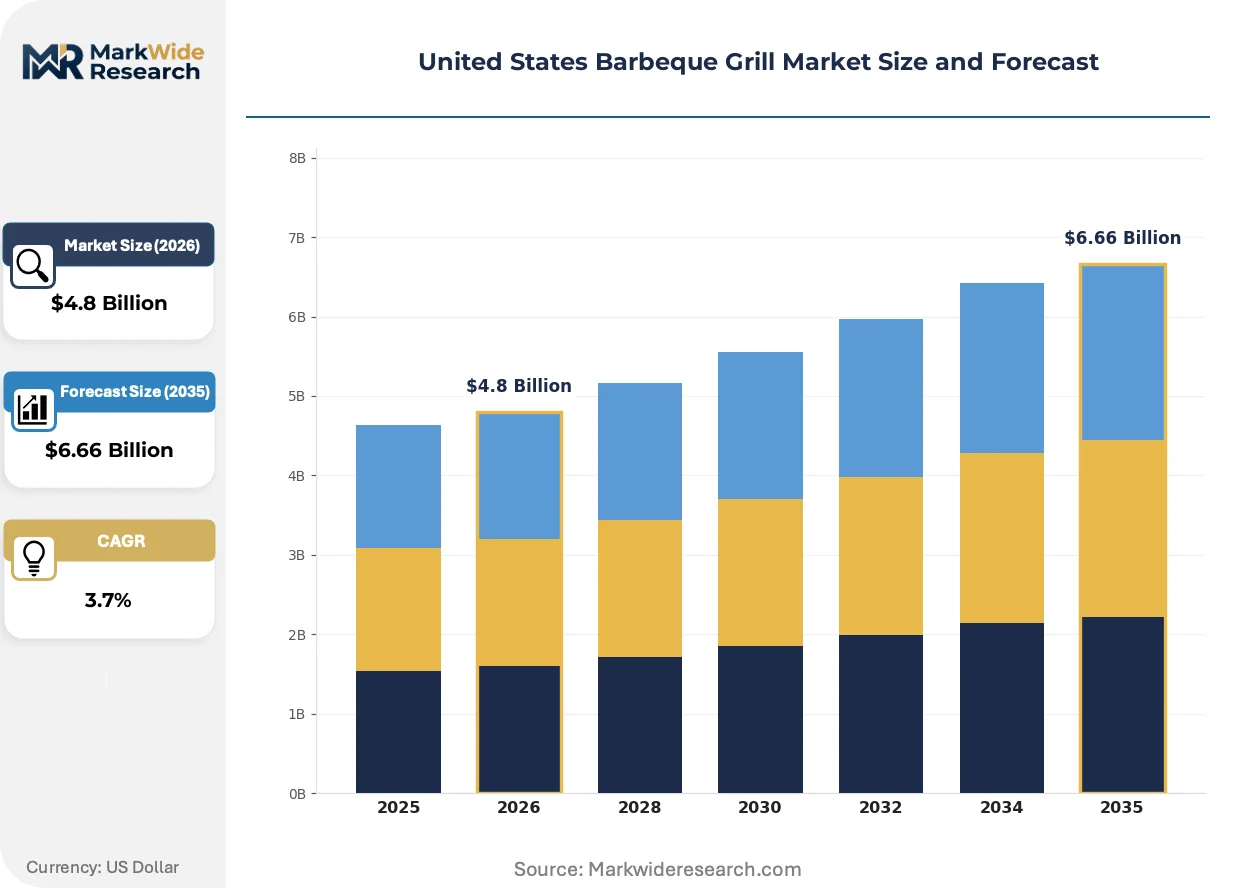
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Charcoal Grills, Gas Grills, Electric Grills, Pellet Grills End User: Residential Users, Commercial Kitchens, Food Trucks, Catering Services Material: Stainless Steel, Cast Iron, Aluminum, Ceramic Feature: Smart Technology, Portable Design, Infrared Cooking, Multiple Burners |
| Companies Covered | Napoleon Grills, The Coleman Company Inc., Weber Inc., Pit Boss Grills, Nexgrill Industries, Traeger Grills, Blackstone Products, Camp Chef, Char-Broil LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Barbeque Grill Market Strategic Shifts
Product development trajectories center on thermal precision automation and fuel-flexible platforms, with regulatory pressure and suburban lifestyle evolution acting as twin accelerants of hardware and software convergence.
Pellet grill technology with automated auger feed and PID temperature control is overtaking traditional offset smokers among barbecue competition participants and weekend enthusiasts alike. The 225°F-to-500°F stable temperature bands eliminate manual fire management, compressing the skill gap between novice and experienced pitmasters. This capability expansion is overtaking charcoal's historical dominance in low-and-slow cooking applications across Texas Hill Country and Kansas City metropolitan markets.
The Consumer Product Safety Commission's updated stability testing protocols for freestanding gas grills mandate tip-resistance thresholds that manufacturers address through wider wheelbase configurations and weighted tank enclosures. Compliance deadlines in 2024 forced engineering redesigns that added 8-12 pounds to shipping weights and altered retail packaging dimensions. California and Texas municipalities have adopted these federal standards into local fire codes, creating uniform enforcement geography that simplifies national product line planning.
Direct-to-consumer pellet fuel subscription models are restructuring aftermarket revenue capture, with automated replenishment algorithms triggered by cook-cycle data from Wi-Fi-enabled controllers. Big-box retail partnerships for cylinder exchange are losing share to doorstep delivery of compressed hardwood pellets in 20-pound weatherproof packaging. This channel rotation is most pronounced in Pacific Northwest and Upper Midwest metros where pellet grill penetration exceeds 35% of outdoor cooking appliance sales.
United States Barbeque Grill Market Segmentation
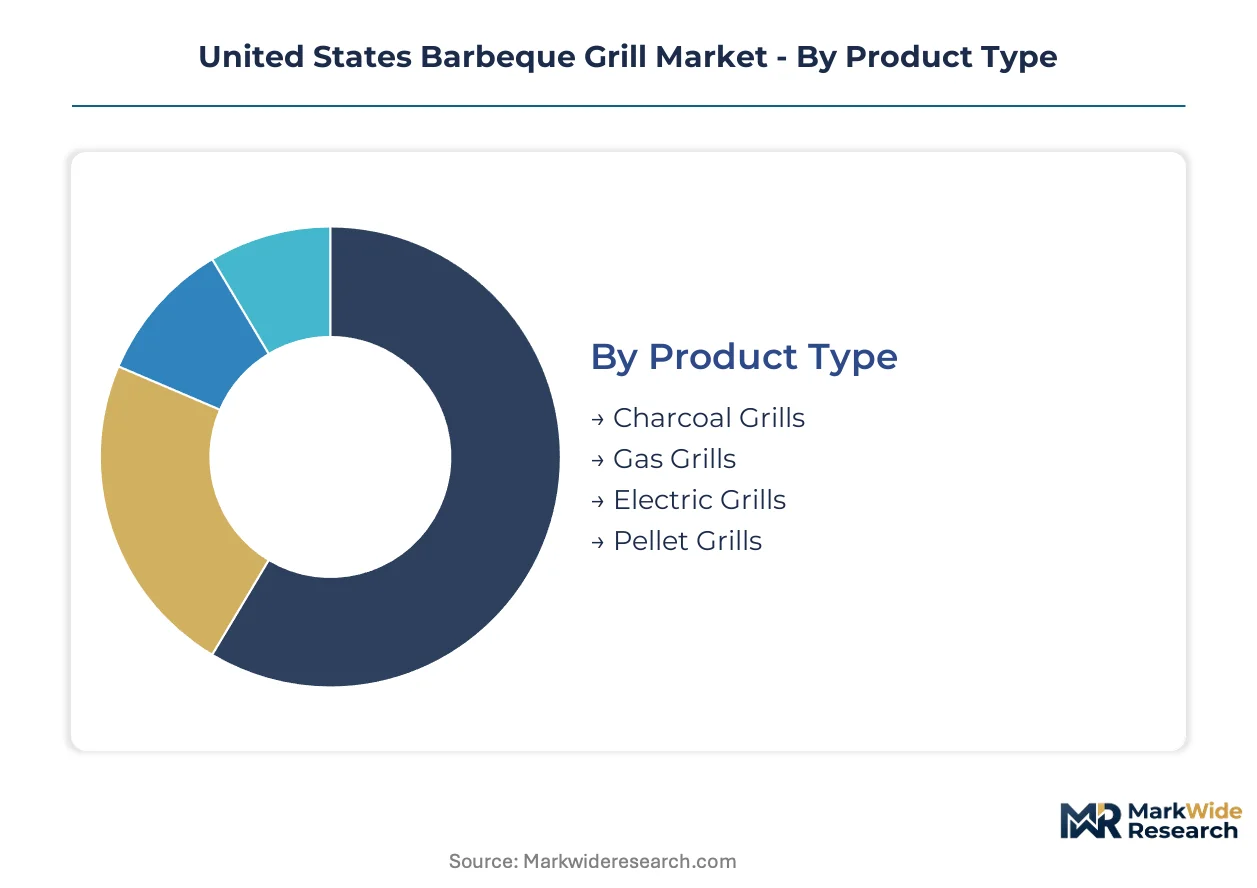
Grill manufacturers must navigate divergent buyer expectations across fuel preferences, construction materials, and connectivity tiers. Segmentation clarity determines whether product development resources flow toward mass-market propane platforms or enthusiast-grade pellet systems with Wi-Fi integration.
Product Type:
Gas grills anchor volume shipments through suburban hardware channels, while pellet systems command premium positioning through specialty retailers.
- Gas Grills:Propane and natural gas configurations utilizing 304-grade stainless burners dominate Texas and Florida residential markets. Convenience-focused suburban homeowners in year-round grilling climates sustain replacement cycles every five to seven years.
- Pellet Grills:Automated hardwood auger systems with PID temperature controllers attract barbecue competition participants and digitally native enthusiasts. Wi-Fi-enabled models from Traeger and competitors concentrate in Pacific Northwest and Upper Midwest metros where wood-fired flavor commands loyalty.
- Charcoal Grills:Traditional kettle designs persist among purists seeking high-heat searing capability.
- Electric Grills:Infrared elements suit apartment balconies and municipalities with open-flame restrictions.
Mature deployment sits with gas infrastructure in Sun Belt suburbs. Newer deployment is concentrated in pellet systems with subscription fuel replenishment.
End User:
Residential buyers drive ninety percent of unit volume, while commercial operators prioritize durability certifications and rapid recovery times.
- Residential Users:Suburban homeowners purchasing through big-box and direct-to-consumer channels represent the core revenue base. Patio-centric new construction in Florida retirement communities sustains first-time premium purchases among relocating empty-nesters.
- Commercial Kitchens:High-BTU stainless platforms with NSF certification serve steakhouse chains and independent barbecue restaurants. Texas Hill Country smokehouses demand 36-inch and larger configurations with rotisserie attachments.
- Food Trucks:Compact propane units with fold-down side tables maximize mobile kitchen efficiency.
- Catering Services:Towable smokers and modular grilling stations address off-site event volume.
Residential buyers cluster in replacement-driven suburban markets. Commercial deployment is expanding fastest in Texas metropolitan foodservice construction.
Material:
Stainless steel construction commands margin premiums, while cast iron retains heat retention advantages for searing surfaces.
- Stainless Steel:304-grade and 430-grade alloys dominate frame and hood fabrication, with marine-grade 316 specified for coastal Florida installations. Nickel price volatility directly impacts manufacturer cost structures.
- Cast Iron:Porcelain-enameled grates deliver superior heat retention and Maillard reaction performance for steak enthusiasts. Weber and competitors specify cast iron for cooking surfaces on premium gas platforms.
- Aluminum:Lightweight die-cast components reduce shipping costs for portable and entry-level models.
- Ceramic:Kamado-style insulated cookers from Big Green Egg and competitors enable 225°F-to-750°F temperature range.
Stainless deployment dominates built-in outdoor kitchen specifications. Ceramic adoption is climbing fastest among barbecue competition participants.
Feature:
Smart connectivity and infrared burner technology now separate premium tiers from commodity alternatives.
- Smart Technology:Bluetooth thermometers, app-controlled ignition, and cloud-connected temperature logging enable remote monitoring. Firmware fragmentation across Weber, Traeger, and emerging vendor ecosystems creates retailer support complexity.
- Infrared Cooking:Ceramic radiant elements achieving 700°F+ surface temperatures attract buyers seeking restaurant-quality crust formation. Texas and California enthusiasts drive adoption of sear station configurations.
- Portable Design:Collapsible legs and tabletop configurations address camping and tailgating applications.
- Multiple Burners:Three-to-six burner layouts enable zone cooking for direct and indirect heat management.
Multiple burner layouts represent mature standard configurations. Infrared integration is gaining share fastest among premium gas grill upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters along three distinct climatic and demographic corridors, with suburban patio infrastructure investment driving replacement cycles and premium-tier upgrades across distinct state-level markets.
Texas
Hill Country and Gulf Coast metropolitan areas sustain year-round outdoor cooking viability, with barbecue competition culture and steakhouse dining norms reinforcing equipment quality expectations. Municipal fire codes in Austin and Houston impose clearance mandates that shape built-in installation specifications. Dallas-Fort Worth anchors wholesale distribution networks serving the Southwest.
California
Bay Area and Los Angeles basin consumers drive smart connectivity adoption, with Silicon Valley proximity accelerating Wi-Fi-enabled temperature control penetration. South Coast Air Quality Management District regulations restrict open-flame appliances in designated non-attainment zones. Sacramento and San Diego concentrate specialty retail channels for pellet-fueled platforms.
Florida
Retirement migration to Tampa, Orlando, and Southwest Florida generates first-time premium purchases among downsizing homeowners establishing outdoor kitchens. State building codes mandate wind-load ratings for freestanding equipment in coastal counties. Miami-Dade and Broward counties represent the densest concentration of marine-grade stainless steel specifications.
Pacific Northwest
Seattle and Portland metropolitan areas exhibit the highest pellet grill penetration rates nationally, with wood-fired flavor preferences and environmental consciousness converging. Washington State Department of Ecology guidelines influence cleaner-burning fuel-type selection. Boise and Spokane extend distribution reach into Mountain West markets.
Southeast
Atlanta and Charlotte suburbs replicate Texas-style patio-centric construction patterns, with humidity-resistant material specifications gaining priority. Georgia and North Carolina state propane regulations govern cylinder exchange infrastructure development. Nashville and Raleigh-Durham emerge as secondary growth nodes for premium gas grill replacement demand.
United States Barbeque Grill Market Competitive Environment
Midwestern and Southern producers anchor the mass-market tier; West Coast specialists hold the connected-equipment segment. The vendor base exhibits moderate concentration, with three to four national brands commanding hardware channel shelf space while regional fabricators serve specialty barbecue retailers. Two strategic archetypes dominate: vertically integrated stainless-steel manufacturers controlling burner fabrication, and platform-agnostic software developers licensing temperature-control firmware across hardware brands. Capacity expansion and direct-to-consumer channel development represent the prevailing competitive vectors.
Within the premium gas segment, Weber Inc. and Napoleon Grills occupy positions defined by dealer network density and construction material specifications. Traeger Grills exemplifies the connected-pellet archetype, with its geographic origin signaling West Coast technology integration priorities. Nexgrill Industries and Char-Broil LLC represent scale-driven fabrication models serving big-box retail channels with multi-burner configurations at accessible price points.
| Leading Market Players |
|---|
| Napoleon Grills |
| The Coleman Company Inc. |
| Weber Inc. |
| Pit Boss Grills |
| Nexgrill Industries |
| Traeger Grills |
| Blackstone Products |
| Camp Chef |
| Char-Broil LLC |
| Others |
Value Chain & Pricing Dynamics
Wi-Fi-enabled temperature control integration is compressing cost economics for premium manufacturers while simultaneously concentrating supply leverage among semiconductor-integrated controller suppliers. This technology shift forces hardware producers to absorb firmware licensing costs or pursue in-house development, reshaping margin structures across gas and pellet grill tiers.
Pricing Analysis
Volume shipments cluster in mass-market propane configurations while margin capture concentrates in connected pellet platforms with subscription fuel bundling. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel construction grades and smart feature inclusion. Pricing pressure stems from nickel and chromium commodity volatility squeezing 304-grade fabrication costs. Mass-market suburban buyers exhibit highest price sensitivity, while barbecue competition enthusiasts accept premium positioning for PID-controlled precision.
Supply Chain Analysis
AWS-certified TIG welder qualification gating constrains domestic production capacity for premium stainless platforms. Manufacturing concentrates in China, Mexico, and domestic Midwest fabrication facilities. Raw material inputs hinge on Indonesian nickel ore, South African chromium, and domestic 304-grade stainless sheet. Single-source vulnerability sits with ceramic infrared burner element suppliers in Germany and Japan. Distribution runs through big-box retail partnerships and direct-to-consumer pellet fuel subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive control over hardwood pellet production and Wi-Fi controller firmware development to defend margin erosion from commodity volatility and licensing fees.
For Market Incumbents: Lock in certified welding capacity through apprenticeship pipeline investments and exclusive supplier agreements. Secure long-term stainless steel offtake contracts indexed to nickel futures. Traeger-style connected-platform entrants threaten dealer-dependent gas grill incumbents through direct-to-consumer fuel subscription models. For New Entrants and Emerging Players: Specialty barbecue retailers represent the most accessible channel partner type for establishing premium positioning without big-box slotting fee barriers. Target Florida retirement migration corridors with compact electric infrared platforms for balcony-constrained empty-nesters. White-space exists in marine-grade 316 stainless specifications for coastal hurricane-zone installations. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by outdoor living conglomerates seeking smart appliance portfolios. Long-term viability favors vertically integrated pellet producers with captive hardwood supply and subscription revenue streams. Watch AWS welding certification graduation rates as inflection indicator for domestic premium manufacturing capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Pellet Fuel Subscription Launch | Traeger's replenishment algorithms create recurring revenue capture beyond hardware margins. |
| Marine-Grade Stainless Certification | Florida coastal building codes mandate 316 alloy specifications for wind-load compliance. |
| In-House Firmware Development | Proprietary temperature control ecosystems reduce licensing dependency on third-party chip suppliers. |
| AWS Welder Pipeline Investment | Domestic fabrication capacity constraints favor producers with captive certified labor pools. |
| Electric Infrared Platform Expansion | California South Coast Air Quality Management District restrictions position zero-emission alternatives for subsidy capture. |
Study Parameters
Document review covered EPA emissions filings, Consumer Product Safety Commission stability test protocols, and state fire code databases, complemented by interviews with product development executives at grill manufacturers, category buyers at home improvement retailers, AWS-certified welding instructors, and hardwood pellet mill operators. Secondary validation drew from customs import records for stainless steel sheet, propane cylinder exchange infrastructure reports, and barbecue competition association membership data. Bottom-up shipment estimates triangulated against top-down consumer expenditure surveys.
Unit volume and value projections across the analysis window reflect segment-level modeling of gas, pellet, charcoal, and electric configurations by construction material tier and smart feature inclusion. CAGRs were derived from replacement cycle analysis, new household formation rates in target geographies, and technology adoption S-curves for Wi-Fi-enabled controllers. Industry-specific inputs incorporated nickel price volatility scenarios and municipal electrification incentive program announcements.
Caveats apply where EPA volatile organic compound regulation tightening or propane cylinder recertification infrastructure bottlenecks could materially shift the outlook. Forecasts reflect assumptions regarding suburban patio construction trends and retirement migration patterns. A model refresh is warranted upon material change in AWS welding certification throughput or hardwood pellet supply consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Car Air Freshener Market
Household Items
Canada Digital Showers Market
Household Items
Global Electronic Bidet Seats Market
Household Items
Compressed Tablet Towel Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Neck Pillows Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Air Care Market
Household Items
Global Sports Bottle Market
Household Items
Electric Shoe Polisher Market
Household Items
Party Supplies Market
Household Items
Air Freshener Market
Household Items
Smart Pool Skimmer Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Global Disposable Toilet Seat Covers Market