
 Water Purifier Market | 2026-2036
Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Water Purifier Market Intelligence
Manufacturing expansion in Southeast Asia, particularly Vietnam and Thailand, is fragmenting the established production landscape. A. O. Smith Corporation leverages its strong brand recognition in North America and China to maintain its market position. In contrast, Coway Co., Ltd. specializes in a service-oriented rental model that dominates the South Korean market. Pentair PLC competes across a wide range of residential and commercial applications with its diverse product portfolio.
A water purifier is a device designed to remove biological contaminants, suspended solids, and chemical impurities from water. These systems employ multi-stage filtration, often combining technologies like reverse osmosis membranes with a pore size under 0.0001 microns and UV sterilization lamps. The primary purpose is to render water potable and safe for human consumption. Reverse Osmosis (RO) systems command the largest share due to their high effectiveness, while the residential customer type continues to be the primary volume driver.
Product standards are influenced by a matrix of national and international regulations. The U.S. Environmental Protection Agency (EPA) sets contaminant limits, while certifications like NSF/ANSI 42 and 53 provide performance benchmarks recognized across North America. In parallel, compliance with China's GB standards is mandatory for market entry there. Success hinges on developing products that can meet these divergent regional certification requirements efficiently.
Market Dynamics
The market's primary dynamic is the tension between the need for globally standardized product platforms and the reality of fragmented regional certification requirements. This forces manufacturers to balance economies of scale in production with the high cost of region-specific product validation and compliance.
Growth Catalysts
- Rising Health Consciousness:Heightened consumer awareness regarding waterborne diseases and contaminants, particularly in developing nations like India, is a primary demand driver for residential purification systems.
- Regulatory Mandates:Stricter governmental regulations, such as China's GB standards for drinking water quality, compel both municipalities and consumers to invest in advanced filtration technologies.
- Membrane Technology Advances:Continuous improvements in reverse osmosis membrane efficiency and cost reduction are making highly effective RO systems more affordable and accessible to a broader residential customer base.
Market Restraints
- High Initial Capital Outlay:The significant upfront cost of multi-stage RO and UV purifiers remains a substantial barrier to adoption for price-sensitive households in emerging economies.
- Water Wastage in RO Systems:Conventional reverse osmosis technology discards a considerable amount of water as brine, creating environmental concerns and regulatory scrutiny in water-stressed regions.
- Divergent Certification Standards:The need to comply with a matrix of different standards, like NSF/ANSI in North America and local rules elsewhere, complicates product design and delays market entry.
Strategic Opportunities
- IoT and Service Integration:The convergence of IoT sensors with purifiers enables predictive maintenance, filter life monitoring, and new subscription-based business models centered on guaranteed water quality.
- Expansion in Southeast Asia:Markets such as Vietnam and Thailand present significant growth potential due to rapid urbanization, a rising middle class, and inadequate public water infrastructure.
- Portable and Faucet-Mounted Devices:Development of smaller, non-electric, and portable purification solutions can unlock demand from renters, students, and consumers in areas with unreliable electricity.
Industry Challenges
- After-Sales Service Network:Establishing a widespread and skilled service network for installation, troubleshooting, and timely filter replacement is a major operational hurdle, especially in geographically diverse markets. *Component Sourcing Complexity: Managing a global supply chain for critical components like membranes and UV lamps that meets varied international material safety regulations, such as the EU's RoHS directive, is increasingly complex.
Report Scope
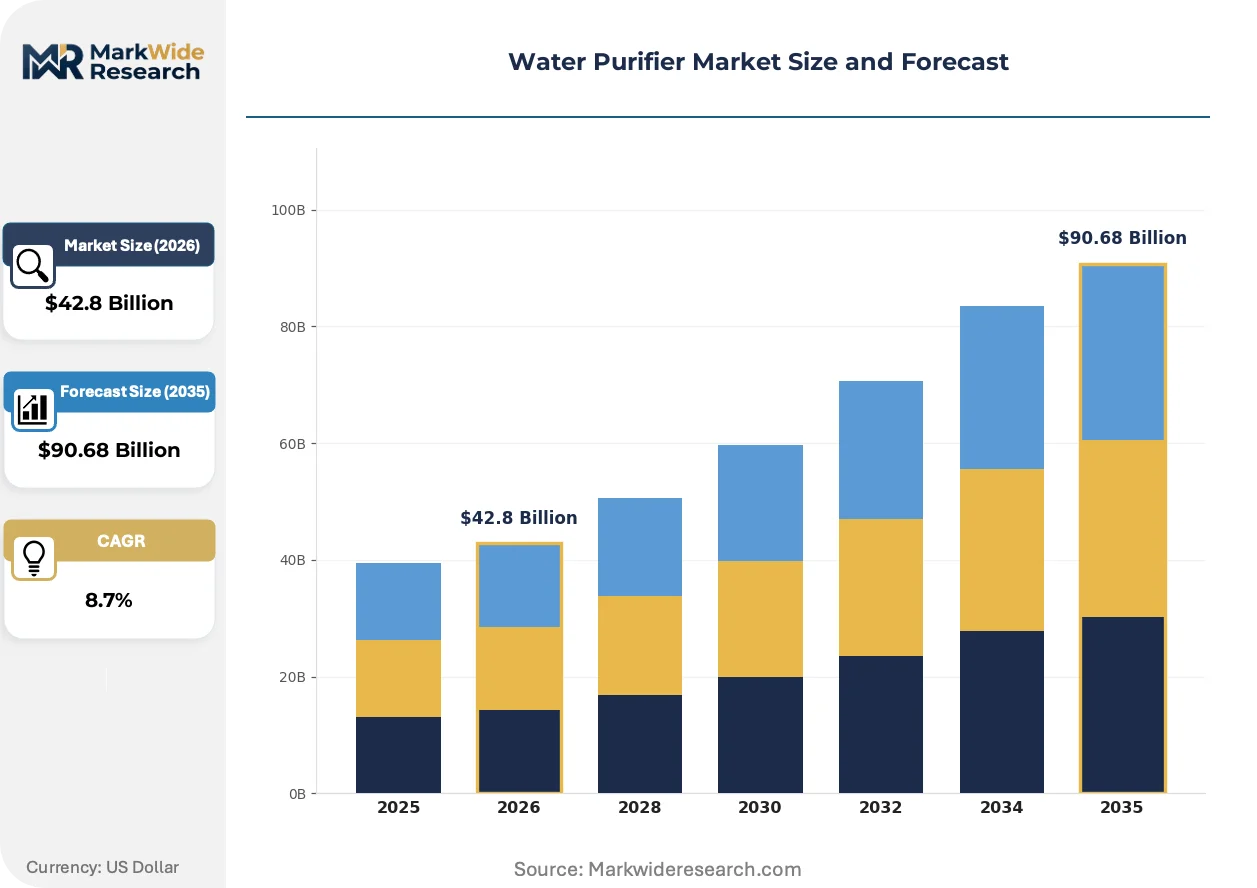
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Purifier Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $90.68 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Ultraviolet, Activated Carbon, Ceramic, Ion Exchange, Alkaline Technology: Membrane Filtration, Electrochemical, UV Sterilization, Activated Carbon Adsorption, Mechanical Filtration, Biological Treatment Installation: Under Sink, Countertop, Wall Mounted, Portable, Faucet Mounted, Whole House Customer Type: Residential, Commercial, Educational Institutions, Hospitality, Healthcare Facilities, Government Agencies |
| Companies Covered | Pentair PLC, A. O. Smith Corporation, Culligan International, Brita GmbH, Coway Co., Ltd., Eureka Forbes, LG Electronics, Panasonic Corporation, Kent RO Systems Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Purifier Market Strategic Shifts & Innovations
The pursuit of superior filtration efficacy and digital connectivity is reshaping product development, moving the value proposition beyond simple contaminant removal. This evolution transforms purifiers from standalone appliances into integrated components of a connected and health-conscious home environment, emphasizing performance data and user convenience.
Advanced sensor arrays integrated into filtration systems provide real-time monitoring of water quality parameters like Total Dissolved Solids and pH. The residential segment, particularly in technologically advanced urban centers, is adopting these smart features. This integration of data feedback is collapsing the distinction between a simple appliance and a connected health device, creating new value propositions around performance transparency.
India's Bureau of Indian Standards (BIS) continues to tighten its certification requirements for water purifiers, mandating specific performance levels for contaminant removal and material safety. This policy elevates the overall quality floor by compelling manufacturers to invest in R&D and phase out non-compliant models. The unorganized, low-cost assembler segment faces significant pressure, while brands committed to BIS certification gain a clear market advantage.
A notable consumer preference shift is occurring from one-time product purchases toward subscription-based rental models. This service-oriented approach, which bundles the device with installation, regular maintenance, and filter replacements, disrupts the traditional retail sales channel. The trend is most prominent in dense urban areas across Asia, where convenience and guaranteed performance are highly valued by middle-class households.
Water Purifier Market Segmentation
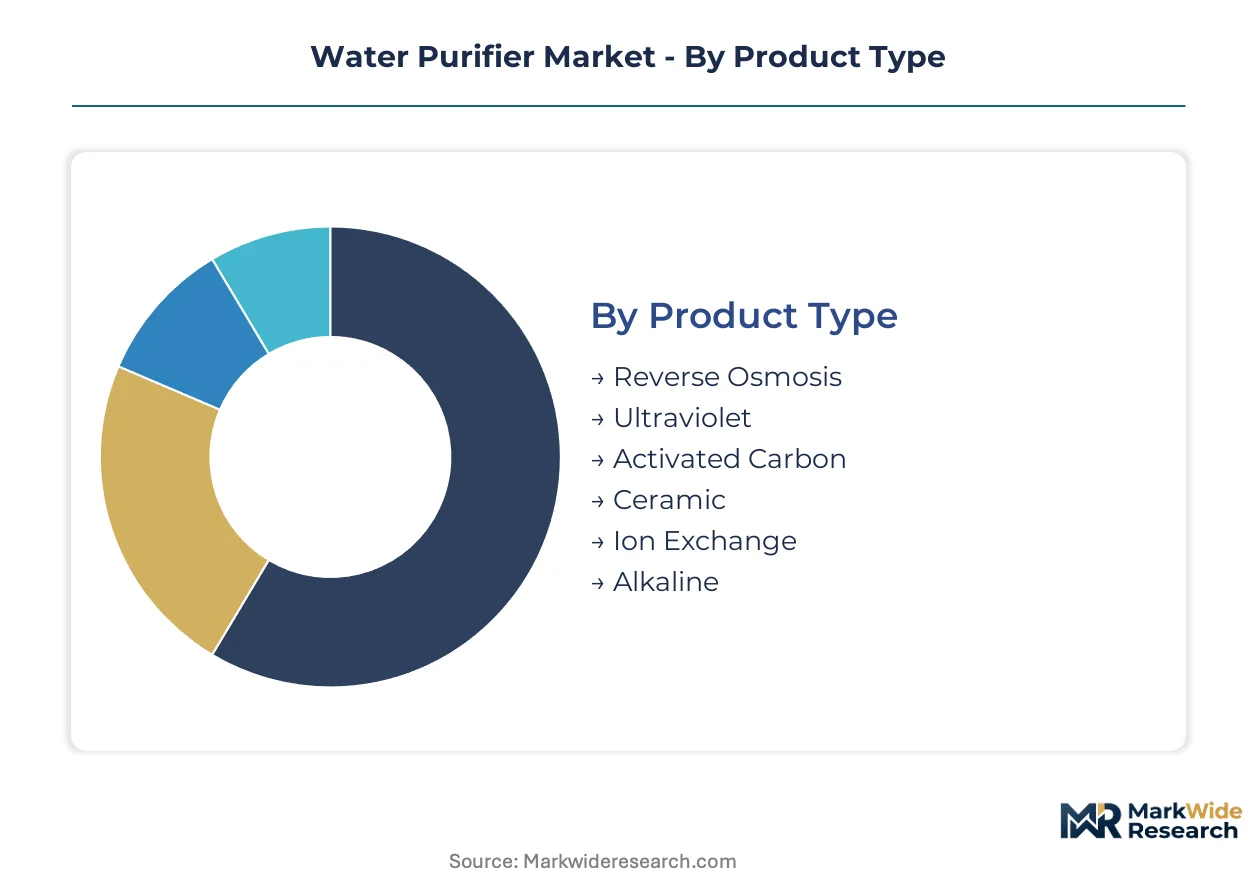
The water purifier market segmentation delineates the varied technological solutions and application areas driving demand across different user groups. This granular view highlights specific consumer needs and regulatory requirements shaping product development and market penetration strategies.
Product Type:
The product type segmentation reveals a mature core alongside emerging specialized solutions.
- Reverse Osmosis:These systems employ semi-permeable membranes with a pore size under 0.0001 microns to remove dissolved solids, bacteria, and viruses. Demand concentrates heavily in residential households in countries like India, driven by health consciousness and concerns over waterborne diseases.
- Ultraviolet:UV purifiers utilize germicidal UV lamps to inactivate bacteria, viruses, and other microorganisms without altering water chemistry. Residential consumers in urban centers, particularly those seeking chemical-free purification, show strong preference for these systems.
- Activated Carbon:Activated carbon filters effectively remove chlorine, sediment, volatile organic compounds, and improve water taste and odor.
- Ceramic:Ceramic filters provide micro-filtration, physically blocking sediment, bacteria, and cysts, often used in remote areas or for portable solutions.
- Ion Exchange:These systems replace undesirable ions like calcium and magnesium with less harmful ones, primarily used for water softening and heavy metal removal.
- Alkaline:Alkaline purifiers adjust water pH levels, often marketed for perceived health benefits associated with higher pH water.
Reverse Osmosis retains volume leadership; Alkaline holds the steepest expansion curve.
Technology:
Technology segmentation highlights diverse approaches to contaminant removal across various applications.
- Membrane Filtration:This category encompasses technologies like Reverse Osmosis, Ultrafiltration, and Nanofiltration, using physical barriers to remove impurities based on pore size. Commercial and industrial sectors, alongside residential users, rely on these for high purification standards.
- UV Sterilization:UV sterilization technology employs specific wavelengths of ultraviolet light to disrupt the DNA of microorganisms, rendering them harmless. Healthcare facilities and residential consumers prioritize this method for effective, chemical-free disinfection.
- Electrochemical:Electrochemical methods utilize electricity to induce chemical reactions for contaminant removal, often applied in advanced oxidation processes for industrial wastewater.
- Activated Carbon Adsorption:This technology uses porous carbon to adsorb contaminants, effectively removing chlorine, organic chemicals, and improving taste and odor.
- Mechanical Filtration:Mechanical filtration systems physically block larger particles like sediment, rust, and debris through screens or fibrous media.
- Biological Treatment:Biological treatment methods use microorganisms to break down organic pollutants, primarily employed in larger-scale water treatment plants.
Membrane Filtration technologies command the largest market value; Electrochemical methods are rapidly gaining adoption.
Installation:
Installation methods cater to varied consumer convenience preferences and spatial limitations.
- Under Sink:These purifiers are installed beneath the kitchen sink, connected to the cold water line, often with a dedicated faucet for purified water. Residential consumers in developed markets prefer this for its concealed nature and high volume output.
- Wall Mounted:Wall-mounted units are affixed to a vertical surface, common in residential kitchens, particularly in countries like India, due to traditional preferences and ease of access for maintenance.
- Countertop:Countertop purifiers sit on the kitchen counter, offering easy installation and portability, suitable for renters or smaller living spaces.
- Portable:Portable devices are designed for on-the-go use, including water bottles with integrated filters or small, battery-operated units for travel and outdoor activities.
- Faucet Mounted:These small units attach directly to the existing kitchen faucet, providing basic filtration for drinking and cooking water.
- Whole House:Whole house systems are installed at the main water line entry point, treating all water entering the home for comprehensive protection.
Under Sink installations dominate in terms of market share; Portable devices show a significant increase in adoption rates.
Customer Type:
Customer type segmentation highlights the diverse volume requirements and regulatory compliance needs across user groups.
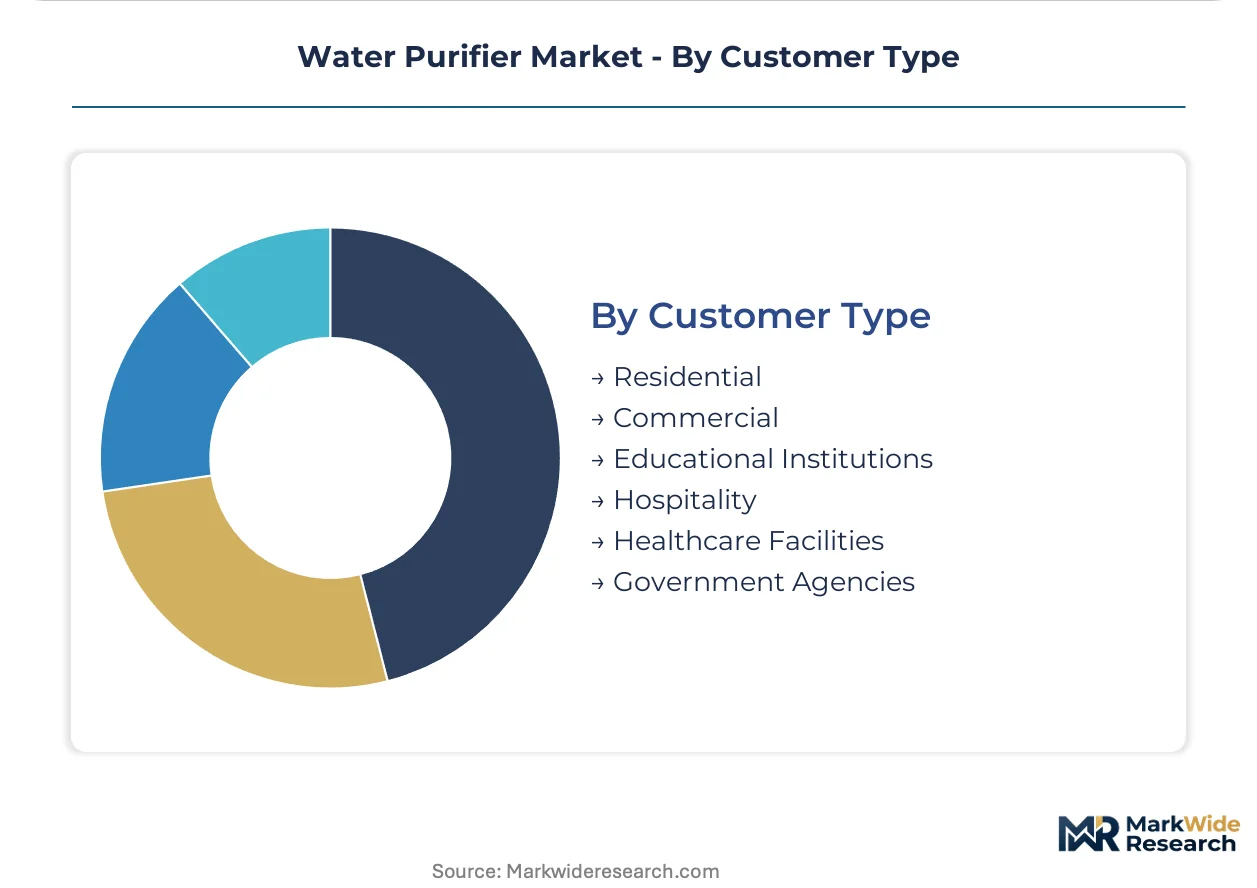
- Residential:This segment includes individual households purchasing purifiers for drinking and cooking water, driven by health consciousness and perceived tap water quality issues. Demand is particularly strong in countries like India and China, reflecting a rising middle class.
- Commercial:Commercial customers include offices, restaurants, retail establishments, and small businesses requiring purified water for employees, customers, or specific operational needs. Regulatory compliance and employee welfare are key drivers in this segment.
- Educational Institutions:Schools, colleges, and universities require water purifiers to ensure safe drinking water for students and staff, often driven by public health mandates.
- Hospitality:Hotels, resorts, and cafes invest in water purification to enhance guest experience and maintain brand image by providing high-quality drinking water.
- Healthcare Facilities:Hospitals, clinics, and laboratories demand highly purified water for patient care, sterilization, and sensitive medical equipment, adhering to stringent quality standards.
- Government Agencies:Government bodies purchase purifiers for public buildings, military facilities, and disaster relief efforts, ensuring safe water access in various contexts.
Residential customers represent the largest volume segment; Healthcare Facilities exhibit strong growth potential due to strict water quality mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing expansion in Southeast Asia, particularly Vietnam and Thailand, is fragmenting the established production landscape for water purifiers. This shift creates a dynamic environment where established markets and emerging economies both contribute to demand. India and China represent significant volume drivers, while regulatory frameworks shape market access.
India
India's market expansion stems from rising health consciousness and prevalent water quality issues. The Bureau of Indian Standards (BIS) continually tightens certification requirements for purifiers, elevating quality standards. Urban centers like Delhi-NCR concentrate significant demand, where middle-class households prioritize advanced purification systems.
China
China's substantial consumer base reflects a rising middle class and increasing focus on water safety. Compliance with China's GB standards is mandatory for all market entrants, ensuring product quality. The Yangtze River Delta region, including Shanghai, sees significant adoption of smart, IoT-enabled purification technologies.
South Korea
South Korea exhibits strong demand for water purifiers, driven by high urbanization and a preference for convenience. The Ministry of Environment establishes stringent water quality and appliance safety standards for household devices. Seoul's dense urban areas lead the adoption of subscription-based rental models, emphasizing guaranteed performance.
Vietnam
Vietnam presents significant growth potential due to rapid urbanization and concerns over public water infrastructure. The Ministry of Health sets national drinking water quality standards, influencing product development and market entry. Ho Chi Minh City and Hanoi are emerging as key markets for residential purification systems.
United States
United States consumers prioritize health consciousness and perceived tap water quality issues. The U.S. Environmental Protection Agency (EPA) sets strict contaminant limits, ensuring product efficacy. California and the Northeast corridor exhibit robust demand for NSF/ANSI certified purification systems.
Water Purifier Market Key Industry Players
Brand-driven global players and service-oriented specialists split the water purifier market, alongside diversified portfolio providers. The market exhibits a tiered structure, with established international brands competing against regional specialists and local assemblers. Companies pursue strategic partnerships to expand geographic reach and invest in R&D for smart, IoT-enabled features.
Among the brand-driven global players, A. O. Smith Corporation leverages its strong recognition across North America and China, anchoring its market position through established channels. Coway Co., Ltd. exemplifies the service-oriented model, dominating the South Korean market with its innovative rental-based offerings that prioritize convenience and guaranteed performance. Pentair PLC occupies a position as a diversified portfolio provider, catering to a wide range of residential and commercial applications with its extensive product offerings. These entities collectively represent the varied strategic approaches defining the competitive landscape, from brand-centric sales to service-driven subscriptions.
| Leading Market Players |
|---|
| Pentair PLC |
| A. O. Smith Corporation |
| Culligan International |
| Brita GmbH |
| Coway Co., Ltd. |
| Eureka Forbes |
| LG Electronics |
| Panasonic Corporation |
| Kent RO Systems Ltd |
| Others |
Cost & Logistics Intelligence
Manufacturing overcapacity in Southeast Asia influences supplier behavior, driving competitive pricing. This utilization dynamic shapes the overall pricing posture across the water purifier market.
Pricing Analysis
India's Bureau of Indian Standards (BIS) dictates the pricing tier structure, compelling manufacturers to invest in R&D for compliance. The market exhibits premium-mid-economy pricing differentiation, driven by certification levels and comprehensive after-sales service bundles. Pricing pressure stems from the proliferation of unorganized, low-cost assemblers, particularly in emerging economies. Residential households in price-sensitive regions represent the most sensitive buyers, while healthcare facilities prioritize performance over cost.
Supply Chain Analysis
Extended payment terms are common for component suppliers in the water purifier industry, particularly for manufacturers sourcing from Asia. Geographic supply concentration for critical components like reverse osmosis membranes and UV lamps centers heavily in China and, increasingly, Southeast Asia. Component sourcing complexity presents a structural risk, driven by varied international material safety regulations such as the EU's RoHS directive. Distribution runs through established retail channels, direct-to-consumer sales, and rapidly expanding service-oriented rental networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water purifier market presents a defensive-moat story, anchored by significant regulatory entrenchment. Compliance with diverse national and international standards creates high barriers to entry for new players.
For Market Incumbents:
Insulate core market share by deepening investment in IoT-enabled features and advanced sensor arrays, creating performance transparency. Expand service network capabilities, especially in diverse markets like India, to counter operational hurdles and differentiate from low-cost assemblers. Leverage certification investment, such as NSF/ANSI and GB standards, to reinforce brand trust and maintain pricing power against emerging entrants. Control over critical component supply, like advanced membranes, also limits competitor access.
For New Entrants and Emerging Players:
Underpenetration in rapidly urbanizing Southeast Asian markets like Vietnam and Thailand offers significant white-space opportunities. Target the residential segment with portable and faucet-mounted devices, suitable for renters and areas with unreliable electricity. A service-oriented, subscription-based model, bundling maintenance and filter replacements, provides a compelling go-to-market angle. Leverage digital channels for efficient customer acquisition and support in these regions.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upwards across the smart, IoT-enabled purifier sub-segment, indicating long-term viability for integrated solution providers. Target regional specialists with robust service networks or technology firms developing advanced sensor arrays and AI for predictive maintenance. The sustained tightening of certification requirements, such as India's BIS standards, serves as a crucial signal to watch for market consolidation. Investment in these areas promises durable returns over the next decade.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | This initiative fragments the established production landscape, reducing manufacturing costs for global players. |
| R&D in IoT and AI Integration | Advanced sensor arrays enable real-time water quality monitoring and predictive maintenance for residential users. |
| Strategic Partnerships for Service Networks | Collaborations expand after-sales service reach, particularly critical in geographically diverse markets like India. |
| Acquisition of Regional Specialists | Acquiring local players provides immediate market access and expertise in meeting varied regional certification requirements. |
| Global Rollout of Subscription Models | This shifts consumer preference from one-time purchases to recurring revenue streams, enhancing customer loyalty. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary insights were gathered from R&D directors, procurement managers, channel partners, and regulatory compliance officers across key markets. Secondary data sources included government water quality reports, filings from national standards bodies like India's BIS and the U.S. EPA, and industry association publications. A comprehensive bottom-up and top-down triangulation approach ensured data accuracy and consistency.
Forecast inputs considered include evolving water quality indices, urbanization rates, and consumer health consciousness across the analysis window. The analytical framework modeled market dynamics across product type, technology, installation, and customer type segments, alongside regional regulatory frameworks. Compound annual growth rates (CAGRs) were derived from historical data trends and projected future demand. Technological advancements in membrane efficiency also served as a key forecast input.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or consumer spending would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and the pace of technological innovation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Handheld Fans Market
Household Items
Scouring Pads Market
Household Items
Cat Hair Remover Market
Household Items
Car Air Freshener Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
United Kingdom Air Purifier Market
Household Items
Toilet Care Wipes Market
Household Items
Infuser Water Bottles Market
Household Items
Remote Control Holder Market
Household Items
Smart Connected Water Purifier Market
Household Items
Moving Supplies Market
Household Items
Electric Mop Market
Household Items
United States Commercial Bathroom Products Market
Household Items
Command Hooks Market
Household Items
Acrylic Aquarium Market
Household Items
Asia-Pacific Digital Showers Market