
 Global Nap Pod Market | 2026-2036
Global Nap Pod Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nap Pod Market Outlook
Leasing and subscription-based financing is fragmenting the competitive landscape for nap pod deployment, lowering capital barriers for mid-size employers and hospitality operators. MetroNaps leverages its airport lounge partnerships to sustain premium positioning in transit hubs. NapCabs GmbH anchors European deployment through modular pod suites designed for German railway stations. Sleepbox competes on manufacturing scale, while MinuteSuites differentiates through integrated booking platforms that control reservation flow across multiple U.S. airports.
A nap pod is a self-contained, ergonomically designed rest enclosure typically measuring 2-4 square meters, incorporating sound-dampening materials, adjustable lighting systems between 2000-3000K color temperature, and ventilation rated at 30-50 cubic feet per minute to enable brief sleep cycles in commercial environments. Office pods dominate current volume due to enterprise wellness budget expansion, while portable units represent the fastest-growing category as flexible workspace operators seek redeployable assets. Custom designs command the deepest margin pools, particularly in healthcare facilities requiring antimicrobial fabric surfaces and HIPAA-compliant acoustic privacy standards.
The U.S. Occupational Safety and Health Administration's indoor air quality guidelines and the EU's CE marking requirements for electrical furnishings jointly shape product certification pathways, with REACH compliance adding material traceability obligations for European sales. Japan's METI energy-efficiency standards for commercial equipment further constrain heating and ventilation specifications in that market. Stakeholders must monitor evolving building code interpretations across jurisdictions, as fire safety classifications for enclosed sleep structures remain inconsistently applied and could abruptly restrict installation eligibility in high-occupancy commercial buildings.
Market Dynamics
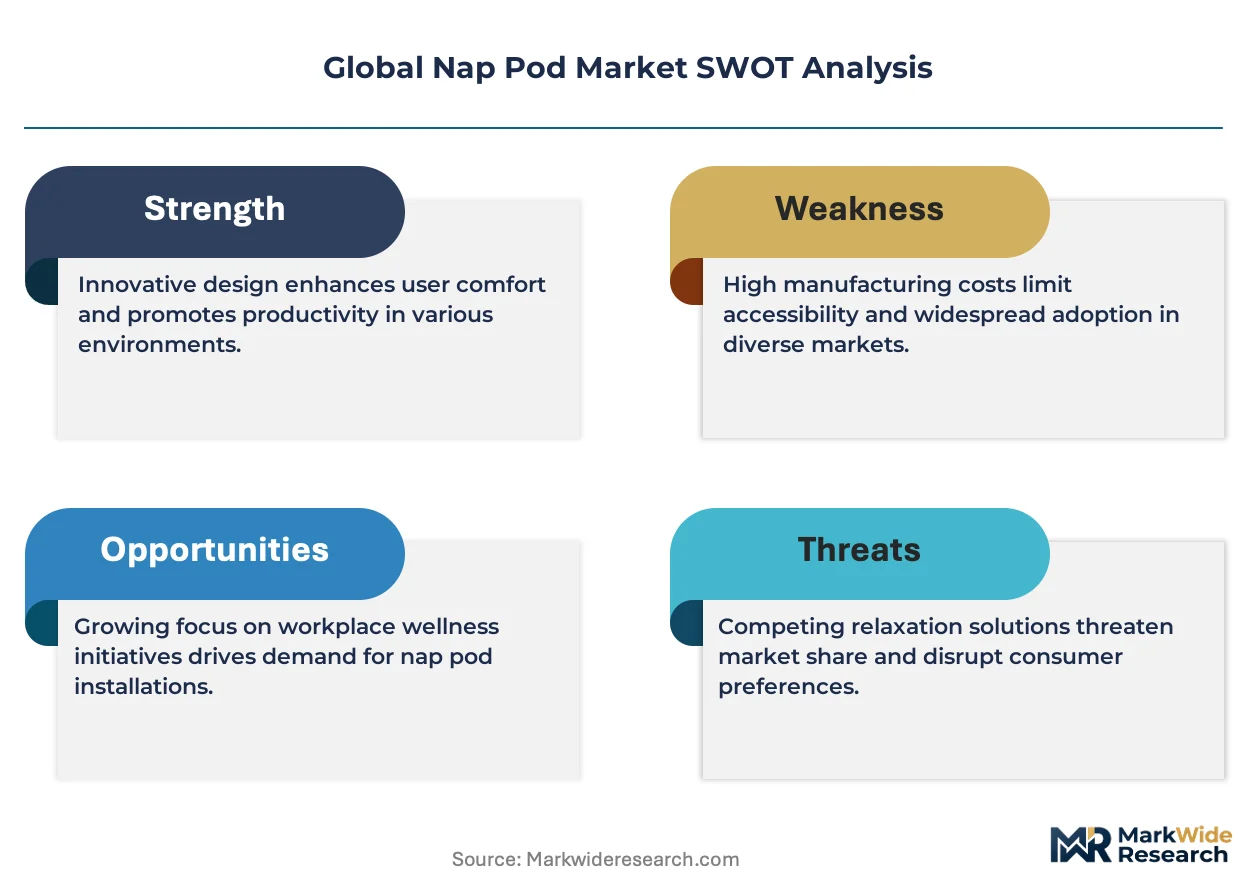
Leasing and subscription-based financing is fragmenting the competitive landscape for nap pod deployment, lowering capital barriers for mid-size employers and hospitality operators while reshaping how procurement decisions flow through enterprise wellness budgets.
Growth Catalysts
- EU Green Deal material mandates:The EU Green Deal's sustainability requirements are pushing manufacturers toward recycled fabric and certified wood construction, creating procurement preference for compliant suppliers.
- Tokyo office density:Japan's dense office districts and airport terminals sustain high installation rates as commercial real estate constraints intensify demand for compact rest solutions.
- OSHA indoor air quality guidelines:U.S. workplace safety standards are elevating ventilation specifications to 30-50 cubic feet per minute, driving specification upgrades across corporate wellness programs.
Market Restraints
- Fire safety classification inconsistency:Building code interpretations for enclosed sleep structures remain inconsistently applied across jurisdictions, abruptly restricting installation eligibility in high-occupancy commercial buildings.
- REACH material traceability costs:European chemical compliance adds documentation burdens and supplier qualification timelines that compress margin pools for imported components.
- Antimicrobial fabric input volatility:Healthcare-grade surface treatments face supply concentration in specialty textile suppliers, creating cost unpredictability for custom pod designs.
Strategic Opportunities
- Flexible workspace redeployability:Portable nap pod units represent the fastest-growing category as operators seek assets that transfer across locations without structural modification.
- German railway station modular suites:European transit infrastructure presents untapped deployment potential for pod suites designed around commuter dwell times.
- METI energy-efficiency incentives:Japan's commercial equipment standards create regulatory tailwinds for HVAC-integrated pods that exceed baseline thermal performance thresholds.
Industry Challenges
- HIPAA-compliant acoustic engineering:Healthcare facility deployments require specialized sound-dampening materials and privacy certifications that extend product development cycles.
- CE marking electrical furnishing pathways:European certification timelines for combined mechanical-electrical systems create working capital pressure during market entry phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nap Pod Market |
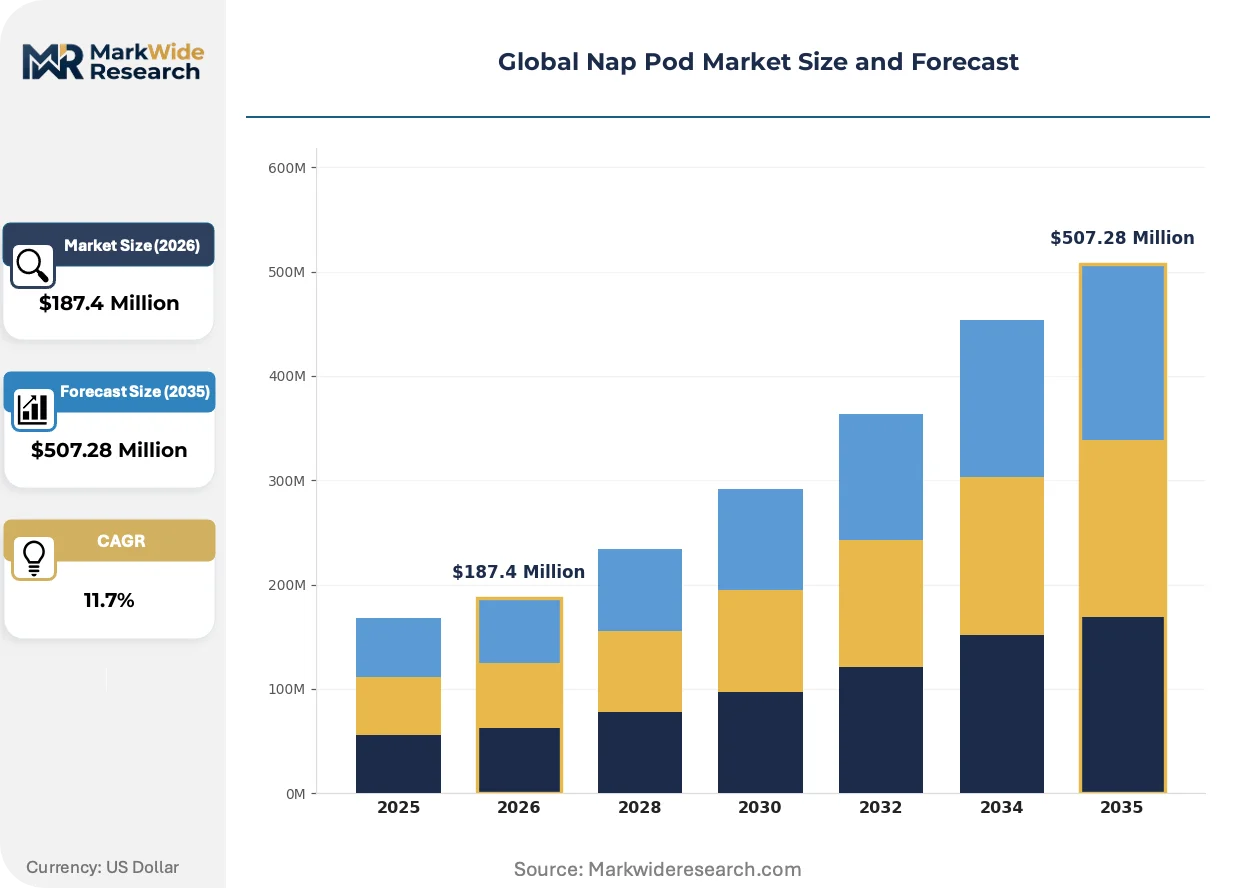
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Pod Suites, Office Pods, Custom Designs End User: Corporate Offices, Healthcare Facilities, Educational Institutions, Airports Material: Wood, Metal, Fabric, Plastic Size: Compact, Medium, Large, Extra Large |
| Companies Covered | NapCabs GmbH, MinuteSuites, MetroNaps, 9 Hours, SnoozeCube, Sleepbox, Podtime, Snooze at My Space, GoSleep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nap Pod Market Strategic Shifts
Integrated booking platforms and IoT-enabled pod management systems are actively compressing reservation friction and operational visibility gaps across distributed nap pod networks.
Sensor-embedded occupancy detection is digitizing how operators manage utilization rates and maintenance scheduling. Airport lounge operators and corporate campus managers are deploying these systems at accelerating pace. Real-time availability data is digitizing yield management practices that previously relied on manual tracking.
Japan's METI energy-efficiency standards for commercial equipment are constraining heating and ventilation specifications in that market. Manufacturers must redesign thermal management systems to comply with seasonal power consumption limits. Healthcare and hospitality segments in Japan are responding by specifying pods with demand-controlled ventilation and LED-only lighting arrays.
Enterprise buyers are consolidating vendor relationships around integrated wellness platform providers rather than standalone pod suppliers. Corporate procurement teams are displacing fragmented equipment purchases with multi-year service agreements that bundle installation, maintenance, and usage analytics. This consolidation is most visible across United States technology campuses where facilities teams prioritize single-contract accountability.
Global Nap Pod Market Segmentation
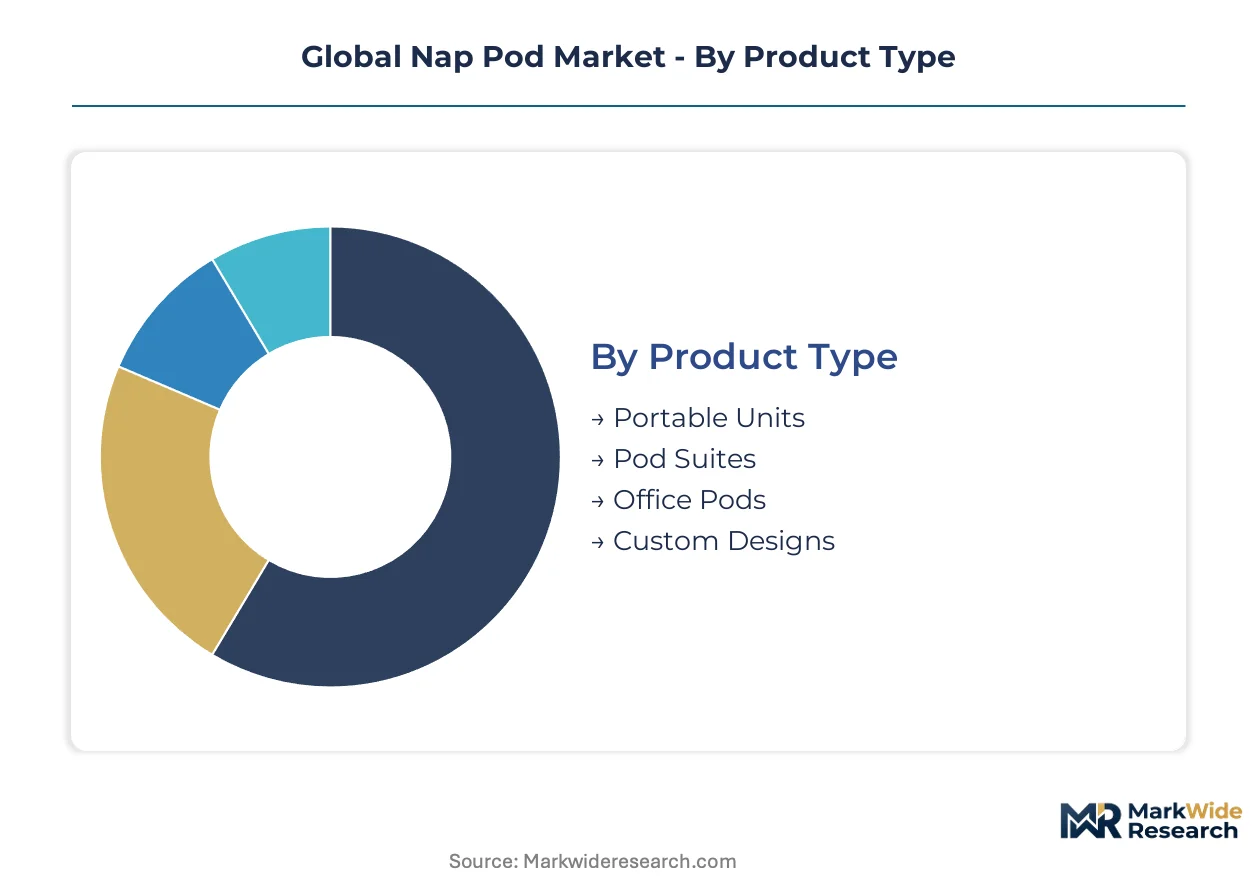
Nap pod segmentation reveals distinct service intensity profiles across product architectures, with modular and portable configurations demanding fundamentally different maintenance cadences and lifecycle support commitments than fixed installations.
Product Type:
After-sales service intensity varies sharply across product architectures, with permanently installed office pods requiring scheduled HVAC filter replacement and acoustic panel refurbishment while portable units prioritize rapid field swap-out protocols.
- Portable Units:These redeployable enclosures feature quick-disconnect electrical systems and wheeled bases enabling same-day relocation across co-working sites. Demand concentrates among flexible workspace operators in Germany and the Netherlands seeking assets that transfer between locations without structural modification. Their fastest expansion trajectory reflects the shift toward hybrid office models.
- Pod Suites:Modular multi-unit configurations designed for transit corridors and hospital wards incorporate shared ventilation manifolds and centralized booking interfaces. German railway stations anchor European deployment volumes as NapCabs GmbH scales platform-based service agreements. After-sales contracts bundle predictive maintenance analytics with component refresh cycles.
- Office Pods:Fixed-installation single-occupancy enclosures dominate current procurement volumes through enterprise wellness budget expansion.
- Custom Designs:Bespoke configurations for healthcare and aviation lounges command premium margins but extend engineering lead times.
By volume, Office Pods lead. By growth pace, Portable Units are ahead.
End User:
Customer procurement sophistication diverges markedly across verticals, with corporate facilities teams consolidating multi-year service agreements while healthcare administrators prioritize HIPAA-compliant acoustic certifications and antimicrobial surface protocols.
- Corporate Offices:United States technology campuses drive specification standards through integrated wellness platform procurement, bundling installation, maintenance, and usage analytics under single-contract accountability. Enterprise buyers favor pods with IoT-enabled occupancy detection and demand-controlled ventilation.
- Healthcare Facilities:Hospitals and clinics require specialized sound-dampening materials meeting privacy regulations alongside fabric surfaces treated with antimicrobial agents. Japan's dense urban medical districts sustain concentrated demand for compact rest solutions in nursing stations and visitor areas.
- Educational Institutions:University wellness centers and library installations in the United Kingdom and Australia represent emerging deployment channels with seasonal utilization patterns.
- Airports:Transit lounge operators leverage real-time availability data for yield management across distributed pod networks, with Tokyo Narita and London Heathrow sustaining premium positioning.
Corporate Offices capture the deepest contract values. Healthcare Facilities show the steepest specification complexity.
Material:
Supply chain configuration directly shapes margin durability, with EU Green Deal mandates accelerating supplier qualification timelines for recycled fabric and certified wood while metal and plastic face cost volatility from energy-intensive processing.
- Fabric:Acoustic textile surfaces rated for 30-50 cubic feet per minute ventilation compatibility dominate pod interior specifications, with REACH compliance adding traceability documentation burdens for European sales.
- Wood:Certified timber construction gains procurement preference under EU sustainability procurement guidelines, particularly for visible exterior panels in premium hospitality deployments.
- Metal:Steel and aluminum framing provides structural durability for high-traffic transit installations but faces energy-efficiency scrutiny under Japan's METI commercial equipment standards.
- Plastic:Injection-molded components enable cost-efficient portable unit production though recycling end-of-life obligations tighten under extended producer responsibility frameworks.
Fabric commands the widest application scope. Wood is climbing fastest on sustainability tailwinds.
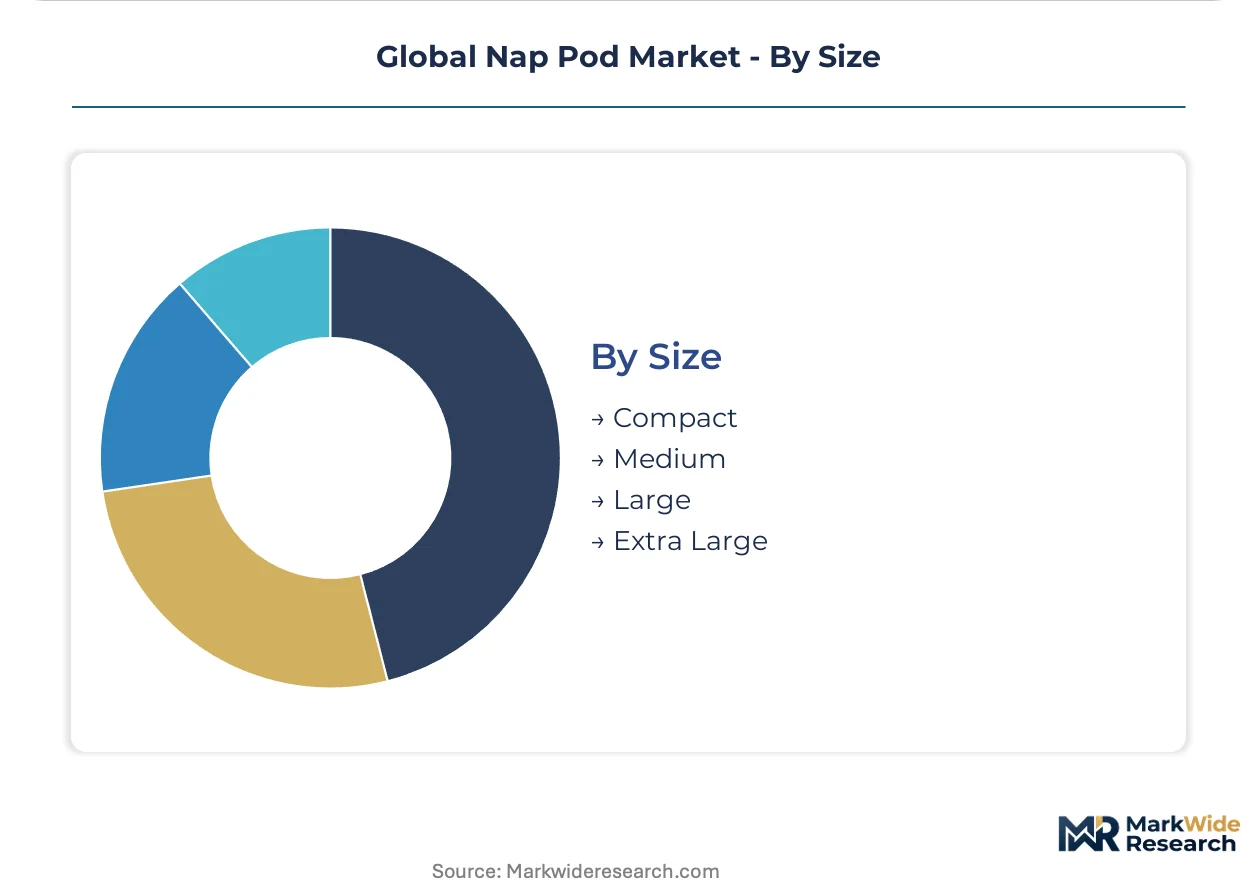
Size:
Real estate constraints in dense commercial districts favor compact footprints, though premium lounge operators specify larger enclosures to justify extended dwell-time pricing and differentiated amenity tiers.
- Compact:Two-square-meter enclosures optimized for 15-20 minute rest cycles dominate Japanese office district installations where floor space commands premium valuations.
- Medium:Standard three-square-meter configurations balance occupant comfort with installation flexibility across corporate campuses and co-working networks.
- Large:Four-square-meter units accommodate luggage storage and seated working positions, concentrating demand in airport lounges and hotel lobbies.
- Extra Large:Multi-functional suites with integrated desk surfaces and entertainment systems target premium transit lounges and executive wellness centers.
Compact sizes lead installation counts. Large formats gain share in hospitality yield management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in nap pod equipment tilt toward net imports in emerging deployment zones while established manufacturing bases in Germany and Japan supply regional hubs. Trade documentation reveals concentrated component sourcing from certified wood and acoustic textile suppliers in Northern Europe and East Asia.
United States
Corporate wellness budget expansion drives procurement volumes across technology campuses in California and Washington State. OSHA indoor air quality guidelines mandate 30-50 cubic feet per minute ventilation specifications that elevate product compliance costs. Dallas-Fort Worth and Atlanta office clusters sustain concentrated installation rates as hybrid workplace models stabilize.
Germany
Railway station modernization programs generate sustained demand for modular pod suites designed around commuter dwell times. EU Green Deal material mandates accelerate supplier qualification timelines for recycled fabric and certified wood construction. Frankfurt and Munich transit hubs anchor European deployment volumes through platform-based service agreements.
Japan
Tokyo's dense office districts and airport terminals sustain the highest per-capita installation rates globally as commercial real estate constraints intensify. METI energy-efficiency standards for commercial equipment constrain heating and ventilation specifications, forcing thermal management redesigns. Osaka and Nagoya medical districts concentrate demand for compact rest solutions in nursing stations.
United Kingdom
University wellness centers and library installations in London and Manchester represent emerging deployment channels with seasonal utilization patterns. CE marking requirements for electrical furnishings shape product certification pathways alongside REACH material traceability obligations. Heathrow Airport sustains premium positioning for transit lounge operators leveraging real-time availability data.
Australia
Flexible workspace operators in Sydney and Melbourne seek redeployable portable units that transfer between locations without structural modification. Extended producer responsibility frameworks tighten recycling end-of-life obligations for plastic components. Brisbane's co-working networks show accelerating adoption as hybrid office models penetrate regional markets.
Global Nap Pod Market Competitive Environment
On the supply side, the industry is consolidating around integrated wellness platform providers that bundle installation, maintenance, and usage analytics under multi-year service agreements. The vendor base separates into three strategic archetypes: airport lounge specialists commanding premium positioning, modular transit suite fabricators, and manufacturing-scale producers competing on unit economics. Dominant competitive moves include geographic expansion through platform-based partnerships and portfolio diversification into IoT-enabled occupancy detection systems.
Within the airport lounge specialist tier, MetroNaps and MinuteSuites exemplify premium positioning through integrated booking platforms that control reservation flow across distributed networks. NapCabs GmbH anchors European deployment through its German-registered corporate structure, representing the modular transit suite archetype with railway station-focused configurations. Sleepbox occupies a position within the manufacturing-scale tier, competing on production volume and component standardization.
| Leading Market Players |
|---|
| NapCabs GmbH |
| MinuteSuites |
| MetroNaps |
| 9 Hours |
| SnoozeCube |
| Sleepbox |
| Podtime |
| Snooze at My Space |
| GoSleep |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in certified acoustic textile manufacturing across Northern Europe is compressing supplier margins while elevating procurement premiums for REACH-compliant fabric surfaces, simultaneously pushing pod assemblers toward longer-term offtake agreements and reshaping how buyers negotiate volume commitments.
Pricing Analysis
Corporate wellness buyers anchor subscription-based pricing structures across multi-year service agreements that bundle installation, maintenance, and IoT analytics. Price differentiation hinges on certification tier—CE-marked electrical furnishings command premiums over baseline configurations—and after-sales service intensity. Cost compression in portable unit segments is intensifying because flexible workspace operators prioritize redeployability over feature depth. Hospitality operators show lowest price sensitivity, while mid-size employers in co-working networks exhibit highest elasticity.
Supply Chain Analysis
Export-control restrictions on advanced HVAC sensor technology limit component flows from Japanese suppliers to European assemblers, fragmenting sourcing strategies. Manufacturing concentrates in Germany, Japan, and China, with German fabricators specializing in modular railway station suites and Japanese producers dominating compact office pod designs. Raw material dependencies center on acoustic textiles, certified timber, and precision ventilation components. Single-source vulnerability in antimicrobial fabric treatments creates supply risk. Distribution runs through platform-based service agreements rather than discrete equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as integrated booking systems and IoT-enabled pod management create ecosystem lock-in, with interoperability between reservation platforms and building access control emerging as the decisive interoperability shift.
For Market Incumbents: Harden defensive positions by deepening backward integration into certified wood supply chains to secure EU Green Deal compliance margins, and accelerate HIPAA-compliant acoustic engineering capabilities to capture healthcare facility premiums. Emerging modular transit suite fabricators threaten lounge-specialist incumbents through lower-cost platform-based service models.
For New Entrants and Emerging Players: Pursue white-space opportunities in Australian flexible workspace networks where extended producer responsibility frameworks have slowed incumbent expansion, and target German railway station modernization programs through partnerships with established transit infrastructure operators. A direct-to-facilities-manager sales motion bypasses consolidated wellness platform procurement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated wellness platform providers bundling multi-year service agreements. Long-term viability favors vendors with captive IoT analytics capabilities and established airport lounge partnerships. The signal to watch is consolidation of vendor relationships by United States technology campuses toward single-contract accountability models.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrated booking systems controlling reservation flow across distributed pod networks compress operational friction for MetroNaps and MinuteSuites. |
| Backward Integration | In-house production of REACH-compliant acoustic textiles secures margin pools threatened by European chemical documentation burdens. |
| Healthcare Certification Pathway | HIPAA-compliant acoustic privacy standards extend product development cycles but command deepest margin pools in hospital deployments. |
| Geographic Expansion | Modular pod suites designed for German railway stations anchor NapCabs GmbH's European deployment volumes through transit infrastructure partnerships. |
| Green Manufacturing Transition | Recycled fabric and certified wood construction aligns procurement preference under EU Green Deal material sustainability mandates. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facilities managers at United States technology campuses, procurement leads at German railway operators, healthcare administrators in Tokyo medical districts, and flexible workspace operators in Sydney and Melbourne. Secondary validation drew from OSHA indoor air quality guidelines, EU REACH substance databases, Japan's METI energy-efficiency standards, and customs trade documentation for acoustic textile imports. Bottom-up pod installation counts across airport terminals, corporate campuses, and transit hubs were triangulated against top-down wellness budget allocation estimates.
Calibration against historical procurement cycles and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-user vertical, material composition, and geographic deployment cluster. CAGRs were derived from weighted average growth trajectories across portable unit, pod suite, office pod, and custom design categories, with inputs from IoT-enabled occupancy detection adoption curves and METI-compliant HVAC specification upgrade rates.
Sensitivities concentrate around fire safety classification rulings in high-occupancy commercial buildings and REACH material traceability cost escalations. Forecasts reflect documented assumptions about enterprise wellness budget expansion and hybrid workplace model stabilization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Bristle Brush Market
Household Items
Folded Tissues Market
Household Items
Oman Gas Hobs Market
Household Items
Non-Stick Cookware Market
Household Items
Japan Faucets Market
Household Items
Pet Fur Remover Market
Household Items
Home Use Air Purifiers Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Coffin and Cremation Urn Market
Household Items
Electric Clothes Drying Hanger Market
Household Items
Drinkware Accessories Market
Household Items
Global Paper Towels Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
Global Electronic Bidet Seats Market
Household Items
South Korea Cookware Market
Household Items
Tablet Tissue Paper Market