
 Germany Digital Showers Market | 2026-2036
Germany Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Digital Showers Market Insights
The Germany digital showers category is restructuring around a widening gap between luxury connected systems and basic thermostatic units. Grohe AG leverages its German manufacturing base to sustain dominance in high-margin IoT-enabled fixtures. Hansgrohe AG anchors its position through specialized digital control interfaces. Aloys F. Dornbracht GmbH and Co. KG differentiates via bespoke modular installations for architectural projects.
Germany digital showers comprise electronically controlled water delivery systems that regulate temperature, flow rate, and spray patterns through digital interfaces, typically incorporating thermostatic mixing valves with ±0.5°C accuracy and Bluetooth or Wi-Fi connectivity for remote operation. These systems serve residential, commercial, and hospitality sectors seeking precise water management and energy conservation. Smart showers lead product type demand as homeowners prioritize connected bathroom ecosystems, while sensor-driven technology captures the fastest growth trajectory among control modalities. Hospitality end users concentrate procurement in premium-tier digital systems, whereas retrofit installation types face margin compression against new construction pipelines.
Germany's Federal Ministry for Economic Affairs and Climate Action (BMWK) enforces Building Energy Act efficiency mandates that directly shape digital shower specification requirements, while KBA-adjacent construction product standards and DVGW certification protocols govern market access for plumbing fixtures. Stakeholders must monitor evolving GEG amendments and DVGW testing protocols to align product roadmaps with compliance timelines.
Market Dynamics
Germany's Building Energy Act (GEG) efficiency mandates are compressing specification cycles for bathroom fixtures, forcing manufacturers to accelerate thermostatic accuracy improvements and connected-system integration ahead of compliance deadlines.
Growth Catalysts
- GEG Water Efficiency Mandates:The Building Energy Act establishes minimum flow-rate thresholds that digital showers satisfy through precision thermostatic control, creating specification pull from architects and developers in Berlin, Munich, and Hamburg.
- Residential Renovation Clusters:Bavaria and Baden-Württemberg exhibit concentrated bathroom upgrade activity as homeowners replace aging fixtures with connected ecosystems during energy retrofits.
- Bluetooth and Wi-Fi Connectivity:Smart home integration protocols enable remote temperature presetting and usage tracking, aligning digital showers with broader home automation investments.
Market Restraints
- Copper and Electronic Component Volatility:Thermostatic valve manufacturing depends on copper alloys and semiconductor chips, exposing margins to commodity price swings and foundry capacity constraints.
- DVGW Certification Timelines:The German Technical and Scientific Association for Gas and Water imposes extended testing protocols for electronic mixing valves, delaying product launches by six to twelve months.
- Basic Thermostatic Substitution:Non-connected thermostatic units satisfy GEG requirements at lower price points, capturing cost-sensitive renovation segments in eastern German states.
Strategic Opportunities
- Sensor-Driven Control Modalities:Touchless and proximity-activated interfaces address hygiene priorities in hospitality and healthcare end uses, opening specification channels beyond residential.
- Modular Bespoke Installations:Architectural projects in premium urban housing developments demand customizable spray configurations and concealed valve systems, rewarding flexible manufacturing capabilities.
- GEG Amendment Trajectory:Anticipated tightening of efficiency thresholds through 2030 creates regulatory tailwind for manufacturers with advanced R&D pipelines in thermostatic precision.
Industry Challenges
- Embedded Software Expertise Scarcity:Firmware development for ±0.5°C accuracy control competes with automotive and industrial automation sectors for qualified engineers in southern Germany.
- Legacy Plumbing Integration Complexity:Retrofit installations require compatibility with existing pipe configurations and pressure systems, complicating field deployment and service training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Digital Showers Market |
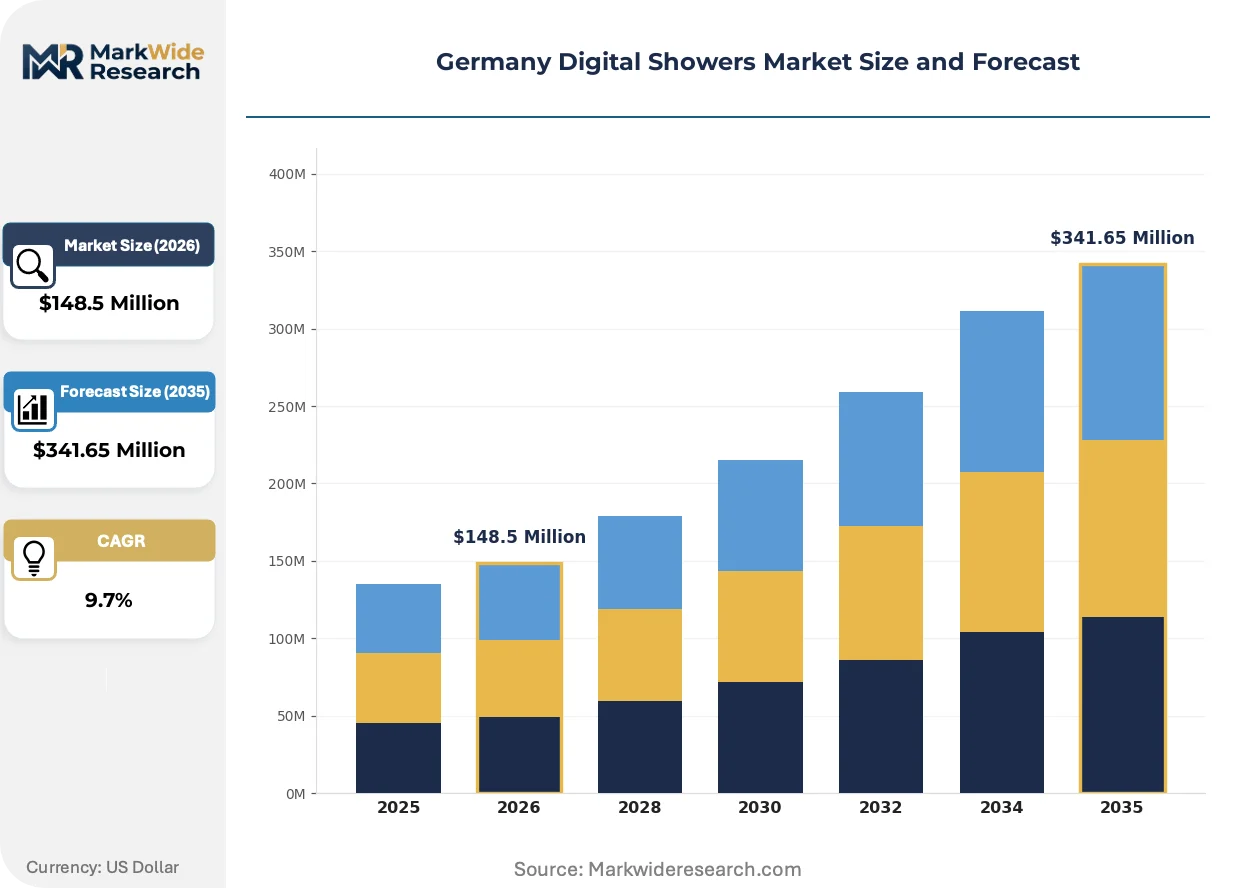
| Market Size in 2026 | $148.5 Million |
| Market Size in 2035 | $341.65 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Showers, Thermostatic Showers, Digital Control Systems, Pressure Balance Showers End User: Residential, Commercial, Hospitality, Healthcare Technology: IoT-Enabled, Wireless Control, App-Based, Sensor-Driven Installation Type: New Construction, Retrofit, Modular, Custom |
| Companies Covered | Grohe AG, Hansgrohe AG, Aloys F. Dornbracht GmbH and Co. KG, Dornbracht Deutschland GmbH & Co. KG, Aqualisa Products Limited, Kohler Co., Delta Faucet, Masco Corporation, Moen Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Digital Showers Market Trends and Innovations
Digital shower technology is bifurcating between luxury connected ecosystems and precision-engineered thermostatic cores, with software-defined functionality displacing mechanical differentiation as the primary value driver.
Thermostatic mixing valves with embedded machine learning algorithms are rewriting competitive boundaries in the premium segment. Hospitality operators in Hamburg and Munich are deploying these systems to optimize water consumption across property portfolios. The technology is compressing hardware margins while expanding recurring revenue potential through predictive maintenance subscriptions.
The Building Energy Act amendment trajectory is tightening flow-rate specifications faster than anticipated by fixture manufacturers. DVGW certification bodies are expanding test protocols to cover connected-system cybersecurity, adding compliance layers for Wi-Fi-enabled models. Premium-tier suppliers are responding by pre-certifying entire product families rather than individual SKUs.
Specification authority is migrating from general contractors to smart-home integrators in high-end residential developments. These specialists bundle digital showers with lighting and climate control systems, displacing traditional plumbing distributors in Berlin's luxury housing pipeline. The shift concentrates procurement decisions among a smaller cohort of technology-fluent buyers who prioritize API compatibility over brand heritage.
Germany Digital Showers Market Segmentation
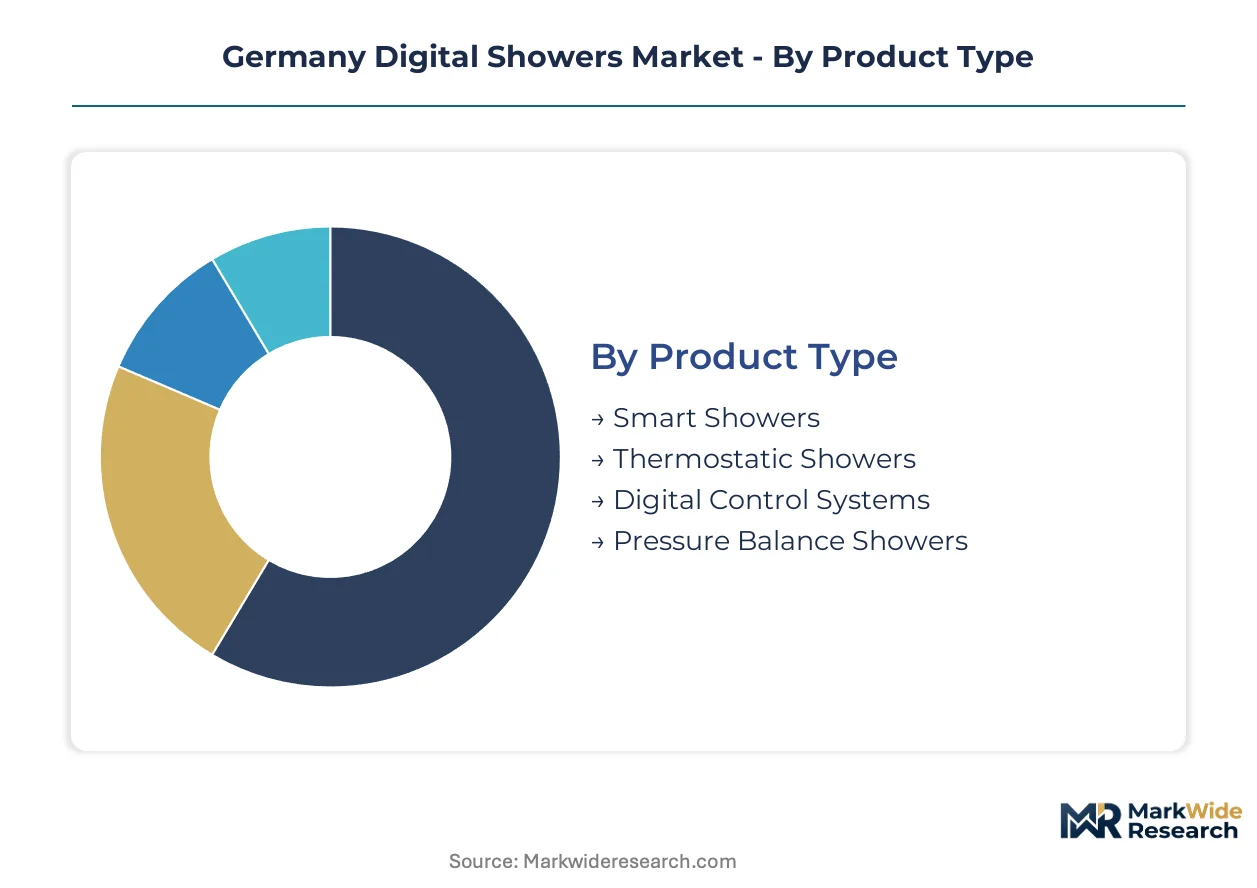
Germany's digital showers market fragments across four distinct axes that determine specification authority and margin capture. Product architecture, end-use application, connectivity protocol, and installation context each create separate competitive battlegrounds for manufacturers competing under GEG compliance pressure.
Product Type:
Technical sophistication and connectivity depth separate premium positioning from commodity substitution in fixture specification.
- Smart Showers:Fully connected systems integrate Wi-Fi and Bluetooth protocols with thermostatic cores achieving ±0.5°C precision. Berlin and Munich luxury residential developments specify these for home automation integration, though copper alloy and semiconductor supply constraints compress hardware margins.
- Thermostatic Showers:Electronically controlled mixing valves deliver precise temperature regulation without network connectivity. Bavaria and Baden-Württemberg renovation clusters favor these for GEG compliance at accessible price points, capturing volume share in cost-sensitive retrofit segments.
- Digital Control Systems:Modular interface modules enabling remote operation through proprietary or third-party home automation platforms.
- Pressure Balance Showers:Mechanical-digital hybrid units maintaining output stability during pressure fluctuations in older building infrastructure.
Smart showers lead on scale; sensor-ready thermostatic platforms lead on momentum.
End User:
Procurement sophistication and specification cycles vary dramatically across buyer categories, reshaping channel requirements.
- Residential:Individual homeowners and property developers in Hamburg, Berlin, and Munich drive connected-system demand through smart-home integration investments. GEG retrofit mandates in energy-efficient housing stock accelerate replacement cycles for aging fixtures.
- Hospitality:Premium hotel operators in Munich and Hamburg deploy sensor-driven systems for hygiene differentiation and water consumption optimization across property portfolios. Procurement concentrates among technology-fluent buyers prioritizing API compatibility.
- Commercial:Office and retail facility managers specifying durable fixtures for high-traffic washroom environments.
- Healthcare:Hospitals and eldercare facilities requiring touchless activation and antimicrobial surface specifications.
Residential commands volume concentration; hospitality delivers margin expansion through specification premiums.
Technology:
Control modality determines software development investment requirements and cybersecurity compliance exposure under evolving DVGW protocols.
- IoT-Enabled:Full-stack connected architectures integrating cloud platforms, mobile applications, and predictive maintenance algorithms. Machine learning-enabled thermostatic cores are compressing hardware differentiation while expanding recurring revenue potential through subscription services.
- Sensor-Driven:Proximity and touchless activation systems addressing hygiene priorities in hospitality and healthcare end uses. These interfaces are expanding fastest among control modalities as post-pandemic specification standards harden.
- Wireless Control:Local network protocols without cloud dependency, reducing cybersecurity certification burden.
- App-Based:Smartphone-dependent interfaces requiring robust firmware development competing with automotive and industrial automation sectors for qualified engineers in southern Germany.
IoT-enabled systems anchor revenue concentration; sensor-driven modalities climb the fastest on hygiene specification tailwinds.
Installation Type:
Field deployment complexity and service training requirements separate new construction economics from retrofit margin structures.
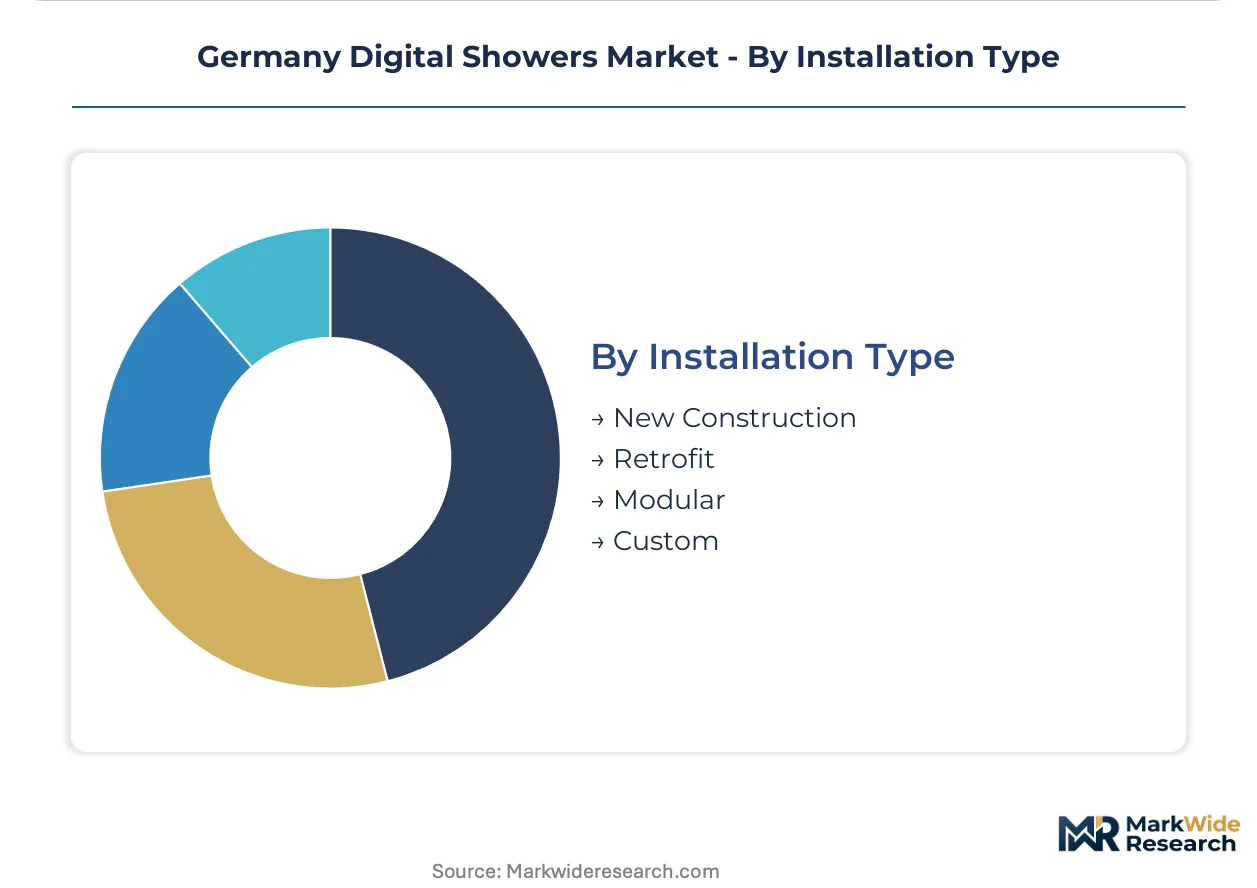
- New Construction:Greenfield plumbing infrastructure enables concealed valve systems and optimized pressure configurations from foundation. Premium urban housing developments across Berlin, Munich, and Hamburg concentrate procurement here, rewarding flexible manufacturing capabilities for bespoke modular installations.
- Retrofit:Legacy pipe compatibility requirements and pressure system constraints complicate field deployment. Eastern German states exhibit price-sensitive renovation activity where basic thermostatic units capture share from connected alternatives.
- Modular:Standardized component systems enabling rapid configuration for mid-tier residential and commercial applications.
- Custom:Architectural project-specific solutions for signature developments requiring unique spray configurations and aesthetic integration.
New construction sustains margin premiums; retrofit installations face structural compression against basic thermostatic substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers with embedded software and thermostatic valve expertise concentrate in southern German industrial corridors, anchoring the country's digital shower manufacturing base and R&D infrastructure.
Bavaria
Residential renovation clusters in Munich and Nuremberg drive specification demand for connected bathroom ecosystems. The Building Energy Act mandates stricter water efficiency thresholds that accelerate fixture replacement cycles. Premium housing developments in Munich concentrate procurement for smart home-integrated digital showers.
Baden-Württemberg
Homeowners in Stuttgart and Karlsruhe prioritize energy retrofits that bundle bathroom upgrades with building envelope improvements. KBA-adjacent construction product standards shape certification requirements for electronic mixing valves. The Stuttgart metropolitan area hosts concentrated manufacturing capabilities for thermostatic cores.
North Rhine-Westphalia
Commercial hospitality projects in Cologne and Düsseldorf specify sensor-driven systems for hygiene differentiation. DVGW certification protocols govern market access for plumbing fixtures deployed across hotel portfolios. The Ruhr region's industrial heritage creates legacy building stock requiring pressure-balanced retrofit solutions.
Berlin-Brandenburg
Smart-home integrators in Berlin displace traditional plumbing distributors in luxury residential procurement. GEG amendments tighten flow-rate specifications faster than anticipated by fixture manufacturers. New construction pipelines in Potsdam and Berlin enable concealed valve systems from foundation.
Hamburg
Premium hotel operators deploy machine learning-enabled thermostatic systems to optimize water consumption across property portfolios. Anticipated GEG tightening through 2030 creates regulatory tailwind for manufacturers with advanced R&D pipelines. The city's port infrastructure facilitates component import for semiconductor-dependent production.
Germany Digital Showers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Germany's digital shower landscape. The vendor base fragments between integrated manufacturers with captive foundry capacity and specialized firms outsourcing thermostatic core production. Three archetypes dominate: vertically integrated fixture conglomerates, modular system specialists, and connectivity-focused technology entrants. Competitive intensity concentrates on DVGW certification pre-approval strategies and smart-home API compatibility partnerships.
Among German-based fabricators, Grohe AG exemplifies the vertically integrated archetype with domestic manufacturing infrastructure. Hansgrohe AG occupies a position within the specialized digital control tier, while Aloys F. Dornbracht GmbH and Co. KG represents the bespoke modular installation segment for architectural projects. These three anchors illustrate the market's tripartite structure: scale-driven manufacturing, interface specialization, and custom project execution.
| Leading Market Players |
|---|
| Grohe AG |
| Hansgrohe AG |
| Aloys F. Dornbracht GmbH and Co. KG |
| Dornbracht Deutschland GmbH & Co. KG |
| Aqualisa Products Limited |
| Kohler Co. |
| Delta Faucet |
| Masco Corporation |
| Moen Incorporated |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange copper alloy pricing cascades through Germany's digital shower supply chain, compressing hardware margins for IoT-enabled fixtures while amplifying premium capture for manufacturers with captive thermostatic core production. Bavaria and Baden-Württemberg renovation clusters absorb cost volatility through bundled installation services that obscure component pricing from end consumers.
Pricing Analysis
Bundled installation services versus unbundled component sales split pricing architecture across Germany's digital shower market. Three-tier pricing structure across premium, standard, and economy levels reflects DVGW certification grade and thermostatic precision capability, with GEG compliance tiers driving price differentiation. Pricing pressure stems from copper alloy and semiconductor cost volatility, compressing margins on connected systems. Eastern German retrofit buyers exhibit highest price sensitivity, while Munich luxury developers prioritize API compatibility over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries supplying thermostatic control chips, creating exposure for German manufacturers dependent on ±0.5°C precision firmware. Supply draws from Germany for thermostatic valve casting, China for electronic component assembly, and Taiwan for microcontroller fabrication. Copper alloy sourcing from Chile and Zambia introduces commodity price volatility risk. Distribution runs through plumbing wholesalers in traditional channels and smart-home integrators in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's Building Energy Act functions as a regulatory compounder, with anticipated 2030 efficiency threshold tightening creating sustained specification pull for advanced thermostatic systems ahead of compliance deadlines.
For Market Incumbents: Deepen backward integration into copper alloy casting and semiconductor firmware development to defend against commodity volatility and embedded software expertise scarcity. Accelerate DVGW pre-certification of entire product families rather than individual SKUs to compress launch timelines against compliance deadlines. Prioritize API compatibility partnerships with Berlin and Munich smart-home integrators displacing traditional plumbing distributors. For New Entrants and Emerging Players: Sensor-driven touchless control modules offer a technology-first wedge into hospitality and healthcare procurement channels beyond residential saturation. Target North Rhine-Westphalia commercial hospitality projects specifying hygiene-differentiated fixtures for Cologne and Düsseldorf hotel portfolios. Pursue white-label manufacturing partnerships with established plumbing brands lacking firmware development capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with modular system specialists possessing flexible manufacturing capabilities for bespoke architectural installations. Five-to-ten-year viability favors manufacturers with captive thermostatic core production and established DVGW certification relationships. Monitor GEG amendment trajectory and DVGW cybersecurity protocol expansion as inflection indicators for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| DVGW Pre-Certification Investment | Compresses product launch timelines by six to twelve months against compliance deadlines. |
| Smart-Home Integrator Partnership | Secures specification authority in Berlin and Munich luxury residential developments. |
| Sensor-Driven Interface Development | Captures hospitality and healthcare procurement prioritizing hygiene post-pandemic. |
| Copper Alloy Backward Integration | Insulates margins from London Metal Exchange price volatility in thermostatic valve production. |
| Embedded Firmware Talent Acquisition | Addresses scarcity competing with automotive and industrial automation sectors in southern Germany. |
Research Methodology
Direct dialogue with product development directors at fixture manufacturers, smart-home integration specialists in Berlin and Munich, DVGW certification engineers, plumbing wholesale procurement managers, and hospitality facility operators grounded this analysis. Secondary validation drew from BMWK policy documents, DVGW testing protocol updates, German Federal Statistical Office construction data, and trade association publications. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-level value and volume trajectories across the analysis window reflect modeled adoption curves for smart versus thermostatic shower architectures, GEG compliance-driven replacement cycles, and connectivity protocol penetration rates. CAGRs derive from regression analysis against renovation activity indices and new construction permit data. Forecast inputs incorporate DVGW certification timeline assumptions and copper alloy price elasticity coefficients.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GEG amendment timing, semiconductor supply normalization, and smart-home platform consolidation dynamics. Forecasts reflect documented assumptions regarding regulatory trajectory and commodity price regimes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Air Purifier Market
Household Items
Domestic Sauna Heaters Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
US Digital Showers Market
Household Items
Aquarium Hydrometers Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
North America Tankless Water Heater Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
Chest Freezers Market
Household Items
Portable Iron Market
Household Items
Lunch Box Market
Household Items
Smart Toilet Market
Household Items
Multi-Door Fridges Market
Household Items
Residential Air Purifiers Market
Household Items
China Cookware Market