
 Latin America Flow Cytometry Market | 2026-2036
Latin America Flow Cytometry Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Flow Cytometry Market Insights
The Latin America flow cytometry landscape is consolidating around a widening gap between premium analytical platforms and entry-level cell counters. BD leverages its installed base of clinical diagnostics instruments to sustain service revenue across Brazilian public hospital networks. Thermo Fisher Scientific Inc. competes through distributed technical support teams that anchor customer loyalty in Mexico and Argentina. Bio-Rad Laboratories, Inc. differentiates by specializing in research-grade reagent systems for academic immunology programs.
Flow cytometry refers to a laser-based analytical technique that measures physical and chemical characteristics of cells or particles suspended in fluid, typically detecting fluorescence emission at wavelengths from 400 to 800 nanometers for multiparametric phenotyping. The technology serves primary commercial purposes in clinical diagnostics, drug discovery, and biomedical research requiring quantitative cell population analysis. Instruments command the largest capital allocation among product categories, while oncology applications generate the fastest growth trajectory due to rising precision medicine protocols across Latin American cancer centers. Reagents capture recurring margin pools through consumable replenishment cycles tied to installed instrument bases.
ANVISA in Brazil and COFEPRIS in Mexico enforce medical device registration requirements that shape instrument import timelines and calibration standards for clinical flow cytometry systems. The region's national pharmaceutical regulators increasingly reference ICH Q5D guidelines for cell-based assay validation, creating compliance complexity for multinational vendors. Stakeholders must monitor how evolving diagnostic reimbursement frameworks in Colombia and Chile reshape capital equipment purchasing cycles across hospital procurement networks.
Market Dynamics
Flow cytometry platforms in Latin America face a structural squeeze between high-throughput clinical diagnostics demand and fragmented research funding pools that bifurcate purchasing authority across hospital procurement networks and academic grant cycles.
Growth Catalysts
- Precision oncology protocols:Cancer centers in São Paulo and Rio de Janeiro are integrating multiparametric immunophenotyping into routine leukemia diagnostics, expanding instrument utilization rates.
- ANVISA-ICH convergence:Brazil's harmonization with ICH Q5D guidelines for cell-based assay validation is compressing regulatory timelines for instrument registration.
- Reagent pull-through economics:Installed bases of clinical analyzers generate recurring consumable demand that stabilizes vendor revenue visibility across Mexican diagnostic laboratories.
Market Restraints
- Import duty structures:Brazil's industrialized goods tax regime adds 12-18% to instrument landed costs, compressing hospital capital budgets.
- Technical service scarcity:Certified field engineers for laser alignment and fluidics maintenance concentrate in São Paulo and Mexico City, extending downtime for peripheral installations.
- Fluorophore supply concentration:Specialty dye synthesis for rare markers depends on North American and European chemical suppliers, creating replenishment lag.
Strategic Opportunities
- Colombian diagnostic expansion:INVIMA's streamlined medical device pathway and rising private insurance penetration are opening procurement channels in Bogotá and Medellín hospital systems.
- Point-of-care cytometry miniaturization:Microfluidic chip-based cell counters are penetrating rural health posts where full-scale analyzers remain uneconomical.
- Academic core facility centralization:Federal research grants in Argentina and Chile are consolidating dispersed departmental instruments into shared-service platforms with reagent volume contracts.
Industry Challenges
- Multicolor panel design expertise:Compensation mathematics for 12+ color flow requires specialized bioinformatics training that outpaces regional graduate program output.
- Legacy LIS integration:Hospital information systems in Brazilian public networks run on 1990s-era architectures that resist HL7 FHIR connectivity with modern cytometers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Flow Cytometry Market |
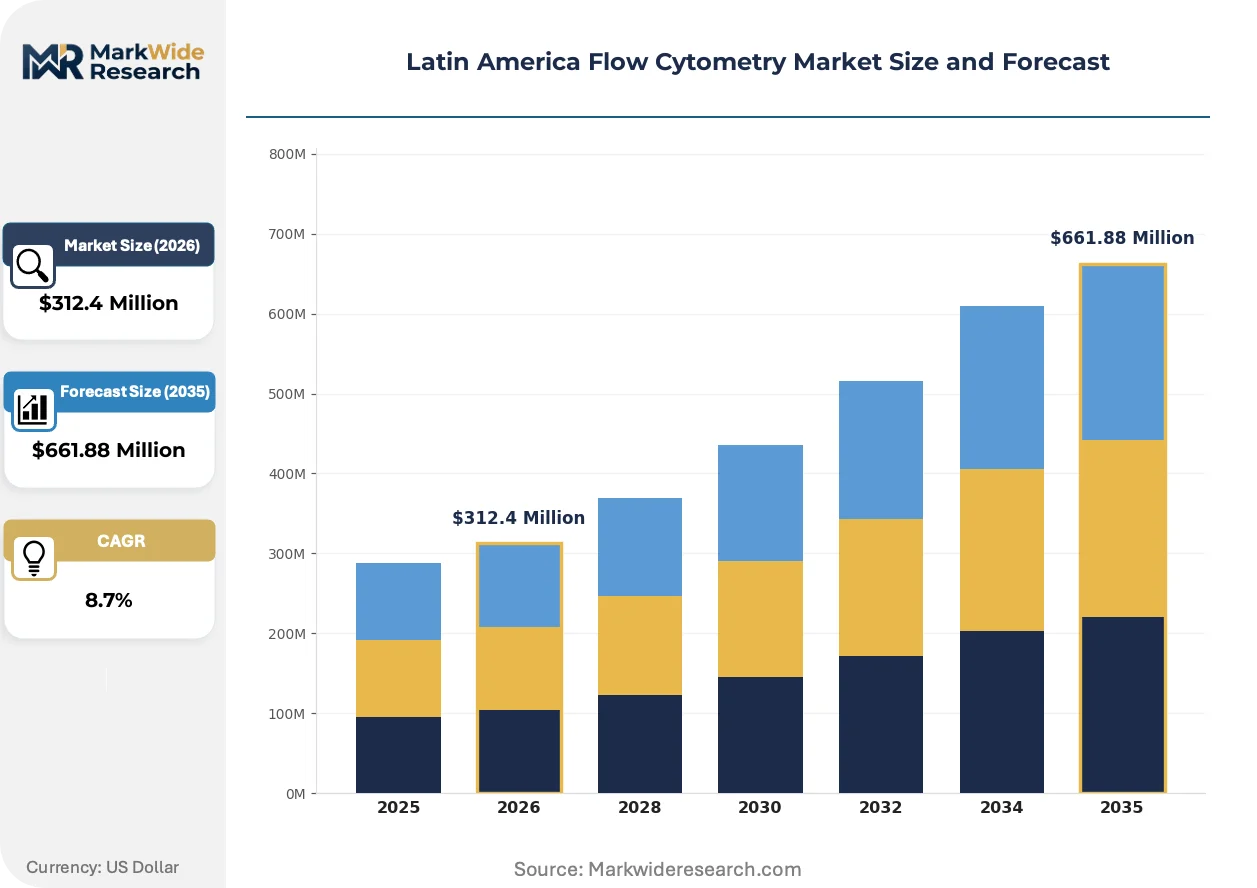
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Accessories End User: Hospitals, Academic Institutions, Research Laboratories, Diagnostic Centers Application: Cell Biology, Immunology, Oncology, Hematology Sales Channel: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | Cytiva, Sartorius AG, BD, Agilent Technologies, Inc., Sysmex Corporation, Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., Miltenyi Biotec, Danaher Corp, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Flow Cytometry Market Trends and Innovations
Spectral flow cytometry is compressing the traditional compensation workflow while artificial intelligence algorithms automate gating decisions that previously required manual cytometrist intervention.
Spectral detection arrays are replacing conventional optical filter sets by capturing full emission signatures across 32-64 detectors, enabling simultaneous measurement of fluorophores with overlapping spectra. Large cancer centers in Brazil and Mexico are adopting these systems for complex immunophenotyping panels. The technology is consolidating analytical capability into fewer physical instruments per laboratory, reducing capital footprint while expanding parameter depth.
ANVISA's 2023 medical device software guidance now mandates cybersecurity documentation for networked cytometers, adding validation steps to registration dossiers. Manufacturers must demonstrate encrypted data transmission and audit trail integrity for cloud-connected instruments. Clinical diagnostics vendors are responding by segregating Brazilian product SKUs with hardened firmware configurations distinct from research-grade units sold elsewhere in Latin America.
Hospital procurement offices are unbundling service contracts from instrument purchases, soliciting third-party maintenance bids that undercut manufacturer pricing. São Paulo's largest public hospital network recently split a 48-unit service agreement across two independent technical service providers. This behavior concentrates in Brazilian states where fiscal austerity measures cap multi-year contractual commitments.
Latin America Flow Cytometry Market Segmentation
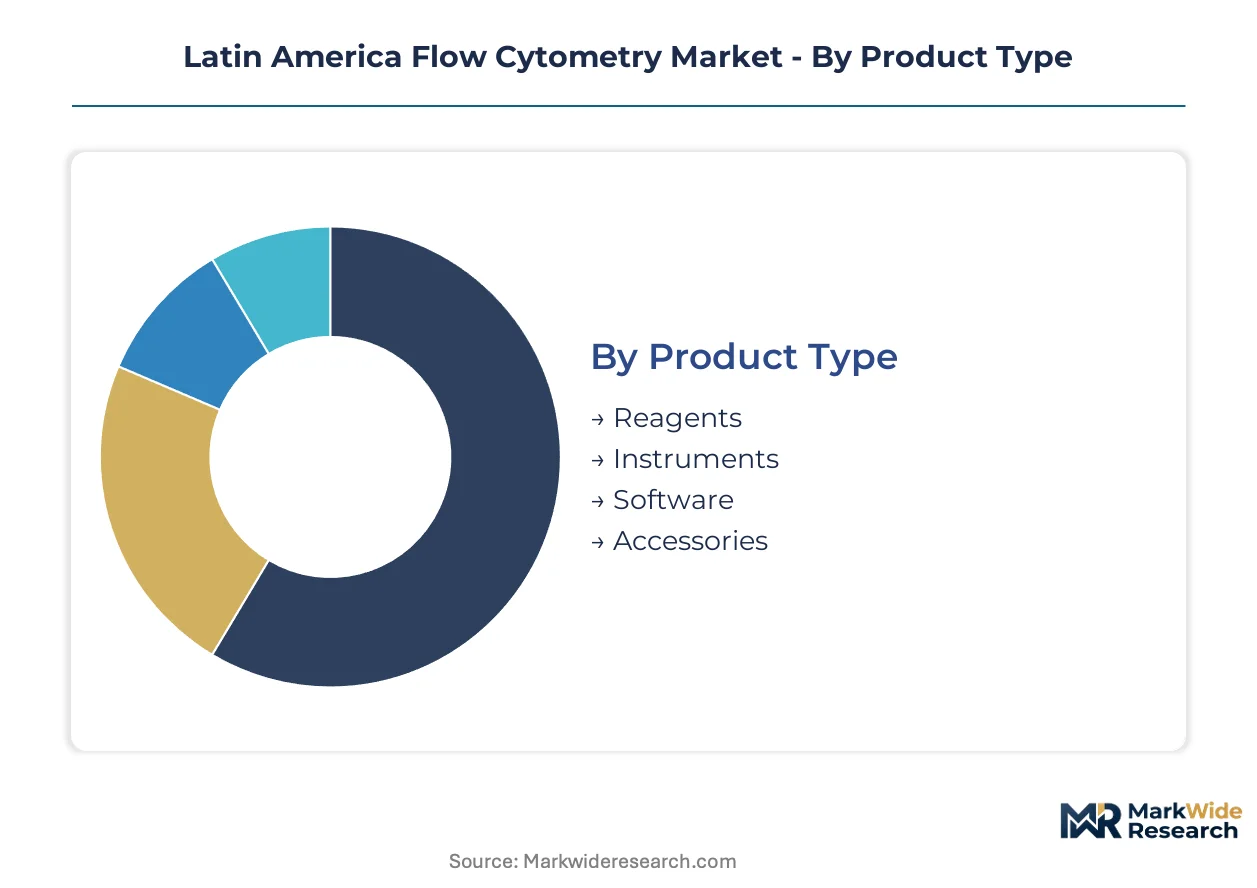
Flow cytometry procurement in Latin America splits across capital-intensive instrument platforms and recurring consumable revenue streams. Each segment category reflects distinct purchasing authority structures spanning hospital procurement networks, academic grant cycles, and distributor-mediated supply chains.
Product Type:
Customization intensity varies sharply across this category, from configured-to-order laser arrays to standardized reagent kits.
- Instruments:Laser-based analyzers and cell sorters with configurable detector arrays dominate capital allocation. São Paulo and Rio de Janeiro hospital clusters concentrate demand for 12-16 color clinical diagnostics platforms. ANVISA registration timelines compress procurement cycles for systems with pre-validated assay protocols.
- Reagents:Fluorophore-conjugated antibodies and buffer systems generate recurring margin pools tied to installed instrument bases. Mexican diagnostic laboratories drive volume through high-frequency leukemia and lymphoma profiling panels. Supply concentration in North American dye synthesis creates replenishment lag for rare markers.
- Software:Analysis platforms for compensation mathematics and automated gating decisions. Research laboratories in Argentina prioritize open-source compatibility with existing bioinformatics pipelines.
- Accessories:Fluidics components, calibration beads, and replacement optical filters. Peripheral Brazilian states extend lead times due to São Paulo-centric technical service concentration.
Leading the category by volume: Reagents. Growing fastest: Instruments with spectral detection arrays.
End User:
Purchasing authority fragments across fiscal environments with divergent budget cycles and compliance obligations.
- Hospitals:Clinical diagnostics departments in Brazilian public networks command the largest capital equipment budgets. Precision oncology protocols in São Paulo cancer centers are expanding multiparametric immunophenotyping utilization. Legacy LIS integration challenges persist with 1990s-era hospital information architectures.
- Diagnostic Centers:Independent laboratories in Mexico and Colombia concentrate high-throughput screening volumes. INVIMA's streamlined registration pathway accelerates instrument procurement in Bogotá and Medellín.
- Academic Institutions:Federal research grants in Argentina and Chile are consolidating dispersed departmental instruments into shared-service core facilities.
- Research Laboratories:Biotechnology and pharmaceutical R&D units with specialized panel design requirements. Multicolor compensation expertise scarcity outpaces regional graduate program output.
Hospitals capture the largest revenue share. Diagnostic centers are expanding most quickly with private insurance penetration.
Application:
Clinical utility depth determines reagent consumption intensity and instrument configuration requirements.
- Oncology:Leukemia and lymphoma immunophenotyping protocols drive the steepest expansion trajectory. Brazilian cancer centers are integrating minimal residual disease monitoring into routine diagnostics. Spectral flow cytometry adoption concentrates in high-complexity reference laboratories.
- Hematology:Complete blood count differential and bone marrow analysis for anemia and coagulation disorders. Standardized assay menus dominate procurement specifications across Mexican hospital networks.
- Immunology:T-cell subset enumeration and autoimmune marker profiling. Academic programs in Chile prioritize research-grade reagent flexibility over clinical validation.
- Cell Biology:Apoptosis detection and cell cycle analysis for drug discovery applications. Pharmaceutical R&D budgets in Argentina face currency volatility constraints.
Oncology leads absolute spending. Immunology is gaining share fastest with precision medicine protocol expansion.
Sales Channel:
Channel selection reflects technical complexity, regulatory burden, and procurement scale.
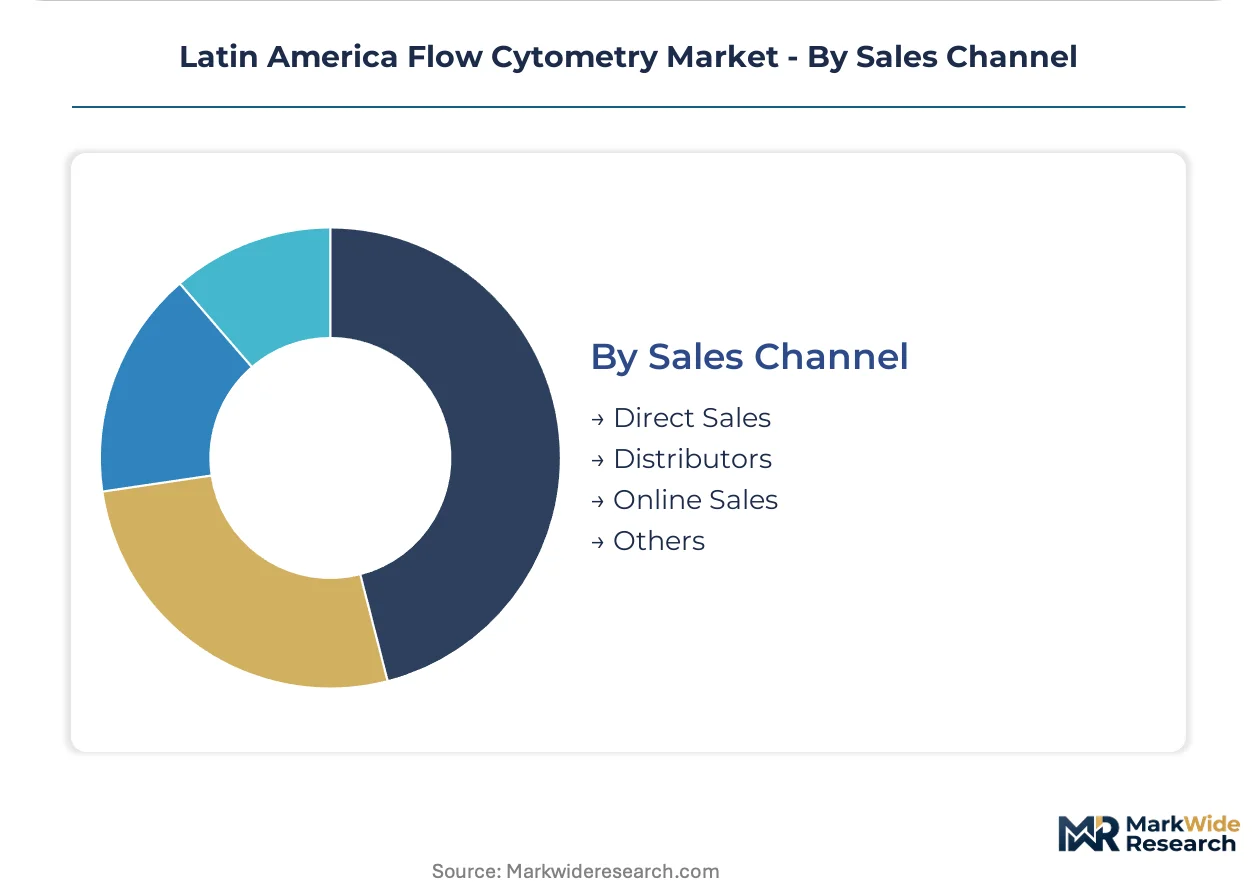
- Distributors:Local inventory holding and technical support anchoring dominate mid-market penetration. São Paulo-based distributors maintain service engineer concentration for laser alignment and fluidics maintenance.
- Direct Sales:Manufacturer-led account management for large hospital network contracts. ANVISA registration dossier preparation requires direct regulatory affairs engagement.
- Online Sales:Reagent replenishment and standard accessories through e-procurement platforms. Colombian private laboratory procurement offices increasingly favor digital catalog browsing.
- Others:Group purchasing organizations and consignment arrangements. Brazilian fiscal austerity measures are extending third-party service contract unbundling.
Distributors handle the majority of transaction volume. Direct sales are expanding fastest with spectral platform complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors Latin American flow cytometry demand through its dense concentration of cancer centers and diagnostic laboratories serving Brazil's public health network.
Brazil
Precision oncology protocols in Rio de Janeiro and São Paulo hospital clusters are expanding multiparametric immunophenotyping utilization for leukemia diagnostics. ANVISA's convergence with ICH Q5D guidelines compresses regulatory timelines for instrument registration. São Paulo-based distributors maintain the region's densest concentration of certified field engineers for laser alignment and fluidics maintenance.
Mexico
Independent diagnostic laboratories in Mexico City concentrate high-throughput screening volumes for lymphoma profiling panels. COFEPRIS enforces medical device registration requirements that shape instrument import timelines and calibration standards. Northern border states extend lead times for technical service due to engineer concentration in the capital.
Argentina
Federal research grants are consolidating dispersed departmental instruments into shared-service core facilities with reagent volume contracts. The country's national pharmaceutical regulator references international cell-based assay validation standards for clinical system approval. Buenos Aires academic programs prioritize research-grade reagent flexibility over clinical validation protocols.
Colombia
INVIMA's streamlined medical device pathway and rising private insurance penetration are opening procurement channels in Bogotá and Medellín hospital systems. The national regulatory agency accelerates instrument registration for systems with pre-validated assay protocols. Caribbean coastal laboratories face extended replenishment lag for specialty fluorophores dependent on North American chemical suppliers.
Chile
Academic immunology programs in Santiago drive demand for open-source software compatibility with existing bioinformatics pipelines. Evolving diagnostic reimbursement frameworks reshape capital equipment purchasing cycles across hospital procurement networks. Antofagasta mining region laboratories extend downtime for peripheral installations due to technical service scarcity.
Latin America Flow Cytometry Market Competitive Landscape
Premium-margin players sit above commodity-margin players across instrument configuration depth and reagent customization intensity. The vendor base stratifies between full-platform manufacturers with installed base service revenue and specialized reagent suppliers anchoring academic relationships. Three archetypes dominate: integrated diagnostics conglomerates with Brazilian public hospital networks, distributed technical service specialists penetrating Mexican mid-markets, and research-grade reagent pure-plays targeting federal grant cycles. Competitive moves concentrate on unbundling service contracts from instrument purchases and consolidating academic core facilities through shared-service reagent volume agreements.
Within the integrated diagnostics tier, BD and Thermo Fisher Scientific Inc. occupy positions sustained by installed base economics and distributed technical support teams. Bio-Rad Laboratories, Inc. exemplifies the research-grade reagent specialist archetype, anchoring customer relationships through academic immunology program penetration. Sysmex Corporation and Danaher Corp represent diversified life sciences conglomerates with multi-product hospital network contracts. These five entities collectively span the spectrum from clinical diagnostics instrumentation through consumable replenishment cycles.
| Leading Market Players |
|---|
| Cytiva |
| Sartorius AG |
| BD |
| Agilent Technologies, Inc. |
| Sysmex Corporation |
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories, Inc. |
| Miltenyi Biotec |
| Danaher Corp |
| Others |
Pricing and Supply Chain Analysis
Rare earth oxide price indices for neodymium and europium feed directly into fluorophore synthesis costs, cascading through North American dye manufacturers into tiered instrument and reagent pricing across Brazilian and Mexican hospital procurement networks.
Pricing Analysis
Instrument uptime guarantees anchor value-based pricing for clinical diagnostics platforms in São Paulo cancer centers. Three-tier pricing structure across premium spectral systems, standard clinical analyzers, and economy cell counters reflects detector array depth and pre-validated assay menus. Cost compression in the economy tier intensifies because public hospital networks unbundle service contracts and solicit third-party maintenance bids. Diagnostic laboratories in Mexico City exhibit highest price sensitivity due to fragmented purchasing authority, while research core facilities in Argentina prioritize reagent flexibility over unit economics.
Supply Chain Analysis
Brazil's local-content requirements for medical device procurement are reshaping sourcing patterns for fluidics components and optical assemblies. Specialty fluorophore synthesis concentrates in Germany, Switzerland, and the United States, while laser diode manufacturing centers on Japan and South Korea. Single-source vulnerability runs through North American dye suppliers for rare markers, extending replenishment lag for Caribbean coastal laboratories. Distribution runs through São Paulo-based distributors holding regional inventory and certified field engineer concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified field engineer scarcity props pricing power for technical service contracts across Brazilian states outside São Paulo, sustaining margin pools for incumbent service networks.
For Market Incumbents: Lock in long-term reagent volume agreements with consolidating academic core facilities in Argentina and Chile before federal grant cycles shift procurement authority. Deepen backward integration into fluorophore synthesis partnerships to offset North American supply concentration risk. Counter third-party service contract unbundling by embedding predictive maintenance software that requires proprietary firmware access. For New Entrants and Emerging Players: INVIMA's streamlined medical device pathway in Colombia opens a window for spectral platform entry into Bogotá and Medellín hospital systems before incumbent distributor relationships solidify. Target diagnostic centers in Mexican northern border states where technical service scarcity extends downtime and creates switching costs. Pursue point-of-care cytometry miniaturization for rural health posts as the most penetrable white space. For Investors and Strategic Acquirers: Distressed-cycle entries favor research-grade reagent specialists with anchored academic immunology programs in Buenos Aires and Santiago. Long-term viability hinges on spectral detection patent estates and reagent pull-through economics from installed instrument bases. Watch for ANVISA cybersecurity guidance enforcement as an inflection indicator for vendor compliance cost differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Volume Contract Consolidation | Federal grant cycles in Argentina and Chile are concentrating dispersed departmental instruments into shared-service platforms with multi-year consumable commitments. |
| Spectral Platform CE Marking Pathway | Pre-validated assay protocols accelerate INVIMA registration timelines for entry into Colombian private insurance networks. |
| Third-Party Service Contract Unbundling | Brazilian fiscal austerity measures cap multi-year manufacturer commitments, fragmenting maintenance revenue across independent technical providers. |
| Point-of-Care Microfluidic Miniaturization | Rural health posts in peripheral Brazilian states and Colombian coastal regions remain uneconomical for full-scale analyzer deployment. |
| Fluorophore Sourcing Backward Integration | Specialty dye supply concentration in North America and Europe creates replenishment vulnerability for rare marker panels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across cytometry platform engineers, hospital procurement managers, biomedical laboratory directors, and distributor technical service heads. ANVISA registration dossiers, INVIMA medical device approvals, and COFEPRIS import records provided calibration benchmarks for instrument penetration timelines. Bottom-up triangulation against top-down sector spending estimates validated regional demand distribution.
Segmentation granularity modeled product type at the instrument-reagent-software disaggregation level, end user across hospital-diagnostic-academic-research taxonomy, and application by clinical utility depth from routine hematology through complex oncology immunophenotyping. CAGRs derived from instrument replacement cycles, reagent consumption intensity per installed base unit, and precision medicine protocol adoption curves across Latin American cancer centers. Spectral detection technology migration and AI-assisted gating algorithm penetration served as key technology adoption inputs.
The model assumes a particular technology adoption path; alternative pathways for point-of-care microfluidic cytometry would alter the outlook for capital equipment demand concentration. Forecasts reflect assumptions regarding regulatory harmonization pace, reimbursement framework evolution, and field service network expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Cell Signaling Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Cell Analysis Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Glycomics Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Cell Separation Market
Biomedical Technology
Global Glycomics/Glycobiology Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Exonucleases Market
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
Oligonucleotide Synthesis Market
Biomedical Technology
Brain Biomarkers Market