
 Imaging Biomarkers Market | 2026-2036
Imaging Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Imaging Biomarkers Market Outlook
North American imaging infrastructure is rewriting competitive dynamics across the biomarker landscape. Siemens Healthineers AG leverages its molecular imaging installed base to sustain recurring revenue from radiopharmaceutical consumables. GE HealthCare Technologies Inc. anchors its position through cyclotron networks that supply short-lived isotopes to regional hospital systems. Philips Healthcare differentiates via integrated informatics platforms that connect scanner hardware to AI-assisted quantification workflows.
Imaging biomarkers comprise quantifiable biological indicators detected through medical imaging modalities, typically requiring standardized acquisition protocols and validated analysis algorithms to ensure reproducibility across clinical sites. These markers serve primarily to stratify patient populations, monitor therapeutic response, and predict disease progression in regulated healthcare environments. PET scan applications in oncology command premium positioning due to the technical complexity of radiotracer synthesis and the specialized distribution infrastructure required for fluorinated compounds. MRI-based neurological biomarkers occupy a mature but expanding segment where digital imaging protocols enable multicenter trial standardization. Contrast-enhanced imaging across cardiology applications represents a high-velocity growth corridor driven by perfusion quantification software adoption.
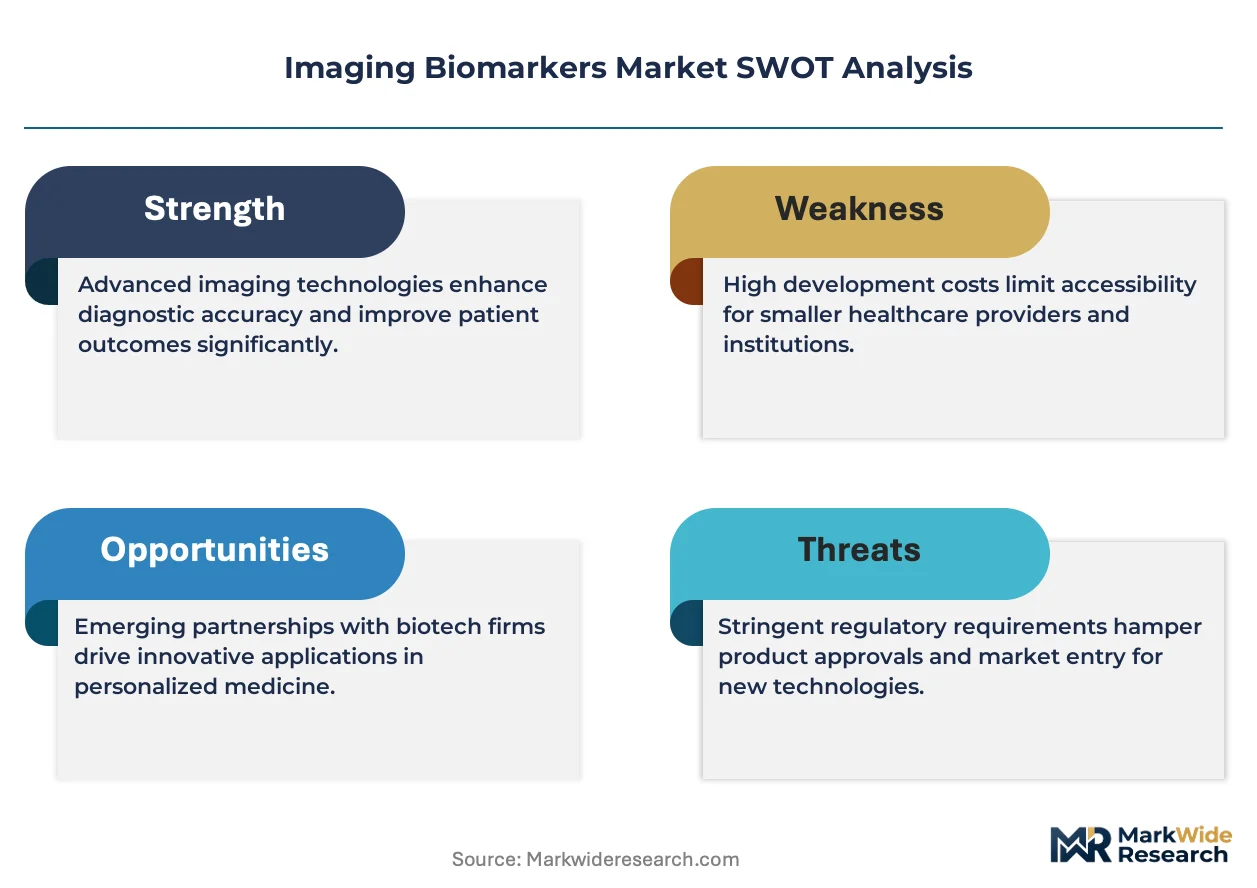
The FDA oversees imaging biomarker qualification through its biomarker qualification program, while the EMA's parallel scientific advice process shapes European development pathways for companion diagnostics. ISO 13485 quality management requirements and IEC 62304 software lifecycle standards constrain market entry for new platform developers. Stakeholders must monitor evolving reimbursement frameworks for quantitative imaging biomarkers as payors shift toward value-based coverage determinations.
Market Dynamics
The imaging biomarkers market is undergoing structural compression as AI-enabled quantification tools displace manual image interpretation, forcing radiology departments to reconfigure workflow economics around software licensing rather than per-scan professional fees.
Growth Catalysts
- AI-enabled diagnostic workflows:FDA breakthrough device designations accelerate commercialization timelines for algorithm-based quantification tools, reducing regulatory friction for novel biomarker platforms.
- Medicare reimbursement expansion:United States payor policies increasingly cover companion diagnostic imaging procedures, creating direct revenue pathways for PET tracer applications in oncology treatment planning.
- Radiopharmaceutical infrastructure:Regional cyclotron networks address distribution constraints for short-lived fluorinated isotopes, enabling same-day tracer delivery to community hospital systems.
Market Restraints
- Isotope supply concentration:Molybdenum-99 production concentrates in a handful of aging research reactors, creating vulnerability to unplanned outages that disrupt SPECT imaging availability.
- Capital intensity of MRI biomarker deployment:Standardized acquisition protocols require hardware upgrades and coil replacements that strain radiology capital budgets at mid-tier hospitals.
- Regulatory fragmentation:Divergent qualification pathways between FDA biomarker qualification programs and EMA parallel scientific advice processes extend development timelines for multinational trials.
Strategic Opportunities
- Neurological MRI biomarkers:Digital imaging protocols enable multicenter trial standardization for neurodegenerative disease monitoring, opening white space in Alzheimer's progression tracking applications.
- Cardiology perfusion quantification:Contrast-enhanced imaging software adoption accelerates in interventional cardiology suites, creating demand for integrated hardware-software bundles.
- ISO 13485 certification arbitrage:Quality management compliance gaps among emerging platform developers create acquisition targets for established players seeking validated manufacturing processes.
Industry Challenges
- Quantification algorithm validation:Reproducibility across clinical sites requires extensive phantom studies and inter-reader variability trials that extend time-to-market for new biomarker algorithms.
- Legacy PACS integration:Hospital information systems built on DICOM standards struggle to accommodate AI-generated structured reports, forcing costly middleware development.
- Radiochemist talent scarcity:PET tracer synthesis demands specialized expertise in good manufacturing practice radiochemistry that outpaces training program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Imaging Biomarkers Market |
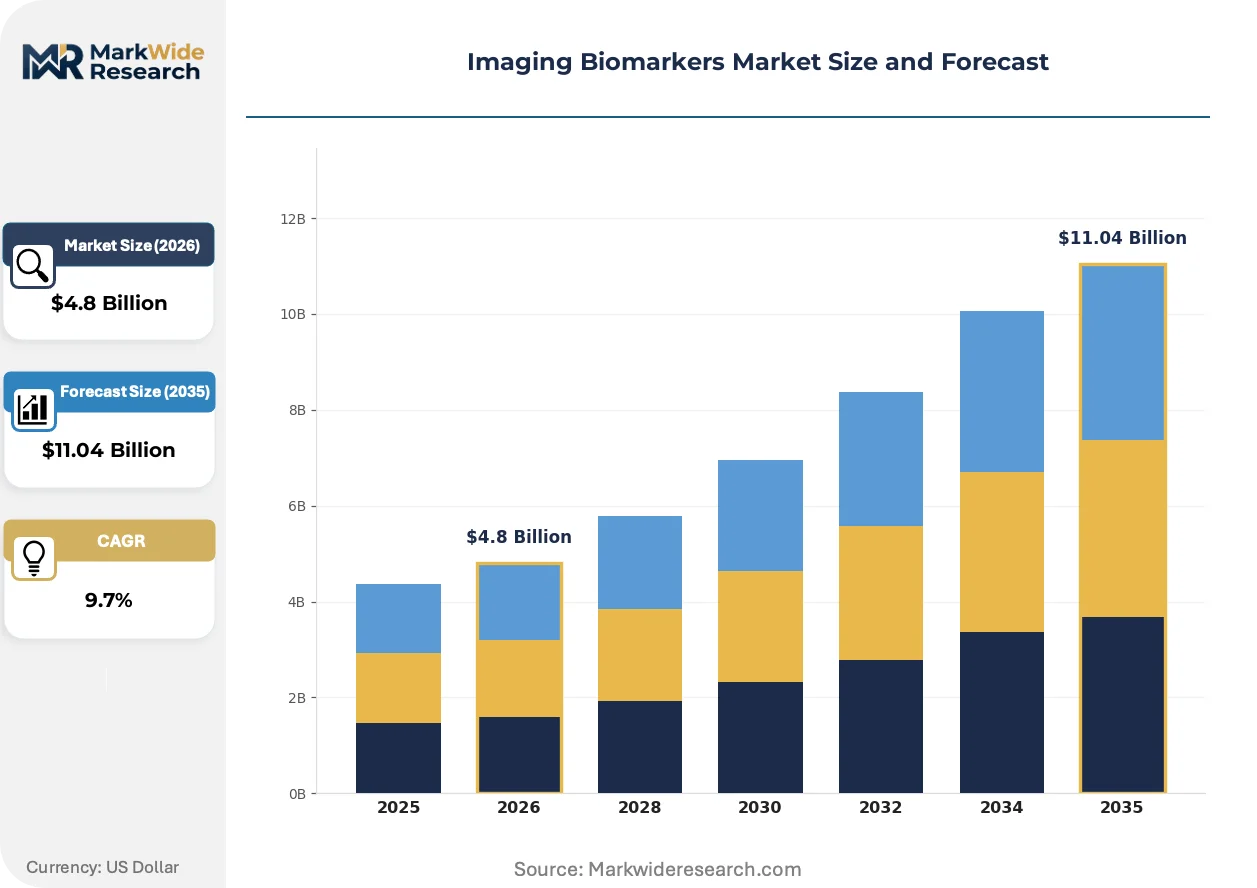
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MRI, CT Scan, PET Scan, Ultrasound Application: Oncology, Cardiology, Neurology, Orthopedics Technology: 3D Imaging, Molecular Imaging, Digital Imaging, Contrast-Enhanced Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics |
| Companies Covered | Siemens Healthineers AG, GE HealthCare Technologies Inc., Philips Healthcare, Thermo Fisher Scientific Inc., Merck KGaA, Fujifilm Holdings Corporation, PerkinElmer Inc., Roche Diagnostics International Ltd., Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Imaging Biomarkers Market Strategic Shifts
Computational pathology and machine learning are collapsing traditional boundaries between imaging acquisition and diagnostic interpretation, compressing value chains that previously separated hardware manufacturers from clinical decision support.
Deep learning-based lesion segmentation is collapsing the manual contouring bottleneck in radiation oncology, enabling automated tumor volume delineation that previously consumed hours of physician time. Academic medical centers in the United States are deploying these tools for treatment planning, compressing the interval between scan acquisition and therapy initiation.
EMA's Medical Device Regulation (MDR) implementation is tightening conformity assessment requirements for software-as-a-medical-device, forcing imaging biomarker developers to restructure quality management systems around notified body oversight. European radiology departments are prioritizing CE-marked quantification tools, compressing procurement cycles for unvalidated research algorithms.
Radiology group purchasing organizations are consolidating vendor selection around integrated platform contracts that bundle scanner hardware, AI software licenses, and maintenance services. Hospital systems in Germany and France are displacing point-solution procurement with multi-year enterprise agreements, concentrating purchasing power among integrated suppliers.
Imaging Biomarkers Market Segmentation
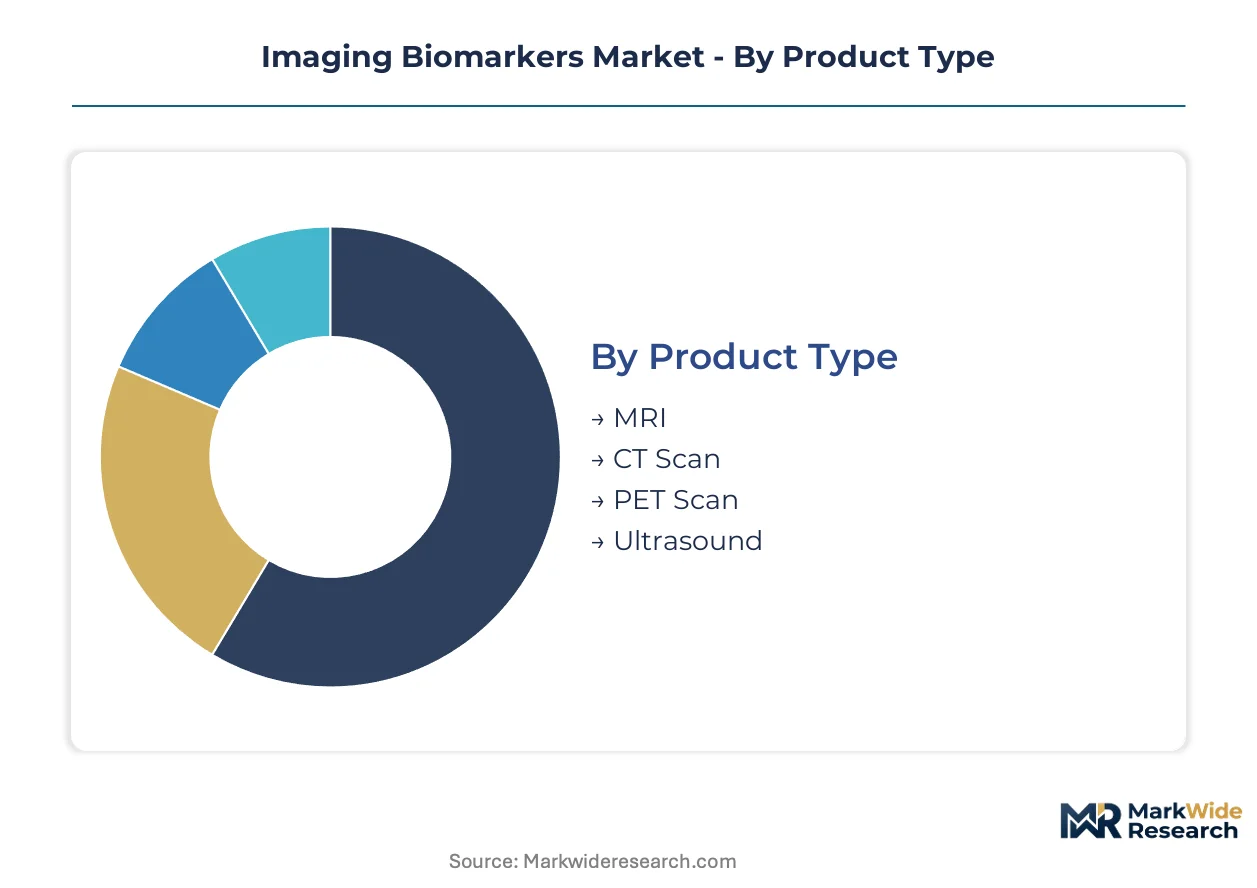
Imaging biomarkers demand heterogeneous deployment models across modalities, with each segment requiring distinct service infrastructure, regulatory pathways, and reimbursement frameworks. Segmentation clarity enables vendors to align R&D investment with specific clinical workflows and capital replacement cycles.
Product Type:
After-sales service intensity varies dramatically across modalities, with PET scanners demanding specialized radiopharmaceutical logistics and cyclotron maintenance contracts that generate recurring revenue streams exceeding hardware margins.
- PET Scan:Positron emission tomography systems detect metabolic activity through radiotracer distribution, requiring on-site radiochemistry capabilities or regional isotope supply chains. United States oncology departments at academic medical centers drive demand for precision treatment planning applications, constrained by molybdenum-99 production concentration in aging research reactors.
- MRI:Magnetic resonance imaging leverages magnetic fields and radio waves for soft-tissue contrast without ionizing radiation, enabling repeated longitudinal monitoring. Neurological biomarker applications in Alzheimer's progression tracking concentrate demand at research hospitals with standardized digital imaging protocols.
- CT Scan:Computed tomography systems use X-ray rotation for rapid anatomical visualization, suited for emergency and interventional workflows.
- Ultrasound:Acoustic imaging platforms offer portable, real-time visualization without radiation exposure, dominating point-of-care and obstetric applications.
By volume, CT scan installations lead due to lower capital barriers and broader clinical utility. By growth pace, PET scan deployments are climbing the fastest, propelled by Medicare reimbursement expansion for companion diagnostic procedures.
Application:
Clinical application segmentation tracks reimbursement policy divergence, with oncology commanding premium pricing for tracer-based diagnostics while cardiology volumes scale through software-enabled perfusion quantification.
- Oncology:Tumor characterization, staging, and treatment response monitoring dominate PET tracer utilization, with FDG-PET established for solid malignancies and novel radiopharmaceuticals expanding to prostate and neuroendocrine indications. United States Medicare policies increasingly cover companion diagnostic imaging, creating direct revenue pathways.
- Cardiology:Myocardial perfusion imaging and viability assessment drive contrast-enhanced CT and MRI adoption, with quantification software reducing inter-reader variability. Interventional cardiology suites in Germany and France prioritize integrated hardware-software bundles.
- Neurology:Neurodegenerative disease biomarkers for Alzheimer's and Parkinson's progression tracking concentrate at academic medical centers with multicenter trial infrastructure.
- Orthopedics:Musculoskeletal imaging for implant positioning, inflammation assessment, and sports injury evaluation serves ambulatory surgical centers and specialized clinics.
Oncology generates the highest revenue per procedure. Cardiology is gaining share fastest as perfusion software penetrates community hospital systems.
Technology:
Technology segmentation reflects the shift from hardware-centric to algorithm-driven value capture, with AI-enabled quantification tools displacing manual interpretation and restructuring radiology department economics.
- Molecular Imaging:Radiotracer-based detection of cellular and molecular processes enables functional assessment beyond anatomical structure, requiring specialized radiochemistry expertise and cyclotron infrastructure. PET applications in precision oncology concentrate demand at centers with on-site synthesis capabilities.
- Digital Imaging:Standardized acquisition protocols and AI-assisted analysis algorithms enable multicenter trial reproducibility for neurological biomarkers, with EMA MDR implementation tightening conformity assessment for software-as-a-medical-device.
- 3D Imaging:Volumetric reconstruction from tomographic data supports surgical planning and radiation therapy targeting, with deep learning-based lesion segmentation automating tumor contouring.
- Contrast-Enhanced Imaging:Pharmacological agents improve tissue differentiation in MRI and CT, with gadolinium-based and iodinated formulations subject to renal safety monitoring protocols.
Digital imaging commands the largest installed base. Molecular imaging shows the steepest expansion trajectory as novel radiopharmaceuticals receive FDA breakthrough designations.
End User:
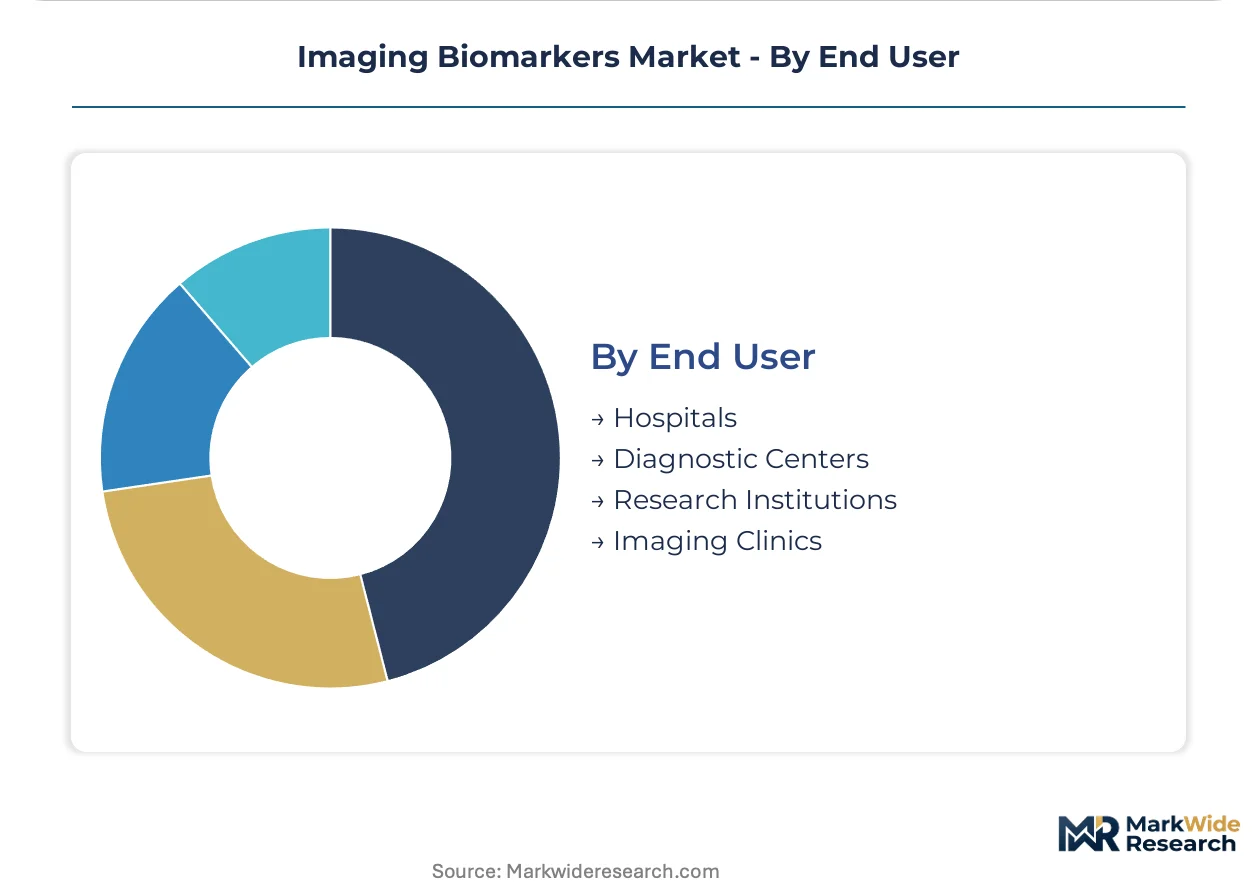
End-user segmentation captures capital intensity gradients, with hospitals absorbing full-modalities infrastructure while imaging clinics specialize in high-volume, protocolized procedures.
- Hospitals:Integrated health systems deploy comprehensive imaging portfolios across emergency, inpatient, and outpatient settings, with radiology group purchasing organizations consolidating vendor selection around multi-year enterprise agreements bundling hardware, software, and maintenance.
- Diagnostic Centers:Dedicated imaging facilities optimize throughput for routine procedures, with United States outpatient centers benefiting from favorable site-of-service reimbursement differentials for PET and MRI.
- Research Institutions:Academic medical centers drive biomarker validation and qualification studies, requiring ISO 13485-compliant manufacturing partnerships for investigational tracer production.
- Imaging Clinics:Specialized outpatient facilities focus on high-margin procedures such as breast MRI or coronary CT angiography, constrained by legacy PACS integration costs for AI-generated structured reports.
Hospitals account for the greatest absolute procedure volume. Diagnostic centers are expanding most quickly as payors shift toward value-based coverage determinations favoring lower-cost settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cyclotron networks radiating from university medical centers in Boston and Baltimore supply short-lived fluorinated isotopes across the eastern United States, anchoring the country's role in precision oncology infrastructure.
United States
Medicare reimbursement expansion for companion diagnostic imaging procedures drives PET tracer utilization at academic medical centers. FDA breakthrough device designations for AI-enabled diagnostics accelerate commercialization timelines for algorithm developers. The Greater Boston cluster hosts cyclotron facilities supplying same-day radiopharmaceutical delivery to regional hospital systems.
Germany
Radiology group purchasing organizations consolidate vendor selection around multi-year enterprise agreements bundling hardware, software, and maintenance services. EMA Medical Device Regulation implementation tightens conformity assessment requirements for software-as-a-medical-device. The Munich-Stuttgart corridor concentrates integrated platform procurement for interventional cardiology suites.
China
Domestic cyclotron manufacturing capacity expands to reduce dependency on imported fluorinated isotopes for oncology applications. NMPA streamlined review pathways for innovative medical imaging devices shorten registration timelines. The Yangtze River Delta cluster anchors regional distribution networks for short-lived radiopharmaceuticals.
Japan
PET tracer synthesis capabilities concentrate at university hospitals with on-site radiochemistry infrastructure for neurodegenerative disease research. PMDA parallel consultation processes align biomarker qualification studies with international trial standards. The Kanto region around Tokyo hosts multicenter validation networks for Alzheimer's progression tracking protocols.
United Kingdom
NHS England specialized commissioning frameworks create procurement pathways for quantitative imaging biomarkers in cancer care pathways. MHRA post-Brexit regulatory autonomy enables accelerated access schemes for AI-enabled diagnostic tools. The Oxford-Cambridge-London arc concentrates research institution demand for ISO 13485-compliant investigational tracer production.
Imaging Biomarkers Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in radiochemistry and algorithm development. The imaging biomarkers market structures around three tiers: full-modality manufacturers with cyclotron networks, AI software vendors seeking hardware partnerships, and radiopharmaceutical suppliers with regional distribution reach. Strategic moves concentrate on backward integration into isotope production and forward integration into quantification software licensing.
Among diversified health technology conglomerates, Siemens Healthineers AG and GE HealthCare Technologies Inc. exemplify platform integrators with cyclotron-installed bases generating recurring consumable revenue. Philips Healthcare occupies a position emphasizing informatics connectivity over hardware manufacturing. These three anchors represent distinct strategic postures: German-engineered molecular imaging systems, American cyclotron network density, and Dutch-originated software-hardware integration.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE HealthCare Technologies Inc. |
| Philips Healthcare |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Fujifilm Holdings Corporation |
| PerkinElmer Inc. |
| Roche Diagnostics International Ltd. |
| Canon Medical Systems Corporation |
| Others |
Value Chain & Pricing Dynamics
Molybdenum-99 production concentration in aging research reactors across Canada, the Netherlands, and South Africa anchors pricing power for SPECT isotope suppliers downstream. PET tracer synthesis commands premium positioning where regional cyclotron networks constrain same-day delivery feasibility, concentrating margin capture with integrated manufacturers possessing captive isotope supply.
Pricing Analysis
Volume-discount tiering separates academic medical center enterprise agreements from community hospital spot purchases for radiopharmaceutical consumables. Pricing stratifies across FDA breakthrough-designated AI quantification tools, CE-marked software under EMA MDR, and unvalidated research algorithms lacking regulatory clearance. Cost compression in standard MRI coil replacements intensifies as mid-tier hospitals defer hardware upgrade cycles. Community imaging clinics exhibit highest price sensitivity to per-scan software licensing fees, while integrated health systems absorb bundled platform contracts with less procurement friction.
Supply Chain Analysis
Upstream feedstock for fluorinated radiotracers draws from cyclotron facilities concentrated in the United States, Germany, and Japan, with emerging domestic capacity expansion in China reducing import dependency. Key inputs encompass enriched water targets, specialized vacuum pumps, and gadolinium-based contrast agents subject to renal safety monitoring protocols. Single-source vulnerability permeates molybdenum-99 generator supply following research reactor decommissioning schedules. Distribution runs through regional radiopharmacy networks delivering short-lived isotopes within six-hour half-life windows to hospital nuclear medicine departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as radiology group purchasing organizations consolidate procurement around interoperable hardware-software bundles rather than discrete point solutions. The collapse of manual interpretation workflows into automated quantification pipelines restructures value capture toward algorithm licensors with validated FDA submissions.
For Market Incumbents: Insulate recurring revenue from cyclotron-installed bases by embedding multi-year radiopharmaceutical supply contracts with penalty clauses for volume migration. Deepen backward integration into isotope production to offset molybdenum-99 supply disruptions threatening SPECT imaging availability. Prioritize ISO 13485 certification maintenance as EMA MDR implementation tightens conformity assessment for software-as-a-medical-device exports into European hospital systems. For New Entrants and Emerging Players: Build out AI-assisted quantification tools targeting neurological MRI biomarkers for Alzheimer's progression tracking, where multicenter trial standardization creates demand for validated analysis algorithms. Penetrate community hospital systems in the United States underserved by integrated platform vendors through SaaS-tiered pricing models reducing upfront capital barriers. Pursue FDA breakthrough device designation pathway to accelerate commercialization timelines relative to standard 510(k) review cycles. For Investors and Strategic Acquirers: Capital is best deployed toward ISO 13485-compliant radiochemistry specialists with validated manufacturing processes and regional distribution reach, as quality management compliance gaps among emerging platform developers create asymmetric acquisition value. Long-term viability hinges on positioning within algorithm-driven workflow economics displacing per-scan professional fees. Monitor Medicare reimbursement policy shifts for quantitative imaging biomarkers as the inflection signal indicating payor acceptance of AI-generated structured reports.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Network Expansion | Regional isotope production reduces dependency on aging research reactors in Canada and the Netherlands. |
| FDA Breakthrough Device Designation | Accelerated review timelines compress time-to-market for AI-enabled quantification algorithms in oncology. |
| ISO 13485 Certification Investment | Quality management compliance enables EMA MDR conformity assessment for European software distribution. |
| Integrated Platform Procurement | Multi-year enterprise agreements bundle hardware, software, and maintenance to lock in radiology GPO consolidation. |
| Radiopharmaceutical Supply Contracting | Long-term offtake agreements with academic medical centers secure recurring revenue from tracer consumables. |
Study Parameters
Cross-validation between primary interviews with nuclear medicine physicians, radiology department chairs, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary sources including FDA 510(k) and breakthrough device filings, EMA parallel scientific advice records, CMS Medicare reimbursement determinations, and hospital procurement database extracts. Bottom-up segmentation modeling triangulates with top-down macroeconomic calibration across the analysis window.
Calibration against historical cyclotron installation records and radiopharmaceutical consumption patterns validates the projection framework. Segmentation dimensions span imaging modality, clinical application, technology type, and end-user facility tier. CAGRs derive from fitted growth curves incorporating Medicare policy expansion trajectories, AI regulatory approval velocities, and isotope supply infrastructure buildout schedules across modeled geographies.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-rich technology conglomerates entering algorithm development would shift outcomes through accelerated R&D spending. Cross-checking against CMS national coverage determination timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Multiplex Biomarker Imaging Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Global Bifida Ferment Lysate Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Global Molecular Biosensors Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
E2 Antibody Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Global Oncology Based in-Vivo CRO Market
Biomedical Technology
Stem Cell Banking Market