
 Recombinant DNA Market | 2026-2036
Recombinant DNA Market Size, Share, and Industry Trends Forecast 2026-2036
Recombinant DNA Market Analytics
CRISPR-based gene editing is reshaping recombinant DNA workflows by enabling programmable, site-specific modifications that bypass traditional restriction enzyme cloning. Thermo Fisher Scientific leverages its integrated reagent-to-instrument portfolio to dominate consumable supply chains for academic and commercial labs. Novartis anchors its position through captive demand for CAR-T manufacturing, where plasmid DNA serves as a critical starting material. Amgen competes by specializing in large-molecule biologics production that depends on stable recombinant cell lines.
Recombinant DNA comprises DNA molecules engineered through laboratory manipulation to combine genetic material from multiple sources, typically constructed using restriction enzymes, ligases, and host-vector systems such as bacterial plasmids or viral backbones. These constructs enable the expression of proteins, therapeutic genes, or modified organisms across pharmaceutical, agricultural, and diagnostic applications. Vectors and plasmids command the largest product volume share, driven by viral vector demand for gene therapy and mRNA vaccine templates. CRISPR and synthetic biology represent the fastest-expanding technology segments, where automated DNA synthesis and multiplexed editing reduce design-build-test cycles. Agricultural biotechnology lags gene therapy and vaccine development in revenue contribution but sustains margin pools in trait-stacked crop development programs.
FDA's gene therapy guidance and EMA's ATMP framework impose stringent quality and traceability standards on recombinant DNA inputs, effectively filtering non-GMP suppliers from clinical-grade supply chains. EPA and USDA-APHIS oversight of genetically modified organisms further shapes product development pathways for agricultural applications. ISO 13485 and ICH Q5D standards govern plasmid identity and stability testing, creating compliance barriers that favor established manufacturers with validated quality systems. Stakeholders must monitor evolving regulatory convergence between gene editing oversight and traditional biologics frameworks to anticipate qualification requirements for next-generation modalities.
Market Dynamics
Gene therapy manufacturing pipelines are compressing plasmid DNA supply chains as FDA and EMA accelerated approval pathways force contract manufacturers to qualify GMP-grade inputs faster than capacity expansion permits.
Growth Catalysts
- ATMP Framework:EMA's advanced therapy medicinal products pathway compresses clinical-to-commercial timelines for viral vector producers, pulling forward demand for qualified plasmid DNA templates.
- Cell therapy manufacturing:CAR-T and CAR-NK production facilities in Boston and San Diego are absorbing multi-kilogram plasmid orders previously reserved for research-grade supply.
- CRISPR multiplexing:Automated guide RNA synthesis platforms are collapsing design-build-test cycles from weeks to days, expanding construct throughput per facility.
Market Restraints
- GMP-grade fermentation capacity:Stainless steel bioreactor availability for plasmid production concentrates among three North American contract manufacturers, creating queue bottlenecks.
- Endotoxin clearance costs:Chromatography resin and membrane filtration consumables for plasmid purification have risen 40% since 2022, compressing margins on clinical-grade batches.
- Host cell licensing:Dharmacon and Broad Institute CRISPR patents require per-construct royalties that accumulate across multiplexed editing workflows.
Strategic Opportunities
- India CDMO expansion:CDSCO's streamlined biosimilar pathway and PLI scheme incentives are attracting plasmid manufacturing investment to Hyderabad and Bengaluru.
- mRNA vaccine templates:Self-amplifying RNA constructs require novel plasmid backbones with reduced immunogenicity sequences, opening design-service revenue pools.
- Continuous processing:Integrated perfusion fermentation and inline analytics are enabling real-time release testing that cuts batch release timelines from 21 days to 72 hours.
Industry Challenges
- Qualified personnel scarcity:GMP-grade plasmid manufacturing requires hybrid skills in microbial fermentation and gene therapy regulatory filing that training programs have not scaled.
- Legacy quality system integration:Academic spinouts entering contract manufacturing struggle to adapt paper-based batch records to FDA's data integrity expectations for gene therapy inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombinant DNA Market |
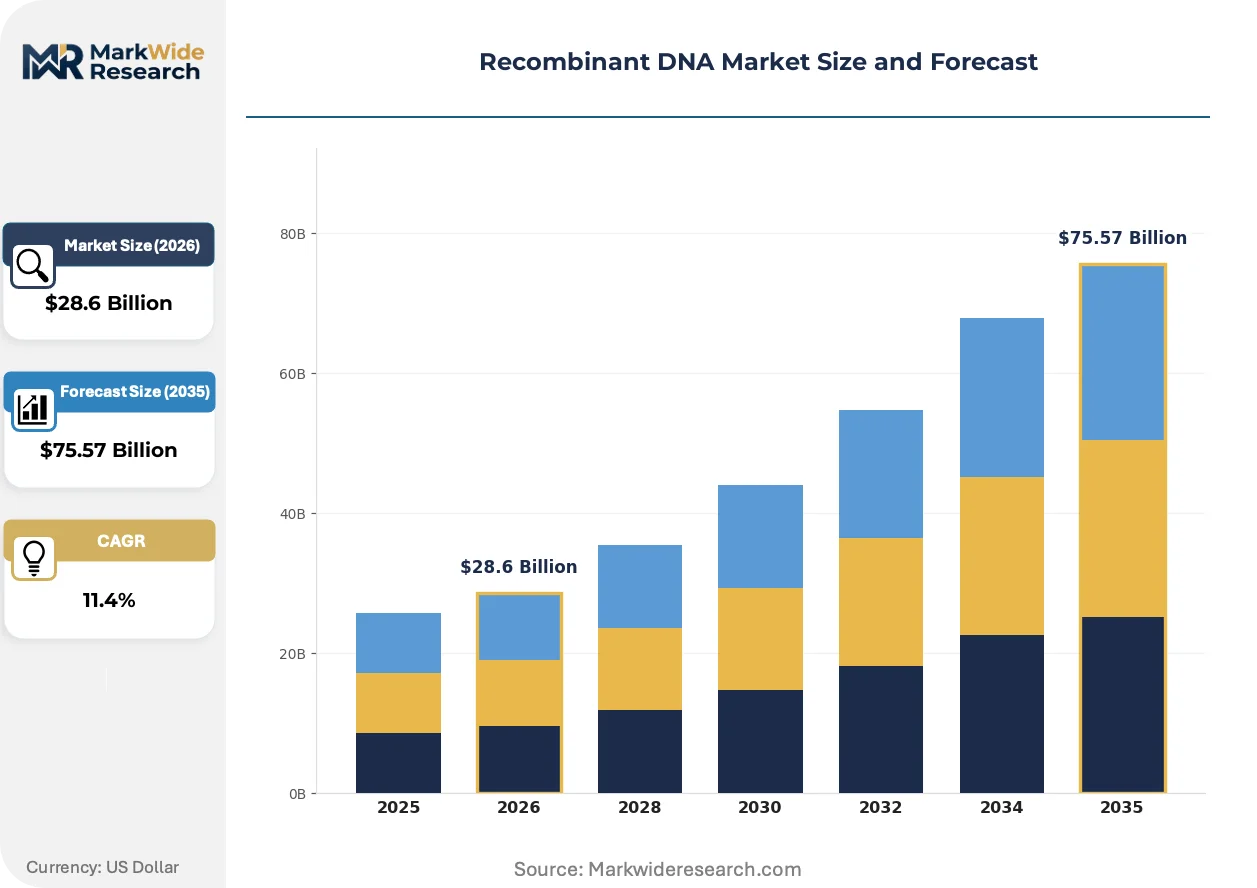
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vectors, Enzymes, Linear DNA, Plasmids Application: Gene Therapy, Vaccine Development, Agricultural Biotechnology, Diagnostics End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Research Laboratories Technology: CRISPR, Synthetic Biology, Gene Editing, Sequencing |
| Companies Covered | Thermo Fisher Scientific Inc., Novartis AG, Amgen Inc., F. Hoffmann-La Roche Ltd., Pfizer Inc., Merck KGaA, GenScript, GlaxoSmithKline plc., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombinant DNA Market Evolving Landscape
Automated DNA synthesis and AI-guided construct optimization are collapsing the traditional design-build-test cycle, while regulatory frameworks race to keep pace with editing precision.
Cloud-based LIMS platforms are digitizing plasmid sequence verification and batch release documentation across contract manufacturing organizations. Gene therapy CDMOs in Research Triangle Park and Basel are adopting these systems to support FDA's real-time review pilot programs. The shift is digitizing quality assurance workflows that previously required 14-day paper-based review cycles.
REACH's updated restriction on per- and polyfluoroalkyl substances is forcing European plasmid manufacturers to reformulate chromatography buffer systems and single-use bioprocess containers. The industrial consequence is a 12-18 month requalification timeline for existing GMP processes. German and Swiss CDMOs are responding by accelerating validation of fluorine-free alternatives ahead of the 2025 enforcement window.
Academic research groups are consolidating purchasing through centralized core facilities rather than maintaining individual plasmid preparation laboratories. This channel consolidation is displacing small-scale reagent distributors that previously served principal investigator accounts. The pattern is most visible in Boston and San Francisco, where university procurement offices have mandated preferred vendor agreements with integrated supply platforms.
Recombinant DNA Market Segmentation
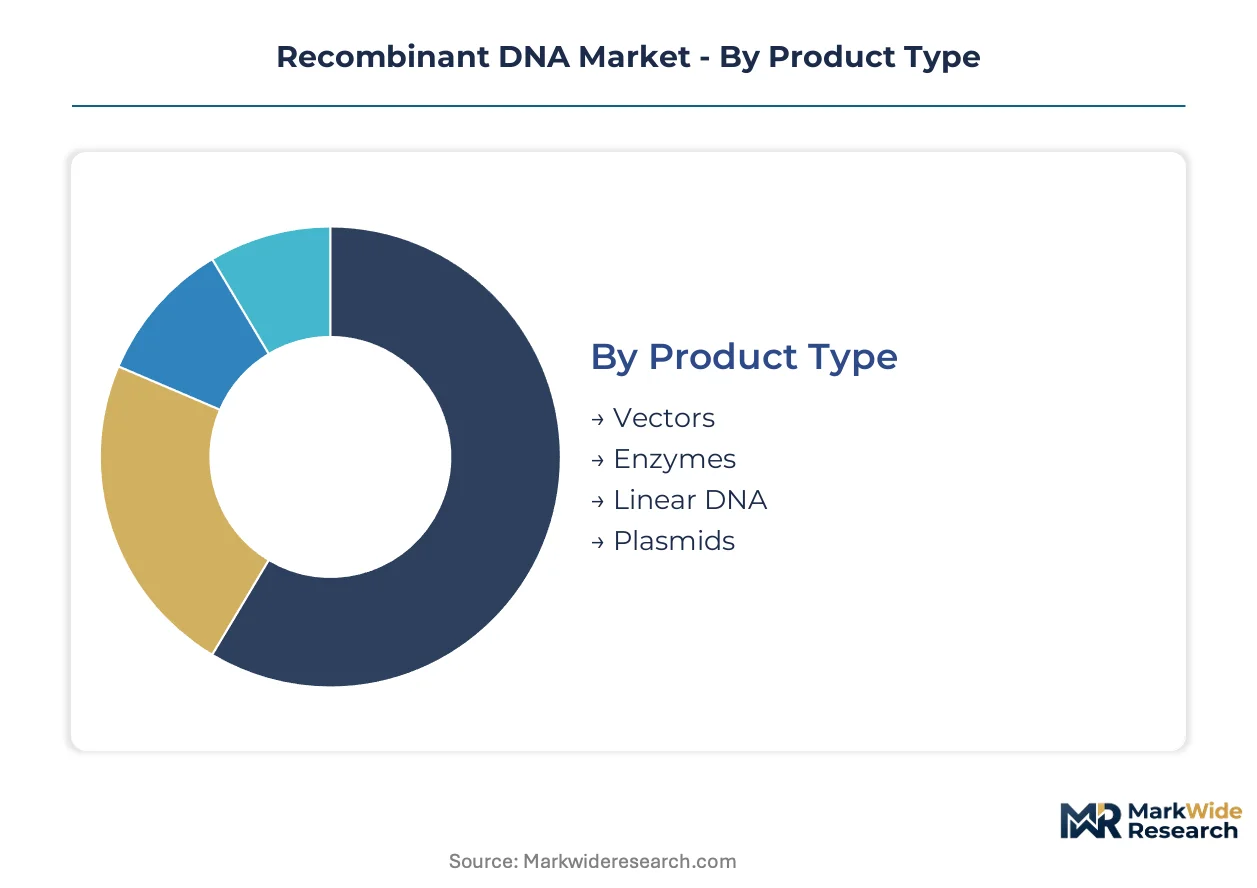
Recombinant DNA supply chains fragment across four critical dimensions. Product specifications determine manufacturing complexity and regulatory burden. Application focus dictates capacity allocation and margin structure. End-user procurement patterns separate GMP-grade from research-grade demand tiers.
Product Type:
Cost tier stratification separates high-purity clinical inputs from commodity research reagents, with purification burden driving margin dispersion.
- Vectors:Viral and non-viral delivery vehicles incorporate tissue-specific targeting moieties and regulatory elements. Adeno-associated virus demand from Boston and San Diego gene therapy facilities is exhausting qualified plasmid template supply. GMP-grade lentiviral vector production requires endotoxin clearance protocols that extend batch release timelines.
- Plasmids:Circular DNA backbones carry antibiotic resistance markers and origin-of-replication sequences for host propagation. CAR-T manufacturers in Research Triangle Park are absorbing multi-kilogram orders previously reserved for research supply. FDA's gene therapy guidance imposes identity and stability testing that filters non-validated suppliers.
- Enzymes:Restriction endonucleases, ligases, and polymerases catalyze construct assembly reactions. Thermo Fisher Scientific dominates consumable supply chains through integrated reagent-to-instrument portfolios.
- Linear DNA:PCR-amplified or synthetic double-stranded fragments enable rapid construct prototyping without bacterial propagation. Automated synthesis platforms are collapsing design-build-test cycles from weeks to days.
Vectors hold installed capacity. Plasmids is rotating up the share rankings.
Application:
Volume concentration in therapeutic modalities is displacing agricultural biotechnology from revenue leadership despite sustained trait-stacked crop programs.
- Gene Therapy:Viral vector manufacturing and CRISPR-edited cell therapies depend on qualified DNA inputs from GMP-certified facilities. FDA and EMA accelerated approval pathways compress development timelines and expand demand for traceable plasmid templates. Novartis anchors demand through captive CAR-T manufacturing requirements.
- Vaccine Development:mRNA and DNA vaccine templates require novel plasmid backbones with reduced immunogenicity sequences. Self-amplifying RNA constructs are opening design-service revenue pools for contract manufacturers with synthetic biology capabilities.
- Agricultural Biotechnology:Trait-stacked crop development sustains margin pools through regulatory-compliant transformation vectors. EPA and USDA-APHIS oversight shapes product development pathways for genetically modified organism field releases.
- Diagnostics:Recombinant DNA constructs serve as calibrators, controls, and amplification targets in molecular testing platforms. Academic core facility consolidation is displacing small-scale distributors in Boston and San Francisco procurement channels.
Gene Therapy commands capacity allocation priority. Vaccine Development is climbing the fastest among application segments.
End User:
Customer type determines quality system requirements, with GMP-grade procurement separating pharmaceutical manufacturers from research laboratories.
- Pharmaceutical Companies:Integrated biopharma firms and gene therapy developers require batch records, stability data, and regulatory filing support. Amgen specializes in large-molecule biologics production dependent on stable recombinant cell lines.
- Biotechnology Firms:Venture-backed cell and gene therapy developers outsource plasmid manufacturing to contract organizations with validated quality systems. CDSCO's streamlined biosimilar pathway is attracting investment to Hyderabad and Bengaluru CDMOs.
- Academic Institutions:University core facilities consolidate purchasing through preferred vendor agreements with integrated supply platforms. Cloud-based LIMS adoption is digitizing sequence verification and batch release documentation.
- Research Laboratories:Principal investigator accounts face procurement office mandates displacing individual laboratory plasmid preparation. REACH's per- and polyfluoroalkyl substances restrictions are forcing 12-18 month requalification timelines for European suppliers.
Pharmaceutical Companies hold installed capacity. Biotechnology Firms is rotating up the share rankings.
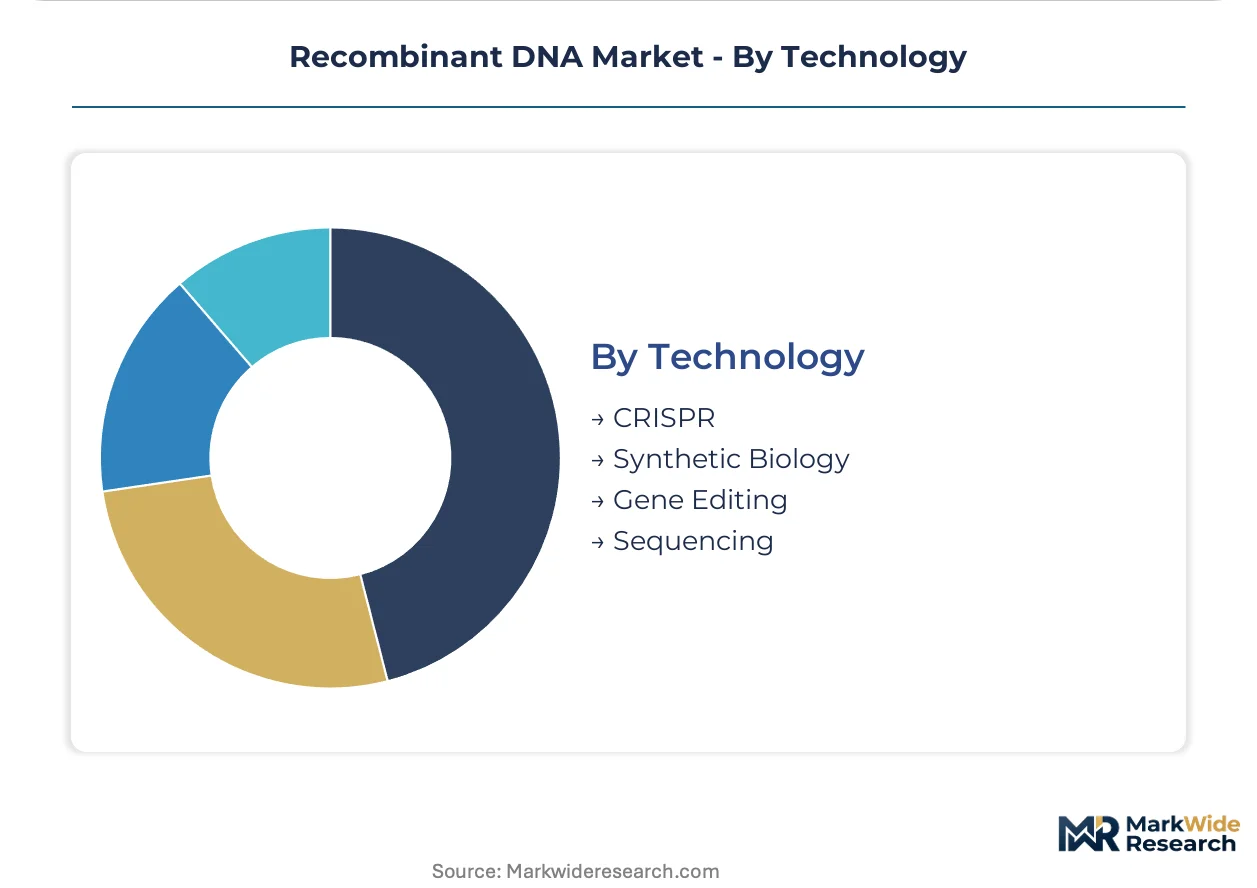
Technology:
Maturity curves separate established sequencing workflows from emerging multiplexed editing platforms that collapse development timelines.
- CRISPR:Programmable nucleases enable site-specific modifications bypassing traditional restriction enzyme cloning. Dharmacon and Broad Institute patent royalties accumulate across multiplexed editing workflows. Automated guide RNA synthesis platforms expand construct throughput per facility.
- Synthetic Biology:Automated DNA synthesis and AI-guided construct optimization integrate design and fabrication. Continuous processing with perfusion fermentation and inline analytics enables real-time release testing cutting batch release from 21 days to 72 hours.
- Gene Editing:Zinc finger nucleases and transcription activator-like effector nucleases retain niche applications requiring specific intellectual property positions. TALENs sustain demand in agricultural trait development with established regulatory dossiers.
- Sequencing:Next-generation and Sanger verification workflows confirm construct identity and clonality. ISO 13485 and ICH Q5D standards govern plasmid identity testing creating compliance barriers favoring established manufacturers.
Sequencing holds installed capacity. CRISPR is gaining share fastest among technology segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasmid DNA exports from the United States flow into contract manufacturing facilities across Germany and Switzerland, while Indian CDMOs in Hyderabad and Bengaluru supply research-grade constructs to European and North American biotechnology firms. Trade corridors concentrate around GMP-certified production hubs that serve gene therapy developers with accelerated regulatory timelines.
United States
FDA's accelerated approval pathways for cell and gene therapies compress development timelines for CAR-T manufacturers clustered in Boston and San Diego. The agency's gene therapy guidance imposes stringent identity and stability testing that filters non-GMP suppliers from clinical-grade supply chains. Research Triangle Park hosts expanding plasmid production facilities absorbing multi-kilogram orders previously reserved for research supply.
Germany
REACH's updated restriction on per- and polyfluoroalkyl substances forces plasmid manufacturers to reformulate chromatography buffer systems and single-use bioprocess containers. EMA's ATMP framework pulls forward demand for qualified plasmid DNA templates from viral vector producers. Swiss and German CDMOs in the Rhine corridor accelerate validation of fluorine-free alternatives ahead of enforcement windows.
India
CDSCO's streamlined biosimilar pathway and PLI scheme incentives attract plasmid manufacturing investment to Hyderabad and Bengaluru. Contract manufacturers leverage cost advantages in microbial fermentation to supply research-grade constructs for European and North American biotechnology firms. Quality system investments separate export-capable facilities from domestic-only suppliers.
Switzerland
Swissmedic's alignment with EMA standards enables seamless cross-border supply into EU gene therapy manufacturing networks. Basel-based CDMOs adopt cloud-based LIMS platforms to support real-time review pilot programs. The country's central European position anchors logistics corridors connecting German plasmid production to French and Italian pharmaceutical facilities.
China
NMPA's evolving gene therapy oversight creates qualification requirements for next-generation modalities that domestic manufacturers must anticipate. Yangtze River Delta biotech clusters invest in automated DNA synthesis platforms to collapse design-build-test cycles. Local contract manufacturers compete on synthetic biology capabilities rather than GMP-grade fermentation scale.
Recombinant DNA Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply segments. Integrated life science conglomerates dominate consumable supply chains through reagent-to-instrument portfolios, while biotechnology specialists anchor demand through captive manufacturing requirements. Three archetypes structure competition: diversified conglomerates with fermentation scale, gene therapy developers with backward-integrated plasmid demand, and synthetic biology platforms with automated synthesis capabilities. Capacity expansion and technology licensing constitute the dominant competitive moves as qualified GMP fermentation availability concentrates among North American contract manufacturers.
Among diversified conglomerates, Thermo Fisher Scientific occupies a position exemplifying integrated reagent-to-instrument control over academic and commercial laboratory supply. Novartis represents the gene therapy developer archetype with captive demand for plasmid DNA as a critical starting material in CAR-T manufacturing. Amgen sits within the large-molecule biologics specialist tier, dependent on stable recombinant cell lines for production workflows.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Novartis AG |
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Merck KGaA |
| GenScript |
| GlaxoSmithKline plc. |
| Sanofi S.A. |
| Others |
Value Network & Pricing Analysis
Boston and San Diego gene therapy clusters concentrate GMP-grade plasmid fermentation capacity among three North American contract manufacturers, granting these facilities substantial pricing leverage over CAR-T developers facing accelerated FDA approval timelines. This supply concentration compresses procurement options for clinical-grade DNA inputs while amplifying margin capture at qualified production sites.
Pricing Analysis
Next-generation CRISPR-edited constructs command substantial premiums over legacy restriction-enzyme cloning workflows, while research-grade plasmids face commoditization from automated synthesis platforms. Three-tier pricing structure across GMP-certified clinical, preclinical, and research tiers reflects endotoxin clearance burdens and batch documentation intensity. Cost compression in research-grade supply intensifies as academic core facilities consolidate purchasing through preferred vendor agreements. Biotechnology firms with captive CAR-T manufacturing exhibit lowest price sensitivity, while principal investigator accounts face procurement office mandates that prioritize cost over customization.
Supply Chain Analysis
Aldevron, Thermo Fisher Scientific, and Charles River Laboratories anchor North American GMP fermentation capacity, with expansion lagging viral vector demand from Boston and San Diego facilities. Stainless steel bioreactor availability draws from United States, Germany, and Switzerland production networks. Chromatography resin and membrane filtration consumables feed from specialized chemical suppliers concentrated in European industrial corridors. Single-source vulnerability concentrates in endotoxin clearance resin supply. Distribution runs through qualified CDMO relationships with direct-to-biopharma contractual offtake rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy manufacturing pipelines are recovering from pandemic-era capacity constraints as FDA accelerated approval pathways restore normalized demand patterns for GMP-grade DNA inputs.
For Market Incumbents: Insulate qualified fermentation capacity through backward integration into chromatography resin supply and exclusive host cell licensing agreements with Broad Institute and Dharmacon patent holders. Defensive patent accumulation around novel plasmid backbones for self-amplifying RNA constructs protects margin pools from synthetic biology platform entrants. Priority investment in continuous processing infrastructure with inline analytics supports real-time release testing that compresses batch timelines from 21 days to 72 hours. For New Entrants and Emerging Players: India CDMO expansion into Hyderabad and Bengaluru represents the most penetrable entry point, leveraging CDSCO streamlined biosimilar pathways and PLI scheme incentives to capture research-grade construct demand from European and North American biotechnology firms. Automated DNA synthesis platforms with AI-guided construct optimization enable design-service revenue pools without GMP fermentation scale requirements. Go-to-market positioning as synthetic biology specialists rather than commodity plasmid suppliers differentiates against incumbent fermentation assets. For Investors and Strategic Acquirers: Long-term, this sits as a platform technology play because CRISPR multiplexing and gene therapy manufacturing create durable demand for qualified DNA inputs across therapeutic modalities. Acquisition targets with validated quality systems and FDA gene therapy guidance compliance command premium positioning. Monitor EMA ATMP framework expansion and NMPA gene therapy oversight evolution as regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Fermentation Capacity Expansion | Stainless steel bioreactor investment in Research Triangle Park addresses queue bottlenecks for CAR-T plasmid supply. |
| Continuous Processing Validation | Perfusion fermentation with inline analytics enables real-time release testing under FDA pilot programs. |
| Fluorine-Free Buffer Requalification | German and Swiss CDMOs accelerate REACH-compliant chromatography system validation ahead of enforcement windows. |
| Cloud-Based LIMS Implementation | Gene therapy CDMOs digitize batch records to meet FDA data integrity expectations for accelerated review. |
| Patent Licensing Consolidation | Exclusive Dharmacon and Broad Institute CRISPR agreements reduce royalty stacking across multiplexed editing workflows. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with gene therapy manufacturing executives, regulatory affairs leads at CDMOs, academic core facility directors, and biotechnology procurement managers; and secondary validation through FDA gene therapy guidance documents, EMA ATMP framework submissions, ClinicalTrials.gov entries, and SEC filings from publicly traded biopharma firms. Bottom-up plasmid demand modeling by therapeutic modality triangulated against top-down market sizing from contract manufacturer capacity disclosures.
Forecast inputs considered viral vector production pipelines, CRISPR therapeutic advancement rates, and mRNA vaccine template requirements across the projection horizon. Segmentation dimensions modeled include product type, application focus, end-user procurement tier, and technology maturity curve. CAGRs derived from capacity expansion announcements correlated with regulatory approval velocity for cell and gene therapies.
Practitioners should monitor GMP fermentation queue lengths, chromatography resin pricing volatility, and patent licensing cost trajectories for early signals of supply-demand imbalance. Forecasts reflect assumptions regarding regulatory pathway stability and qualified personnel availability scaling. Quarterly review of CDSCO biosimilar pathway utilization and REACH fluorine-free alternative validation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Genetic Engineering Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
Gene Editing Market
Gene Editing & CRISPR
CRISPR Technology Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Gene Editing Off-Target Effect Detection Test Systems Market
Gene Editing & CRISPR
DNA Modifying Agents Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
Gene Editing Technology Market
Gene Editing & CRISPR
Global Plant Breeding and CRISPR Plant Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market
Gene Editing & CRISPR
Cas9 Nuclease Market