
 GCC Desert Air Coolers Market | 2026-2036
GCC Desert Air Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Desert Air Coolers Market Insights
Saudi Arabia is narrowing its dependence on imported desert air cooler units through localized assembly investments near Jeddah and Dammam industrial zones. Gree leverages backward integration into compressor and fan motor production to protect margin structures. Daikin Industries Ltd. anchors its GCC position through premium ducted cooler systems engineered for commercial installations. Midea Group Co Ltd. competes aggressively on portable cooler variants distributed through hypermarket wholesale channels.
Desert air coolers are evaporative cooling devices that force hot, dry ambient air through water-saturated cellulose or aspen wood wool pads, producing supply air at 15–25°C wet-bulb depression with power draws typically 75% below vapor-compression equivalents; they serve as the primary mechanical cooling solution in arid climates where relative humidity remains below 40%. Portable coolers lead volume shipments across the GCC due to low entry pricing and zero installation requirements, while ducted coolers capture the dominant margin pool through integrated building projects and five-year maintenance contracts. Rooftop coolers sustain growth in industrial and agricultural end uses where centralized air handling serves large footprint facilities.
Gulf Standardization Organization (GSO) energy labeling rules and Saudi Standards, Metrology and Quality Organization (SASO) mandatory efficiency ratings are reshaping product design priorities toward variable-speed pumps and corrosion-resistant housings. UAE's Emirates Authority for Standardization and Metrology (ESMA) now requires seasonal energy efficiency ratios for evaporative coolers sold in Dubai and Abu Dhabi emirates. Stakeholders must monitor how municipal green building codes in Qatar and Kuwait integrate evaporative cooling into mandatory renewable energy compliance pathways.
Market Dynamics
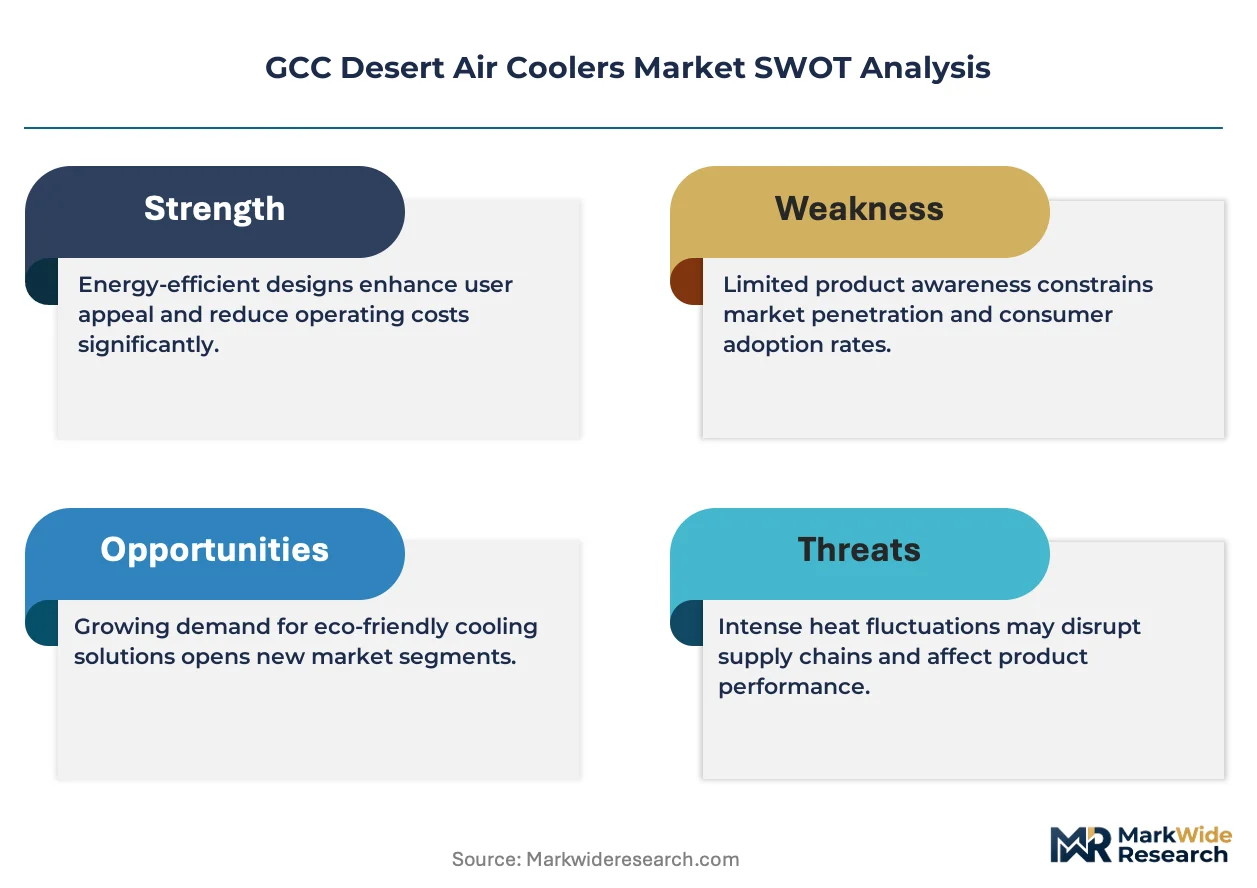
Energy-efficiency mandates from Gulf Standardization Organization and Saudi Standards, Metrology and Quality Organization are compressing legacy product margins while accelerating variable-speed pump adoption across Saudi Arabia and UAE assembly lines.
Growth Catalysts
- Riyadh-Dammam corridor heat extremes:Summer temperatures exceeding 50°C sustain replacement cycles for residential compound cooling systems. Dammam industrial zones anchor localized assembly investments.
- SASO mandatory efficiency ratings:Saudi Arabia's efficiency framework redirects procurement toward corrosion-resistant housings and variable-speed pump configurations.
- Cellulose pad material advances:Water-saturated cellulose media achieve 15–25°C wet-bulb depression with 75% lower power draw than vapor-compression alternatives.
Market Restraints
- Humidity ceiling constraint:Evaporative cooling effectiveness collapses above 40% relative humidity, limiting coastal UAE and Qatar deployment windows.
- Copper coil import dependence:GCC manufacturing relies on East Asian copper supply chains subject to freight volatility and currency fluctuation.
- ESMA seasonal efficiency testing costs:UAE's Emirates Authority for Standardization and Metrology certification requirements extend product launch timelines by 8–14 weeks for Dubai and Abu Dhabi emirate sales.
Strategic Opportunities
- Kuwait municipal green building codes:Evaporative cooling integration into renewable energy compliance pathways opens specification opportunities for integrated building projects.
- Qatar agricultural greenhouse segment:Rooftop cooler installations for large-footprint facilities remain underpenetrated versus Saudi Arabia's industrial adoption curve.
- Hypermarket wholesale channel expansion:Portable cooler variants distributed through Carrefour and Lulu networks capture price-sensitive residential demand with zero installation requirements.
Industry Challenges
- Variable-frequency drive programming expertise:SASO-compliant pump systems require controls engineers scarce in Jeddah and Dammam industrial zones.
- Five-year maintenance contract fulfillment:Ducted cooler installations demand service infrastructure that strains distributor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Desert Air Coolers Market |
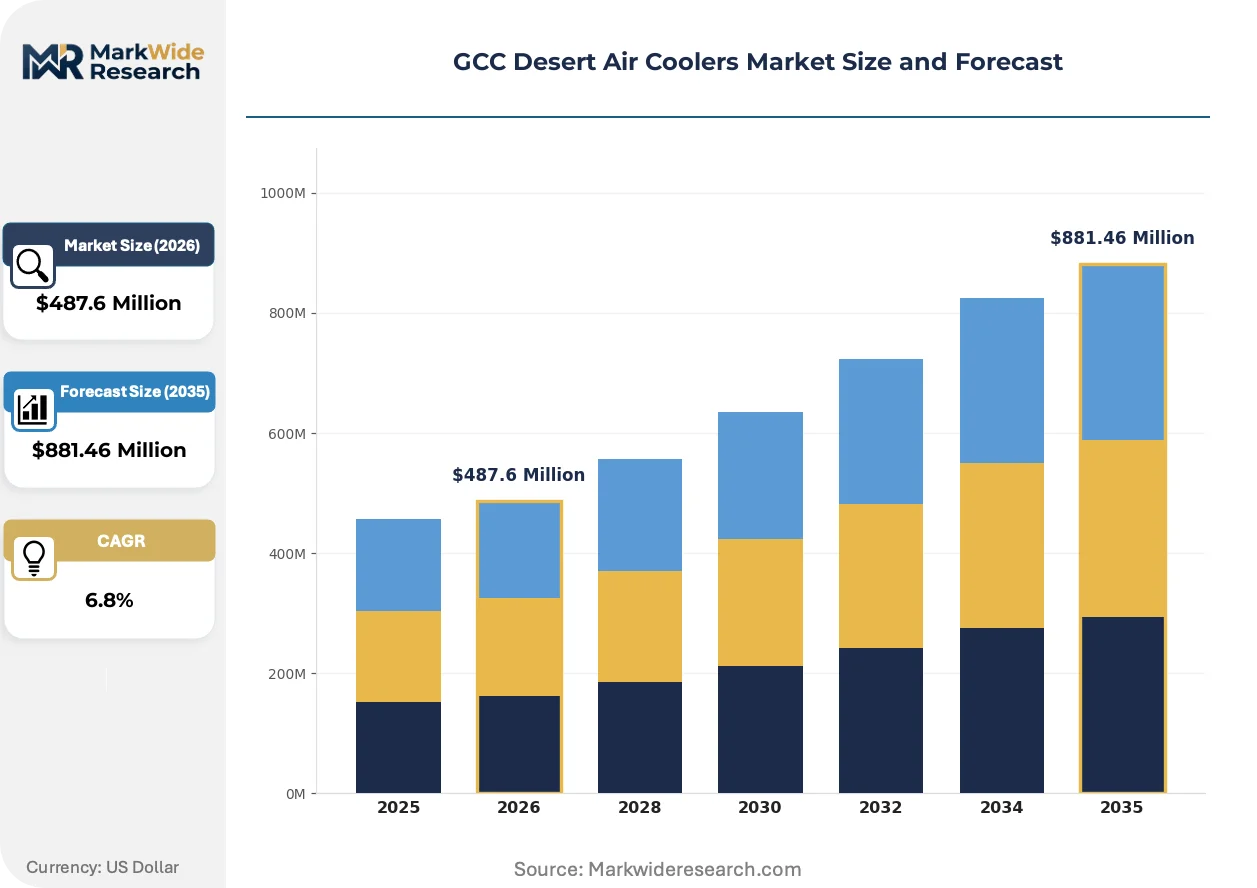
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Coolers, Window Coolers, Rooftop Coolers, Ducted Coolers End User: Residential, Commercial, Industrial, Agriculture Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale Installation Type: Outdoor, Indoor, Fixed, Mobile |
| Companies Covered | Gree, Evvoli, SuperGeneral, AuX, Crownline, Toshiba Corporation, Daikin Industries Ltd., Midea Group Co Ltd., Carrier, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Desert Air Coolers Market Trends and Innovations
Product design priorities across the GCC are converging on corrosion-resistant materials and smart pump controls as regulatory pressure intensifies and summer temperature records climb.
Variable-speed pump technology is migrating from fixed-speed asynchronous motors to electronically commutated permanent magnet drives. Commercial installers in Saudi Arabia's Riyadh-Dammam corridor specify these systems for five-year maintenance contracts. The shift compresses energy consumption curves while extending pad saturation cycles.
Gulf Standardization Organization energy labeling rules now mandate wet-bulb efficiency disclosure for all evaporative coolers sold across member states. Industrial buyers in UAE free zones delay procurement until ESMA seasonal energy efficiency ratio certification completes. Ducted cooler manufacturers respond by pre-certifying product families for Dubai and Abu Dhabi emirate deployment.
Residential buyers increasingly unbundle after-sales service from initial equipment purchase. Hypermarket channels in Saudi Arabia and UAE displace traditional HVAC contractor relationships for portable cooler segments. This pattern concentrates margin pressure on distributors while transferring service risk to third-party maintenance networks.
GCC Desert Air Coolers Market Segmentation
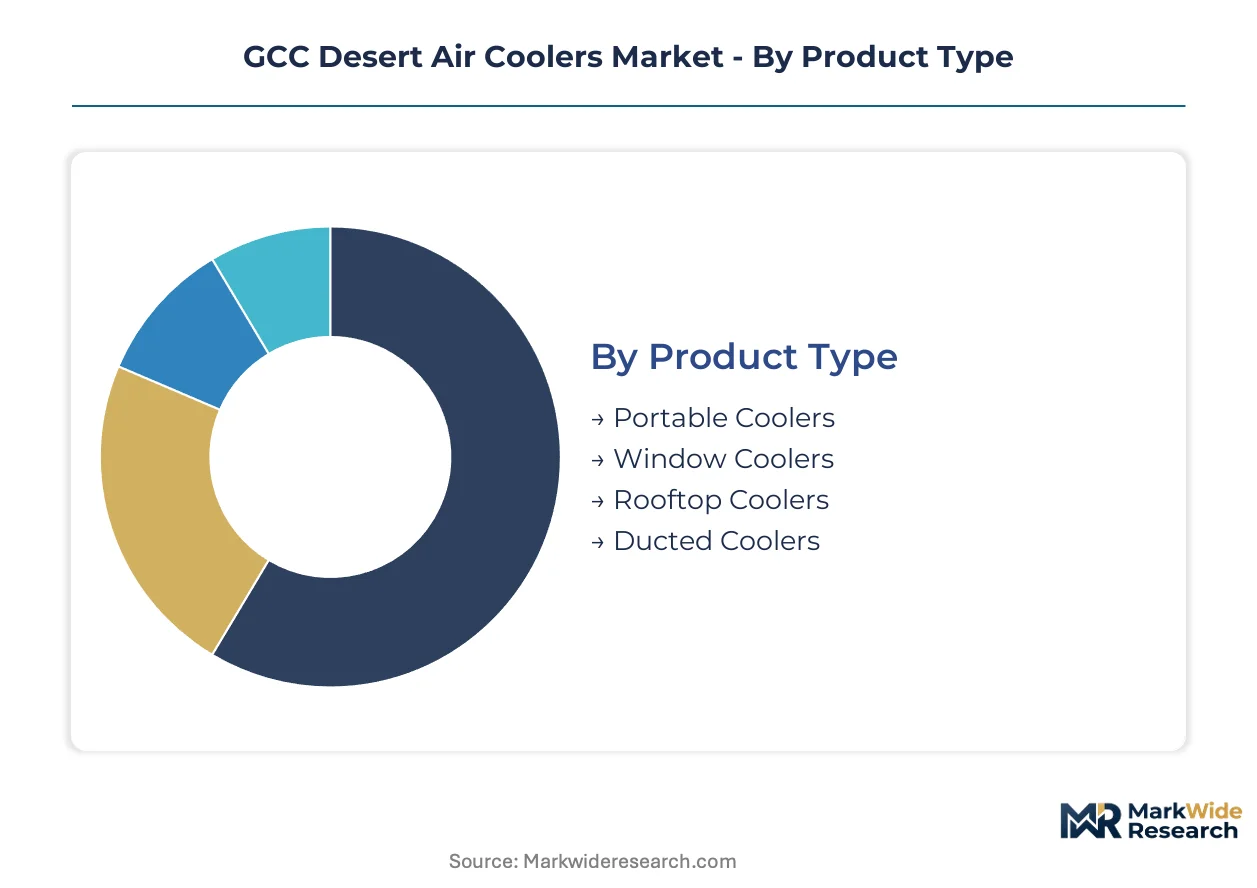
Product configuration in the GCC desert air cooler market directly determines service contract structures and replacement part revenue streams. Segmentation reveals how portable units generate minimal recurring service income while ducted installations anchor multi-year maintenance agreements.
Product Type:
After-sales-service intensity varies dramatically across product configurations, with ducted systems demanding dedicated technician networks and portable units requiring virtually no post-purchase support.
- Portable Coolers:Self-contained evaporative units with integrated water tanks and castor-mounted chassis designed for residential room-scale cooling. Demand concentrates in Saudi Arabia's hypermarket channels where Carrefour and Lulu retail networks serve price-sensitive buyers seeking immediate deployment without installation logistics.
- Ducted Coolers:Centralized evaporative air handling systems with plenum connections and multi-zone damper controls engineered for commercial building integration. Saudi Arabia's Riyadh-Dammam corridor anchors specification activity where five-year maintenance contracts accompany new construction projects and facility retrofits.
- Window Coolers:Through-wall evaporative units with fixed chassis dimensions for residential perimeter mounting.
- Rooftop Coolers:Weather-hardened evaporative systems with galvanized housings for industrial and agricultural centralized cooling.
By volume, Portable Coolers leads. By growth pace, Ducted Coolers is ahead.
End User:
Cost tier stratification separates premium-specified commercial installations from mass-market residential procurement, with industrial buyers occupying a mid-tier position on total cost of ownership metrics.
- Residential:Individual household and compound villa deployments where portable and window configurations dominate procurement patterns. Saudi Arabia's central region sustains replacement cycles as summer temperature extremes accelerate equipment degradation and drive upgrade demand.
- Commercial:Office complexes, retail facilities, and hospitality properties requiring ducted evaporative systems with building management system integration. UAE's Dubai and Abu Dhabi emirates tighten procurement specifications through ESMA seasonal efficiency mandates that redirect specification toward variable-speed pump configurations.
- Industrial:Manufacturing facilities and warehouse operations requiring high-capacity rooftop installations with corrosion-resistant housings.
- Agriculture:Greenhouse and livestock cooling applications where evaporative humidity control serves crop protection and animal welfare objectives.
Residential segment captures the largest unit volume. Commercial segment commands the highest average transaction value and service contract attachment rates.
Distribution Channel:
Volume concentration in wholesale and offline retail channels reflects the GCC's established HVAC contractor networks and the technical complexity of ducted system specification.
- Offline Retail:Brick-and-mortar electronics and home appliance stores serving immediate-need residential buyers with portable cooler inventory. Saudi Arabia's traditional souk-based electronics districts and UAE mall-based appliance retailers anchor this channel's regional presence.
- Wholesale:Bulk procurement pathways for construction contractors and facility management companies specifying ducted systems across multi-unit residential compounds and commercial developments. Dammam industrial zone distributors maintain regional warehousing for project-scale fulfillment.
- Online Retail:E-commerce platforms and direct-to-consumer digital channels with logistics-dependent fulfillment timelines.
- Direct Sales:Manufacturer-led specification engineering for large-scale commercial and industrial projects requiring custom system design.
Wholesale channel moves the highest absolute unit volume for ducted configurations. Online Retail is expanding most quickly as logistics infrastructure matures across Saudi Arabia and UAE.
Installation Type:
Application context dictates mobility requirements, with fixed outdoor installations dominating commercial and industrial specifications while mobile indoor units serve residential flexibility needs.
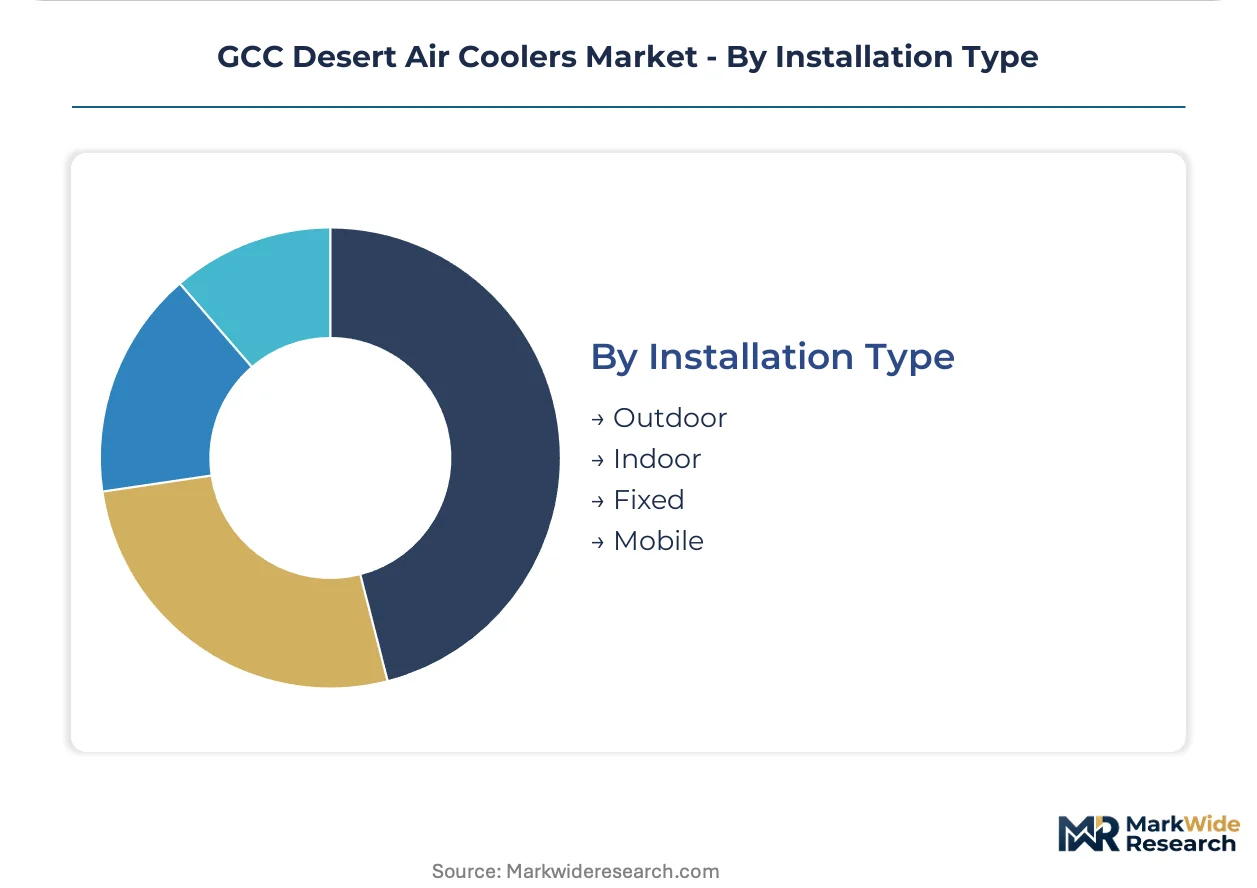
- Outdoor:Weather-exposed evaporative systems with IP-rated electrical enclosures and UV-stabilized housings for rooftop and perimeter mounting. Saudi Arabia's extreme solar load and sand exposure accelerate material specification toward corrosion-resistant coatings and sealed pump assemblies.
- Fixed:Permanently mounted installations with hard-plumbed water connections and dedicated electrical circuits. UAE commercial building codes increasingly mandate fixed evaporative infrastructure as primary or supplementary cooling in green building certification pathways.
- Indoor:Interior-space evaporative units with localized water reservoir systems and caster mobility.
- Mobile:Fully transportable configurations with no permanent installation requirements and plug-and-play electrical connections.
Outdoor installation type dominates commercial and industrial project specifications. Mobile configuration shows the steepest expansion trajectory in residential portable segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the GCC. Saudi Arabia deploys ducted systems for compound-scale cooling while UAE prioritizes portable units for apartment dwellers, and Qatar's coastal humidity constrains evaporative uptake to industrial zones.
Saudi Arabia
The Riyadh-Dammam corridor drives replacement cycles as summer temperatures breach 50°C. SASO mandatory efficiency ratings redirect procurement toward corrosion-resistant housings. Localized assembly investments near Jeddah and Dammam industrial zones reduce import dependence for residential compound deployments.
United Arab Emirates
Dubai and Abu Dhabi emirates anchor commercial specification activity for integrated building projects. ESMA seasonal energy efficiency ratio certification extends product launch timelines by 8–14 weeks. Abu Dhabi's Masdar City development cluster specifies ducted evaporative systems for green building compliance pathways.
Qatar
Coastal humidity above 40% relative humidity limits residential evaporative cooling viability. Industrial rooftop installations dominate procurement for manufacturing facilities in Ras Laffan Industrial City. Municipal green building codes are integrating evaporative cooling into renewable energy compliance frameworks for new construction.
Kuwait
Agricultural greenhouse cooling represents an underpenetrated segment versus Saudi industrial adoption curves. The country's national standards body is aligning with Gulf Standardization Organization energy labeling rules. Jahra and Al Ahmadi governorates concentrate industrial rooftop cooler installations for warehouse operations.
Oman
Interior desert regions sustain portable cooler demand through hypermarket retail channels. The sultanate's public authority for consumer protection enforces wet-bulb efficiency disclosure requirements. Sohar Port free zone distributors maintain regional warehousing for cross-border fulfillment into Yemen and East Africa.
GCC Desert Air Coolers Market Competitive Landscape
Capability concentration sits with premium-tier manufacturers of ducted systems; scale advantage sits with portable cooler specialists distributing through mass retail. The vendor base organizes around three strategic archetypes: integrated manufacturers with backward control over compressor and fan motor production, premium ducted system engineers targeting commercial installations, and price-aggressive portable specialists leveraging hypermarket wholesale channels. Dominant competitive moves include capacity expansion in Saudi assembly zones and five-year maintenance contract bundling for commercial projects.
Within the integrated manufacturing tier, Gree exemplifies backward integration strategies through captive production of core components. Daikin Industries Ltd. and Midea Group Co Ltd. occupy distinct positioning vectors—Daikin anchors premium commercial specification while Midea represents aggressive price competition in portable segments distributed through Carrefour and Lulu networks.
| Leading Market Players |
|---|
| Gree |
| Evvoli |
| SuperGeneral |
| AuX |
| Crownline |
| Toshiba Corporation |
| Daikin Industries Ltd. |
| Midea Group Co Ltd. |
| Carrier |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Saudi Arabia's Jeddah and Dammam assembly zones drives supplier prioritization toward five-year maintenance contract bundles and compresses spot-market availability for portable units. This utilization squeeze elevates pricing power for ducted system manufacturers while forcing hypermarket channels to absorb margin pressure on mass-market configurations.
Pricing Analysis
Project-based contracting dominates commercial ducted installations, with five-year maintenance agreements anchoring premium pricing tiers and portable units transacting through spot-market hypermarket channels. Price differentiation separates corrosion-resistant SASO-certified systems from economy-grade imports lacking variable-speed pump configurations. Cost compression in the portable tier intensifies as Midea and AuX compete through Carrefour and Lulu wholesale networks. Residential buyers in Saudi Arabia's central region exhibit highest price sensitivity, while UAE commercial developers prioritize efficiency certification over upfront cost.
Supply Chain Analysis
Export-control scrutiny on permanent-magnet motor technology from China constrains variable-speed pump sourcing for SASO-compliant assembly lines. Manufacturing concentration centers on China for cellulose cooling pads and copper coil windings, with South Korea supplying corrosion-resistant pump housings. Single-source vulnerability sits with East Asian copper supply chains subject to freight volatility. Distribution runs through Dammam industrial zone warehousing for project-scale fulfillment into Saudi Arabia's Riyadh-Dammam corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC desert air coolers market is entering a cyclical recovery phase as Saudi Arabia's localized assembly investments mature and replacement cycles accelerate from sustained heat extremes above 50°C.
For Market Incumbents: Harden service infrastructure around five-year maintenance contract fulfillment to lock out emerging distributors with weaker balance sheets. Deepen backward integration into fan motor production to offset copper coil import volatility and protect margin structures from hypermarket price erosion. For New Entrants and Emerging Players: Pursue Qatar's agricultural greenhouse segment where rooftop cooler penetration lags Saudi Arabia's industrial adoption curve. Target Kuwait's municipal green building code integration as specification entry point. Lead with direct sales engineering for integrated building projects rather than wholesale channel competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ducted system manufacturers with captive five-year maintenance contract portfolios. Long-term viability over a multi-year horizon favors acquisition targets with pre-certified ESMA product families for Dubai and Abu Dhabi deployment. Monitor SASO efficiency rating enforcement intensity as inflection signal for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Pump Localization | Captive production in Jeddah industrial zone insulates margins from East Asian supply volatility. |
| ESMA Pre-Certification Investment | Accelerated Dubai and Abu Dhabi product launches bypass 8-14 week approval delays. |
| Five-Year Maintenance Contract Bundling | Long-term service agreements lock commercial buyers into recurring revenue streams. |
| Hypermarket Channel Expansion | Carrefour and Lulu wholesale networks capture price-sensitive residential portable demand. |
| Corrosion-Resistant Housing R&D | SASO-mandated durability standards redirect procurement toward premium-tier specifications. |
Research Methodology
A spread of perspectives from HVAC contractor procurement managers, facility maintenance directors, hypermarket category buyers, and GSO regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with distributor inventory planners and aftermarket service technicians. Secondary validation drew from SASO efficiency rating disclosures, ESMA certification registries, Gulf Standardization Organization technical bulletins, and customs import data for copper coil and cellulose pad shipments. Bottom-up unit shipment tallies triangulated against top-down construction permit analysis for commercial and residential cooling installations.
Demand-supply balance modeling anchored the projection framework across the analysis window. Segmentation dimensions included product configuration, end-use sector, distribution channel, and installation type, with regulatory compliance tier as an industry-specific overlay. CAGRs derived from replacement cycle velocity in Saudi Arabia's heat-extreme zones and efficiency mandate adoption curves in UAE emirates. Forecast inputs incorporated wet-bulb depression performance standards and variable-speed pump penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese portable specialists or sudden copper tariff impositions would shift outcomes. Material shifts in GSO energy labeling enforcement or humidity-driven coastal market abandonment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Airflow Management Market
Energy Management Systems
Global Digital Thermostats Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
Global Thermal Management Technologies Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Grid Operations Management Software Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
AI Water Heater Market