
 Global Bluetooth Beacon and Ibeacon Market | 2026-2036
Global Bluetooth Beacon and Ibeacon Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bluetooth Beacon and Ibeacon Market Analysis
Embedded systems engineering talent is rotating toward low-power wireless firmware development, unlocking faster beacon iteration cycles. Apple Inc. leverages its proprietary iBeacon protocol and tight iOS integration to dominate consumer-facing proximity deployments. Estimote, Inc. competes through modular hardware architectures that extend deployment flexibility across industrial environments. Kontakt.io, Inc. specializes in cloud-managed beacon fleets, sustaining recurring revenue streams from enterprise clients.
Bluetooth beacons and iBeacons are compact radio transmitters operating on the 2.4 GHz ISM band using Bluetooth Low Energy protocols, broadcasting unique identifiers to nearby receiving devices for location-aware services and contextual engagement. The hardware transmits at configurable intervals between 100 ms and 1280 ms while drawing sub-100 microampere currents, enabling multi-year battery life from coin cells. Bluetooth Low Energy beacons anchor the installed base due to universal smartphone compatibility and minimal power draw, while location services technology is capturing expanding share as indoor positioning accuracy demands tighten. Retail marketing applications occupy the largest revenue pool today, though asset tracking is registering the fastest trajectory as warehouse and logistics operators digitize inventory visibility.
The FCC in the United States governs unlicensed 2.4 GHz emissions, while the EU AI Act and GDPR constrain how beacon-captured location data is processed and stored across European deployments. Japan's METI promotes IoT interoperability standards that facilitate cross-manufacturer beacon compatibility in smart city projects. Stakeholders must monitor evolving data localization mandates and spectrum allocation rulings that could alter hardware certification pathways and cloud data routing requirements.
Market Dynamics
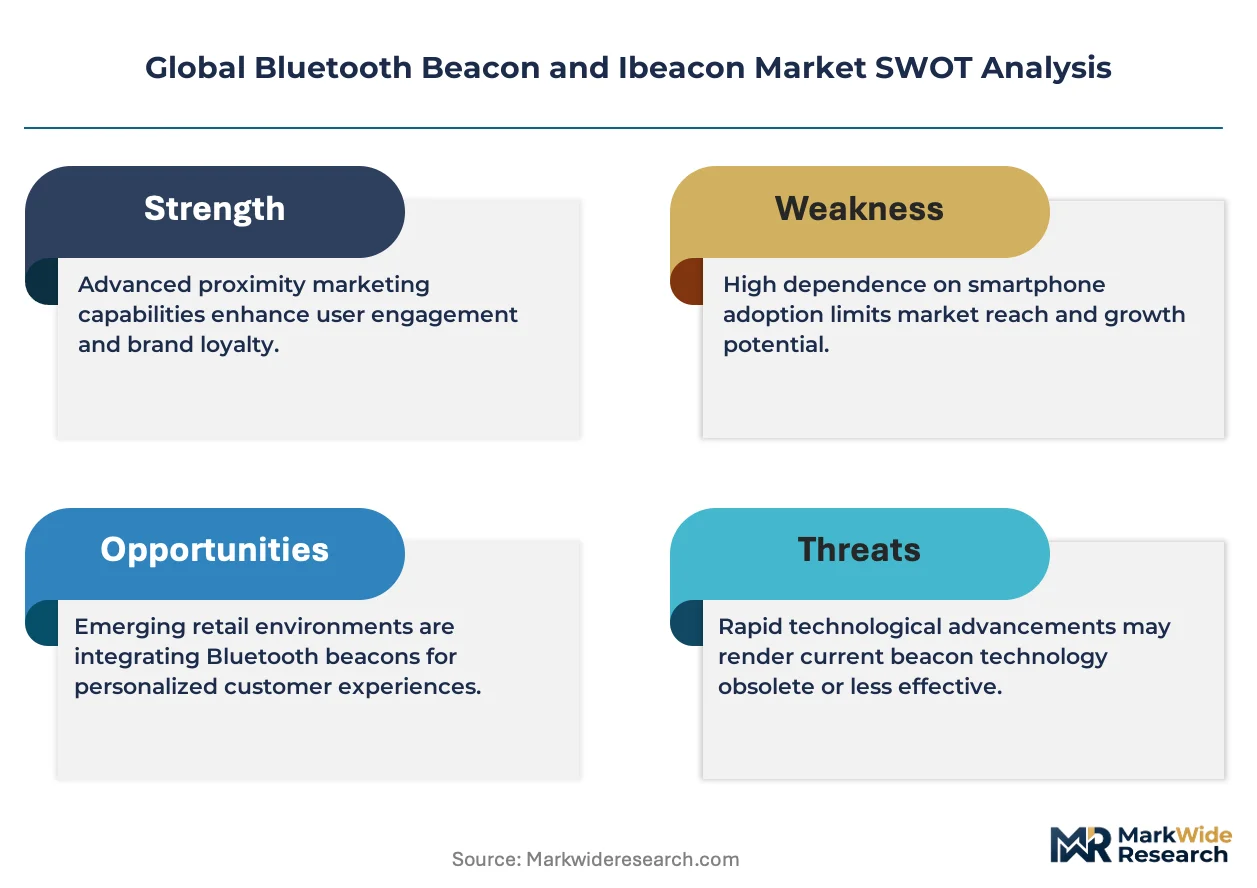
Proximity marketing infrastructure investments are compressing deployment timelines as BLE hardware costs fall below mass-adoption thresholds, forcing beacon vendors to pivot from hardware sales toward recurring software revenue models.
Growth Catalysts
- GDPR-Compliant Data Frameworks:European retailers are expanding beacon deployments under privacy-by-design architectures that anonymize location signals, unlocking consumer trust in proximity engagement.
- Warehouse Digitization:Logistics operators in Germany and Japan are deploying dense beacon mesh networks to achieve sub-meter inventory positioning, displacing legacy RFID systems.
- FCC Spectrum Stability:Unlicensed 2.4 GHz continuity in the United States removes hardware recertification risks, accelerating retailer capex commitments.
Market Restraints
- Coin Cell Supply Concentration:CR2032 battery sourcing depends on East Asian chemical processors, exposing beacon manufacturers to lithium carbonate price volatility.
- EU AI Act Friction:Automated location profiling triggers algorithmic risk classification, extending compliance timelines for European smart retail deployments.
- UWB Substitution Threat:Ultra-wideband chips from Apple and Samsung are displacing BLE beacons in high-accuracy indoor positioning applications.
Strategic Opportunities
- India Smart City Mandates:Municipal IoT interoperability requirements under the PLI scheme create openings for cloud-managed beacon fleets in urban transit hubs.
- Healthcare Asset Tracking:Hospital systems in the United States are piloting BLE-enabled patient flow optimization, expanding beyond retail-centric demand.
- Ambient IoT Convergence:Integration with energy-harvesting sensors and LPWAN backhaul is enabling battery-free beacon deployments in industrial environments.
Industry Challenges
- Firmware Engineering Scarcity:Low-power wireless stack development expertise concentrates in Nordic semiconductor clusters, inflating talent acquisition costs.
- Multi-Protocol Certification Burden:Simultaneous Bluetooth SIG qualification, FCC Part 15 testing, and CE marking extends product launch timelines.
- Legacy POS Integration Complexity:Retail IT departments face middleware development costs to bridge beacon-triggered promotions with existing transaction systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bluetooth Beacon and Ibeacon Market |
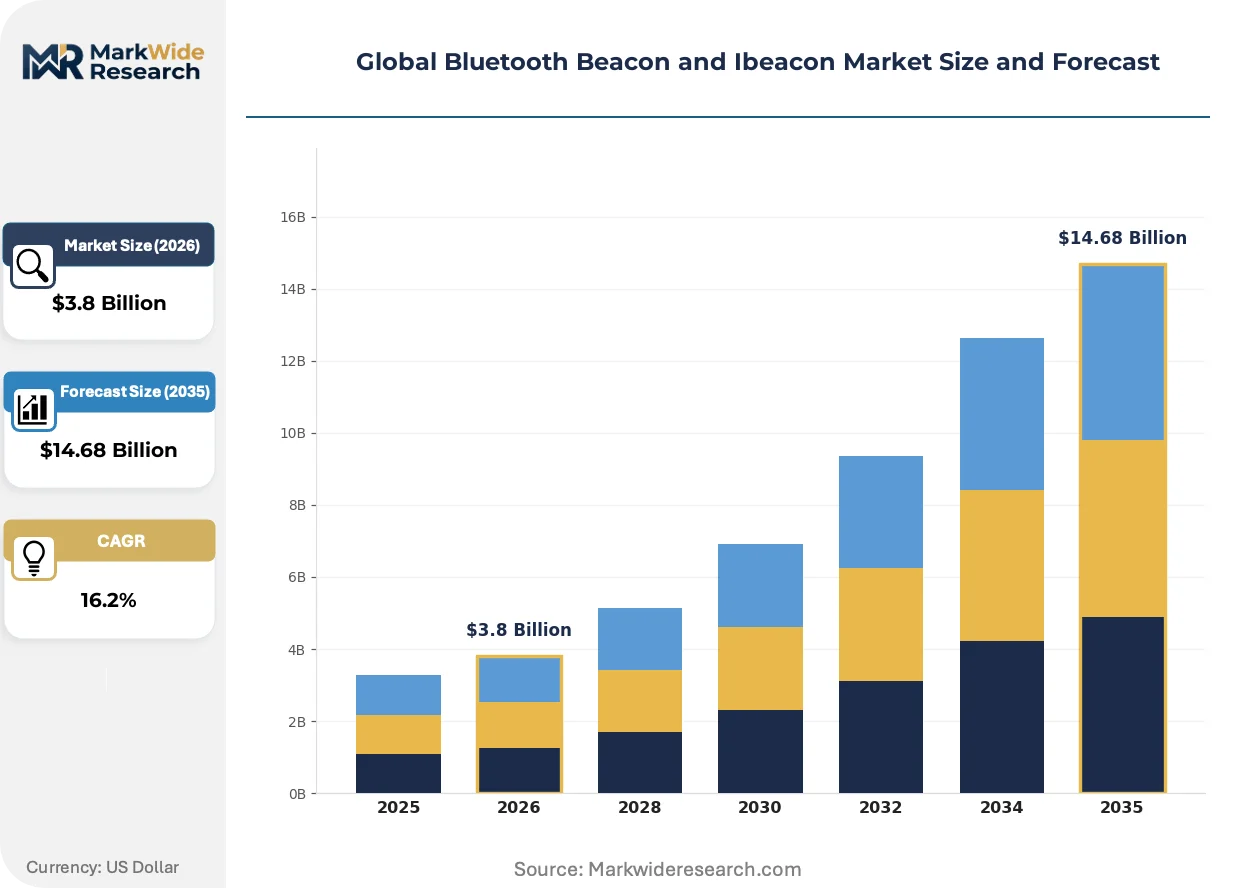
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.68 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Beacons, iBeacons, Sensors, Wearables Technology: Bluetooth Low Energy, Near Field Communication, RFID, Location Services Application: Retail Marketing, Proximity Marketing, Navigation, Asset Tracking End User: Retailers, Event Organizers, Transportation, Hospitality |
| Companies Covered | Apple Inc., Estimote, Inc., Kontakt.io, Inc., Gimbal, Inc., Radius Networks, Inc., BlueCats Australia Pty Ltd, Beaconinside GmbH, Sensoro Co., Ltd., Aruba Networks, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bluetooth Beacon and Ibeacon Market Emerging Trajectories
Beacon hardware is undergoing functional compression as silicon integration advances, while regulatory data governance and procurement model evolution reshape how proximity infrastructure is financed and deployed.
System-in-package BLE modules is miniaturizing beacon form factors below one cubic centimeter, enabling integration into product packaging and wearable accessories. Cosmetics brands in France and luxury retailers in Japan are embedding disposable beacons directly into limited-edition packaging. This compression is collapsing the distinction between dedicated beacon hardware and ambient product intelligence.
GDPR Article 25 mandates are forcing beacon operators to implement data minimization by default, requiring on-device signal processing rather than raw location transmission to cloud servers. European retail chains are adopting edge-computing beacon gateways that filter identifiers locally. This regulatory architecture is advantaging vendors with pre-certified privacy architectures over hardware-only suppliers.
Retailers are unbundling beacon hardware procurement from software licensing, demanding month-to-month SaaS contracts with zero upfront capex. This shift is visible most acutely among mid-market United States apparel chains and German grocery cooperatives. Vendors responding with hardware-as-a-service models are capturing multi-year recurring revenue streams while absorbing device refresh cycles.
Global Bluetooth Beacon and Ibeacon Market Segmentation
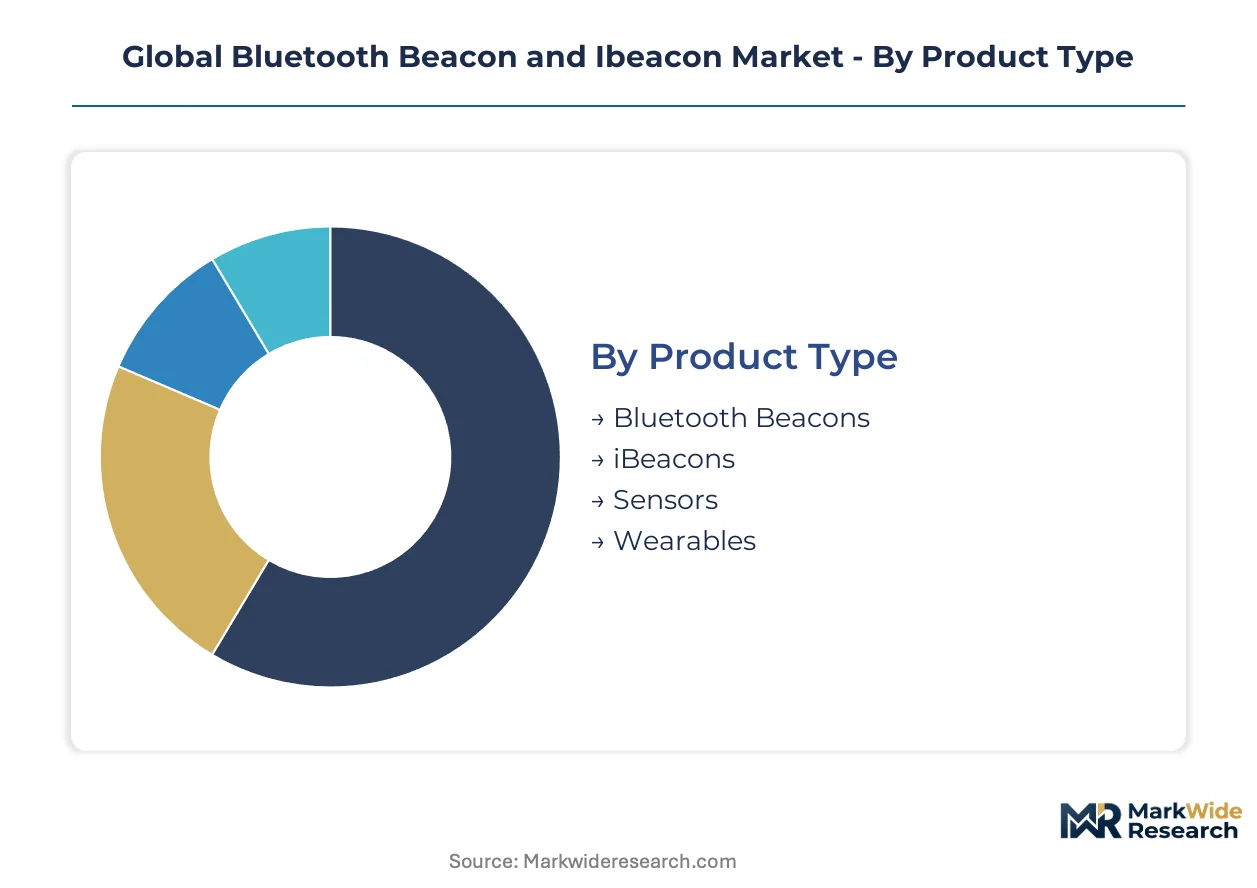
Bluetooth beacon deployments fragment across hardware configurations, wireless protocols, and vertical use cases. Each segmentation axis carries distinct procurement patterns, margin profiles, and geographic concentration that shape vendor strategy.
Product Type:
Bluetooth Beacons and iBeacons dominate domestic consumption in the United States and Germany, while sensor-integrated variants flow disproportionately to export-led industrial deployments in Japan.
- Bluetooth Beacons:Compact radio transmitters operating on the 2.4 GHz ISM band with configurable broadcast intervals between 100 ms and 1280 ms. United States retailers deploy these for aisle-level proximity engagement as BLE hardware costs fall below mass-adoption thresholds.
- iBeacons:Apple Inc.'s proprietary protocol variant with tight iOS integration and standardized UUID transmission formats. Consumer-facing deployments concentrate in North American shopping malls where iPhone penetration exceeds sixty percent.
- Sensors:Multi-modal units combining BLE transmission with temperature, humidity, or motion detection capabilities. German logistics operators embed these in pharmaceutical cold chains.
- Wearables:Beacon-integrated wristbands and badges for personnel tracking and access control. Japanese hospital systems pilot these for patient flow optimization.
Bluetooth Beacons command the established base. The steepest expansion runs through Sensors.
Technology:
Cost tier separation distinguishes universal smartphone-compatible protocols from specialized high-accuracy alternatives requiring dedicated infrastructure investment.
- Bluetooth Low Energy:Dominant protocol drawing sub-100 microampere currents for multi-year coin cell operation. Universal smartphone compatibility anchors retail and logistics demand across all major economies.
- Near Field Communication:Ultra-short-range contactless technology operating below 10 cm. Payment-integrated deployments concentrate in Japanese transit hubs and European point-of-sale retrofits.
- RFID:Legacy inventory tracking technology facing displacement by BLE mesh networks in German and Japanese warehouse digitization projects.
- Location Services:Enhanced positioning accuracy through trilateration and fingerprinting algorithms. United States and German industrial facilities adopt these for sub-meter asset positioning.
Bluetooth Low Energy holds the volume base. Location Services climbs the fastest as accuracy requirements tighten.
Application:
Customer type bifurcation separates consumer-engagement deployments from operational-efficiency implementations with distinct procurement cycles and stakeholder decision structures.
- Retail Marketing:Proximity-triggered promotions and loyalty integration at United States apparel chains and German grocery cooperatives. Month-to-month SaaS contracting is displacing upfront hardware purchases.
- Proximity Marketing:Contextual engagement extending beyond retail into museums, stadiums, and urban districts. French cosmetics brands embed disposable beacons in limited-edition packaging.
- Navigation:Indoor wayfinding for complex environments including airports and hospitals. Japanese smart city projects under METI interoperability standards drive standardization.
- Asset Tracking:Real-time inventory visibility in warehouses and manufacturing facilities. German logistics operators deploy dense beacon meshes to displace legacy systems.
Retail Marketing captures the revenue base. Asset Tracking gains share fastest as warehouse digitization accelerates.
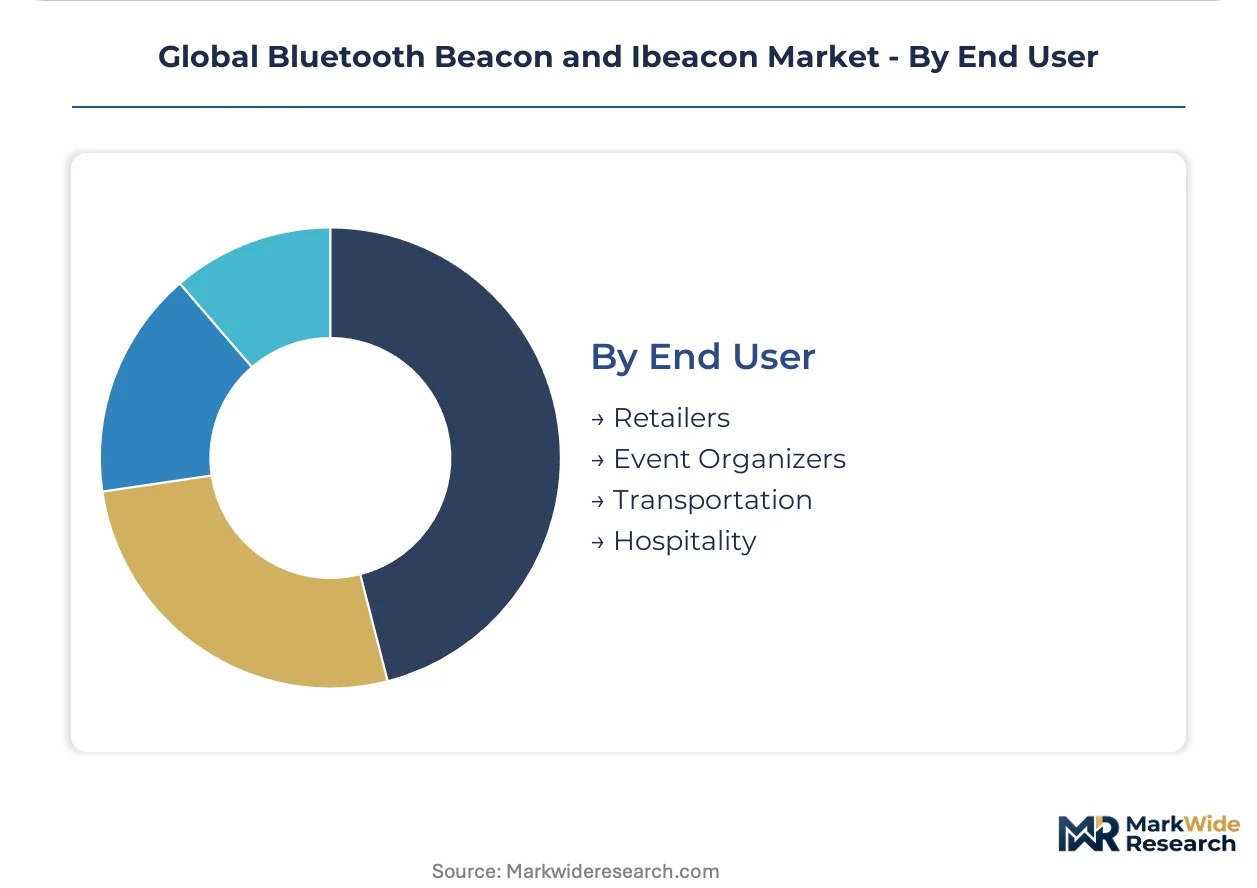
End User:
Maturity stage varies sharply across verticals, with retail and transportation operating decade-old beacon programs while hospitality pilots remain exploratory.
- Retailers:Primary demand source spanning proximity marketing, inventory management, and customer analytics. GDPR Article 25 compliance requirements reshape European deployment architectures.
- Event Organizers:Temporary deployments for crowd flow management and sponsor activation. United States sports venues lead adoption.
- Transportation:Transit hubs and airports deploying navigation and passenger tracking. India's urban transit projects under PLI scheme interoperability mandates create procurement openings.
- Hospitality:Hotels and resorts piloting guest experience personalization and staff coordination. Deployment remains concentrated in luxury properties in Japan and France.
Retailers anchor the installed base. Transportation shows the steepest expansion trajectory through municipal infrastructure programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum stability in the United States anchors near-term deployment confidence, while GDPR Article 25 mandates and Japan's METI interoperability standards reshape procurement architectures across their respective markets.
United States
Proximity marketing infrastructure investments at apparel chains and sports venues drive hardware demand. FCC Part 15 continuity for unlicensed 2.4 GHz emissions removes recertification risks. Dallas-Fort Worth logistics hubs deploy dense beacon meshes for warehouse digitization.
Germany
Pharmaceutical cold chain operators and grocery cooperatives expand sensor-integrated beacon fleets. EU AI Act algorithmic risk classification extends compliance timelines for automated location profiling. Rhine-Ruhr logistics corridors displace legacy RFID with BLE mesh networks.
Japan
Smart city transit projects and hospital patient flow pilots concentrate demand for wearable beacon form factors. METI IoT interoperability standards facilitate cross-manufacturer compatibility. Osaka-Kobe manufacturing clusters adopt sub-meter asset positioning systems.
India
Urban transit hubs under PLI scheme mandates create procurement openings for cloud-managed beacon fleets. BIS certification requirements shape hardware import pathways. Maharashtra municipal corporations pilot navigation systems in dense commercial districts.
France
Cosmetics brands embed disposable beacons in limited-edition packaging for proximity engagement. CNIL oversight of location data processing enforces GDPR data minimization by default. Paris retail corridors adopt edge-computing beacon gateways with local signal filtering.
Global Bluetooth Beacon and Ibeacon Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with protocol control and cloud management capabilities separating the tiers. Apple Inc. leverages proprietary iBeacon protocol integration to dominate consumer-facing proximity deployments. Estimote, Inc. and Kontakt.io, Inc. compete through modular hardware architectures and cloud-managed beacon fleets respectively. Strategic moves concentrate on pivoting from hardware sales toward recurring software revenue models and absorbing device refresh cycles through hardware-as-a-service offerings.
Within the integrated platform tier, Apple Inc. exemplifies protocol-level control through tight mobile operating system integration. Estimote, Inc. and Kontakt.io, Inc. occupy positions spanning modular hardware specialization and enterprise cloud management archetypes. These three entities represent the dominant competitive anchors against which mid-market specialists and regional fabricators position alternative pricing and deployment flexibility.
| Leading Market Players |
|---|
| Apple Inc. |
| Estimote, Inc. |
| Kontakt.io, Inc. |
| Gimbal, Inc. |
| Radius Networks, Inc. |
| BlueCats Australia Pty Ltd |
| Beaconinside GmbH |
| Sensoro Co., Ltd. |
| Aruba Networks, Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day component lead times for Nordic Semiconductor BLE modules concentrate pricing power among integrated firmware vendors while squeezing hardware-only suppliers into commodity margins. This inventory compression cascades through contract manufacturers in Taiwan and Malaysia, amplifying cost differentials between cloud-managed beacon fleets and disposable packaging-embedded units.
Pricing Analysis
United States-Germany unit price spreads of 15-20 percent reflect divergent after-sales service bundling rather than hardware cost differentials. The dominant pricing structure is month-to-month SaaS licensing with zero upfront capex, though German grocery cooperatives retain preference for three-year hardware-as-a-service contracts. Price differentiation rests on GDPR pre-certification tier and cloud analytics depth, with mid-market United States apparel chains exhibiting highest price sensitivity while Japanese smart city integrators prioritize interoperability over unit cost. Pricing pressure stems from UWB substitution in high-accuracy positioning applications, compressing BLE beacon margins in warehouse digitization segments.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose beacon manufacturers to lithium carbonate supply disruptions from East Asian chemical processors. Component sourcing concentrates in Taiwan for BLE system-in-package modules, China for CR2032 battery assembly, and Germany for precision sensor calibration. Raw material dependencies span lithium manganese dioxide chemistry, FR4 substrate laminates, and Nordic Semiconductor nRF52 series chipsets. Single-source vulnerability runs through Nordic's firmware stack dominance, while distribution feeds through electronics distributors Arrow and Avnet into regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Bluetooth Beacon and Ibeacon Market represents a high-growth disruption as warehouse digitization and GDPR-compliant edge architectures displace legacy RFID and centralized cloud processing. Regulatory inflection at the EU AI Act's algorithmic risk classification threshold is compressing deployment timelines for non-compliant vendors.
For Market Incumbents: Compound cloud management capabilities through acquisition of edge-computing gateway specialists to defend against UWB displacement in sub-meter positioning. Absorb device refresh cycles via hardware-as-a-service contracts that lock in multi-year recurring revenue. Prioritize backward integration into Nordic Semiconductor firmware customization to reduce talent acquisition costs in low-power wireless engineering.
For New Entrants and Emerging Players: CE marking fast-track through pre-certified privacy-by-design architectures unlocks European retail procurement blocked to hardware-only competitors. Target India's PLI scheme municipal transit projects where interoperability mandates favor cloud-native entrants over legacy RFID incumbents. Deploy disposable beacon-in-packaging solutions for French cosmetics and Japanese luxury retail segments underserved by durable hardware vendors.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial automation conglomerates divesting non-core proximity marketing divisions as they pivot toward UWB and 5G positioning. Five-to-ten year viability favors vendors with recurring software revenue exceeding sixty percent of total mix. Monitor FCC spectrum allocation proceedings as signal for hardware recertification risk exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Tight iOS and Android SDK bundling captures consumer-facing proximity deployments at North American shopping malls. |
| Acquisition of Specialist Firm | Edge-computing gateway vendors with GDPR Article 25 pre-certification command premium valuations from cloud-managed beacon incumbents. |
| Geographic Expansion | Maharashtra municipal pilot programs under India's PLI scheme create first-mover advantage for interoperability-compliant entrants. |
| Strategic Partnership | Hospital system partnerships in the United States extend beacon demand beyond retail into patient flow optimization. |
| Product Launch | Battery-free energy-harvesting beacon releases target industrial environments where coin cell supply volatility disrupts maintenance schedules. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. The research team conducted structured conversations with BLE firmware engineers, retail IT procurement directors, logistics warehouse automation leads, and hospital biomedical systems managers. Secondary sources encompassed FCC Part 15 equipment authorization databases, EU AI Act implementation guidance, METI IoT interoperability standards documentation, and BIS certification registries. Bottom-up unit economics modeling triangulated against top-down market sizing from customs trade flows and semiconductor shipment data.
Sensitivity analysis across hardware cost decline trajectories and SaaS pricing elasticity shaped the analytical framework. Segmentation dimensions modeled include product type, wireless protocol, application vertical, end-user industry, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and net new deployment velocity across warehouse digitization and smart city infrastructure programs. Industry-specific forecast inputs incorporated lithium carbonate price volatility bands and Nordic Semiconductor capacity expansion announcements.
Decision-makers should treat outputs as directional under assumptions of continued FCC 2.4 GHz spectrum stability and EU AI Act enforcement consistency; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as UWB chip cost curves and energy-harvesting component maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Femtocell Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
Global Wireless Health Market
Wireless Technologies
Wigig Market
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Mesh Wifi System Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Latin America Wireless Mesh Networking Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Prepaid Wireless Service Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market