
 Wireless Paging Systems Market | 2026-2036
Wireless Paging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Paging Systems Market Analytics
Premium encrypted paging tiers is decoupling from basic numeric alerting on reliability metrics and spectrum resilience. LONG RANGE SYSTEMS, LLC. leverages proprietary RF protocols to dominate long-range campus deployments. Telcom & Data Inc. anchors its position through specialized healthcare integration services. Visiplex, Inc. differentiates by sustaining manufacturing scale across voice-capable pager lines.
Wireless paging systems are dedicated one-way or two-way communication devices operating on licensed VHF/UHF spectrum bands, typically 152-158 MHz or 454-460 MHz, designed to deliver short message alerts to portable receivers across wide geographic footprints. These systems serve critical notification functions where cellular network congestion or failure risks operational continuity. Alphanumeric and digital product types capture the strongest margin pools as hospitals demand message-rich displays for patient telemetry integration. BLE-enabled technology segments are expanding fastest in retail and hospitality end-user applications where proximity-triggered guest paging replaces traditional coaster systems.
FCC Part 22 and Part 90 rules govern paging spectrum allocation and device certification in the United States, while the EU Radio Equipment Directive and ETSI standards shape market access across European member states. FDA oversight of healthcare communication infrastructure indirectly elevates pager reliability requirements above consumer-grade alternatives. Stakeholders must monitor spectrum reallocation proceedings and hospital digitization budgets to calibrate hardware refresh timing against replacement cycle windows.
Market Dynamics
Spectrum scarcity and hospital digitization timelines are colliding to compress replacement cycles for legacy paging hardware while elevating encrypted messaging tiers above basic alerting functionality.
Growth Catalysts
- FCC Part 90 paging allocations:Sustained licensed spectrum access in the 454-460 MHz band preserves dedicated channel reliability for critical healthcare alerts where cellular failover remains unacceptable.
- German hospital infrastructure programs:Federal modernization budgets sustain multi-year replacement cycles for aging VHF paging systems across acute care networks.
- BLE-enabled proximity paging:Bluetooth Low Energy integration into retail and hospitality coaster replacements is opening volume segments beyond traditional healthcare verticals.
Market Restraints
- RF component supply concentration:Specialized VHF/UHF transceiver fabrication concentrates among a limited supplier base in East Asian semiconductor foundries.
- Cellular network substitution:5G mission-critical service tier marketing by mobile operators threatens paging's reliability positioning in non-healthcare segments.
- ETSI EN 301 489 certification friction:European electromagnetic compatibility testing timelines extend device approval cycles by six to nine months versus FCC Part 15 equivalents.
Strategic Opportunities
- Underpenetrated Indian healthcare infrastructure:District hospital networks lack redundant communication layers for emergency coordination, creating greenfield paging demand.
- Voice-capable pager convergence:Two-way audio integration with existing nurse call systems enables premium tier pricing in US acute care procurement.
- EU Medical Device Regulation (MDR) Article 10:New clinical evaluation requirements for patient-connected devices indirectly elevate pager reliability standards above consumer alternatives.
Industry Challenges
- RF engineering talent scarcity:Specialized VHF propagation and antenna design expertise concentrates among aging practitioner cohorts with limited pipeline replacement.
- Legacy system integration complexity:Hospital IT departments face middleware development burdens when bridging 1980s-era paging protocols with modern electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Paging Systems Market |
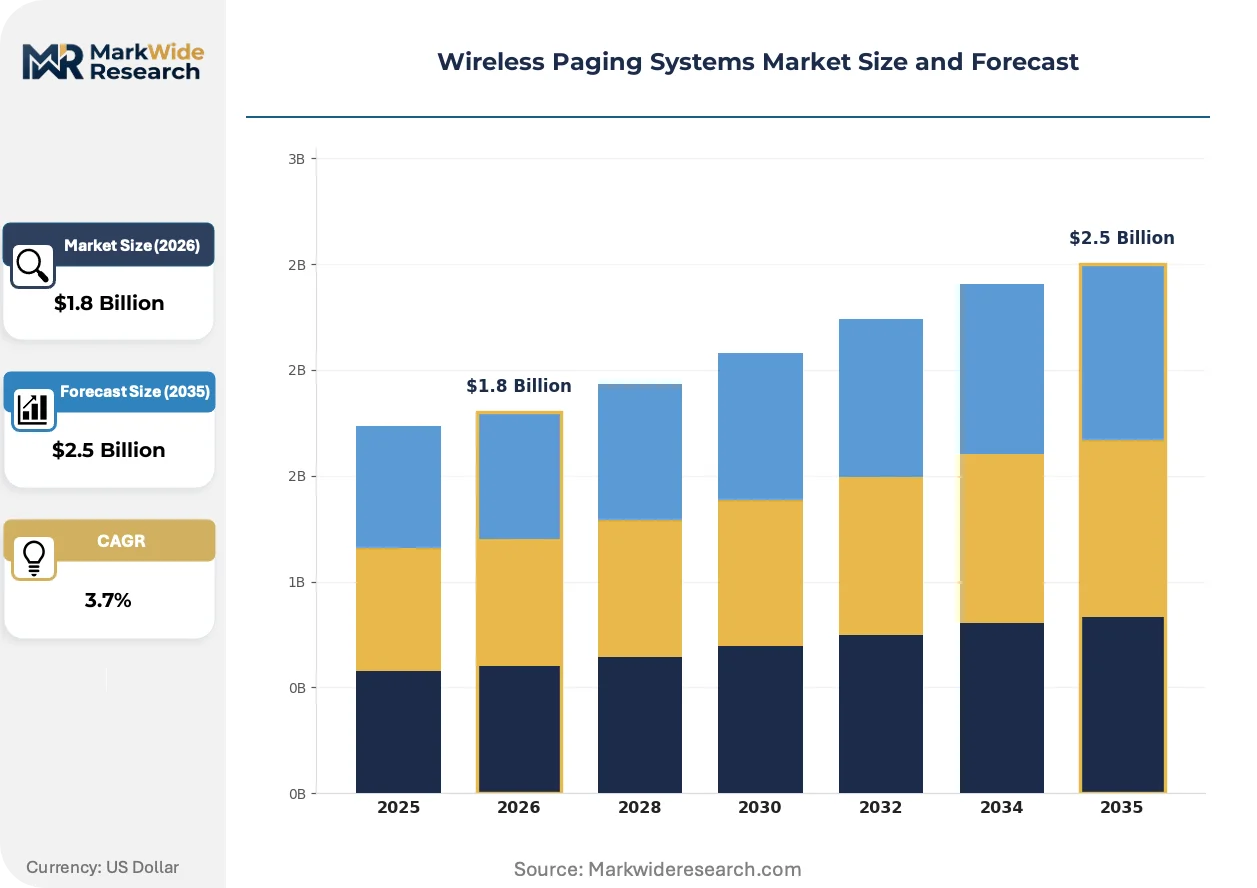
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Alphanumeric, Numeric, Voice End User: Healthcare, Retail, Hospitality, Industrial Technology: Radio Frequency, Infrared, Wireless LAN, BLE Application: Emergency Services, Customer Notification, Staff Communication, Alert Systems |
| Companies Covered | LONG RANGE SYSTEMS, LLC., Telcom & Data Inc., Visiplex, Inc., Quest Retail Systems Inc., Pager Genius, JTECH, CORNELL, MMCall, INTERPAGE, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Paging Systems Market Evolving Landscape
BLE proximity technology and encrypted messaging protocols are bifurcating the market into premium healthcare tiers and commoditized hospitality applications.
Bluetooth Low Energy paging modules are converging with traditional RF alerting infrastructure to enable location-aware message routing in large campus deployments. Hospital facilities in Texas and California are piloting hybrid systems that switch between licensed VHF for emergency codes and BLE for departmental coordination. This dual-protocol architecture is compressing hardware refresh timelines as procurement committees demand future-proofed platforms.
EU Radio Equipment Directive (RED) 2014/53/EU enforcement is tightening electromagnetic exposure documentation for body-worn paging devices. Manufacturers must now submit specific absorption rate testing for pager clips and holsters previously exempt under legacy telecom terminal rules. German notified bodies are processing these submissions with twelve-week backlogs, delaying product launches for voice-capable alphanumeric units.
Acute care procurement committees are unbundling pager service contracts from hardware purchases, forcing vendors to compete on recurring platform fees rather than bundled device subsidies. This shift is compressing margins for traditional full-service paging operators while creating openings for specialized healthcare integrators. The pattern is most visible in US health system consolidation, where centralized IT governance favors multi-hospital platform standardization over site-specific vendor relationships.
Wireless Paging Systems Market Segmentation
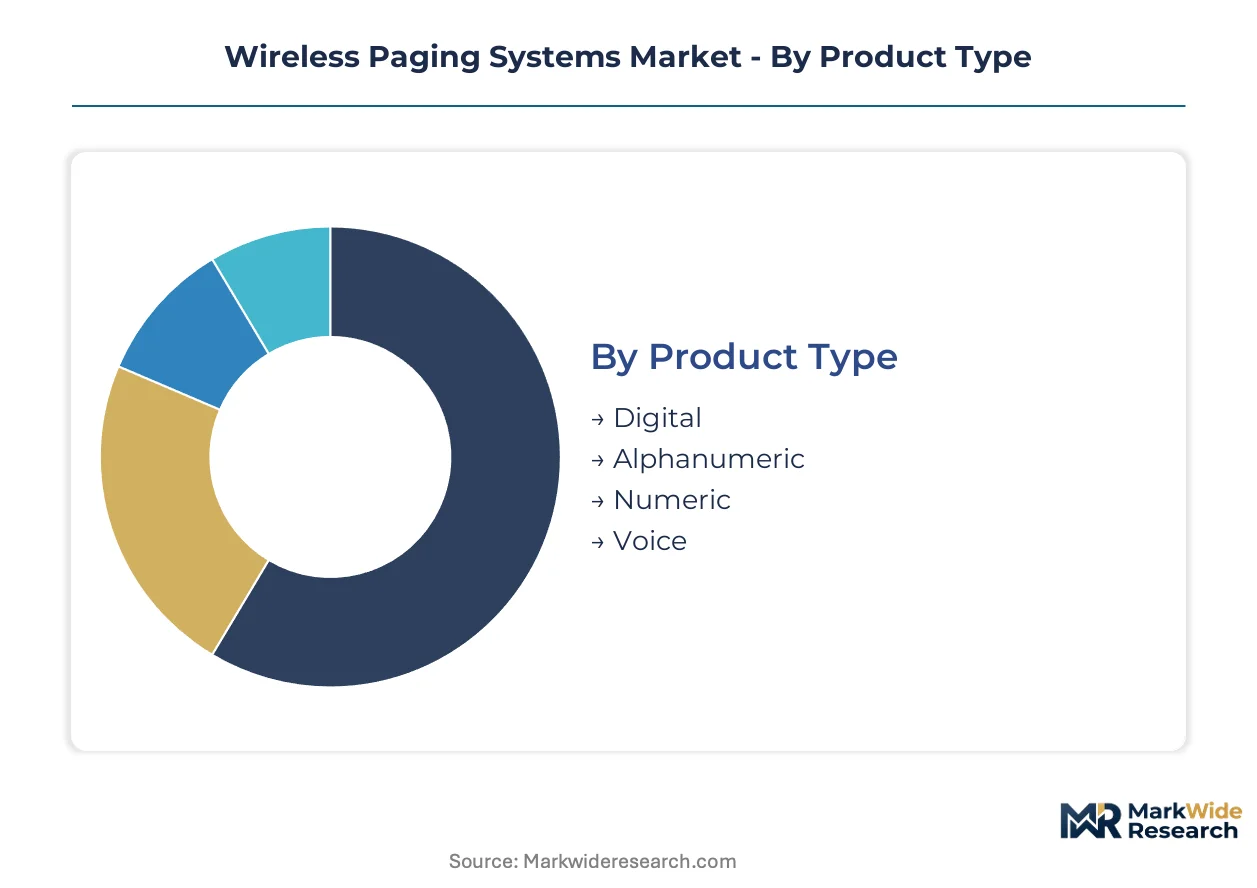
Wireless paging systems fragment across four critical dimensions where supply concentration, end-use reliability requirements, and protocol standardization create divergent margin structures. Procurement committees in acute care networks and hospitality chains demand fundamentally different performance specifications from shared hardware platforms.
Product Type:
Component sourcing for display modules and voice codecs concentrates among East Asian semiconductor foundries, compressing margins for basic units while encrypted tiers sustain premium positioning.
- Alphanumeric:Full-text message displays integrate with patient telemetry systems for rich clinical data delivery. US hospital networks in Texas and California prioritize these units for code blue response coordination where message clarity reduces escalation errors.
- Voice:Two-way audio capability enables direct verbal confirmation between nursing stations and mobile staff. German acute care procurement committees specify voice integration with existing nurse call infrastructure, commanding premium tier pricing.
- Digital:Compact receivers with basic icon-based alerting serve cost-sensitive departmental deployments.
- Numeric:Legacy seven-segment displays persist in budget-constrained facilities requiring simple callback coordination.
Alphanumeric units absorb the bulk of installed capacity in acute care; voice-capable pagers are expanding most quickly through integration mandates.
End User:
Customer procurement sophistication varies sharply across verticals, with healthcare compliance requirements creating structural pricing power unavailable in retail or hospitality segments.
- Healthcare:FDA-oversight of patient-connected communication infrastructure elevates reliability standards above consumer-grade alternatives. German federal modernization budgets sustain multi-year replacement cycles for aging VHF systems across district hospital networks.
- Hospitality:BLE-enabled coaster replacements dominate guest notification systems where proximity-triggered alerting replaces traditional RF pagers. Texas resort chains pilot hybrid protocols combining licensed spectrum for emergencies with Bluetooth for spa and dining coordination.
- Retail:Queue management applications favor low-cost numeric pagers for customer recall in pharmacy and service counter environments.
- Industrial:Heavy-duty voice pagers serve manufacturing floors where ambient noise excludes visual-only alerting.
Healthcare commands the dominant share of hardware value; hospitality BLE adoption is climbing the fastest as coaster system replacements accelerate.
Technology:
Protocol licensing costs and spectrum access fees create tiered margin structures that favor integrated vendors with captive RF engineering capabilities.
- Radio Frequency:Licensed VHF/UHF spectrum in 152-158 MHz and 454-460 MHz bands delivers dedicated channel reliability where cellular congestion risks operational continuity. FCC Part 90 allocations in the United States preserve this architecture for critical healthcare alerts.
- BLE:Bluetooth Low Energy modules enable location-aware message routing without spectrum licensing burdens. California hospital campuses deploy hybrid architectures switching between licensed RF for emergencies and BLE for departmental coordination.
- Infrared:Line-of-sight protocols persist in controlled environments like operating theaters where RF interference must be eliminated.
- Wireless LAN:Wi-Fi-based paging integrates with existing hospital network infrastructure but remains vulnerable to IT department change control windows.
Radio Frequency retains the largest installed base; BLE is gaining share fastest through retail and hospitality proximity applications.
Application:
Use-case criticality determines procurement committee composition and contract structure, with emergency applications commanding multi-year service agreements.
- Emergency Services:Code blue and rapid response team coordination requires guaranteed message delivery with sub-second latency. US health system consolidation drives centralized platform standardization across multi-hospital networks.
- Staff Communication:Routine paging for physician and nursing coordination integrates with electronic health record workflow engines. German hospital IT departments face middleware development burdens bridging 1980s-era protocols with modern architectures.
- Customer Notification:Retail queue management and hospitality guest recall prioritize cost minimization over message encryption.
- Alert Systems:Facility-wide emergency broadcast functions overlap with fire and security infrastructure, creating procurement bundling opportunities.
Emergency Services accounts for the greatest share of premium-tier revenue; Staff Communication is expanding fastest through EHR integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas hospital campuses anchor wireless paging deployment intensity, where hybrid VHF-BLE architectures pilot emergency-staff coordination systems. German federal budgets sustain replacement cycles for aging infrastructure. Indian district hospitals present greenfield demand for redundant communication layers.
United States
Acute care networks in Texas and California drive hybrid protocol adoption, switching licensed VHF for code blue alerts and BLE for departmental coordination. FCC Part 90 rules govern 454-460 MHz spectrum access, preserving dedicated channel reliability where cellular failover remains unacceptable. Hospital consolidation in the Southeast favors multi-hospital platform standardization over site-specific vendor relationships.
Germany
Federal hospital infrastructure modernization programs sustain multi-year replacement cycles for aging VHF paging systems across district acute care networks. EU Radio Equipment Directive 2014/53/EU enforcement tightens electromagnetic exposure documentation for body-worn devices, with notified bodies processing submissions through twelve-week backlogs. Bavarian hospital clusters prioritize voice-capable alphanumeric units with nurse call integration.
India
District hospital networks lack redundant communication layers for emergency coordination, creating greenfield paging demand as federal health infrastructure budgets expand. The country's national telecommunications regulator shapes spectrum allocation for licensed medical communication bands. Maharashtra and Karnataka state hospital procurement committees evaluate basic numeric alerting systems for cost-sensitive deployments.
Japan
Metropolitan hospital systems in Kanto and Kansai regions maintain legacy paging infrastructure for earthquake-resilient staff communication where cellular network vulnerability persists. METI industrial standards shape device certification timelines for imported hardware. Osaka-based acute care clusters pilot BLE-enabled proximity systems for departmental coordination alongside traditional RF emergency alerting.
United Kingdom
NHS trust consolidation drives centralized procurement of encrypted messaging tiers above basic alerting functionality for physician coordination. MHRA oversight of patient-connected communication infrastructure elevates reliability requirements above consumer-grade alternatives. London and Southeast hospital networks unbundle pager service contracts from hardware purchases, favoring multi-hospital platform standardization.
Wireless Paging Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across encryption capability and healthcare integration depth. The vendor base stratifies between full-service operators with captive spectrum infrastructure and specialized integrators focused on middleware development. Three archetypes dominate: proprietary RF protocol specialists, healthcare integration service providers, and manufacturing-scale voice-capable producers. Consolidation pressure operates through health system procurement centralization and multi-hospital platform standardization mandates.
Within the proprietary protocol tier, LONG RANGE SYSTEMS, LLC. occupies a position exemplifying long-range campus deployment specialization. Telcom & Data Inc. represents the healthcare integration archetype, anchoring market presence through nurse call system interoperability. Visiplex, Inc. sits within the manufacturing-scale tier, sustaining production breadth across voice-capable alphanumeric lines. These three entities collectively illustrate how RF engineering depth, clinical workflow integration, and production scale constitute distinct competitive moats.
| Leading Market Players |
|---|
| LONG RANGE SYSTEMS, LLC. |
| Telcom & Data Inc. |
| Visiplex, Inc. |
| Quest Retail Systems Inc. |
| Pager Genius |
| JTECH |
| CORNELL |
| MMCall |
| INTERPAGE, Inc. |
| Others |
Value Network & Pricing Analysis
Encrypted messaging tiers diverge sharply from basic numeric alerting on certification requirements and spectrum resilience, compressing margins for commodity hardware while sustaining premium positioning for FDA-integrated systems. This bifurcation manifests in procurement patterns where US hospital networks absorb 18-month certification cycles for voice-capable alphanumeric units while hospitality chains optimize for unit cost in BLE coaster replacements.
Pricing Analysis
Uptime guarantees anchor value-based pricing for emergency code delivery systems, with acute care networks contracting for sub-second latency SLAs. Pricing stratifies across encrypted healthcare tiers, standard alphanumeric units, and economy numeric pagers based on FDA certification level and nurse call integration depth. Cost compression in hospitality BLE modules is intensifying because retail coaster deployments prioritize volume scale over message encryption. Healthcare procurement committees demonstrate lowest price sensitivity given patient safety mandates, while retail queue management buyers negotiate aggressively on per-unit hardware costs.
Supply Chain Analysis
Transoceanic freight volatility for semiconductor components from Taiwan and South Korea is elevating landed costs for VHF transceiver modules and display driver ICs. Specialized RF component fabrication concentrates in East Asian foundries, with pager assembly drawing from Chinese contract manufacturers and Mexican maquiladora facilities for North American demand. Single-source vulnerability for 152-158 MHz band filters creates procurement risk given limited qualified suppliers. Distribution runs through healthcare GPOs and hospitality equipment distributors rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive RF protocol development and spectrum infrastructure is accelerating as vendors defend margin position against unbundled service contracts and procurement centralization.
For Market Incumbents: To counter health system consolidation and centralized IT governance, LONG RANGE SYSTEMS and Telcom & Data must deepen proprietary protocol moats through backward integration into transceiver design and expand nurse call middleware capabilities. FCC Part 90 spectrum license holdings represent the critical defensive asset against cellular substitution threats. For New Entrants and Emerging Players: BLE-enabled proximity routing offers the most penetrable technology wedge for retail and hospitality verticals where licensed spectrum expertise is not required. Indian district hospital networks present white-space demand for basic numeric alerting systems. A channel partnership strategy with existing hospitality equipment distributors enables rapid volume scaling without captive sales infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with healthcare integration specialists given EU MDR Article 10 compliance mandates and US hospital digitization budgets. Long-term viability hinges on sustained FCC spectrum allocation and replacement cycle timing against legacy VHF infrastructure obsolescence. The signal to watch is German federal modernization program renewal commitments as a proxy for European replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary RF Protocol Development | Captive spectrum resilience differentiates emergency alerting from cellular failover risks. |
| Nurse Call System Integration | Voice-capable alphanumeric units command premium tier pricing in German acute care procurement. |
| BLE Module Convergence | Hybrid VHF-BLE architectures enable location-aware routing in Texas and California hospital campuses. |
| FDA Certification Investment | Patient-connected device oversight elevates reliability standards above consumer-grade alternatives. |
| Indian Distribution Partnership | District hospital greenfield demand for redundant communication layers supports volume expansion. |
Research Methodology
Multi-period observation of FCC spectrum allocation proceedings, EU MDR enforcement timelines, and hospital procurement database patterns anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and RF system integrators. Secondary validation drew from FDA 510(k) filings, FCC equipment authorization databases, German federal infrastructure budget disclosures, and ETSI certification registries. Bottom-up unit shipment estimates triangulated against top-down healthcare IT spending allocations.
Input-output matrices mapped transmitter infrastructure deployment, pager unit manufacturing capacity, and end-user replacement cycles across the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, technology protocol, and application criticality. CAGRs were derived from installed base turnover rates and digitization budget trajectories. Industry-specific forecast inputs incorporated FCC Part 90 license renewal patterns and EU Radio Equipment Directive enforcement lag effects.
Several conditions sit outside the modeled scope, including unannounced spectrum reallocation proceedings, hospital merger integration disruptions, and semiconductor foundry capacity shocks. Forecasts reflect assumptions about sustained licensed spectrum access and replacement cycle timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
Mobile WLAN Access Points Market
Wireless Technologies
Latin America Wireless Mesh Networking Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
Mobile Signal Booster Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Wireless Charger Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
Wigig Market
Wireless Technologies
Global WLAN Market
Wireless Technologies
North America Wireless Microphone Market