
 Wigig Market | 2026-2036
Wigig Market Size, Share, and Industry Trends Forecast 2026-2036
Wigig Market Intelligence
Multi-gigabit throughput certification is reorganizing competitive hierarchies in wireless connectivity. Qualcomm Technologies leverages its modem-RF system integration to sustain design wins across infrastructure and client devices. Intel Corporation anchors enterprise WiGig deployment through silicon platforms optimized for low-latency edge computing. Broadcom Inc. dominates baseband and RF front-end supply for access point manufacturers seeking beamforming performance.
WiGig denotes IEEE 802.11ad/ay-compliant wireless communication operating in the 60 GHz millimeter-wave band, delivering theoretical throughputs exceeding 7 Gbps using OFDM modulation and phased-array beamforming to overcome oxygen absorption losses. Its primary purpose is to replace wired gigabit Ethernet and DisplayPort connections in scenarios demanding uncompressed video streaming or near-instantaneous file synchronization. Consumer Electronics as an end-user segment occupies mature volume positions in docking and peripheral connectivity, while Automotive applications represent the fastest-growing margin pool as cabin infotainment architectures migrate to wireless hub-and-spoke topologies. Enterprise deployment of millimeter-wave backhaul is concentrating procurement among telecommunications operators replacing fiber-to-the-building runs in dense urban microcells.
The FCC governs 60 GHz unlicensed operation under Part 15 rules with specific effective isotropic radiated power limits that shape transmitter design and range capability. ETSI harmonization across European member states enables cross-border equipment certification, reducing manufacturer compliance fragmentation. China's MIIT issues radio type approval certificates that condition market access for imported WiGig chipsets and finished devices. Stakeholders must monitor spectrum reallocation proceedings and beamforming power-density recalibrations that could obsolete current antenna architectures before design amortization cycles complete.
Market Dynamics
Beamforming silicon consolidation and unlicensed 60 GHz spectrum harmonization are compressing equipment certification timelines while fragmenting antenna subsystem procurement. The FCC's Part 15 power-density recalibrations and ETSI's cross-border type-approval convergence are forcing module suppliers to redesign RF front-ends mid-cycle.
Growth Catalysts
- China base station densification:MIIT radio type approvals for imported chipsets are streamlining as telecom operators deploy millimeter-wave backhaul for urban microcells. Smart manufacturing facilities in Guangdong and Jiangsu provinces require high-throughput wireless links for automated inspection systems.
- Automotive cabin architecture migration:Wireless hub-and-spoke infotainment topologies are replacing copper harnesses in premium vehicle segments. DisplayPort and USB-C over 60 GHz eliminates connector wear while reducing assembly labor.
- ETSI harmonization:Cross-border equipment certification frameworks reduce manufacturer compliance fragmentation across European member states. Shared test procedures accelerate time-to-market for access point vendors serving multiple national markets.
Market Restraints
- Oxygen absorption physics:60 GHz signal attenuation limits outdoor range to approximately 100 meters regardless of transmit power, constraining rural deployment economics and forcing dense infrastructure builds.
- GaN and SiGe substrate concentration:RF front-end foundry capacity clusters in Taiwan and South Korea create supply vulnerability for phased-array antenna modules during semiconductor allocation cycles.
- Fiber-to-the-building substitution:GPON and XGS-PON deployments in commercial real estate compete directly with wireless backhaul for enterprise connectivity contracts in buildings with existing conduit infrastructure.
Strategic Opportunities
- India smart city infrastructure:Municipal surveillance and traffic management networks in Bangalore, Hyderabad, and Pune lack fiber trenching budgets. Unlicensed 60 GHz links offer rapid deployment for video backhaul without spectrum auction costs.
- WPA3-Enterprise convergence:Integration of WiGig with WPA3-Enterprise security frameworks positions millimeter-wave for government and financial campus networks requiring FIPS 140-2 compliance.
- Industrial AR/VR tethering:Untethered head-mounted displays in warehouse picking and maintenance training demand sub-5ms motion-to-photon latency. 802.11ay beamforming satisfies this where Wi-Fi 6E fails.
Industry Challenges
- Millimeter-wave RF engineering scarcity:Phased-array calibration and antenna-in-package design expertise concentrates among legacy radar and satellite communications specialists. Training pipelines for commercial WiGig module development remain underdeveloped.
- Legacy Ethernet integration friction:Enterprise IT departments resist parallel infrastructure management. WiGig access points must present as standard Layer 2 bridges without proprietary controller requirements to gain procurement approval.
- Pre-certification test equipment cost:60 GHz vector network analyzers and over-the-air chambers require capital outlays exceeding two million dollars, excluding smaller module vendors from independent validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wigig Market |
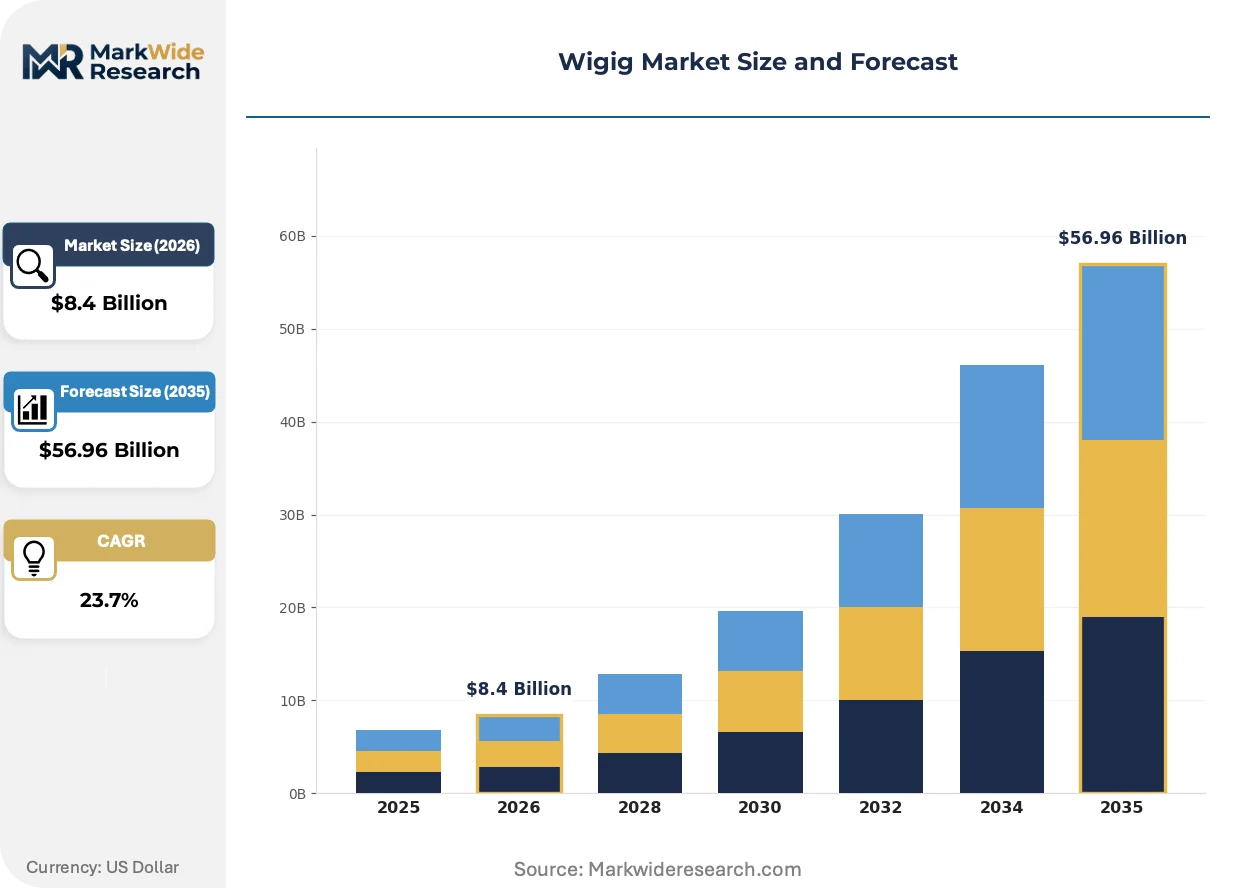
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $56.96 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Streaming, Gaming, Virtual Reality, Augmented Reality Technology: Wireless, Millimeter Wave, Orthogonal Frequency Division Multiplexing, Beamforming End User: Consumer Electronics, Telecommunications, Automotive, Smart Home Devices Deployment: Indoor, Outdoor, Enterprise, Public Hotspots |
| Companies Covered | Qualcomm Technologies, Inc., Peraso Technologies Inc., Intel Corporation, Broadcom Inc., Cisco Systems, Inc., Panasonic Holdings Corporation, STMicroelectronics, Tensorcom, Inc., Marvell Technology Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wigig Market Strategic Shifts & Innovations
Silicon photonics integration and software-defined beam management are compressing module form factors while expanding addressable use cases beyond consumer docking peripherals. These shifts are reconfiguring competitive advantage around semiconductor process geometry rather than discrete RF component sourcing.
802.11ay-compliant beam refinement protocols are supplanting legacy 802.11ad fixed-beam implementations in enterprise access point designs. Telecom operators in Germany and Japan are adopting these systems for building-to-building backhaul where trenching permits face municipal delays. The technology is supplanting licensed microwave links in sub-500-meter urban corridors, collapsing deployment timelines from months to days.
The FCC's 2023 Part 15 recalibration permitting higher effective isotropic radiated power for electronically steerable arrays has triggered antenna subsystem redesigns across North American equipment vendors. This relaxation enables single-hop links exceeding 300 meters with 64-element phased arrays. Outdoor point-to-multipoint infrastructure in the United States is responding with modular antenna platforms that separate radio heads from baseband processors for tower-mounted flexibility.
Enterprise procurement teams are consolidating wireless backhaul vendor relationships under managed service contracts rather than capital equipment purchases. Telecommunications operators in South Korea and Australia now prefer ten-year availability guarantees with remote monitoring over upfront hardware acquisition. This shift concentrates purchasing authority among systems integrators with nationwide service footprints, marginalizing pure-play hardware vendors lacking field engineering scale.
Wigig Market Segmentation
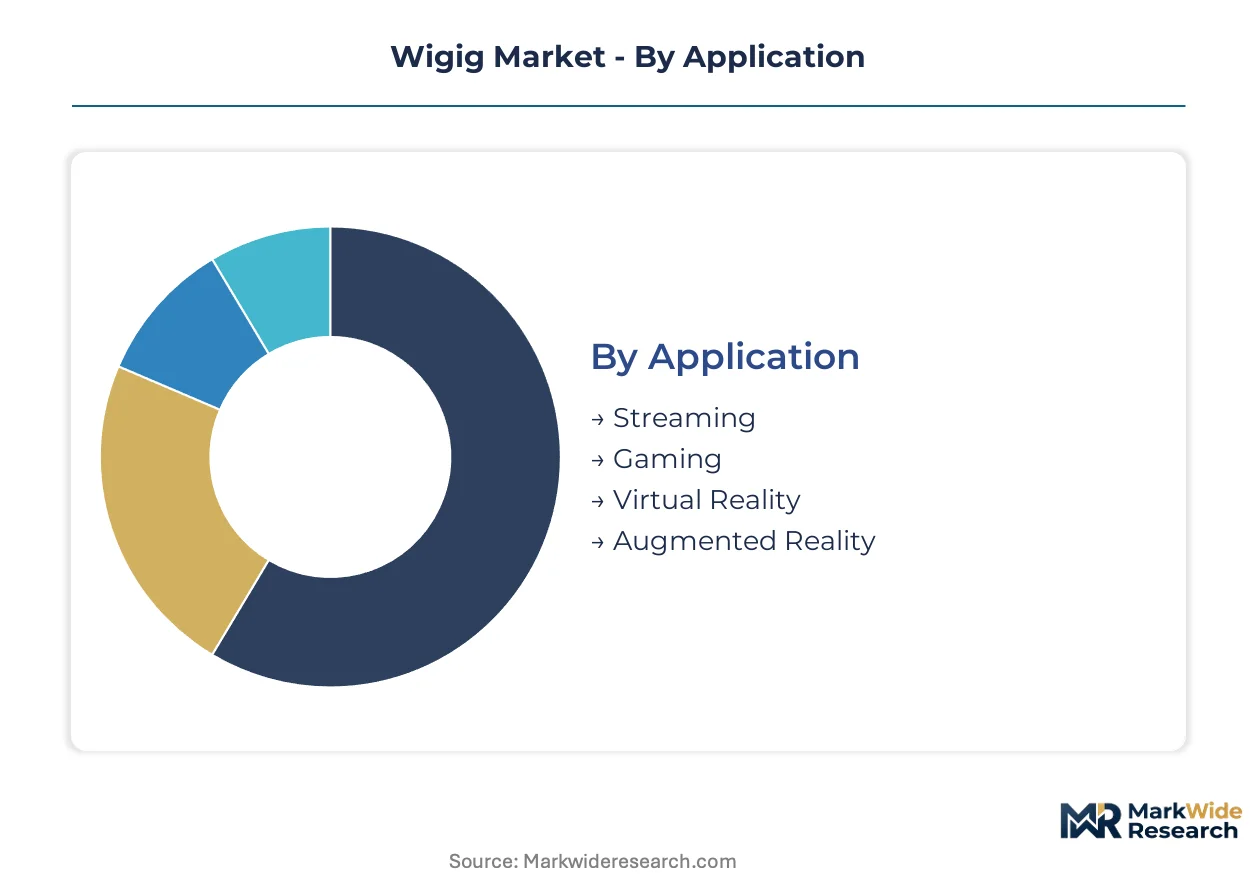
WiGig segmentation reveals divergent maturity curves across use cases and infrastructure environments. Application patterns split between latency-sensitive immersive media and throughput-heavy backhaul, while deployment models reflect fundamentally different regulatory and physical constraints.
Application:
Streaming applications dominate domestic consumption volumes across North American and European households, while gaming and immersive reality segments track export-led growth through Asia-Pacific manufacturing clusters.
- Streaming:Uncompressed 4K/8K video distribution over 60 GHz eliminates buffering artifacts in professional broadcast environments. Demand concentrates in Los Angeles and London post-production facilities where wire replacement reduces setup complexity. Regulatory clarity from the FCC and Ofcom underpins equipment certification for studio deployments.
- Gaming:Cloud gaming services leverage sub-5ms latency for controller-to-screen responsiveness that Wi-Fi 6E cannot guarantee. South Korean internet cafes and Japanese esports venues anchor procurement volumes, with Shenzhen peripheral manufacturers supplying beamforming dongles for international distribution.
- Virtual Reality:PC-tethered VR headsets in enterprise training centers.
- Augmented Reality:Industrial maintenance overlays in German automotive plants.
Streaming holds the largest share; momentum sits with gaming.
Technology:
Cost tiers separate legacy 802.11ad implementations from premium 802.11ay platforms, with beamforming silicon commanding price premiums over basic OFDM modules.
- Wireless:Generic 60 GHz radio implementations without protocol-specific optimization.
- Millimeter Wave:Raw 60 GHz carrier operation subject to oxygen absorption physics limits range regardless of transmit power, constraining outdoor economics and forcing dense infrastructure builds in urban corridors.
- Orthogonal Frequency Division Multiplexing:Modulation scheme enabling 7+ Gbps throughputs in licensed-exempt spectrum. Base station manufacturers in China and South Korea favor OFDM for backhaul density.
- Beamforming:Phased-array antenna systems dynamically steer energy toward receivers. FCC Part 15 recalibrations permitting higher EIRP for electronically steerable arrays triggered redesigns across North American vendors, extending single-hop links beyond 300 meters with 64-element arrays.
Beamforming captures the steepest expansion trajectory as infrastructure vendors upgrade from fixed-beam legacy designs.
End User:
Volume concentrates in consumer electronics maturity, while margin expansion tracks automotive cabin architecture shifts and telecommunications backhaul procurement.
- Consumer Electronics:Docking stations and peripheral connectivity in mature replacement cycles. Retail channel inventory in United States and Germany turns predictably around device refresh seasons.
- Telecommunications:Urban microcell backhaul in China drives procurement concentration. MIIT radio type approvals for imported chipsets streamline as operators densify base stations in Guangdong and Jiangsu provinces.
- Automotive:Wireless hub-and-spoke infotainment topologies replace copper harnesses in premium segments. DisplayPort and USB-C over 60 GHz eliminates connector wear while reducing assembly labor at Stuttgart and Munich manufacturing centers.
- Smart Home Devices:Whole-home video distribution systems in multi-dwelling units.
Consumer Electronics holds the largest share; momentum sits with Automotive.
Deployment:
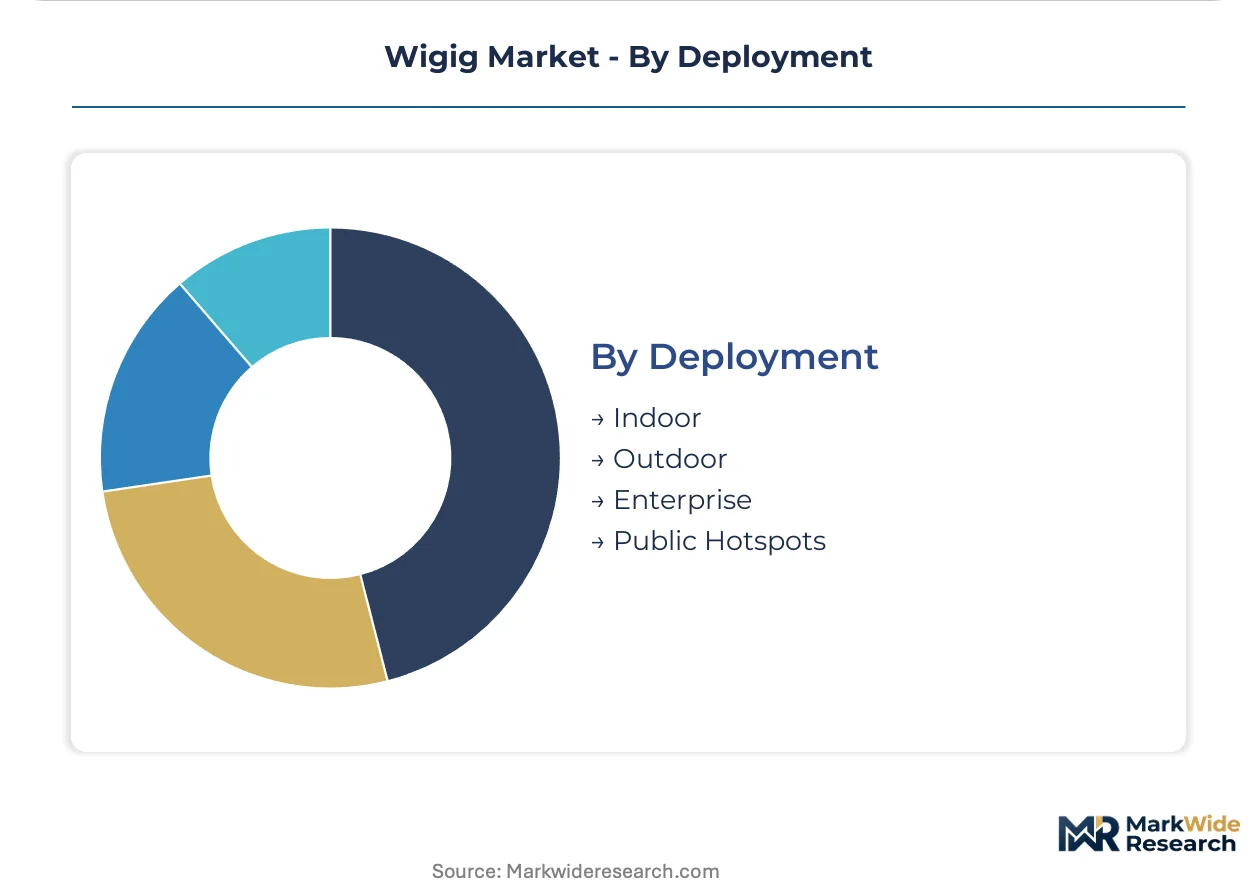
Customer type stratification separates enterprise IT procurement from carrier-managed service contracts, with public infrastructure lagging on municipal budget cycles.
- Indoor:Enterprise conference room and classroom wire replacement. Oxygen absorption matters less in controlled environments, permitting lower-cost antenna designs.
- Outdoor:Building-to-building links where trenching permits face delays. German and Japanese operators adopt 802.11ay for sub-500-meter urban corridors, collapsing deployment timelines from months to days.
- Enterprise:Campus networks requiring WPA3-Enterprise security frameworks and FIPS 140-2 compliance. Procurement teams consolidate vendor relationships under managed service contracts with ten-year availability guarantees.
- Public Hotspots:Municipal Wi-Fi augmentation in Bangalore and Hyderabad where fiber trenching budgets are constrained.
Enterprise holds the largest share; momentum sits with Outdoor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
WiGig trade flows reveal concentrated chipset production in East Asian foundries balanced against equipment assembly in North American and European system houses. Import dependency for phased-array modules shapes procurement strategies across major demand centers.
United States
Enterprise campus networks and broadcast studios in Los Angeles drive equipment demand for uncompressed 4K distribution. The FCC's Part 15 power-density recalibrations for electronically steerable arrays enable extended-range outdoor links. Silicon design activity clusters in San Diego and San Jose, where modem-RF integration teams serve infrastructure vendors.
China
Telecom operator base station densification in Guangdong and Jiangsu provinces consumes millimeter-wave backhaul modules for urban microcells. MIIT radio type approval certificates condition market access for imported chipsets, streamlining as domestic 5G-Advanced deployments accelerate. Smart manufacturing facilities in Shenzhen require high-throughput wireless links for automated inspection systems.
Germany
Automotive cabin infotainment architectures at Stuttgart and Munich manufacturing centers replace copper harnesses with wireless hub-and-spoke topologies. ETSI harmonization enables cross-border equipment certification, reducing compliance fragmentation for access point vendors. Building-to-building backhaul in Berlin and Hamburg collapses deployment timelines where trenching permits face municipal delays.
Japan
Esports venues and internet cafes in Tokyo and Osaka anchor procurement volumes for low-latency gaming peripherals. METI industrial policy supports millimeter-wave R&D consortia targeting 802.11ay beam refinement protocols. Nagoya-area automotive suppliers evaluate DisplayPort-over-60GHz for next-generation cockpit displays.
South Korea
Cloud gaming services and enterprise VR training centers in Seoul demand sub-5ms motion-to-photon latency that beamforming silicon delivers. Telecommunications operators prefer ten-year availability guarantees with remote monitoring over upfront hardware acquisition. Busan-area module houses supply phased-array antennas for regional equipment integrators.
Wigig Market Key Industry Players
Listed leaders compete with private specialists across semiconductor and system integration layers. The vendor base organizes around modem-RF platform providers, discrete baseband suppliers, and antenna subsystem specialists. Three archetypes dominate: integrated semiconductor platforms, RF front-end component houses, and managed service systems integrators. Competitive moves concentrate on strategic partnerships for beamforming silicon and geographic expansion through certification reciprocity agreements.
Within the integrated platform tier, Qualcomm Technologies and Intel Corporation anchor positions through modem-RF system integration spanning infrastructure and client devices. Broadcom Inc. exemplifies the RF front-end archetype, supplying baseband and phased-array components to access point manufacturers. Marvell Technology Group Ltd. occupies a position between these tiers, bridging storage networking heritage with wireless infrastructure silicon.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| Peraso Technologies Inc. |
| Intel Corporation |
| Broadcom Inc. |
| Cisco Systems, Inc. |
| Panasonic Holdings Corporation |
| STMicroelectronics |
| Tensorcom, Inc. |
| Marvell Technology Group Ltd. |
| Others |
Cost & Logistics Intelligence
GaN-on-SiC substrate substitution for legacy silicon germanium is redrawing foundry geography toward Taiwan and South Korea while compressing module pricing through economies of scale in phased-array production. This materials transition simultaneously elevates performance tiers and concentrates procurement leverage among integrated platform vendors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in beamforming silicon procurement. Price differentiation rests on FCC Part 15 certification grade and volume scale commitments from telecommunications operators. Cost compression in standard-tier modules is intensifying because Chinese base station densification is forcing foundry allocation competition. Enterprise IT departments show highest price sensitivity, while automotive Tier 1 suppliers accept premium positioning for cabin infotainment integration.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-Singapore trade lane and Kaohsiung port congestion are elevating landed costs for North American equipment vendors sourcing phased-array substrates. Foundry capacity clusters in Taiwan, South Korea, and Japan draw from gallium nitride wafers, silicon germanium epitaxy, and advanced packaging substrates. Single-source vulnerability concentrates in TSMC's specialty process nodes for beamforming ASICs. Distribution runs through Shenzhen module houses to Berlin and San Jose system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WiGig demand is recovering from semiconductor allocation troughs as China 5G-Advanced deployments and automotive cabin architecture migrations restock channel inventory. Base station densification cycles and unlicensed spectrum harmonization are synchronizing procurement timing across telecommunications and automotive verticals.
For Market Incumbents: Shield modem-RF platform margins through captive supply of phased-array calibration IP against emerging fabless competitors. Secure ten-year availability guarantees with South Korean operators to lock out managed service challengers. Deepen backward integration into antenna-in-package design to preserve differentiation as ETSI harmonization commoditizes basic module certification. For New Entrants and Emerging Players: Industrial AR/VR tethering gaps in German automotive plants and warehouse logistics networks offer white-space entry where latency requirements exceed Wi-Fi 6E capabilities. India's smart city infrastructure presents the most penetrable geography given constrained fiber trenching budgets in Bangalore and Hyderabad. Pursue WPA3-Enterprise certification as the go-to-market wedge for government campus networks requiring FIPS 140-2 compliance. For Investors and Strategic Acquirers: The market sits at an early-cycle expansion phase that favors beamforming silicon specialists with automotive qualification track records. Long-term viability hinges on 802.11ay protocol dominance displacing legacy 802.11ad fixed-beam implementations. Monitor FCC Part 15 power-density recalibration proceedings as the signal for antenna subsystem redesign cycles that trigger consolidation among module vendors lacking R&D scale.| Strategic Initiative | Industry Significance |
|---|---|
| Beamforming Silicon Platform Integration | Qualcomm's modem-RF consolidation forces discrete baseband vendors toward niche automotive applications. |
| ETSI Cross-Border Certification Reciprocity | Reduces compliance fragmentation for access point vendors serving German and French municipal networks simultaneously. |
| Automotive DisplayPort-over-60GHz Qualification | Stuttgart and Munich manufacturing centers validate wireless hub-and-spoke topologies for premium vehicle segments. |
| Managed Service Contract Consolidation | South Korean operators prefer ten-year availability guarantees, marginalizing pure-play hardware vendors. |
| Industrial AR/VR Tethering Partnership | Sub-5ms motion-to-photon latency requirements in warehouse picking create demand pull for 802.11ay beam refinement. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with RF front-end engineering directors, telecommunications procurement leads, automotive platform architects, and semiconductor foundry planning officers; and secondary validation through FCC equipment authorization databases, MIIT radio type approval filings, ETSI harmonization directives, and SEC 10-K disclosures from listed component vendors. Bottom-up module shipment estimates and top-down infrastructure capex trajectories were triangulated against foundry utilization reports.
Across the projection horizon, the analytical framework modeled demand across application type, technology tier, end-user vertical, and deployment environment. CAGRs were derived from regression analysis of historical base station densification patterns and automotive infotainment architecture refresh cycles. Forecast inputs incorporated oxygen absorption physics constraints on outdoor link economics and GaN substrate supply elasticity from Taiwanese foundry partners.
Forecasts assume regulatory continuity in FCC Part 15, ETSI unlicensed spectrum frameworks, and MIIT radio type approval procedures; material policy shifts would require re-modeling. Specific risks include beamforming power-density recalibrations that obsolete current antenna architectures and semiconductor allocation disruptions affecting phased-array module availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Bluetooth Audio Codec Market
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
Public Wi-Fi Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
Global Massive MIMO Market