
 France Fixed Wireless Access (FWA) Market | 2026-2036
France Fixed Wireless Access (FWA) Market Size, Share, and Industry Trends Forecast 2026-2036
France Fixed Wireless Access (FWA) Market Insights
Modular service bundling is restructuring buyer choice across the France FWA landscape, as operators unbundle residential, business, and government tiers to match granular connectivity needs. Orange S.A. leverages its national backbone infrastructure to anchor premium service tiers in underserved departments. Bouygues Telecom S.A. competes through aggressive rural coverage expansion, while Nokia Corporation specializes in supplying massive MIMO radio units optimized for French spectrum allocations.
France Fixed Wireless Access denotes a broadband delivery architecture where radio signals transmit data between carrier base stations and customer premises equipment, typically operating in sub-6 GHz and millimeter-wave bands with throughput capabilities exceeding 100 Mbps. Its primary commercial purpose substitutes for fiber-to-the-home in regions where trenching costs prove prohibitive. 5G technology now leads infrastructure deployments among mobile operators seeking capacity offload, while residential service types capture the deepest subscriber pools despite thinner margins. Enterprise end users represent the fastest-growing segment, as Paris-Saclay SMBs and logistics hubs near Lyon demand SLA-backed wireless alternatives to copper retirement.
ARCEP, France's electronic communications regulator, enforces wholesale access obligations and coverage mandates that directly shape operator rollout priorities and infrastructure sharing economics. The country's national cybersecurity agency, ANSSI, certifies CPE hardware against sovereign resilience standards, creating compliance barriers for non-European vendors. Stakeholders must monitor how upcoming spectrum auctions and France's digital sovereignty agenda recalibrate vendor eligibility and deployment timelines.
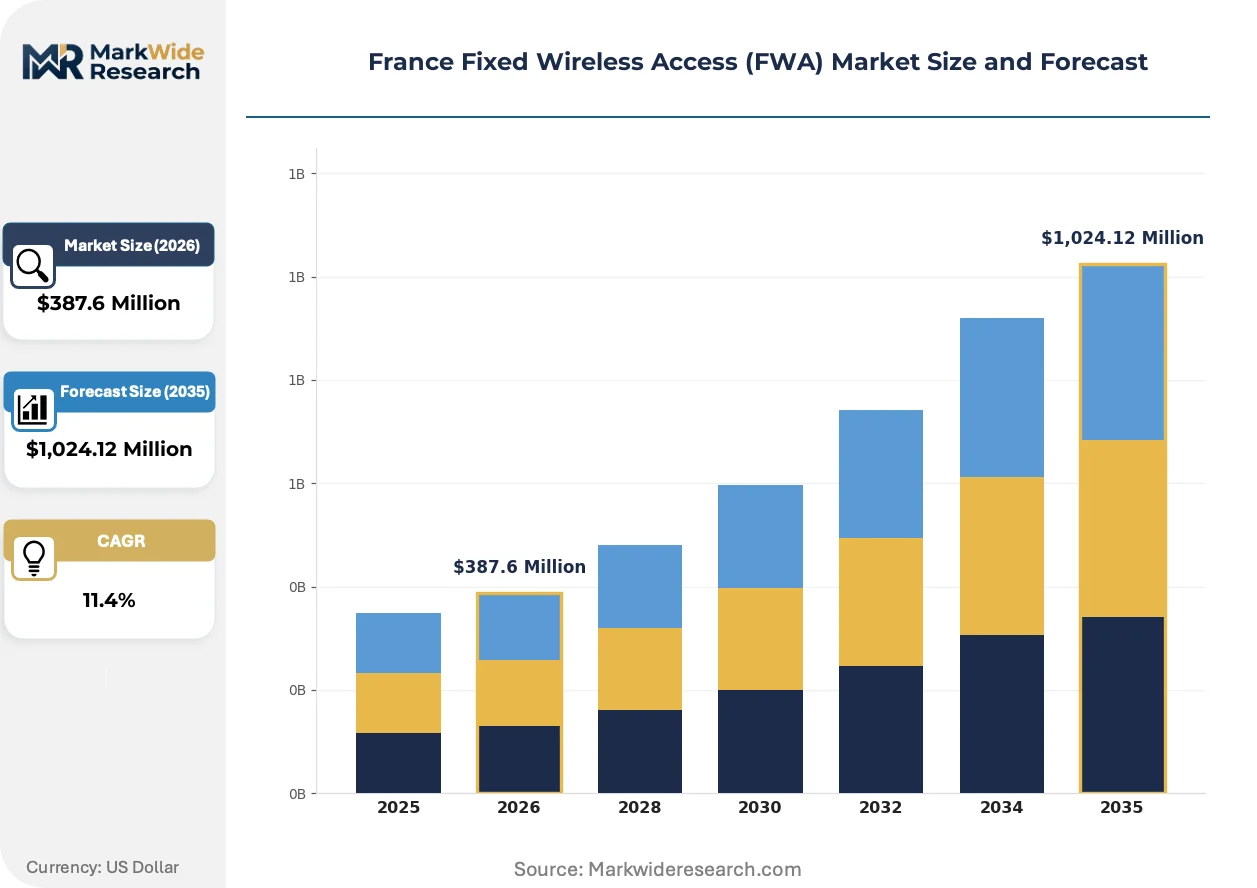
Market Dynamics
ARCEP's mid-band 5G spectrum reallocation is compressing operator deployment timelines while forcing infrastructure sharing agreements that reshape capital allocation across French departments.
Growth Catalysts
- Rural fiber backhaul gaps:Brittany and Normandy municipalities are accelerating FWA procurement to bypass prohibitive trenching costs in granite-rich subsoil regions.
- ANSSI CPE certification:Sovereign resilience standards for customer premises equipment are filtering vendor pools and elevating European hardware suppliers in public tenders.
- Paris-Saclay enterprise corridor:SMB clusters are abandoning copper-dependent leased lines for SLA-backed wireless alternatives with sub-10ms latency guarantees.
Market Restraints
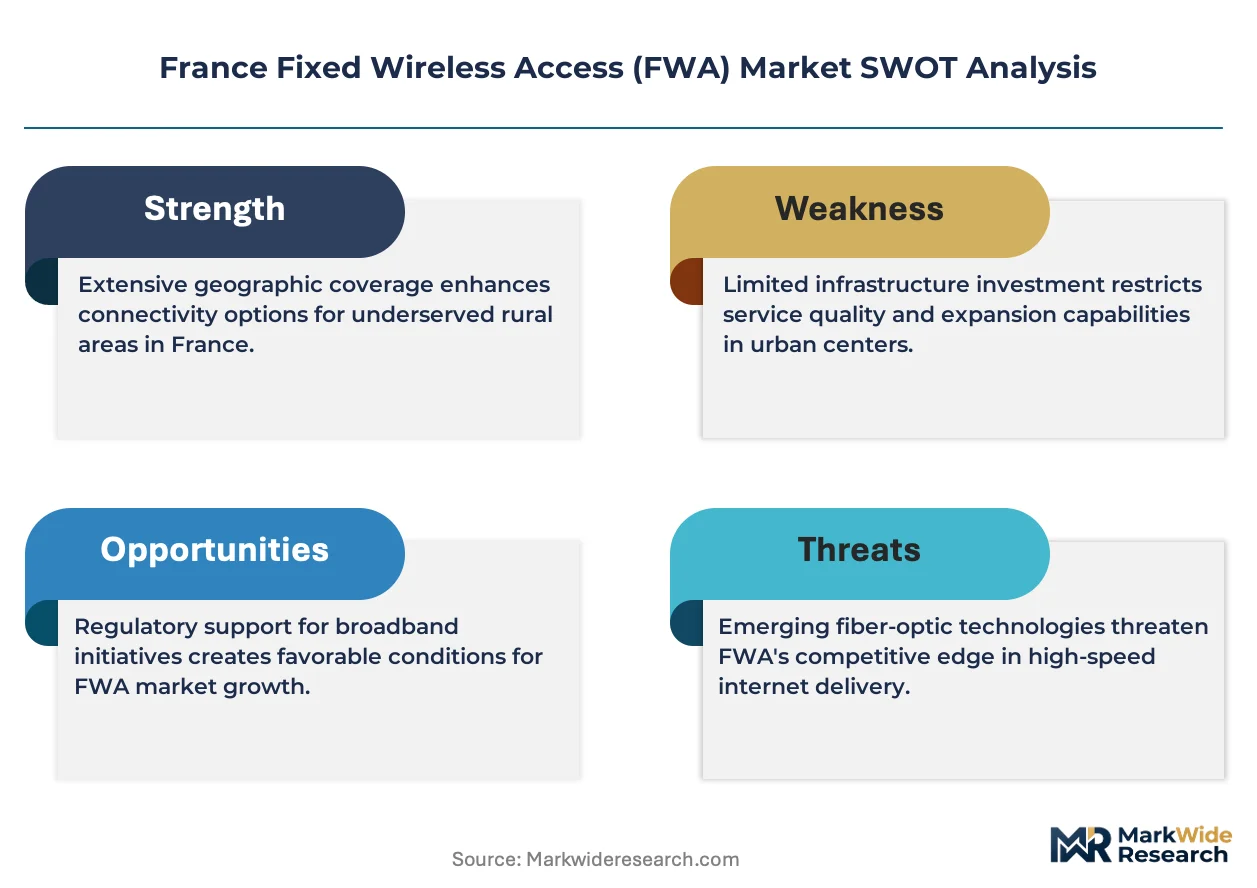
- Mid-band spectrum scarcity:ARCEP's auction reserve prices inflate operator entry costs and constrain rural rollout budgets outside priority zones.
- Non-European vendor exclusion:ANSSI hardware certification creates structural barriers for Asian CPE manufacturers seeking public sector contracts.
- Fiber substitution threat:Orange S.A.'s accelerated FTTH deployment in peri-urban departments directly competes with FWA value propositions in overlapping coverage areas.
Strategic Opportunities
- Grand Est logistics hubs:Strasbourg and Mulhouse distribution centers are piloting private 5G FWA networks for warehouse automation and fleet management.
- CSRD sustainability reporting:Corporate disclosure mandates are driving enterprises toward wireless infrastructure with verifiable carbon footprints versus fiber trenching emissions.
- Massive MIMO-NFV convergence:Virtualized radio access networks are enabling smaller operators to lease rather than build core infrastructure, lowering market entry barriers.
Industry Challenges
- Radio frequency engineering talent:Specialized 5G propagation modeling expertise concentrates in Paris and Grenoble, creating recruitment bottlenecks for regional deployments.
- Legacy copper integration:Operators must maintain hybrid service architectures during copper retirement transitions, complicating network operations center workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Fixed Wireless Access (FWA) Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE, 5G, WiMAX, HSPA Service Type: Residential, Business, Government, Community Deployment Model: On-Premises, Cloud-Based, Hybrid, Remote End User: Consumers, SMBs, Enterprises, Educational Institutions |
| Companies Covered | Huawei Technologies Co. Limited, Qualcomm Technologies, Inc., Orange S.A, Cisco Systems, Inc., Samsung Electronics Co., Ltd., Bouygues Telecom S.A, Telefonaktiebolaget LM Ericsson, ZTE Corporation, Nokia Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Fixed Wireless Access (FWA) Market Trends and Innovations
Software-defined radio architectures and AI-driven network optimization are compressing operational complexity while enabling dynamic spectrum allocation across French operator footprints.
Massive MIMO beamforming is automating interference management in dense suburban deployments. Bouygues Telecom S.A. and SFR are deploying 64T64R radio units across Lyon and Marseille metropolitan zones. This automation is reducing manual cell planning cycles from months to weeks while improving spectral efficiency in shared infrastructure scenarios.
ARCEP's wholesale access obligations are mandating infrastructure sharing in underserved departments. The regulator's 2024 framework requires dominant operators to open dark fiber and tower assets to MVNOs. Rural municipalities in Limousin and Auvergne are leveraging these rules to aggregate demand and negotiate multi-operator FWA coverage.
Enterprise buyers are consolidating connectivity procurement through systems integrators rather than direct operator relationships. Paris-Saclay technology clusters are outsourcing network design to specialized VARs with vertical expertise. This channel shift is most pronounced in Île-de-France, where SMBs prioritize single-vendor accountability over operator direct sales engagement.
France Fixed Wireless Access (FWA) Market Segmentation
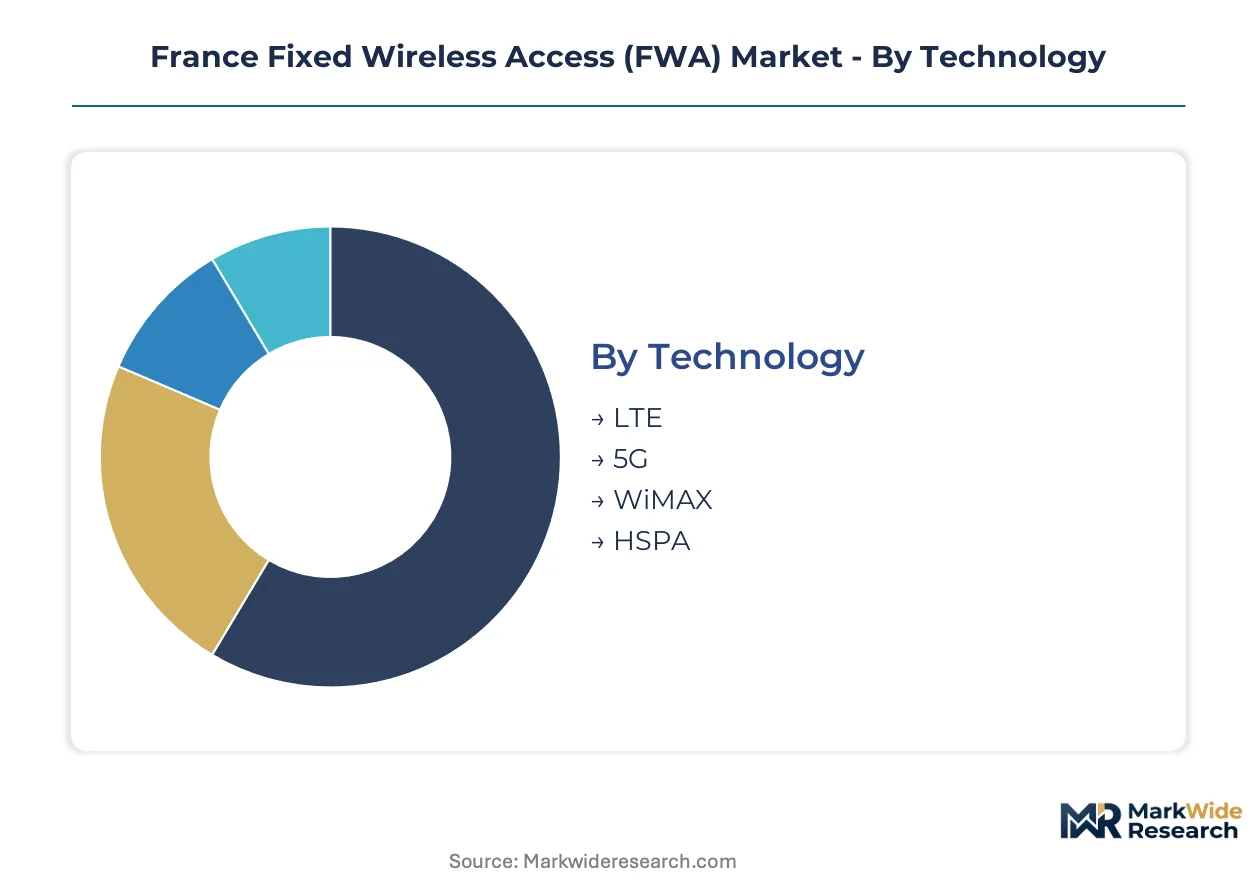
Capital allocation across the France FWA market diverges sharply by segment, with infrastructure-heavy categories demanding sustained investment while service tiers compete on margin structure. Understanding these fault lines clarifies where ARCEP's regulatory pressure and ANSSI certification requirements reshape competitive economics.
Technology:
5G deployments consume the largest share of operator capital expenditure due to massive MIMO radio unit costs and spectrum license fees, while legacy alternatives retain residual utility in constrained deployment scenarios.
- 5G:Massive MIMO beamforming architectures operating in ARCEP-allocated mid-band spectrum deliver sub-10ms latency for Paris-Saclay enterprise clusters. Brittany and Normandy municipalities prioritize 5G FWA to bypass granite-rich trenching costs where fiber backhaul proves prohibitive.
- LTE:Established 4G infrastructure supports rural coverage obligations with lower spectrum costs per subscriber. Departments in Limousin and Auvergne leverage existing LTE towers for cost-effective FWA extension where 5G economics fail.
- WiMAX:Legacy TDD-based systems persist in isolated industrial zones with minimal migration incentives.
- HSPA:3G-derived fallback technology serves emergency continuity scenarios during copper retirement transitions.
5G absorbs the bulk of installed capacity; LTE is expanding most quickly in rural priority zones where capital efficiency dominates.
Service Type:
Margin profiles stratify across service tiers, with government contracts commanding premium pricing through sovereign resilience requirements while residential volumes thin per-subscriber economics.
- Residential:Mass-market subscriptions drive volume economics for Orange S.A. and Bouygues Telecom S.A. in peri-urban departments with overlapping fiber competition. ARCEP's wholesale access obligations enable MVNO participation in price-sensitive segments.
- Business:SLA-backed connectivity with guaranteed throughput attracts Paris-Saclay SMBs abandoning copper-dependent leased lines. VARs and systems integrators increasingly intermediate procurement in Île-de-France technology corridors.
- Government:ANSSI-certified CPE mandates filter vendor pools for public sector tenders, elevating European hardware suppliers.
- Community:Municipal aggregation models in Auvergne and Limousin negotiate multi-operator coverage through infrastructure sharing frameworks.
Residential subscriptions dominate active accounts; business services gain share fastest as copper retirement accelerates.
Deployment Model:
Operational complexity varies by infrastructure control level, with cloud-based architectures reducing fixed costs for smaller entrants while hybrid models balance latency against capital efficiency.
- On-Premises:Dedicated baseband processing at cell sites minimizes latency for Lyon logistics hubs and Strasbourg distribution centers piloting warehouse automation. Private 5G FWA networks in Grand Est require full infrastructure ownership.
- Hybrid:Split processing between edge and core enables mid-sized operators to optimize capital deployment across urban and rural footprints.
- Cloud-Based:Virtualized radio access networks allow smaller operators to lease core infrastructure rather than build, lowering entry barriers in competitive departments.
- Remote:Fully centralized architectures serve sparse population zones with minimal local equipment requirements.
On-premises deployments anchor latency-critical applications; cloud-based models are climbing the fastest as NFV adoption spreads.
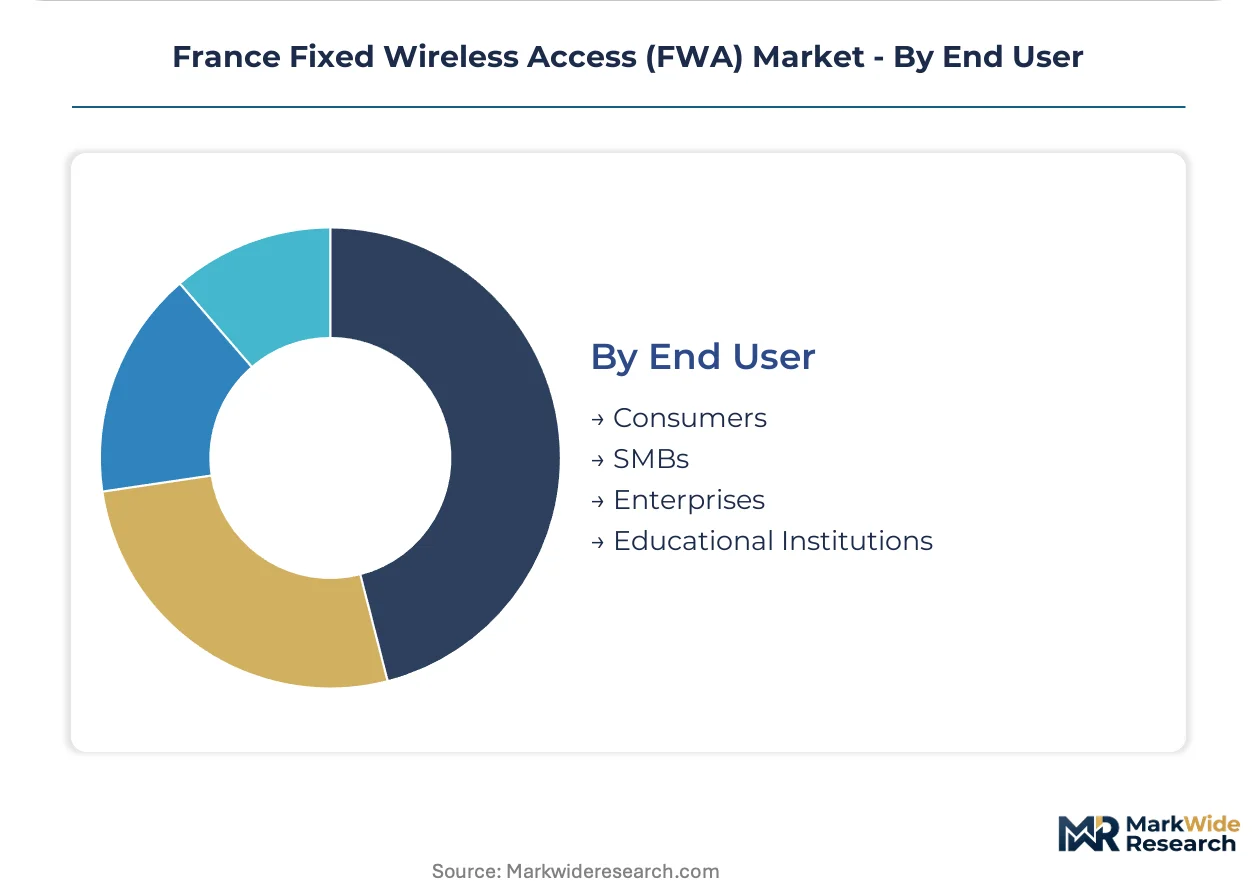
End User:
Procurement sophistication distinguishes customer segments, with enterprises demanding outcome-based contracts while consumers prioritize price transparency and installation speed.
- Enterprises:CSRD sustainability reporting mandates drive wireless infrastructure selection based on verifiable carbon footprints versus fiber trenching emissions. Grand Est logistics hubs and Paris-Saclay technology clusters lead enterprise FWA adoption.
- SMBs:Single-vendor accountability preferences channel procurement through specialized VARs with vertical expertise in Île-de-France.
- Consumers:Price-sensitive households in peri-urban departments choose between Orange S.A.'s FTTH and FWA alternatives where coverage overlaps.
- Educational Institutions:Campus-wide connectivity requirements in university towns leverage community deployment models with municipal support.
Enterprises command the highest revenue per connection; SMBs represent the steepest expansion trajectory as copper retirement forces infrastructure decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France produces FWA infrastructure equipment through Nokia Corporation's radio manufacturing and deploys networks nationwide, yet consumption concentrates in Brittany, Normandy, and Île-de-France where fiber gaps and enterprise demand persist. ARCEP's regulatory frameworks shape deployment economics across all regions.
Île-de-France
Paris-Saclay technology clusters drive enterprise FWA procurement as SMBs abandon copper-dependent leased lines for SLA-backed wireless alternatives. ANSSI certification requirements filter vendor pools for public sector contracts. The metropolitan zone hosts the densest concentration of systems integrators intermediating connectivity procurement for outcome-based contracts.
Brittany
Rural municipalities accelerate FWA procurement to bypass prohibitive trenching costs in granite-rich subsoil regions where fiber backhaul proves uneconomical. ARCEP's wholesale access obligations enable demand aggregation across multiple communes. Brest and Rennes anchor regional deployment coordination for multi-operator coverage agreements.
Normandy
Coastal departments leverage FWA to close connectivity gaps in dispersed agricultural and tourism-dependent communities. The region's topography complicates fiber deployment, elevating wireless alternatives. Le Havre logistics operators pilot private 5G networks for port automation and fleet management applications.
Auvergne-Rhône-Alpes
Lyon logistics hubs and Grenoble's radio engineering talent concentration support latency-critical industrial deployments. Massive MIMO beamforming trials automate interference management in dense suburban zones. Clermont-Ferrand and Saint-Étienne municipalities negotiate infrastructure sharing through ARCEP's 2024 framework.
Grand Est
Strasbourg and Mulhouse distribution centers pilot private 5G FWA networks for warehouse automation and supply chain visibility. CSRD sustainability reporting mandates drive selection of wireless infrastructure with verifiable carbon footprints versus fiber trenching emissions. The region borders German and Swiss markets, creating cross-border spectrum coordination requirements.
France Fixed Wireless Access (FWA) Market Competitive Landscape
The competitive structure tilts toward national mobile network operators with backbone infrastructure assets. Orange S.A. and Bouygues Telecom S.A. anchor the service provider tier, while equipment vendors supply massive MIMO radio units optimized for French spectrum allocations. Three archetypes dominate: incumbent telecom operators leveraging national backbones, challenger mobile operators expanding rural coverage, and European equipment specialists meeting ANSSI certification requirements. Dominant competitive moves include infrastructure sharing agreements mandated by ARCEP and vertical specialization around sovereign resilience standards.
Within the operator tier, Orange S.A. and Bouygues Telecom S.A. exemplify divergent rural deployment strategies, while Nokia Corporation anchors the European equipment vendor archetype. Among global technology suppliers, Huawei Technologies Co. Limited and ZTE Corporation represent non-European hardware manufacturers facing structural barriers in public sector tenders. Qualcomm Technologies, Inc. and Samsung Electronics Co., Ltd. occupy positions in the semiconductor and device ecosystem supporting CPE deployment. Telefonaktiebolaget LM Ericsson and Cisco Systems, Inc. exemplify network infrastructure specialists competing for operator contracts.
| Leading Market Players |
|---|
| Huawei Technologies Co. Limited |
| Qualcomm Technologies, Inc. |
| Orange S.A |
| Cisco Systems, Inc. |
| Samsung Electronics Co., Ltd. |
| Bouygues Telecom S.A |
| Telefonaktiebolaget LM Ericsson |
| ZTE Corporation |
| Nokia Corporation |
| Others |
Pricing and Supply Chain Analysis
Spectrum license fees cascade through operator pricing tiers, with ARCEP auction reserve costs compressing rural deployment budgets while metropolitan enterprise subscriptions absorb premium markups for ANSSI-certified CPE hardware.
Pricing Analysis
Margin tightening in residential tiers reflects ARCEP wholesale access obligations enabling MVNO price competition. Three-tier pricing structure across premium SLA-backed enterprise, standard business, and economy residential levels stratifies by certification grade and latency guarantees. Cost-down pressure on rural deployments accelerates because granite-rich trenching alternatives command infrastructure premiums. Enterprise buyers in Paris-Saclay exhibit lowest price sensitivity, while peri-urban households face acute trade-offs between Orange S.A. FTTH and FWA alternatives.
Supply Chain Analysis
Refurbished CPE flows from enterprise upgrade cycles feed secondary markets in Limousin and Auvergne municipal aggregations. Manufacturing concentrates in Finland, Sweden, and China for massive MIMO radio units, with European vendors dominating ANSSI-certified hardware tiers. Component sourcing draws from Taiwanese semiconductor foundries, South Korean memory suppliers, and German precision filter manufacturers. Single-source vulnerability concentrates in 5G baseband processor supply. Distribution runs through operator-direct channels in Île-de-France and systems integrator intermediation for enterprise corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANSSI sovereign resilience certification creates a structural barrier-to-entry moat, elevating compliant European vendors while filtering non-European competitors from public sector revenue pools.
For Market Incumbents: Anticipate fiber substitution threats from Orange S.A.'s accelerated FTTH rollout by anchoring FWA value propositions in latency-critical applications where wireless outperforms trenching delays. Defend rural market share through infrastructure sharing agreements mandated under ARCEP's 2024 framework, leveraging tower asset control as a channel lever against challenger mobile operators. For New Entrants and Emerging Players: Begin with cloud-based NFV architectures to bypass capital-intensive core infrastructure builds, targeting Grand Est logistics hubs where private 5G FWA pilots demonstrate unmet demand for warehouse automation connectivity. Channel partnerships with Paris-Saclay systems integrators offer the most penetrable go-to-market angle, outsourcing direct operator sales engagement to VARs with vertical expertise. For Investors and Strategic Acquirers: ARCEP spectrum auction participation rates are the leading indicator that deployment economics are compressing toward consolidation thresholds. Long-term viability favors equipment vendors with ANSSI certification pipelines and operator service providers with backbone infrastructure ownership. Target acquisition archetypes include regional VARs with Île-de-France enterprise relationships and European CPE manufacturers with sovereign resilience credentials.| Strategic Initiative | Industry Significance |
|---|---|
| Infrastructure Sharing Agreement | ARCEP-mandated tower access reduces rural rollout capital requirements for challenger operators. |
| ANSSI Certification Investment | Sovereign resilience credentials unlock public sector tenders and filter non-European vendor competition. |
| Massive MIMO-NFV Integration | Virtualized radio access networks lower entry barriers for cloud-native operators in competitive departments. |
| Vertical Specialization Partnership | Systems integrator alliances capture Paris-Saclay enterprise procurement shifting away from direct operator sales. |
| Private 5G Network Deployment | Grand Est logistics pilots demonstrate SLA-backed wireless alternatives to copper-dependent leased lines. |
Research Methodology
Independent corroboration across network operator procurement officers, municipal digital infrastructure directors, and systems integrator account executives underwrites the qualitative findings. Primary fieldwork combined with secondary validation from ARCEP regulatory filings, ANSSI certification databases, and operator spectrum auction disclosures anchors the analysis. Bottom-up subscriber projections and top-down infrastructure investment estimates triangulate market sizing.
Comparable historical deployment periods across LTE and early 5G rollouts anchored the forecast window to proven infrastructure buildout patterns. The analytical framework models technology generation, service tier, deployment architecture, and end-user vertical across the projection horizon. CAGRs derive from installed base growth rates and capital intensity benchmarks. Spectrum allocation timelines and copper retirement schedules feed directly into adoption curve assumptions.
Underlying measurement precision varies by segment; enterprise and government tiers carry tighter precision than residential subscriptions due to contract visibility. Forecasts reflect documented assumptions about ARCEP regulatory continuity and ANSSI certification scope. Practitioners should monitor spectrum auction reserve price adjustments and FTTH coverage expansion maps for early signals of FWA substitution pressure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Fixed LTE Wireless Broadband Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Wifi Kiosks Market