
 India Feminine Hygiene Market | 2026-2036
India Feminine Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
India Feminine Hygiene Market Foresight
Market Context
The capital-intensity divergence between multinational-backed and domestic-funded players is rotating competitive dynamics across India's feminine hygiene sector. Procter & Gamble Hygiene and Health Care Ltd leverages its global R&D infrastructure to sustain premium positioning in Tier-1 cities. Sirona Hygiene competes through specialized digital-first distribution, while Emami Ltd anchors its portfolio with Ayurveda-inspired formulations targeting price-sensitive segments.
Technical Definition and Segment Structure
India feminine hygiene encompasses absorbent and non-absorbent products engineered with superabsorbent polymers, breathable polyethylene back sheets, and pH-balanced surface layers designed to manage menstrual flow, daily discharge, and postpartum bleeding with dermatological safety. The product type dimension shows sanitary napkins occupying the dominant revenue pool due to entrenched consumer familiarity, while menstrual cups represent the fastest-growing category driven by sustainability preferences and total-cost-of-ownership advantages. Within distribution channels, e-commerce is displacing traditional pharmacy-led purchase patterns as direct-to-consumer platforms enable subscription models and privacy-assured delivery.
Regulatory Framework and Outlook
BIS mandates absorbent product standards under IS 5405, while CDSCO oversees medical-grade claims for postpartum and incontinence segments, and the PLI scheme incentivizes domestic manufacturing scale-up. This regulatory triad elevates compliance costs for new entrants while rewarding established players with certified supply chains. Stakeholders must monitor how evolving FSSAI-adjacent labeling norms and state-level menstrual health programs reshape procurement specifications and subsidy-driven volume flows.
Market Dynamics
PLI scheme incentives are accelerating domestic manufacturing scale-up while BIS certification mandates compress the supplier base, creating a bifurcation between certified large-scale producers and informal regional assemblers.
Growth Catalysts
- Workforce feminization:Rising female labor force participation in Maharashtra and Karnataka expands the addressable base for workplace-accessible hygiene solutions.
- IS 5405 standardization:BIS-mandated absorbent product benchmarks elevate quality floors and disqualify substandard imports from neighboring trade zones.
- Superabsorbent polymer localization:Domestic polymer synthesis capabilities reduce import dependency for core raw materials.
Market Restraints
- Petrochemical input volatility:Polyethylene and polypropylene price swings compress margin buffers for mid-tier manufacturers.
- CDSCO medical-grade pathway:Extended clinical validation timelines for postpartum and incontinence claims delay segment entry.
- Cloth-based substitution:Traditional reusable alternatives retain preference in rural Uttar Pradesh and Bihar due to total-cost perception.
Strategic Opportunities
- Tier-2/Tier-3 penetration:Underdeveloped retail infrastructure in Madhya Pradesh and Rajasthan creates first-mover whitespace for organized distribution.
- Direct-to-consumer subscription:Privacy-assured e-commerce platforms enable recurring revenue capture among urban working professionals.
- PLI capacity expansion:Government production-linked incentives reward capital investment in domestic absorbent material fabrication.
Industry Challenges
- Polymer science talent scarcity:Limited domestic expertise in SAP formulation engineering constrains R&D velocity.
- BIS certification backlog:Testing laboratory capacity shortages extend product approval timelines by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Feminine Hygiene Market |
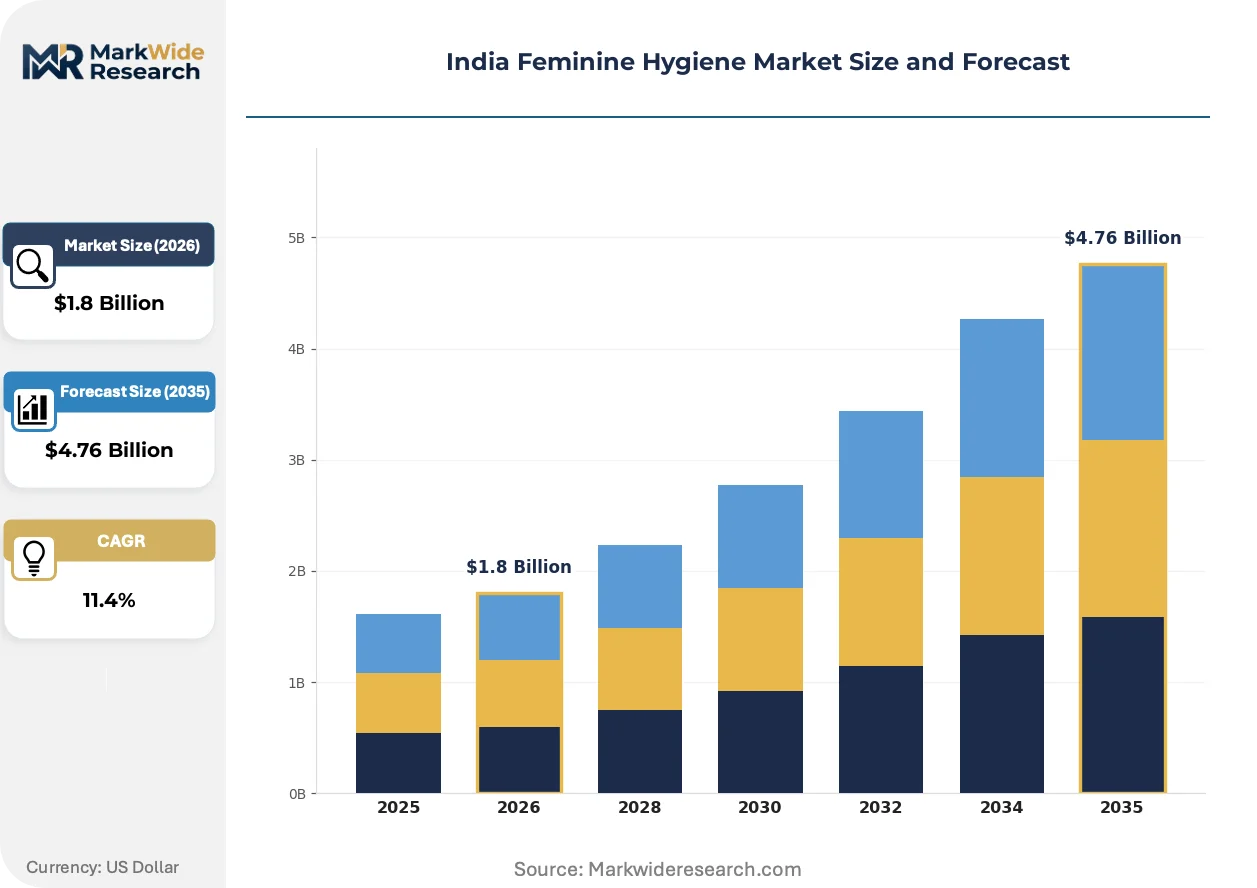
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sanitary Napkins, Tampons, Menstrual Cups, Panty Liners Application: Menstrual Hygiene, Daily Use, Postpartum Care, Urinary Incontinence Distribution Channel: Supermarkets, Pharmacies, E-commerce, Convenience Stores Customer Type: Teenagers, Young Adults, Working Professionals, Homemakers |
| Companies Covered | Unicharm India Pvt Ltd, Emami Ltd, Procter & Gamble Hygiene and Health Care Ltd, Pee Safe, Sirona Hygiene, Kimberly-Clark Lever Ltd, Soothe Healthcare Pvt Ltd, Carmesi, Johnson & Johnson (India) Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Feminine Hygiene Market Shifts & Advancements
Material science advances and channel restructuring are compressing traditional value chains while regulatory tightening separates compliant from non-compliant supply sources.
Biodegradable surface layers derived from bamboo fiber and cornstarch polymers are displacing synthetic top-sheet dominance in premium sanitary napkins. Urban millennials in Bangalore and Mumbai are adopting these alternatives at double-digit rates annually. This shift is displacing petroleum-based nonwoven suppliers from Tier-1 procurement rosters.
BIS is tightening IS 5405 enforcement through expanded market surveillance and random batch testing at retail endpoints. Manufacturers must now maintain batch-level traceability documentation or face distribution bans. Maharashtra-based producers are responding by investing in captive testing laboratories to accelerate compliance verification.
Subscription-based replenishment models are capturing menstrual product purchasing from pharmacy-led discrete transactions. Direct-to-consumer platforms enable cycle-tracking integration and automated delivery scheduling. This pattern is most visible among IT sector employees in Hyderabad and Pune where workplace privacy concerns drive digital preference.
India Feminine Hygiene Market Segmentation
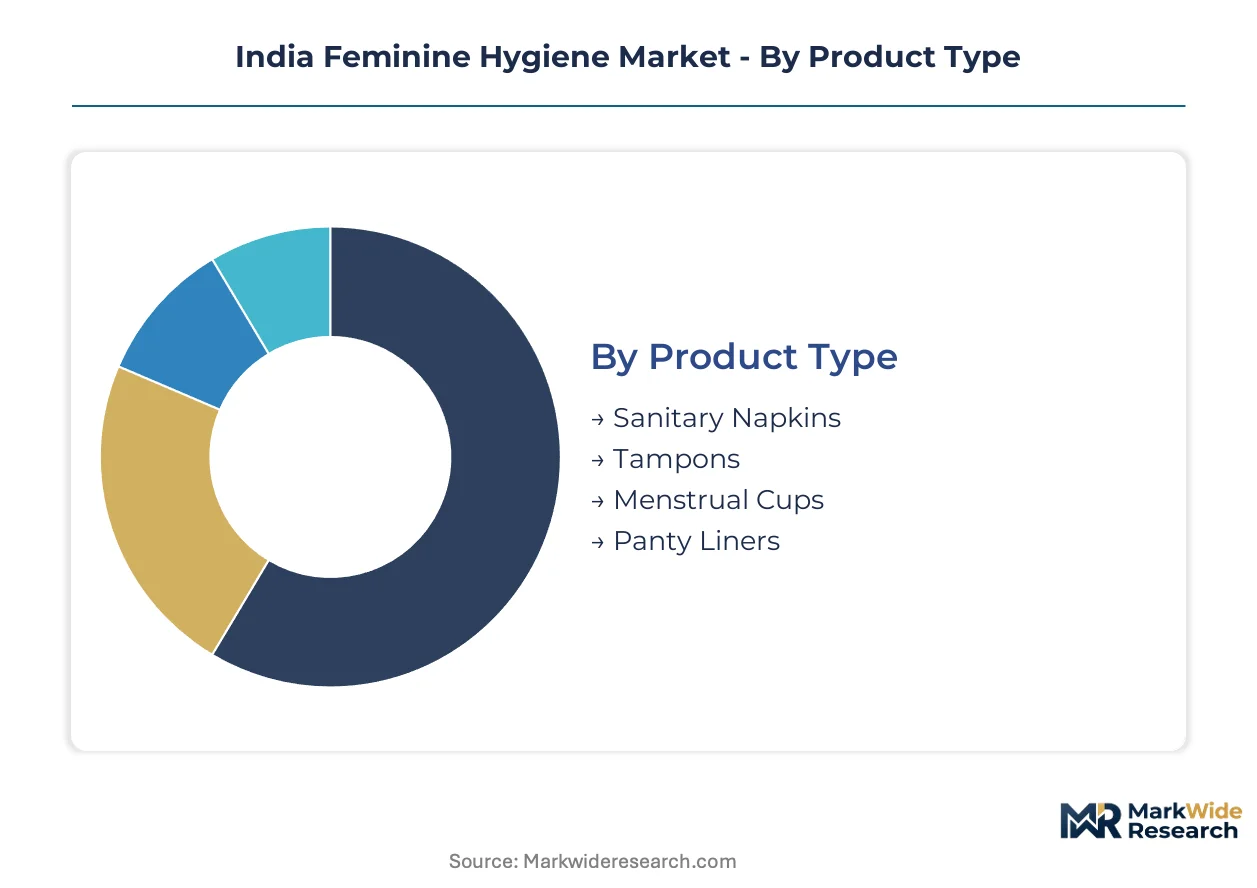
Segmentation in India's feminine hygiene sector reveals how regulatory pressure, channel migration, and demographic shifts are fragmenting demand across distinct product-user-channel combinations. Understanding these divides enables targeted positioning against BIS compliance costs and regional purchasing power variations.
Product Type:
Domestic manufacturing under the PLI scheme favors absorbent products with localized polymer supply chains, while import-dependent categories face margin compression from DGFT tariff adjustments.
- Sanitary Napkins:Multi-layer absorbent pads deploy superabsorbent polymer cores with breathable polyethylene back sheets engineered for 4-8 hour protection. Demand concentrates in Maharashtra and Karnataka where urban retail density supports premium SKU uptake, though BIS IS 5405 testing requirements now disqualify unorganized assemblers from formal distribution.
- Menstrual Cups:Medical-grade silicone or thermoplastic elastomer cups offer 5-10 year reusability with total-cost-of-ownership advantages over disposables. Adoption accelerates among sustainability-conscious consumers in Bangalore and Hyderabad, where digital education campaigns reduce usage-learning barriers.
- Tampons:Rayon or cotton compressed cylinders with applicator or digital insertion formats remain limited by cultural familiarity gaps and higher unit economics relative to napkins.
- Panty Liners:Thin non-absorbent or light-absorbent daily-use products target discharge management and backup protection, gaining traction in white-collar workplace settings across Pune and Chennai.
Sanitary napkins command the established base. The steepest expansion runs through menstrual cups.
Application:
Cost tier differentiation separates subsidized procurement programs from out-of-pocket premium purchases, with CDSCO medical-grade pathways adding compliance overhead to clinical-adjacent segments.
- Menstrual Hygiene:Core category addressing cyclic flow management through absorbent or collection-based technologies. Volume concentrates in government school distribution programs and ASHA worker outreach in rural Uttar Pradesh and Bihar, where price sensitivity sustains basic napkin demand.
- Daily Use:Non-menstrual discharge management and freshness-oriented consumption patterns. Urban working professionals in Mumbai and Delhi NCR drive premium panty liner adoption through pharmacy and e-commerce channels.
- Postpartum Care:High-absorbency maternity pads and specialized underpads for lochia management. CDSCO oversight of medical-grade claims extends validation timelines, limiting domestic manufacturer participation relative to multinational suppliers.
- Urinary Incontinence:Adult absorbent briefs and pads targeting stress or urge incontinence, predominantly among perimenopausal demographics. Market development lags due to stigma barriers and limited urology clinic distribution in Tier-2 cities.
Menstrual hygiene anchors volume procurement. Postpartum care climbs the fastest as hospital channel formalization expands.
Distribution Channel:
Channel restructuring reflects privacy preferences and subscription economics, with e-commerce penetration varying sharply by city tier and female workforce density.
- E-commerce:Direct-to-consumer platforms and marketplace aggregators enable cycle-tracked subscription replenishment with discreet packaging. IT sector clusters in Hyderabad and Pune exhibit highest adoption rates, where workplace privacy concerns override pharmacy convenience.
- Pharmacies:Traditional dominant channel leveraging pharmacist recommendation and immediate availability. Retains preference among first-time buyers and rural consumers in Madhya Pradesh and Rajasthan with limited digital access.
- Supermarkets:Modern trade formats with shelf-space competition driving private-label expansion and promotional bundling. Concentrated in Tier-1 cities where organized retail footprint supports category management investment.
- Convenience Stores:Small-format neighborhood retailers offering emergency purchase accessibility. Emerging as last-mile touchpoints in dense urban wards and transit hubs.
Pharmacies retain the volume base. E-commerce gains share fastest among urban professionals.
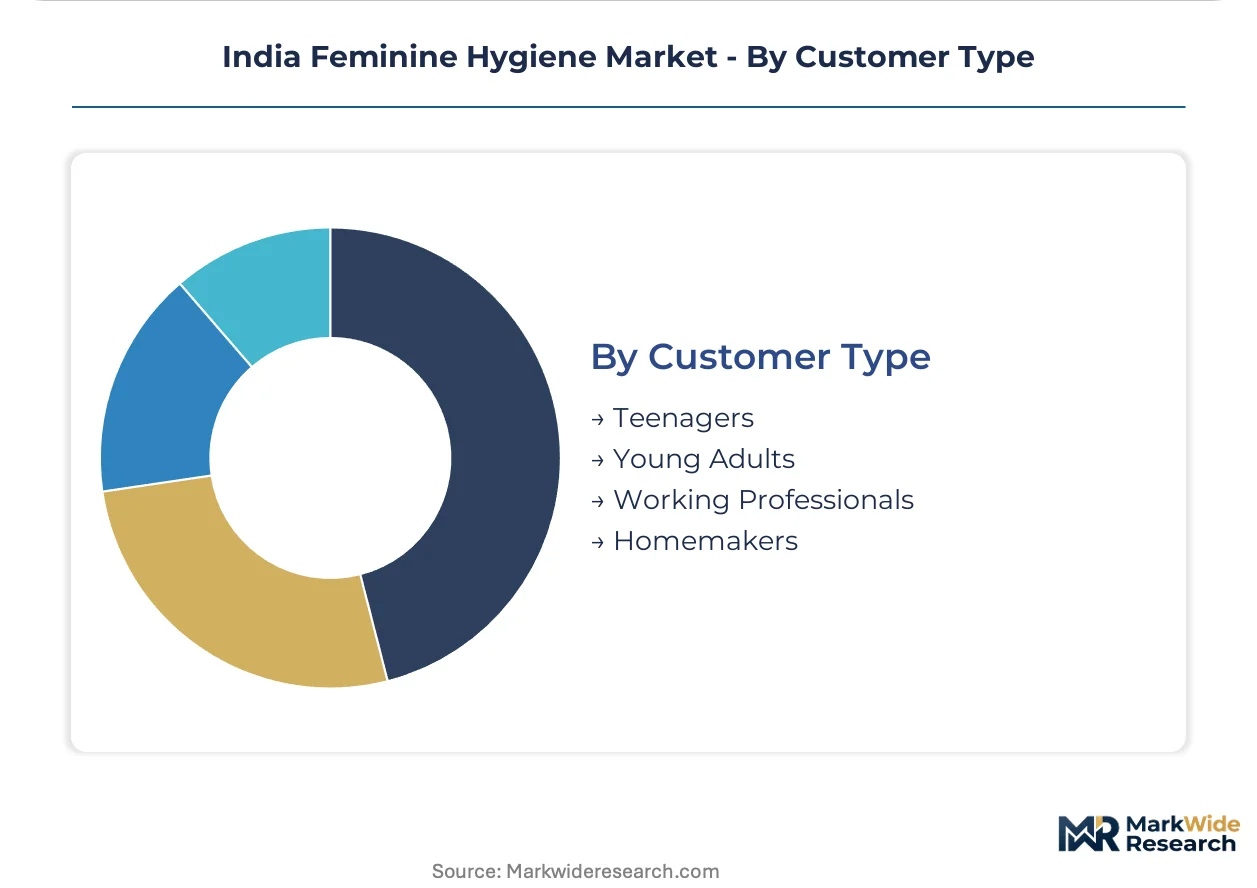
Customer Type:
Life-stage segmentation aligns product format preferences with disposable income trajectories and workplace participation patterns across Indian states.
- Working Professionals:Salaried women in formal employment seeking workplace-appropriate, discreet, and convenient solutions. Concentrated in Karnataka and Maharashtra IT and services sectors, this segment exhibits highest willingness-to-pay for premium and subscription formats.
- Young Adults:College-educated women aged 18-25 establishing independent purchase habits and brand loyalties. Digital-native behavior drives e-commerce preference and social media-influenced trial of sustainable alternatives.
- Teenagers:Menarche-adjacent consumers relying on parental procurement or school-based distribution. Government scheme dependence creates price-anchor effects that persist into adulthood.
- Homemakers:Non-employed women with household budget influence, often prioritizing value formats and bulk purchasing. Traditional channel loyalty and established brand relationships characterize this segment.
Homemakers represent the volume foundation. Working professionals expand most quickly as female labor force participation rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Indian states, with rural Bihar and Uttar Pradesh sustaining cloth-based alternatives while Maharashtra and Karnataka absorb premium SKU markups through formal employment income.
Maharashtra
Mumbai and Pune IT corridors drive subscription-format demand among working professionals. The state's ASHA worker network distributes subsidized napkins under national health missions. Thane district hosts multiple BIS-certified manufacturing facilities serving western India.
Karnataka
Bangalore's services sector feminization creates concentrated demand for workplace-discreet products. State-level menstrual health programs augment central scheme coverage. Mysuru and Hubli-Dharwad clusters support absorbent material suppliers to certified producers.
Tamil Nadu
Chennai's manufacturing base sustains steady institutional procurement for factory-floor female workers. Tamil Nadu's medical device regulatory familiarity aids CDSCO-aligned postpartum product development. Coimbatore's textile engineering heritage feeds nonwoven material innovation.
Gujarat
Surat and Ahmedabad petrochemical corridors enable localized polyethylene and polypropylene supply for back-sheet production. PLI scheme beneficiaries cluster in Vadodara's industrial zone. Gandhinagar's policy proximity accelerates incentive disbursement for absorbent product lines.
Delhi-NCR
Corporate headquarters concentration drives premium brand marketing spend and DTC platform development. Noida's logistics infrastructure supports e-commerce fulfillment for northern states. Gurugram's retail density hosts modern trade format expansion for panty liner categories.
India Feminine Hygiene Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational-backed entities commanding Tier-1 shelf space while domestic-funded players pursue regional whitespace. The structure rewards certified scale: BIS compliance costs filter informal assemblers, concentrating formal distribution among laboratory-equipped producers. Two archetypes dominate—global R&D-leveraged premium positioners and digital-native direct-to-consumer specialists. Competitive moves center on PLI-linked capacity expansion and subscription platform buildout.
Within the multinational tier, Procter & Gamble Hygiene and Health Care Ltd and Kimberly-Clark Lever Ltd represent capital-intensive premium positioning. Among domestic specialists, Sirona Hygiene and Emami Ltd occupy distinct vectors—digital-first distribution versus Ayurveda-formulation mass-market anchoring. Unicharm India Pvt Ltd exemplifies Asia-Pacific regional player adaptation to Indian certification requirements.
| Leading Market Players |
|---|
| Unicharm India Pvt Ltd |
| Emami Ltd |
| Procter & Gamble Hygiene and Health Care Ltd |
| Pee Safe |
| Sirona Hygiene |
| Kimberly-Clark Lever Ltd |
| Soothe Healthcare Pvt Ltd |
| Carmesi |
| Johnson & Johnson (India) Ltd |
| Others |
Supply & Pricing Matrix
Domestic superabsorbent polymer synthesis replacing imported petroleum-based feedstocks is redrawing procurement geographies across Maharashtra and Gujarat while compressing landed-cost premiums for Tier-1 manufacturers. This input substitution simultaneously elevates BIS-certified producers with captive polymer capabilities and erodes margin buffers for import-dependent assemblers facing DGFT tariff adjustments.
Pricing Analysis
Subscription-based replenishment revenue sustains lifetime value capture among IT sector professionals in Hyderabad and Pune. Three-tier pricing structure across premium, standard, and economy levels stratifies by BIS certification grade and SAP core quality, with CDSCO medical-grade claims commanding additional validation premiums. Cost compression in economy tiers intensifies as unorganized assemblers lose formal distribution access under IS 5405 enforcement. Rural procurement programs in Uttar Pradesh and Bihar exhibit highest price sensitivity, while Karnataka's working professionals absorb premium markups for biodegradable surface-layer SKUs.
Supply Chain Analysis
Reliance Industries' Jamnagar petrochemical complex functions as a chokepoint for polyethylene and polypropylene back-sheet supply to western Indian manufacturers. Raw material sourcing draws from Gujarat's polymer corridors, Tamil Nadu's nonwoven textile clusters, and Karnataka's absorbent material engineering hubs. Single-source vulnerability concentrates in SAP precursor imports from China and South Korea. Distribution runs through Maharashtra's ASHA worker networks for subsidized volume, e-commerce fulfillment centers for subscription tiers, and pharmacy-led last-mile for emergency replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against menstrual cup substitution accelerating among Bangalore's sustainability-conscious millennials, where total-cost-of-ownership advantages threaten sanitary napkin volume retention.
For Market Incumbents: Fortify BIS certification moats by investing in captive testing laboratories to compress IS 5405 approval timelines and accelerate product iteration velocity against CDSCO-aligned entrants. Deepen backward integration into SAP synthesis capabilities to offset petrochemical input volatility and secure PLI scheme incentive capture. For New Entrants and Emerging Players: Differentiate on Ayurveda-inspired formulation positioning targeting price-sensitive homemakers in Madhya Pradesh and Rajasthan where organized retail penetration remains underdeveloped. Prioritize direct-to-consumer subscription buildout for urban working professionals, leveraging cycle-tracking integration to capture recurring revenue from pharmacy-led incumbents. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors laboratory-equipped domestic manufacturers with certified supply chains and established ASHA worker distribution networks. Long-term viability hinges on PLI-linked capacity scale and e-commerce subscription platform ownership. Monitor BIS enforcement intensity as the inflection signal separating compliant scale players from disqualified informal assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | Captive testing laboratories in Maharashtra accelerate IS 5405 compliance and disqualify unorganized competitors from formal retail. |
| Direct-to-Consumer Launch | Privacy-assured subscription platforms capture IT sector professionals in Pune and Hyderabad from pharmacy-led incumbents. |
| Backward Integration into SAP | In-house polymer synthesis reduces import dependency and secures PLI scheme production-linked incentives. |
| Sustainability Repositioning | Bamboo fiber and cornstarch surface layers target Bangalore millennials displacing petroleum-based nonwoven suppliers. |
| Distribution Channel Expansion | ASHA worker network penetration in rural Uttar Pradesh and Bihar captures government scheme procurement volume. |
Research Methodology
Cross-validation between primary interviews with BIS certification officers, CDSCO regulatory leads, absorbent product plant managers, and e-commerce category heads anchors the qualitative findings against secondary validation. Bottom-up triangulation incorporates customs records for SAP precursor imports, DGFT tariff schedules, state-level menstrual health program procurement databases, and PLI scheme beneficiary disclosures alongside top-down macroeconomic modeling.
Sensitivity analysis across product type, application, distribution channel, and customer type dimensions shapes the analytical framework over the projection horizon. CAGRs derive from segment-level volume builds calibrated to female labor force participation trajectories, BIS enforcement intensity scenarios, and e-commerce penetration curves specific to IT corridor cities. Forecast inputs include ASHA worker distribution coverage expansion rates and biodegradable material cost-parity timelines against synthetic alternatives.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme funding continuity, BIS laboratory capacity expansion, or stable petrochemical feedstock pricing would require recalibration. Practitioners should keep alternative scenarios live as CDSCO medical-grade pathway timelines and state-level subsidy program allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Enema Bags Market
Medical Supplies
Fibrin Sealants Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Trach Care Trays Market
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Hospital Gowns Market
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
Global Cleanroom Disposable Gloves Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
IV Infusion Gravity Bags Market
Medical Supplies
Menthol Patches Market