
 Dispersant Market | 2026-2036
Dispersant Market Size, Share, and Industry Trends Forecast 2026-2036
Dispersant Market Analysis
ISO 14001 environmental management certification is bifurcating the competitive landscape into qualified suppliers and excluded challengers. BASF SE leverages its integrated petrochemical backbone to sustain feedstock cost advantages across polymeric dispersant grades. Evonik Industries AG anchors its position through specialized organosilane dispersant technology for electronics applications. Dow Inc. competes on manufacturing scale, operating multiple regional production hubs that shorten lead times for coatings customers.
Dispersants are surface-active agents that reduce interfacial tension between immiscible phases, typically functioning through steric stabilization or electrostatic repulsion with molecular weights ranging from hundreds to millions of Daltons. Their primary commercial purpose centers on maintaining uniform particle distribution in suspensions, preventing agglomeration that would degrade product performance in formulated systems. Lubricant dispersants occupy mature volume positions tied to combustion engine maintenance cycles, while coatings applications capture expanding margin pools as waterborne formulations displace solvent-borne alternatives. High-shear mixing technology leads industrial adoption for nanoparticle dispersion, whereas ultrasonic methods penetrate pharmaceutical and electronics sectors demanding minimal thermal degradation.
EPA regulations under the Clean Air Act constrain VOC content in architectural and industrial coatings, directly steering reformulation investments toward compliant dispersant systems. REACH registration requirements in Europe enforce comprehensive toxicological dossiers, raising barriers for entrants lacking dedicated regulatory affairs capabilities. China's MEE enforces stricter effluent standards for chemical manufacturing, pressuring domestic dispersant producers toward closed-loop process redesign. Stakeholders must monitor evolving substance restriction lists across jurisdictions to preempt portfolio obsolescence and secure uninterrupted market access.
Market Dynamics
Waterborne formulation mandates across automotive and architectural coatings are forcing solvent-borne dispersant suppliers into rapid product-line reconfiguration, while battery-grade dispersant specifications in China are creating dual-speed demand patterns that fragment procurement strategies.
Growth Catalysts
- EPA VOC limits:Architectural coatings manufacturers in the United States are reformulating solvent-borne systems to comply with tightened Clean Air Act standards, pulling demand for compliant waterborne dispersant chemistries.
- Lithium-ion electrode slurries:Battery producers in China require high-performance polymeric dispersants to achieve uniform nanoparticle distribution in cathode and anode manufacturing.
- High-shear mixing:Industrial coatings facilities are retrofitting dispersion equipment to handle nanoscale pigment loading, expanding addressable volume for advanced dispersant grades.
Market Restraints
- Ethylene oxide feedstock volatility:Polyether backbone production for non-ionic dispersants faces input cost swings tied to naphtha cracking economics and regional energy pricing.
- REACH dossier requirements:European chemical registration mandates comprehensive toxicological data packages that consume 18-24 month compliance timelines and six-figure regulatory investment.
- Silica nanoparticle substitutes:Inorganic dispersant alternatives are capturing share in low-performance coatings segments where cost sensitivity outweighs formulation flexibility.
Strategic Opportunities
- India automotive OEM:Domestic vehicle production growth and impending BSVI emission-linked coating specifications are opening demand for compliant waterborne refinish systems.
- Organosilane-electronics convergence:Semiconductor packaging and display manufacturing require dispersants compatible with ultra-low contamination thresholds and high-temperature processing.
- Japan METI battery subsidy:Domestic cell manufacturing expansion incentives are pulling localized dispersant supply chain development for electrode slurry producers.
Industry Challenges
- Colloid chemistry specialization:Formulation laboratories face acute shortages of scientists trained in zeta potential optimization and steric stabilization mechanisms for nanoscale systems.
- ISO 14001 certification timelines:Environmental management system audits require 12-18 month implementation cycles that delay supplier qualification for automotive OEM tender participation.
- Legacy equipment retrofit costs:Coatings manufacturers must reconfigure high-speed dispersers and bead mills to handle elevated viscosities of waterborne formulations without capital write-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispersant Market |
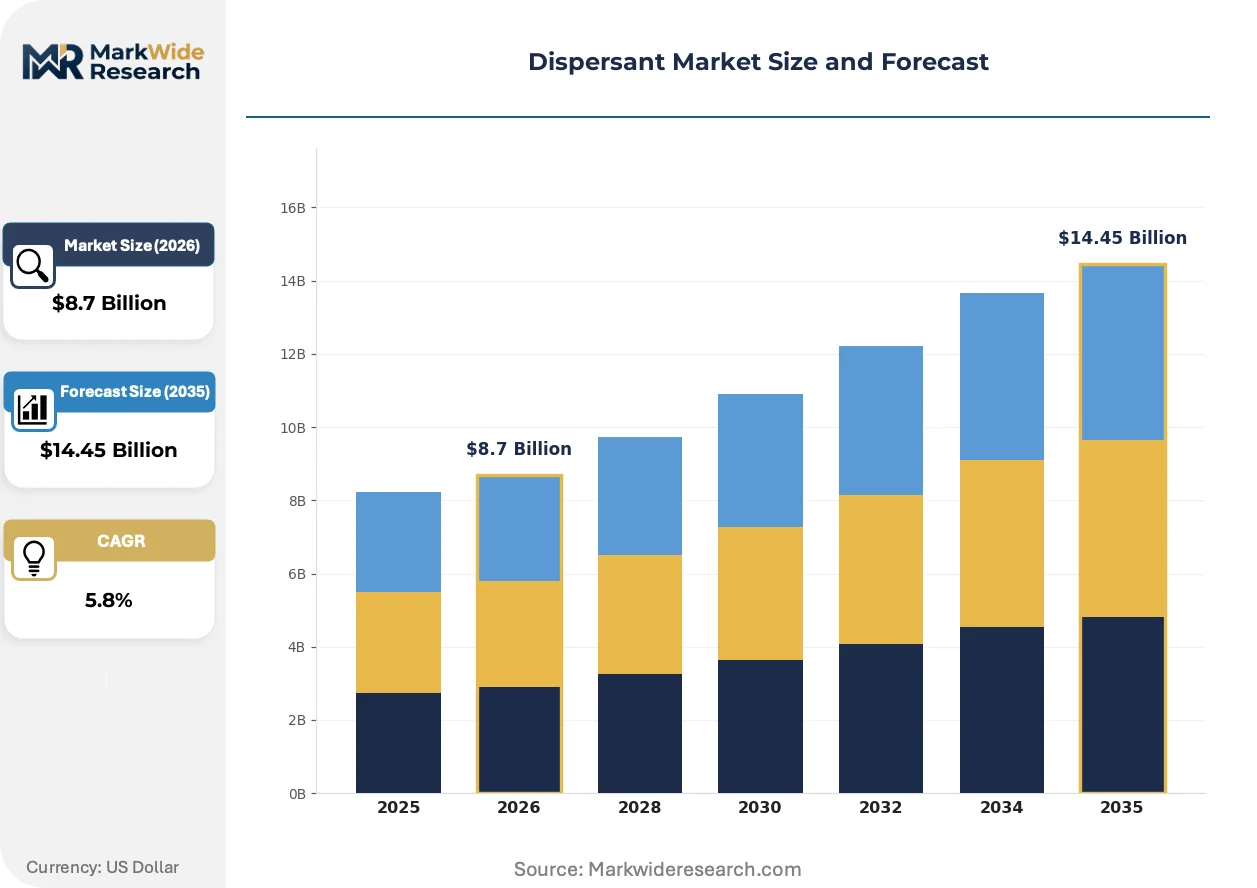
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lubricants, Coatings, Inks, Additives End Use Industry: Paints, Pharmaceuticals, Agriculture, Construction Technology: Ultrasonic Dispersion, Mechanical Agitation, Chemical Dispersion, High-Shear Mixing Form: Liquid, Powder, Concentrate, Gel |
| Companies Covered | Solvay SA, Arkema Group, BASF SE, Altana AG, The Lubrizol Corporation, Evonik Industries AG, Dow Inc., Nouryon, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispersant Market Emerging Trajectories
Polymeric dispersant architecture is splitting into commodity waterborne grades and precision-designed specialty molecules, while regulatory frameworks harden technical barriers and procurement patterns consolidate around qualified supplier pools.
Block copolymer dispersants with tailored hydrophilic-lipophilic balance are bifurcating the competitive landscape between integrated petrochemical producers and specialized fine chemical houses. Automotive OEM clearcoat formulators in Germany and Japan are specifying these molecules for metallic flake orientation control. The technology is bifurcating margin pools toward performance-validated grades while compressing commodity polyacrylate pricing.
China's MEE effluent standards for chemical manufacturing are forcing dispersant producers toward closed-loop water recycling and zero-liquid-discharge process redesign. Domestic facilities face capital intensity for wastewater treatment upgrades that foreign joint-venture plants absorbed earlier. Battery-grade dispersant lines in Jiangsu and Guangdong provinces are most affected, with producers accelerating membrane filtration and solvent recovery investments.
Automotive refinish buyers are consolidating supplier rosters from six-to-eight active vendors toward three-to-four qualified partners with full waterborne portfolios and documented EPA compliance histories. Distributor networks in the United States are losing technical specification influence as OEMs direct-source through approved manufacturer lists. This concentration is most visible in collision repair chains and fleet maintenance operations where liability exposure drives preference for certified formulation systems.
Dispersant Market Segmentation
Dispersant selection hinges on particle size targets, shear tolerance, and regulatory compliance thresholds that vary sharply across end-use specifications. Formulators segment procurement by performance tier rather than chemistry alone, creating distinct margin pools that reward specialization over commodity scale.
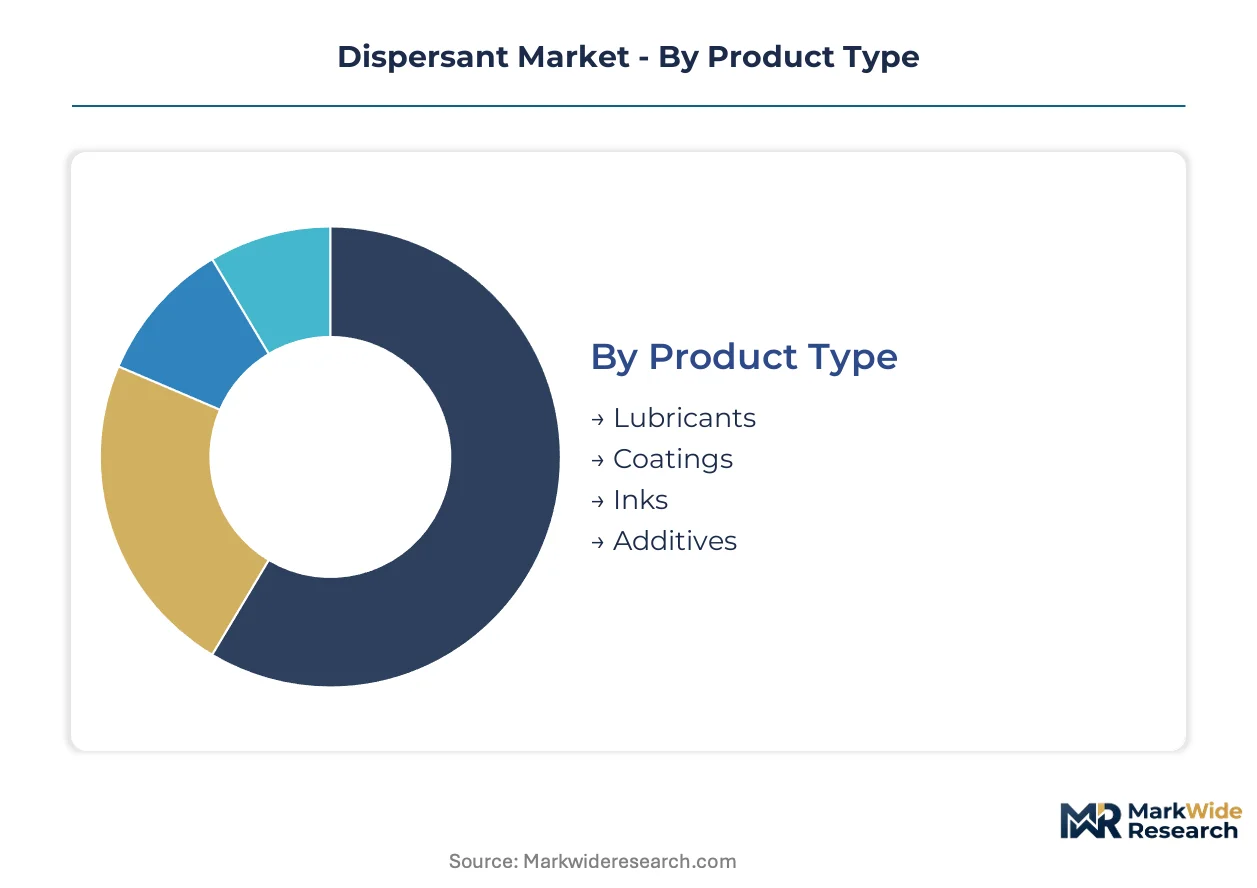
Product Type:
Coatings-grade dispersants face the most acute substitution pressure from silica nanoparticle alternatives in architectural segments, while lubricant and ink formulations maintain stickier demand due to performance-validated OEM specifications.
- Lubricants:Ashless polymeric dispersants suspend soot and oxidation byproducts in engine oils through polar headgroup anchoring to particulate surfaces. Demand concentrates in North American and European heavy-duty diesel maintenance cycles tied to extended drain intervals mandated by API CK-4 and FA-4 categories.
- Coatings:Polyacrylate and polyurethane dispersants stabilize titanium dioxide and organic pigments in waterborne architectural and automotive formulations. China and Germany drive specification intensity as MEE effluent standards and REACH dossier requirements force reformulation toward high-performance grades with documented environmental compliance.
- Inks:Solvent-borne flexographic and gravure systems retain volume in emerging market packaging, though waterborne conversions accelerate in EU and US food-contact applications.
- Additives:Masterbatch and plastic compound dispersants serve polymer processors requiring uniform filler distribution in high-temperature extrusion.
Lubricants anchors the volume base while Coatings gains share at the steepest rate.
End Use Industry:
Margin concentration follows formulation complexity, with pharmaceutical and agricultural applications commanding premium pricing over construction bulk demand.
- Paints:Decorative and industrial coatings manufacturers specify dispersants by VOC compliance tier, with EPA architectural standards and China GB 18582 limits creating dual certification requirements for multinational suppliers.
- Pharmaceuticals:Active pharmaceutical ingredient micronization and inhalable formulation development require ultrasonic-compatible dispersants with validated endotoxin and bioburden documentation. FDA process analytical technology initiatives are pulling demand toward real-time particle size monitoring integration.
- Agriculture:Suspension concentrate and water-dispersible granule formulations for crop protection chemicals rely on lignosulfonate and naphthalene sulfonate dispersants where cost sensitivity limits polymeric alternatives.
- Construction:Cement admixture and waterproofing membrane applications consume commodity-grade dispersants in high volumes with minimal specification differentiation.
Construction anchors the volume base while Pharmaceuticals climbs the fastest.
Technology:
Capital intensity separates industrial-scale mechanical systems from precision pharmaceutical and electronics applications where thermal degradation constraints dominate equipment selection.
- High-Shear Mixing:Rotor-stator and bead mill systems achieve nanoparticle deagglomeration in coatings and ink production through intense localized energy input. Automotive OEM clearcoat facilities in Germany and Japan specify this technology for metallic flake orientation control in waterborne basecoats.
- Ultrasonic Dispersion:Piezoelectric probe systems generate cavitation for pharmaceutical API processing and semiconductor slurry preparation where temperature excursions must stay below 40°C. Battery electrode manufacturing in China and Japan is pulling demand for continuous-flow ultrasonic configurations.
- Mechanical Agitation:High-speed dispersers and paddle mixers serve low-shear requirements in construction and agriculture bulk formulation.
- Chemical Dispersion:In-situ surface modification and controlled precipitation methods produce dispersant-coated nanoparticles for specialized electronics and catalyst applications.
Mechanical Agitation anchors the volume base while Ultrasonic Dispersion expands most quickly.
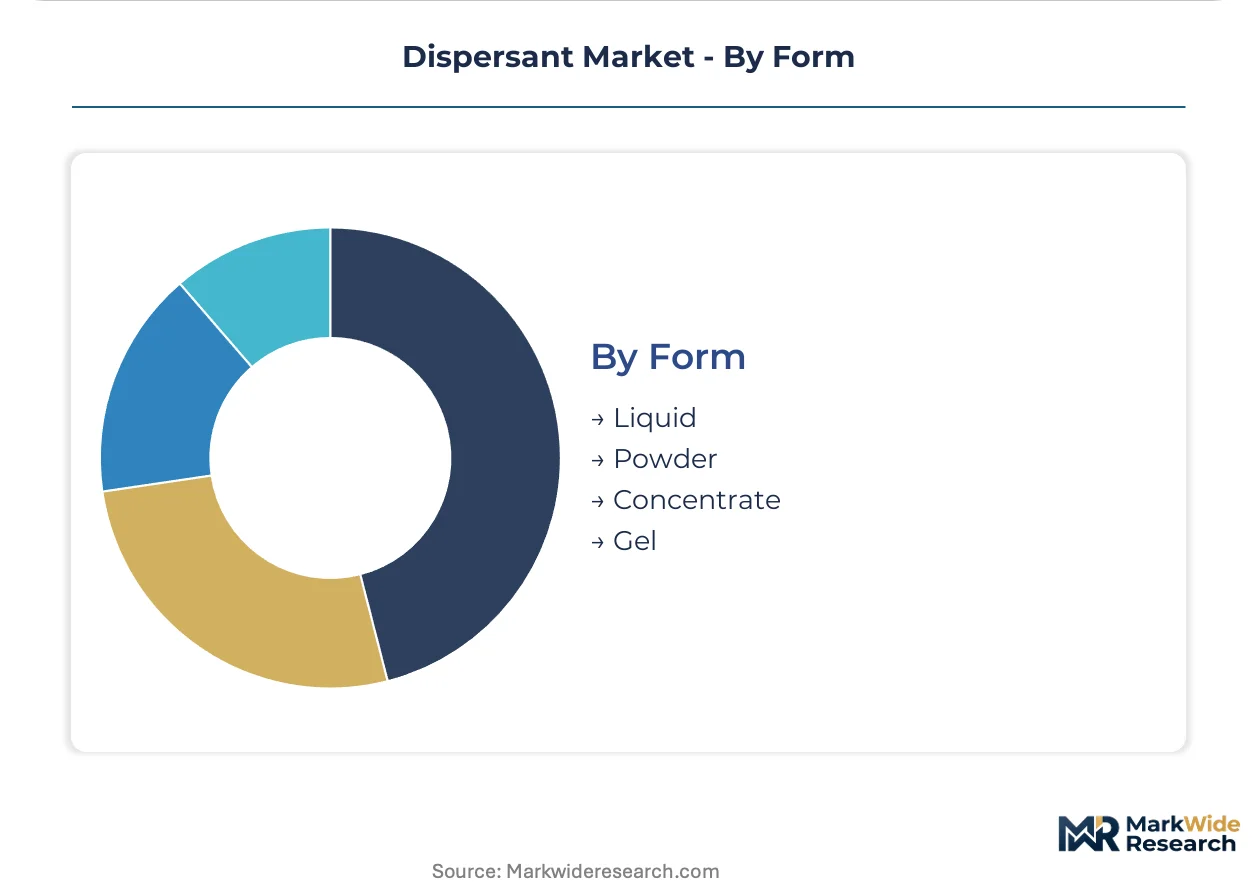
Form:
Supply chain economics favor liquid and concentrate formats for automated dosing systems, though powder forms retain share in remote construction and agriculture markets where water weight drives freight costs.
- Liquid:Pumpable aqueous and solvent-borne solutions enable continuous manufacturing integration with automated in-line dosing and reduced dust exposure. Waterborne coatings plants in the United States and EU prefer liquid dispersants for VOC compliance documentation.
- Concentrate:Reduced-water formulations lower freight costs and packaging waste for high-volume coatings and construction chemical producers with on-site dilution capability.
- Powder:Spray-dried and extruded granule forms serve agricultural formulation and remote construction sites lacking liquid handling infrastructure.
- Gel:Thixotropic semi-solid systems prevent settling in specialty ink and adhesive applications requiring precise rheology control.
Liquid anchors the volume base while Concentrate gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA VOC limits under the Clean Air Act are restructuring procurement patterns for waterborne coatings in the United States. China's MEE effluent standards are accelerating capital deployment for zero-liquid-discharge process redesign among battery-grade dispersant producers. Japan's METI battery subsidies are pulling localized supply chain development for electrode slurry manufacturing.
United States
Automotive OEM refinishing and architectural coatings manufacturers are reformulating solvent-borne systems to comply with tightened EPA Clean Air Act standards. The EPA's architectural coatings rulemaking pulls demand toward compliant waterborne dispersant chemistries. Collision repair chains in Michigan and Ohio direct-source through approved manufacturer lists, consolidating supplier rosters from six-to-eight vendors toward three-to-four qualified partners.
Germany
Automotive clearcoat formulators specify block copolymer dispersants for metallic flake orientation control in waterborne basecoats. REACH registration requirements enforce comprehensive toxicological dossiers that raise barriers for entrants lacking dedicated regulatory affairs capabilities. Industrial coatings facilities in Baden-Württemberg retrofit high-shear dispersion equipment to handle nanoscale pigment loading.
China
Battery producers in Jiangsu and Guangdong provinces require high-performance polymeric dispersants for uniform nanoparticle distribution in cathode and anode manufacturing. MEE effluent standards pressure domestic producers toward closed-loop water recycling and membrane filtration investments. Domestic vehicle production growth and impending emission-linked coating specifications open demand for compliant waterborne refinish systems in Shanghai and Beijing manufacturing corridors.
Japan
Semiconductor packaging and display manufacturing require dispersants compatible with ultra-low contamination thresholds and high-temperature processing. METI battery subsidy programs pull localized dispersant supply chain development for electrode slurry producers. Continuous-flow ultrasonic configurations penetrate pharmaceutical API processing facilities in the Kansai industrial belt where temperature excursions must stay below 40°C.
Dispersant Market Vendor Landscape
Player mix skews toward integrated petrochemical conglomerates with captive feedstock positions and specialized fine chemical houses with organosilane expertise. The competitive landscape bifurcates between qualified suppliers holding ISO 14001 environmental management certification and excluded challengers facing 12-18 month audit timelines. Two dominant strategic archetypes emerge: backward-integrated producers leveraging naphtha cracking economics and precision-focused specialists serving electronics contamination thresholds. Competitive moves concentrate on portfolio diversification into battery-grade specifications and geographic expansion through regional production hubs that shorten coatings customer lead times.
Within the integrated chemical conglomerate tier, BASF SE and Dow Inc. exemplify scale-driven positioning through multiple regional production footprints and petrochemical backbone integration. Evonik Industries AG occupies a specialist position anchored in organosilane dispersant technology for electronics applications. These three entities represent the competitive spectrum from commodity waterborne grades through precision-designed specialty molecules, with qualification status under EPA and REACH frameworks serving as the primary sorting mechanism for automotive and coatings procurement consolidation.
| Leading Market Players |
|---|
| Solvay SA |
| Arkema Group |
| BASF SE |
| Altana AG |
| The Lubrizol Corporation |
| Evonik Industries AG |
| Dow Inc. |
| Nouryon |
| Clariant AG |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety day lead times for battery-grade polymeric dispersants in Jiangsu province concentrate procurement leverage among qualified suppliers, amplifying pricing power for ISO 14001-certified producers while compressing margins for challengers facing extended audit timelines.
Pricing Analysis
Certification level creates the primary spread between qualified and excluded supplier tiers. Three-tier pricing structure across REACH-registered premium, ISO 14001 standard, and uncertified economy levels stratifies the market. Cost compression in commodity waterborne grades intensifies because silica nanoparticle substitutes capture share in architectural coatings. Construction chemical buyers exhibit highest price sensitivity, while pharmaceutical formulators prioritize validated endotoxin documentation over unit cost.
Supply Chain Analysis
Inventory positions for ethylene oxide derivatives fluctuate with naphtha cracking economics, exposing polyether backbone producers to energy price volatility. Manufacturing concentrates in Germany, China, and the United States, with feedstock supply anchored in regional petrochemical complexes. Naphtha, ethylene oxide, and organosilane precursors constitute critical input dependencies. Single-source vulnerability for high-purity organosilane intermediates threatens electronics-grade dispersant continuity. Distribution runs through approved manufacturer lists direct to automotive OEM collision repair chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against silica nanoparticle substitution in low-performance coatings segments where cost sensitivity outweighs formulation flexibility, preserving margin pools in certified specialty grades.
For Market Incumbents: Secure REACH dossier completion ahead of registration deadlines to maintain European market access against delayed challengers. Deepen backward integration into ethylene oxide supply to insulate polyether production from naphtha volatility. Prioritize battery-grade dispersant capacity expansion in Jiangsu and Guangdong provinces to capture electrode slurry specification intensity.
For New Entrants and Emerging Players: ISO 14001 fast-track certification enables qualification for automotive OEM tender participation within compressed timelines. Penetrate India's domestic vehicle production corridor before BSVI-linked coating specifications consolidate supplier rosters. Lead with organosilane-electronics convergence applications where contamination threshold requirements deter commodity competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized dispersant divisions lacking battery-grade focus. Five-to-ten year viability hinges on waterborne formulation mandate compliance across automotive and architectural end uses. Target fine chemical houses with organosilane expertise and existing electronics customer relationships. Monitor EPA architectural coatings rulemaking acceleration as inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive ethylene oxide supply insulates polyether backbone production from naphtha cracking volatility. |
| Zero-Liquid-Discharge Retrofit | Closed-loop water recycling secures MEE compliance for Jiangsu battery-grade dispersant lines. |
| Organosilane R&D Expansion | Specialized molecules penetrate semiconductor packaging contamination thresholds in Japan and South Korea. |
| REACH Dossier Acceleration | Expedited toxicological data packages preempt registration barriers for European coatings procurement. |
| Regional Production Hub Addition | Localized manufacturing shortens lead times for US automotive OEM refinishing customers. |
Methodological Framework
Cross-validation between primary interviews with plant managers at dispersant production facilities and secondary customs trade data anchors the qualitative findings. Procurement leads at downstream coatings OEMs, distribution channel partners, technical R&D directors, and regulatory affairs specialists provided operational perspective. Bottom-up triangulation against SEC 10-K filings, ACC industry reports, and EPA compliance databases validated volume estimates.
Sensitivity analysis around ethylene oxide feedstock cost assumptions and battery-grade specification adoption rates shapes the analytical framework. Segmentation dimensions include product type, end-use industry, technology platform, and regional production hub. CAGRs derive from slope-log regression across the projection horizon. Modeled inputs incorporate REACH registration timelines and MEE effluent standard implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained waterborne formulation mandate enforcement or stable naphtha cracking economics would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance trajectories and substitute penetration ceilings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Sodium Cocoyl Isethionate Market
Surfactants
Polysorbate 40 Market
Surfactants
Soap Salts Market
Surfactants
Cetyl Chloride Market
Surfactants
Global Sodium Lauryl Sulfate Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Global Saponin Market
Surfactants
Trisiloxane Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Cationic Surfactants Market
Surfactants
Selenium Sulphide Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Lauramide DEA Market