
 Disk Encryption Software Market | 2026-2036
Disk Encryption Software Market Size, Share, and Industry Trends Forecast 2026-2036
Disk Encryption Software Market Analysis
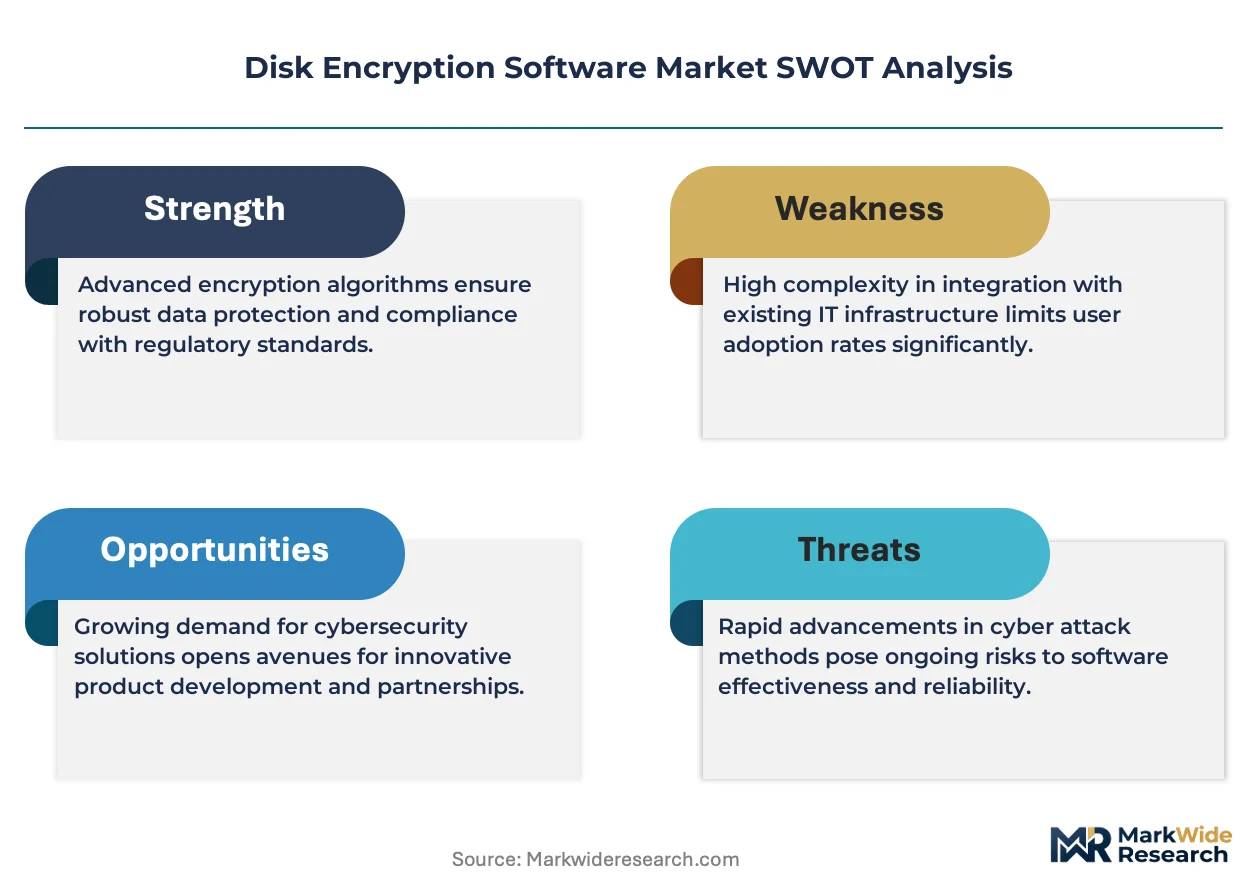
North America is tilting toward cloud-native encryption architectures as enterprises migrate sensitive workloads off legacy data centers. Microsoft Corporation leverages its Azure ecosystem to anchor hybrid deployment pipelines across government and healthcare accounts. IBM Corporation sustains mainframe-grade encryption credibility through specialized hardware security modules that integrate with its software stack. Sophos Limited competes on managed detection and response bundling, wrapping encryption into broader endpoint protection contracts.
Disk encryption software protects stored data by converting plaintext into ciphertext using cryptographic algorithms, rendering information unreadable without authorized decryption keys operating at AES-256 or equivalent strength. The technology serves industries handling regulated personal data, intellectual property, and classified government information where physical device theft or unauthorized access poses existential risk. Full disk encryption dominates enterprise procurement budgets due to baseline compliance requirements, while cloud encryption expands fastest as organizations distribute storage across multi-tenant environments. File-level encryption occupies narrower but higher-margin niches where selective protection of specific documents outweighs whole-volume approaches.
The EU's GDPR and Digital Operational Resilience Act (DORA) impose breach-notification timelines and encryption standards that shape procurement specifications across member states. In the United States, HIPAA and state-level privacy statutes including California's CCPA compel healthcare and consumer-facing sectors to mandate encryption for protected data categories. Stakeholders must monitor evolving quantum-resistant algorithm standards from NIST and their migration timelines for existing encrypted data archives.
Market Dynamics
Quantum-resistant algorithm migration is compressing procurement timelines as enterprises confront cryptographic obsolescence risks in long-term data archives. NIST's post-quantum standardization timeline forces immediate planning for algorithm transitions across hardware and software stacks.
Growth Catalysts
- EU DORA mandates:Critical infrastructure operators in financial services must implement encryption controls by regulatory deadlines, accelerating enterprise-wide deployment decisions.
- Automotive cyber-insurance:German industrial conglomerates face policy requirements mandating full-disk encryption across distributed manufacturing and R&D facilities.
- Cloud workload distribution:Multi-tenant storage architectures are driving demand for encryption that spans hybrid and public cloud environments without performance degradation.
Market Restraints
- Hardware security module costs:Specialized HSM procurement for key management creates capital intensity barriers for mid-market organizations.
- Legacy system integration friction:Mainframe and aging endpoint fleets resist seamless encryption deployment without substantial middleware investment.
- Skills concentration:Cryptographic engineering talent clusters in technology hubs, creating regional deployment bottlenecks for distributed enterprises.
Strategic Opportunities
- Healthcare IoT encryption:Connected medical devices in hospital networks lack standardized protection, creating whitespace for embedded encryption modules.
- Managed detection bundling:Endpoint protection vendors can wrap encryption into broader security service contracts, shifting revenue to recurring models.
- India's data localization:The country's central bank and national regulators are mandating domestic data storage, requiring localized encryption infrastructure.
Industry Challenges
- Key escrow complexity:Balancing employee access recovery against insider threat prevention creates architectural trade-offs that delay deployment decisions.
- Performance overhead management:Full-disk encryption on resource-constrained endpoints requires optimization that stretches internal engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disk Encryption Software Market |
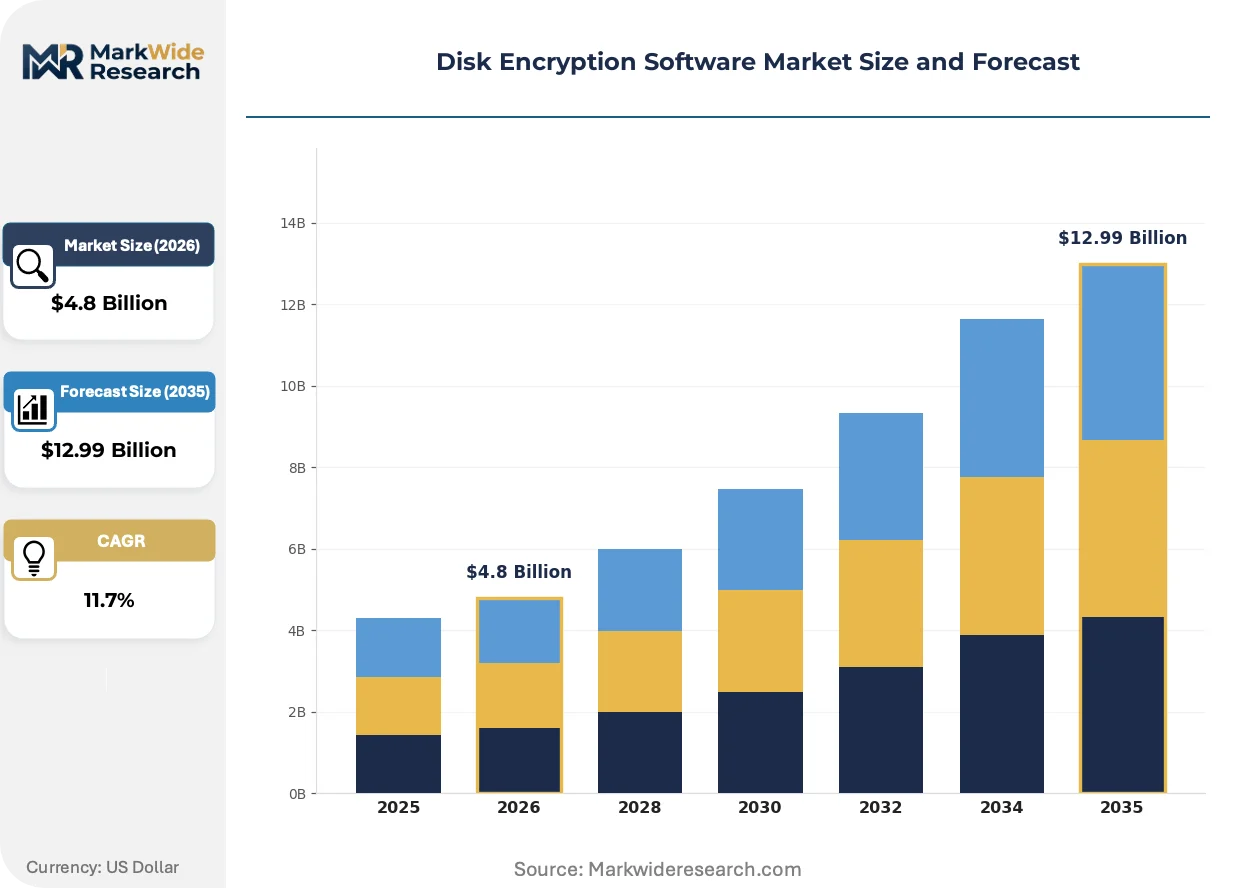
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Disk Encryption, File-Level Encryption, Cloud Encryption, Portable Encryption Technology: Symmetric Encryption, Asymmetric Encryption, Hashing, Tokenization End User: SMBs, Enterprises, Government, Education Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service |
| Companies Covered | Microsoft Corporation, IBM Corporation, Dell Technologies Inc., Thales S.A., Check Point Software Technologies Ltd., Sophos Limited, Trend Micro Incorporated, McAfee LLC, WinMagic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disk Encryption Software Market Emerging Trajectories
Encryption architectures are fragmenting across deployment models as organizations reject one-size-fits-all approaches. Vendors must now support simultaneous on-premise, private cloud, and multi-tenant configurations without operational silos.
Confidential computing is hybridizing hardware-based trusted execution environments with software encryption layers to protect data during active processing. Financial services firms in Frankfurt and Singapore are piloting these integrations for real-time transaction analytics. The approach compresses the traditional boundary between at-rest and in-use protection, collapsing separate procurement categories into unified platforms.
GDPR's breach-notification timelines are forcing encryption to become a default technical safeguard rather than a compensating control. Organizations in France and Spain now specify AES-256 or equivalent strength as non-negotiable in vendor RFPs. Healthcare and consumer-facing sectors face the steepest compliance curves as supervisory authorities impose fines for inadequate cryptographic measures.
Enterprise buyers are consolidating encryption procurement under centralized security operations centers rather than distributed IT departments. Channel partners in Germany and the United States report shorter sales cycles but higher technical qualification thresholds for vendor selection. This concentration favors suppliers offering unified key management across endpoint, server, and cloud workloads.
Disk Encryption Software Market Segmentation
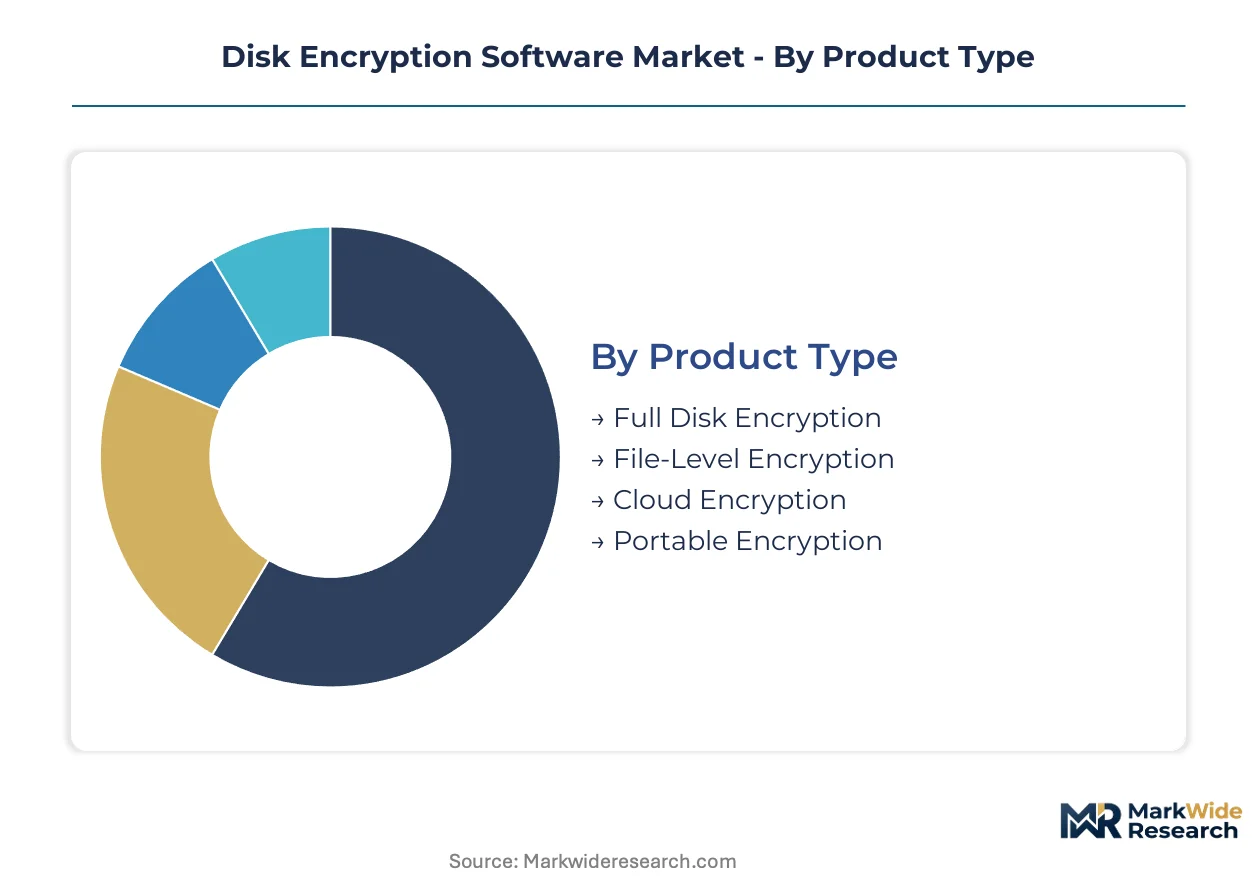
Disk encryption software procurement varies sharply across deployment environments and organizational scale. Buyers prioritize different cryptographic architectures based on regulatory exposure, infrastructure maturity, and data sensitivity classifications.
Product Type:
Application context determines whether organizations protect entire volumes, selective files, or distributed cloud assets.
- Full Disk Encryption:AES-256 algorithms encrypt entire storage volumes at the hardware or operating system layer. Financial services firms in Frankfurt deploy this baseline protection across trader workstations to satisfy DORA mandates and cyber-insurance policy terms.
- Cloud Encryption:Client-side and server-side schemes protect data across multi-tenant storage environments. Healthcare providers migrating patient records to Azure and AWS infrastructure drive concentrated procurement for key management across hybrid boundaries.
- File-Level Encryption:Selective document protection using granular access controls.
- Portable Encryption:Removable media and USB device protection for mobile workforces.
Full disk encryption commands the established base. The steepest expansion runs through cloud encryption.
Technology:
Cost tier and performance requirements shape whether organizations deploy symmetric ciphers, asymmetric key exchange, or alternative data protection schemes.
- Symmetric Encryption:Single-key algorithms like AES deliver computational efficiency for bulk data protection. German automotive manufacturers standardize on AES-256-GCM for manufacturing execution systems where latency constraints rule out heavier alternatives.
- Tokenization:Non-reversible substitution replaces sensitive data elements with surrogate values. Payment processors in Singapore and Frankfurt pilot tokenization for PCI-DSS compliance, eliminating cryptographic key exposure in transaction archives.
- Asymmetric Encryption:Public-private key pairs enabling secure key exchange and digital signatures.
- Hashing:One-way functions for data integrity verification and password storage.
Symmetric encryption retains volume leadership. Tokenization gains share fastest in regulated transaction environments.
End User:
Customer type dictates procurement sophistication, with enterprise and government buyers driving standards adoption.
- Enterprises:Centralized security operations centers mandate unified key management across global endpoint fleets. Fortune 500 technology and pharmaceutical companies consolidate encryption procurement under CISO-directed frameworks with mandatory HSM integration.
- Government:Classified information systems require FIPS 140-2 validated modules and certified algorithm implementations. Federal agencies and defense contractors in the United States specify Common Criteria EAL4+ evaluations for full-disk encryption deployments.
- SMBs:Cost-constrained organizations prioritizing out-of-box deployment simplicity.
- Education:Universities and K-12 districts protecting student records and research intellectual property.
Enterprise accounts anchor revenue concentration. Government verticals follow the steepest compliance-driven expansion curve.
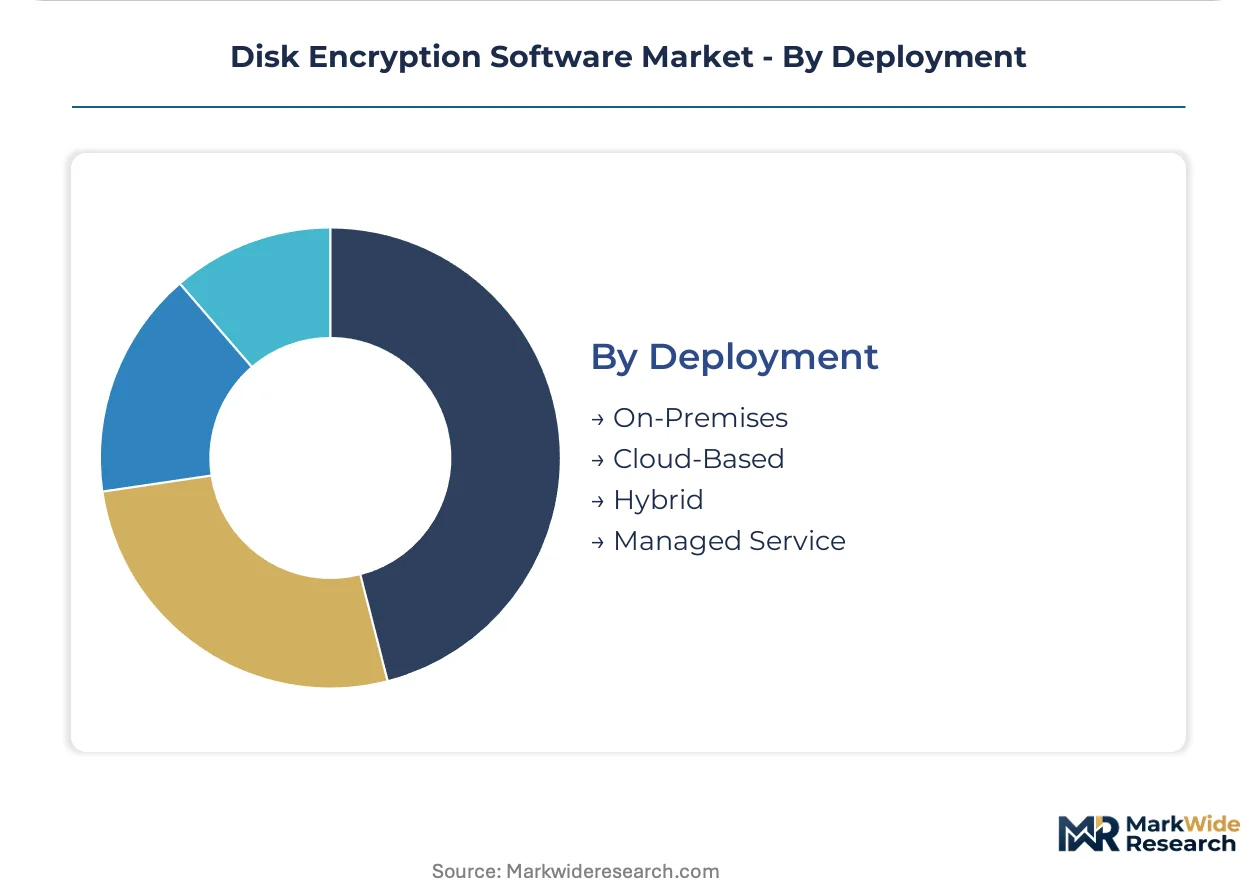
Deployment:
Infrastructure maturity determines whether organizations self-manage encryption or consume protection as a managed service.
- Hybrid:Synchronized key management spanning on-premise data centers and public cloud workloads. Manufacturing conglomerates in Stuttgart operate hybrid architectures linking factory-floor SCADA encryption with cloud-based analytics pipelines.
- Managed Service:Third-party key escrow, rotation, and compliance reporting delivered under subscription contracts. Mid-market financial services firms in Madrid outsource encryption operations to meet GDPR breach-notification timelines without internal cryptographic engineering capacity.
- On-Premises:Self-hosted encryption infrastructure with dedicated hardware security modules.
- Cloud-Based:Native encryption services integrated with single-cloud provider ecosystems.
Hybrid deployment captures the largest committed spend base. Managed services climb fastest as skills constraints bite mid-market organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Cologne rail corridor and Amsterdam-Rotterdam-Antwerp port complex anchor European data infrastructure density. Submarine cable landings at Virginia Beach and Los Angeles underpin transatlantic digital traffic. Singapore's Changi-North-South expressway grid connects ASEAN financial data centers.
United States
Healthcare systems in Boston and Houston drive AES-256 procurement for HIPAA-protected patient archives. The SEC enforces encryption standards for broker-dealer data retention. Cloud concentration in Northern Virginia's Data Center Alley accelerates hybrid key management deployment across federal contractor networks.
Germany
Automotive cyber-insurance mandates from Munich-based underwriters require full-disk encryption across Stuttgart manufacturing plants. DORA implementation deadlines force Frankfurt financial institutions into accelerated procurement cycles. Industrial conglomerates in North Rhine-Westphalia integrate encryption with SCADA systems protecting factory-floor intellectual property.
United Kingdom
London's financial services sector adopts confidential computing for real-time transaction analytics under FCA operational resilience guidelines. NHS trusts in Manchester and Birmingham encrypt patient records amid ransomware frequency. The National Cyber Security Centre certifies encryption modules for government contractor supply chains.
Japan
Tokyo's financial district pilots quantum-resistant algorithms for long-term government bond archives under METI guidance. Osaka pharmaceutical manufacturers encrypt clinical trial data for PMDA submission requirements. Automotive suppliers in Aichi Prefecture protect autonomous vehicle training datasets from cross-border exfiltration.
India
RBI data localization mandates drive encryption infrastructure investment in Mumbai's BKC financial district. Bangalore software exporters encrypt client source code under contract terms with US and European enterprises. The country's national cybersecurity regulator prescribes standards for critical infrastructure operator compliance.
Disk Encryption Software Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in cryptographic hardware and key management modules. The market exhibits moderate concentration with three to five dominant vendors anchoring enterprise procurement frameworks. Strategic archetypes include cloud-native platform providers, hardware-anchored security stacks, and managed detection bundlers. Competitive dynamics center on hybrid deployment certification and quantum-resistant algorithm roadmaps.
Within the cloud-native platform tier, Microsoft Corporation exemplifies ecosystem-anchored encryption delivery through infrastructure integration. IBM Corporation occupies a position bridging mainframe-grade hardware security with software abstraction layers. Sophos Limited represents the managed service bundling archetype, embedding encryption within broader endpoint protection contracts. These three anchors illustrate divergent paths for market positioning.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Dell Technologies Inc. |
| Thales S.A. |
| Check Point Software Technologies Ltd. |
| Sophos Limited |
| Trend Micro Incorporated |
| McAfee LLC |
| WinMagic Inc. |
| Others |
Supply Flow & Price Mechanics
Hardware security module fabrication concentrates in Taiwan and South Korea, anchoring cost structures for enterprise encryption deployments and concentrating margin capture with semiconductor foundries serving Thales and IBM hardware stacks.
Pricing Analysis
EU DORA dictates the pricing tier structure across the European enterprise segment. Three-tier pricing structure across premium, standard, and economy levels separates FIPS 140-2 validated deployments from basic AES-256 implementations and open-source alternatives. Certification grade and volume scale drive price differentiation, with government buyers least price-sensitive and mid-market SMBs facing acute cost compression. Pricing pressure stems from cloud-native competitors commoditizing baseline encryption through bundled infrastructure services.
Supply Chain Analysis
Cryptographic processor silicon feeds from Taiwan, South Korea, and the United States. Advanced encryption standard intellectual property, hardware security module assemblies, and cloud infrastructure capacity constitute critical input dependencies. Single-source vulnerability around specialized cryptographic chip fabrication creates systemic exposure. Distribution runs through direct enterprise sales teams and hyperscaler marketplaces, with channel partners consolidating in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise security operations center consolidation concentrates buyer power, with Fortune 500 CISOs mandating unified vendor frameworks that compress supplier margins and accelerate procurement standardization.
For Market Incumbents: Pre-empt quantum-resistant algorithm obsolescence by accelerating NIST-compliant migration roadmaps for existing customer archives. Defend against cloud-native displacement by embedding hardware security module differentiation into hybrid deployment certifications. Invest in confidential computing integration to collapse at-rest and in-use protection categories.
For New Entrants and Emerging Players: Pursue healthcare IoT encryption whitespace where connected medical devices lack standardized protection protocols. Target mid-market managed service bundling in Madrid and Bangalore where skills constraints prevent self-managed deployments. Lead with subscription-based key escrow and rotation services to bypass capital-intensive hardware procurement barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed endpoint protection vendors seeking encryption module tuck-ins to complete platform breadth. Five-to-ten year viability hinges on quantum-resistant algorithm transition execution and confidential computing integration depth. Monitor NIST post-quantum standardization finalization as inflection signal for accelerated replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Resistant Algorithm Migration | NIST compliance deadlines force accelerated archive re-encryption investments across financial services. |
| Confidential Computing Integration | Hardware-software hybridization collapses separate procurement categories for Frankfurt transaction analytics pilots. |
| Managed Detection Bundling | Recurring revenue shift captures mid-market buyers lacking internal cryptographic engineering capacity. |
| Healthcare IoT Module Development | Embedded encryption addresses standardized protection gaps in hospital network connected devices. |
| India Data Localization Infrastructure | RBI mandates require domestic encryption architecture investment in Mumbai financial district. |
Methodological Framework
A standing panel of CISOs, IT procurement officers, platform engineers, and channel partners provided ongoing calibration across primary interview cycles. These practitioner inputs combined with secondary validation from SEC filings, hyperscaler capex disclosures, NIST standardization documents, and enterprise procurement databases. Bottom-up deployment modeling and top-down market sizing underwent continuous triangulation.
Scenario-bracketing framed analytical development across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derived from encrypted workload growth trajectories and compliance-driven replacement cycles. Quantum-resistant algorithm migration timelines and confidential computing adoption curves served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments and enterprise IT budget cycles would shift the trajectory. Forecasts reflect documented assumptions around regulatory deadline adherence and technology transition pacing. Cross-checking against NIST post-quantum cryptography standardization progress is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Software Defined Perimeter (SDP) Market
Security Software
Global Optical Encryption Market
Security Software
POS Security Market
Security Software
Passwordless Authentication Market
Security Software
Decentralized Identity Software Market
Security Software
Global Consumer IAM Market
Security Software
US Hardware OTP Token Authentication Market
Security Software
Network Video Recorder (NVR) Market
Security Software
Smartphone Security Market
Security Software
Global Digital Vehicle Forensics Market
Security Software
Contactless Smart Card Market
Security Software
User Provisioning Software Market
Security Software
Phone Antivirus Software Market
Security Software
Business Email Compromise (BEC) Market
Security Software
Identity Verification Software Market
Security Software
Extended Detection and Response Market