
 Identity Verification Software Market | 2026-2036
Identity Verification Software Market Size, Share, and Industry Trends Forecast 2026-2036
Identity Verification Software Market Outlook
Banking and fintech is repositioning the Identity Verification Software Market as real-time transaction monitoring replaces periodic batch checks. LexisNexis Risk Solutions leverages its risk data consortium to anchor enterprise fraud prevention workflows. IDEMIA specializes in government-grade biometric enrollment systems that sustain long-term credentialing contracts. Trulioo competes through its global identity network covering emerging market document sets.
Identity verification software encompasses systems that validate individual identity claims through biometric matching, document authentication, and database cross-referencing against government or private records, typically processing liveness detection, OCR extraction, and watchlist screening within sub-second response windows. Its primary purpose is to reduce synthetic identity fraud and satisfy know-your-customer obligations across regulated industries. Biometric authentication leads solution type revenue as facial recognition and voiceprint engines displace password-based workflows, while KYC compliance commands premium pricing from financial institutions facing escalating regulatory penalties. Cloud-based deployment is accelerating fastest among mid-market fintechs seeking elastic verification capacity without capital infrastructure.
Europe's EBA anti-money laundering guidelines, the US FFIEC authentication guidance, and India's Aadhaar-linked eKYC framework are tightening technical standards for identity assurance across jurisdictions. These regulations shape demand by mandating multi-factor verification and audit trails that force legacy system replacements. Stakeholders must monitor evolving biometric consent requirements and cross-border data localization rules that will determine which technology architectures retain market access.
Market Dynamics
Real-time biometric liveness detection is compressing verification latency from minutes to sub-second intervals, forcing infrastructure rebuilds across banking and government credentialing systems. This technical acceleration is redrawing procurement criteria toward cloud-native orchestration platforms.
Growth Catalysts
- FFIEC authentication guidance:US financial institutions must deploy multi-factor verification with audit trails, triggering wholesale replacement of legacy batch-processing systems.
- Digital onboarding surge:Fintechs in Singapore and Germany are consuming elastic API-based verification capacity to support cross-border account opening without physical branches.
- Aadhaar-linked eKYC:India's biometric consent framework mandates government-database cross-referencing, creating sustained demand for enrollment infrastructure.
Market Restraints
- GPU compute cost volatility:Facial recognition training and inference depend on specialized semiconductor supply concentrated in Taiwan and South Korea.
- Cross-border data localization:EU GDPR and India's data residency rules fragment cloud architecture, forcing redundant infrastructure deployment.
- Synthetic identity sophistication:Deepfake injection attacks against liveness detection are outpacing defensive algorithm updates in unsupervised environments.
Strategic Opportunities
- Brazilian banking unbanked segment:ANVISA-aligned health credentialing and central bank digital identity pilots create first-mover whitespace for document-authentication vendors.
- Voiceprint-behavioral biometrics convergence:Call center fraud prevention is absorbing multimodal verification combining voice recognition with keystroke dynamics.
- EU AI Act compliance tooling:Risk classification mandates for biometric systems are spawning audit-automation software subscriptions.
Industry Challenges
- Adversarial machine learning expertise scarcity:Defensive AI teams capable of training against deepfake evasion remain concentrated at academic institutions and national labs.
- Legacy core banking integration:SOAP-based mainframe architectures in incumbent financial institutions resist REST API orchestration without middleware capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Identity Verification Software Market |
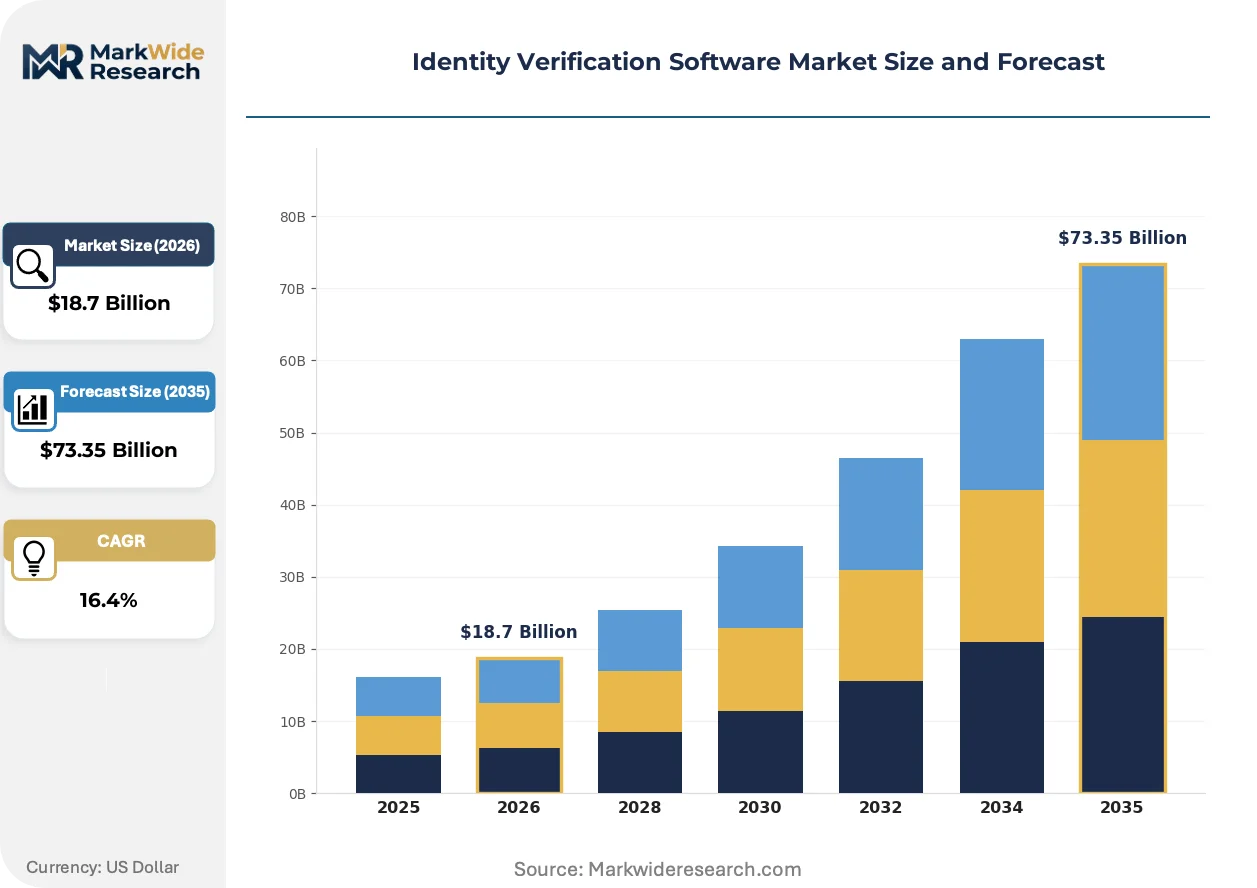
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Biometric Authentication, Document Verification, Identity Proofing, KYC Compliance End User: Financial Institutions, E-Commerce Platforms, Government Agencies, Telecom Companies Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS Technology: Machine Learning, Blockchain, Optical Character Recognition, Facial Recognition |
| Companies Covered | LexisNexis Risk Solutions, Entrust, IDEMIA, Jumio, Trulioo, Onfido, Experian, Mitek Systems, Veriff, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Identity Verification Software Market Strategic Shifts
Document-centric verification is yielding to continuous identity assurance, where behavioral signals and biometric rechecking persist across entire user sessions rather than gating entry alone.
Passive liveness detection using single-frame analysis is converging with edge-computing deployment on mobile devices. Tier-two banks and neobanks are adopting this to reduce server-side processing costs. The convergence is compressing vendor differentiation toward SDK footprint size and battery efficiency rather than cloud accuracy benchmarks.
Europe's EBA anti-money laundering guidelines are mandating transaction-linked identity re-verification for high-risk payments. Payment processors must now maintain persistent identity graphs rather than one-time checks. German and Dutch clearing banks are responding by procuring orchestration platforms that unify KYC, transaction monitoring, and sanctions screening.
Buyer committees in financial services are unbundling point-solution contracts into modular procurement of document capture, biometric matching, and watchlist screening from separate vendors. Systems integrators are capturing margin by stitching these components. This pattern is most visible in US regional banks seeking to displace monolithic legacy suites.
Identity Verification Software Market Segmentation
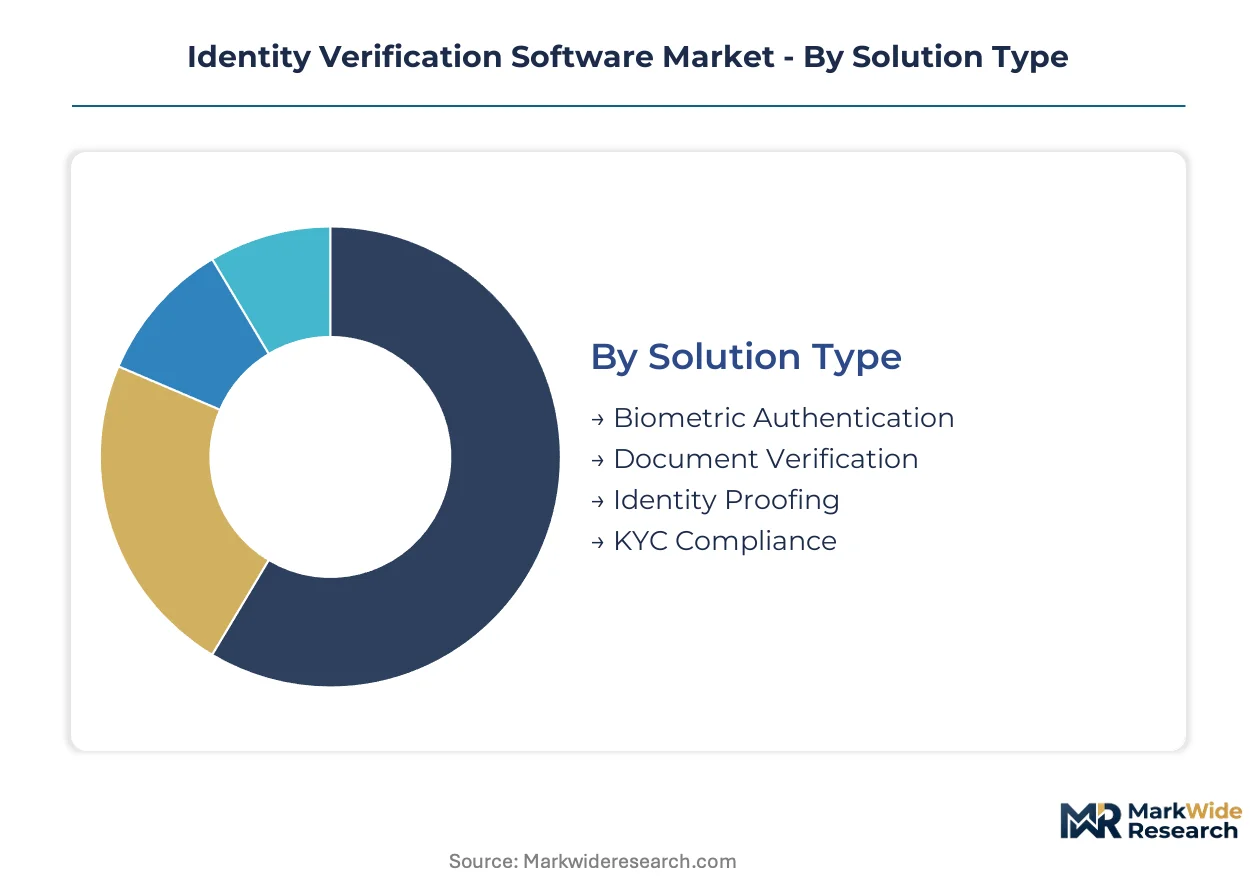
Segmentation reveals how procurement priorities diverge across regulated industries and deployment architectures. Banking and fintech buyers prioritize real-time biometric throughput, while government agencies demand offline-capable document verification with audit-grade chain of custody.
Solution Type:
Supply concentration in facial recognition inference chips from Taiwan and South Korea creates procurement bottlenecks for high-volume biometric deployments.
- Biometric Authentication:Facial recognition and voiceprint engines process liveness detection within sub-second windows using specialized GPU clusters. US and Singaporean banks consume the majority of enterprise-grade capacity as FFIEC guidance mandates multi-factor verification with immutable audit trails.
- KYC Compliance:Regulatory workflow software integrates document authentication, watchlist screening, and risk scoring into unified orchestration platforms. German and Dutch clearing banks drive premium pricing as EU anti-money laundering directives tighten technical standards for transaction-linked identity re-verification.
- Document Verification:OCR extraction and forensic document analysis for government-issued credentials.
- Identity Proofing:Initial enrollment and credential binding for account origination workflows.
Biometric Authentication absorbs the bulk of installed capacity; KYC Compliance is expanding most quickly as regulatory penalties escalate.
End User:
Cost tier stratification separates enterprise buyers with dedicated compliance budgets from mid-market fintechs seeking consumption-based pricing.
- Financial Institutions:Tier-one banks and neobanks deploy continuous identity assurance across entire user sessions rather than gating entry alone. Singaporean digital banks and US regional banks are unbundling monolithic legacy suites into modular procurement of document capture, biometric matching, and watchlist screening.
- Government Agencies:National ID programs and border control systems require government-grade biometric enrollment with decades-long credential lifecycles. India's Aadhaar-linked eKYC framework sustains demand for enrollment infrastructure with mandatory government-database cross-referencing.
- E-Commerce Platforms:Marketplace sellers and high-value transaction verification for fraud prevention.
- Telecom Companies:Subscriber identity verification for SIM registration and mobile money onboarding.
Financial Institutions command the highest per-seat pricing; Government Agencies lock in the longest contract durations.
Deployment Model:
Volume concentration in cloud-native architectures is displacing capital-intensive on-premises installations across mid-market segments.
- Cloud-Based:Elastic API consumption allows fintechs to scale verification capacity without infrastructure capital. Singaporean and German neobanks are consuming this model for cross-border account opening without physical branches, though EU GDPR and India's data residency rules fragment architecture and force redundant deployment.
- SaaS:Pre-configured verification workflows with subscription pricing reduce integration complexity for regional banks. US mid-market financial institutions favor this model to avoid middleware capital expenditure when connecting to SOAP-based mainframe architectures.
- On-Premises:Air-gapped installations for classified government and defense applications.
- Hybrid:Split processing with edge biometric capture and cloud-based watchlist screening.
Cloud-Based deployment carries the majority of new installations; SaaS is climbing the fastest among buyers seeking to minimize integration overhead.
Technology:
Margin differentiation hinges on adversarial robustness against synthetic identity attacks rather than baseline accuracy benchmarks.
- Facial Recognition:Passive liveness detection using single-frame analysis converges with edge-computing deployment on mobile devices. Tier-two banks adopt this to reduce server-side processing costs, compressing vendor differentiation toward SDK footprint size and battery efficiency.
- Machine Learning:Defensive AI training against deepfake evasion requires scarce expertise concentrated at academic institutions and national labs. The sophistication of synthetic identity injection attacks is outpacing algorithm updates in unsupervised environments.
- Optical Character Recognition:Document field extraction and tamper detection for credential authentication.
- Blockchain:Decentralized identity credentialing with selective disclosure for privacy-preserving verification.
Facial Recognition dominates current revenue; Machine Learning is gaining share fastest as adversarial attack sophistication accelerates defensive investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Digital Free Trade Zone and Germany's fintech hubs are concentrating procurement for real-time verification infrastructure. Enterprise buyers in these zones prioritize API-native orchestration platforms that compress onboarding latency from minutes to sub-second intervals.
United States
FFIEC authentication guidance mandates multi-factor verification with immutable audit trails across tier-one banks and regional institutions. The SEC and OCC supervise compliance frameworks that force wholesale replacement of legacy batch-processing systems. New York and San Francisco fintech clusters absorb the majority of elastic API consumption for cross-border account opening.
Germany
BaFin and the EBA anti-money laundering guidelines drive transaction-linked identity re-verification for high-risk payments through German clearing banks. KBA automotive-grade biometric standards spill into financial credentialing workflows. Frankfurt and Berlin neobanks procure orchestration platforms unifying KYC, transaction monitoring, and sanctions screening.
Singapore
MAS digital banking licenses and cross-border payment corridors position Singapore as the dominant verification hub for Southeast Asian fintech expansion. The country's data residency framework permits cloud-native deployment without redundant infrastructure. Raffles Place and One-North fintech clusters consume elastic verification capacity for branchless account origination.
India
RBI and UIDAI Aadhaar-linked eKYC mandates sustain demand for government-database cross-referencing enrollment infrastructure. BIS technical standards govern biometric device certification for financial inclusion programs. Mumbai and Bangalore digital payment platforms deploy liveness detection at scale for the unbanked segment.
Identity Verification Software Market Competitive Environment
Top-tier vendors anchor government-grade biometric enrollment, while mid-market specialists compete on SDK footprint and battery efficiency for mobile deployment. The vendor base stratifies across risk data consortiums, document-authentication networks, and orchestration platform providers. Three archetypes dominate: data-rich incumbents leveraging proprietary risk graphs, pure-play biometric specialists, and global identity network aggregators. M&A activity concentrates on API-native orchestration capabilities, while strategic partnerships target embedded finance verification stacks.
Within the data consortium tier, LexisNexis Risk Solutions and Experian occupy positions anchored by proprietary risk data networks that feed enterprise fraud prevention workflows. IDEMIA exemplifies the government-grade enrollment archetype through its specialization in biometric credentialing systems with decades-long contract horizons. Trulioo represents the global network model, covering emerging market document sets through distributed verification partnerships.
| Leading Market Players |
|---|
| LexisNexis Risk Solutions |
| Entrust |
| IDEMIA |
| Jumio |
| Trulioo |
| Onfido |
| Experian |
| Mitek Systems |
| Veriff |
| Others |
Value Chain & Pricing Dynamics
Enterprise banking procurement committees and government credentialing agencies anchor pricing power in the Identity Verification Software Market, concentrating demand around multi-year SaaS contracts with embedded professional services. This buyer concentration compresses vendor margins on standardized biometric matching while sustaining premium capture for government-grade enrollment infrastructure.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as tier-one banks demand sub-90-day deployment windows for FFIEC compliance deadlines. The market runs on a three-tier pricing structure across premium, standard, and economy levels: government agencies pay premium rates for air-gapped installations with audit-grade chain of custody, mid-market fintechs consume standard SaaS tiers with API-based consumption, and emerging market telecoms negotiate economy rates for batch document verification. Price differentiation rests on certification level — vendors with BIS biometric device clearance and EBA audit trail compliance command 15-30% uplifts. Pricing pressure stems from GPU compute cost volatility in facial recognition training, which squeezes margins for cloud-native providers. Government agencies exhibit lowest price sensitivity due to decade-long credentialing mandates; neobanks show highest sensitivity as they optimize for per-verification unit economics.
Supply Chain Analysis
Dual-sourcing requirements from US and European financial institutions mandate multi-supplier qualification for facial recognition inference chips, forcing vendors to maintain relationships with both Taiwan Semiconductor Manufacturing and Samsung Foundry. Geographic supply concentrates in Taiwan, South Korea, and the United States for GPU and NPU silicon. Raw material dependencies include specialized CMOS image sensors from Sony and OmniVision, rare earth elements for magnetic components in biometric capture devices, and high-purity silicon wafers. Supply chain risk centers on single-source vulnerability in EUV lithography equipment controlled by ASML in the Netherlands. Distribution runs through hyperscaler marketplaces — AWS, Azure, and Google Cloud — for cloud-native deployments, with direct enterprise sales for on-premises government installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Identity Verification Software Market is consolidating around orchestration platform capabilities as modular procurement patterns displace monolithic suite vendors. Adversarial AI expertise scarcity and cross-border data localization compliance costs are forcing weaker point-solution players toward acquisition or exit.
For Market Incumbents: Lock in government credentialing contracts with decades-long renewal horizons before pure-play biometric specialists achieve BIS or KBA certification parity. Defensive moves should center on backward integration into edge-computing SDK development to capture tier-two bank procurement, and channel control through exclusive systems integrator partnerships that box out modular competitors. The emerging threat is API-native orchestration platforms unbundling document capture, biometric matching, and watchlist screening into separate vendor relationships.
For New Entrants and Emerging Players: Enter via Brazilian banking unbanked segments where ANVISA-aligned health credentialing and central bank digital identity pilots create whitespace without incumbent saturation. The most penetrable geography is Southeast Asian neobanks seeking voiceprint-behavioral biometrics convergence for call center fraud prevention. Go-to-market should anchor on consumption-based pricing with elastic API capacity, avoiding the capital expenditure barriers that stall on-premises incumbents.
For Investors and Strategic Acquirers: The window for entry favors orchestration platform aggregators with REST API-native architectures and pre-built connectors to SOAP-based mainframe systems. Long-term viability across the projection horizon rests on defensive AI training capabilities against deepfake evasion. The acquisition target archetype is mid-market document-authentication vendors with emerging market document set coverage. The signal to watch as inflection indicator is EU AI Act risk classification mandates for biometric systems, which will trigger audit-automation software subscription spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies KYC, transaction monitoring, and sanctions screening for German clearing banks under EBA guidelines. |
| Acquisition of Specialist Firm | Adds emerging market document set coverage to expand addressable market in Brazil and India. |
| Geographic Expansion | Establishes Singapore hub to serve MAS-licensed digital banks across Southeast Asian corridors. |
| Product Launch | Introduces passive liveness detection SDK with edge-computing deployment for tier-two bank cost reduction. |
| Strategic Partnership | Embeds verification stack into hyperscaler marketplaces to capture mid-market fintech API consumption. |
Study Parameters
SEC filings, UIDAI procurement disclosures, and EBA regulatory guidance documents formed the secondary backbone of this analysis. Primary interviews with chief technology officers at neobanks, compliance officers at tier-one banks, biometric systems engineers, government credentialing program managers, and API product managers at orchestration platform vendors validated demand assumptions. The research combined bottom-up verification volume estimates with top-down regulatory mandate sizing across the analysis window.
Historical trendline analysis of digital onboarding volumes and regulatory penalty escalations anchored the forecast framework. Segmentation dimensions modeled include deployment model, end-user vertical, solution type, and regional regulatory cluster. CAGRs were derived from elasticity modeling of verification demand against FFIEC, EBA, and Aadhaar-linked eKYC compliance deadlines. Industry-specific forecast inputs included GPU compute cost trajectories and biometric device certification queue lengths at BIS and KBA.
Forecast precision tightens around the base case; tail outcomes carry wider variance under deepfake attack sophistication acceleration and cross-border data localization rule expansion. Deviation in Taiwan semiconductor supply continuity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Security Software for Consumers Market
Security Software
Managed Security Services Market
Security Software
Japan Mobile Biometrics Market
Security Software
Anti-Fraud Management System Market
Security Software
Europe Encryption Software Market
Security Software
Global Background Screening Market
Security Software
Automotive Endpoint Authentication Market
Security Software
Global Security Operation Center As a Service Market
Security Software
Employee Surveillance and Monitoring Software Market
Security Software
Italy Endpoint Detection and Response Market
Security Software
Fraud Detection Software Market
Security Software
Mobile Identity Management Market
Security Software
Identity Governance and Administration Market
Security Software
Unified Threat Management (UTM) Market
Security Software
Smartphone Security Market
Security Software
US Evidence Management Market