
 Contactless Smart Card Market | 2026-2036
Contactless Smart Card Market Size, Share, and Industry Trends Forecast 2026-2036
Contactless Smart Card Market Intelligence
East Asian semiconductor foundries are expanding wafer output for secure element chips to serve card manufacturers worldwide. NXP Semiconductors dominates NFC controller supply with in-house fabrication that reduces dependency on external silicon sources. Thales leverages its aerospace-grade security heritage to anchor high-assurance government credential contracts across multiple continents. Giesecke & Devrient specializes in polycarbonate card bodies with embedded holograms for physical tamper resistance.
A contactless smart card is a pocket-sized credential embedding an antenna coil and integrated circuit that communicates with readers via radio frequency at 13.56 MHz, typically storing cryptographic keys for mutual authentication protocols. The device eliminates physical contact points, reducing mechanical wear and enabling sub-100-millisecond transaction speeds for high-throughput environments. Microprocessor cards command premium positioning due to their Java Card operating systems and public-key infrastructure support for multi-application deployments. Payment Solutions generates the deepest margin pools as EMVCo certification requirements create barriers for unqualified entrants. Memory Cards retain volume dominance in low-cost transit ticketing where cryptographic complexity remains minimal.
ISO/IEC 14443 and EMVCo specifications define physical-layer protocols and application-level security benchmarks that manufacturers must satisfy for financial network acceptance. ETSI standards in Europe mandate interoperability testing that delays uncertified products from entering procurement pipelines. The US Department of Homeland Security drives demand through PIV and PIV-I credential programs for federal employee access. Stakeholders must monitor evolving post-quantum cryptography migration timelines to determine hardware refresh cycles and firmware upgrade pathways.
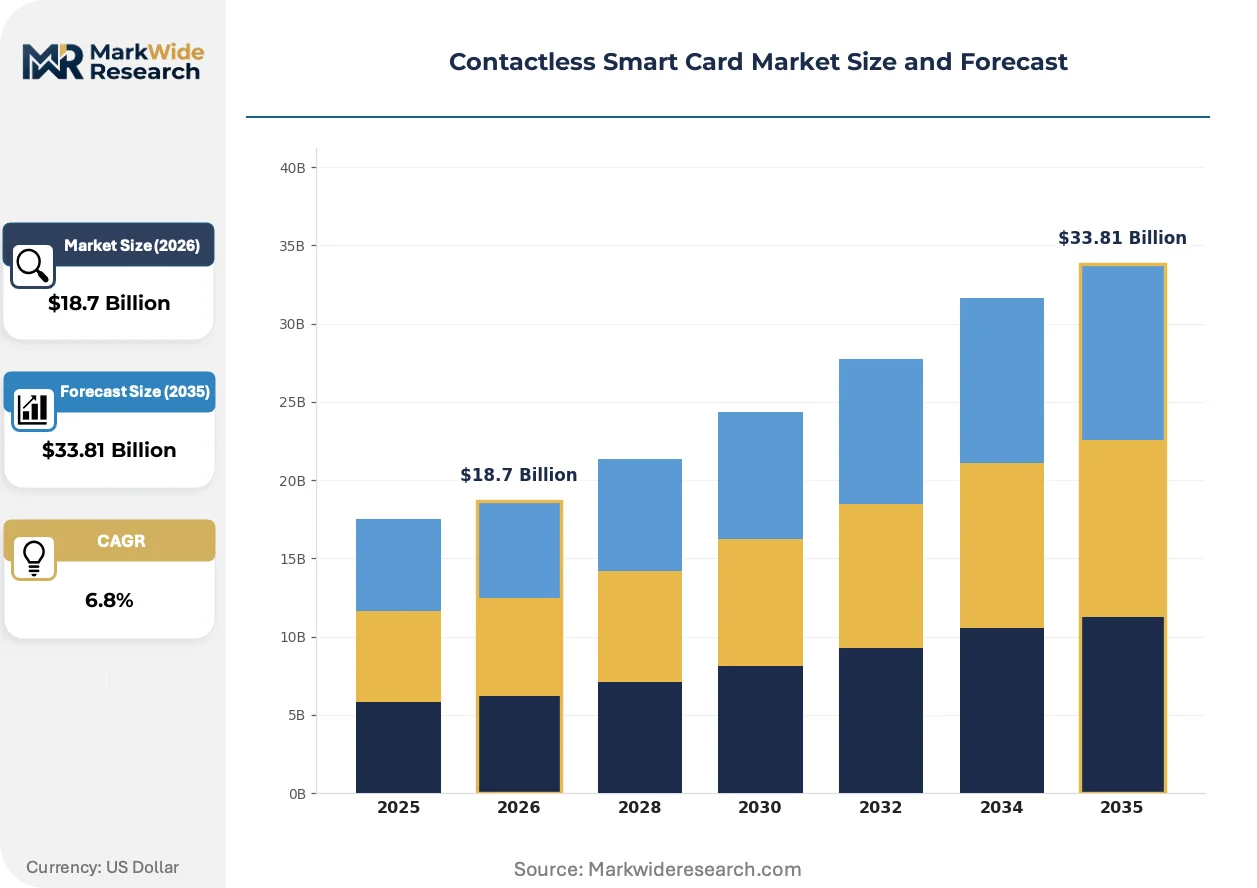
Market Dynamics
Transit authorities in major metropolitan networks are accelerating card deployments as ETSI and ISO standards tighten certification requirements across Europe, creating a structural bottleneck that favors pre-qualified suppliers.
Growth Catalysts
- ETSI Interoperability Mandates:European transit authorities now require certified contactless credentials for cross-border fare systems, forcing municipal operators to refresh legacy token-based infrastructure.
- Federal Credential Programs:The US Department of Homeland Security's PIV and PIV-I mandates for federal employee access drive sustained procurement of high-assurance smart card platforms.
- Dual Interface Migration:EMVCo specifications for contactless payment acceptance are pushing financial institutions toward cards supporting both contact and contactless protocols.
Market Restraints
- Secure Element Supply Concentration:East Asian foundries control wafer output for cryptographic chips, exposing card manufacturers to single-source risks during capacity crunches.
- Polycarbonate Raw Material Volatility:Specialized polymer substrates with embedded holograms face price swings tied to petrochemical feedstock markets.
- Post-Quantum Hardware Refresh Uncertainty:Migration timelines for quantum-resistant cryptography remain undefined, freezing long-term firmware architecture decisions.
Strategic Opportunities
- Municipal Transit Convergence:China's domestic payment rails and city transit systems offer scale deployment models for multi-application credential platforms.
- Biometric-Card Hybridization:Fingerprint sensors embedded in payment credentials are absorbing demand from high-value transaction segments seeking step-up authentication.
- India's Digital Public Infrastructure:The country's central bank and transit regulators are expanding contactless acceptance across tier-two urban centers.
Industry Challenges
- EMVCo Certification Bottlenecks:Laboratory testing queues for payment network approval extend product launch timelines by quarters.
- Legacy System Integration Friction:Transit operators with decades-old fare collection infrastructure face complex middleware requirements for dual-protocol acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactless Smart Card Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Memory Cards, Microprocessor Cards, Dual Interface Cards, Hybrid Cards, Contact-only Cards Technology: NFC, RFID, Secure Element, Bluetooth Low Energy, MIFARE Application: Access Management, Ticketing, Loyalty Programs, Identity Authentication, Payment Solutions End User: Government Agencies, Financial Institutions, Transportation Providers, Corporate Enterprises, Educational Institutions |
| Companies Covered | HID Global, CPI Card Group, Thales, Samsung Electronics, Infineon Technologies, IDEMIA, NXP Semiconductors, Sony Corporation, Giesecke & Devrient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactless Smart Card Market Strategic Shifts & Innovations
Hardware security architectures are converging with biometric modalities and post-quantum cryptographic primitives, reshaping how credentials authenticate users and protect transaction integrity across transit and payment networks.
Reconfigurable antenna designs are absorbing demand from card manufacturers seeking to optimize read-range performance across metal-rich environments like subway turnstiles. Transit operators in London and Singapore are piloting these substrates to reduce transaction failure rates at high-throughput gates. The technology is compressing field deployment cycles by eliminating custom tuning for each installation site.
REACH chemical restrictions in Europe are forcing substrate suppliers to reformulate polycarbonate card bodies and eliminate halogenated flame retardants from lamination layers. Manufacturers serving German and French government credential programs must recertify material stacks under revised ECHA substance evaluations. The regulatory pressure is accelerating migration toward bio-based polymers in premium card segments.
Subscription-based credential provisioning is replacing perpetual-license models among large transit agencies seeking to unbundle hardware acquisition from software maintenance. Transport for London and Transport for New South Wales have shifted toward multi-year service agreements with performance-linked renewals. This restructuring concentrates vendor selection authority within procurement teams rather than technical departments.
Contactless Smart Card Market Segmentation
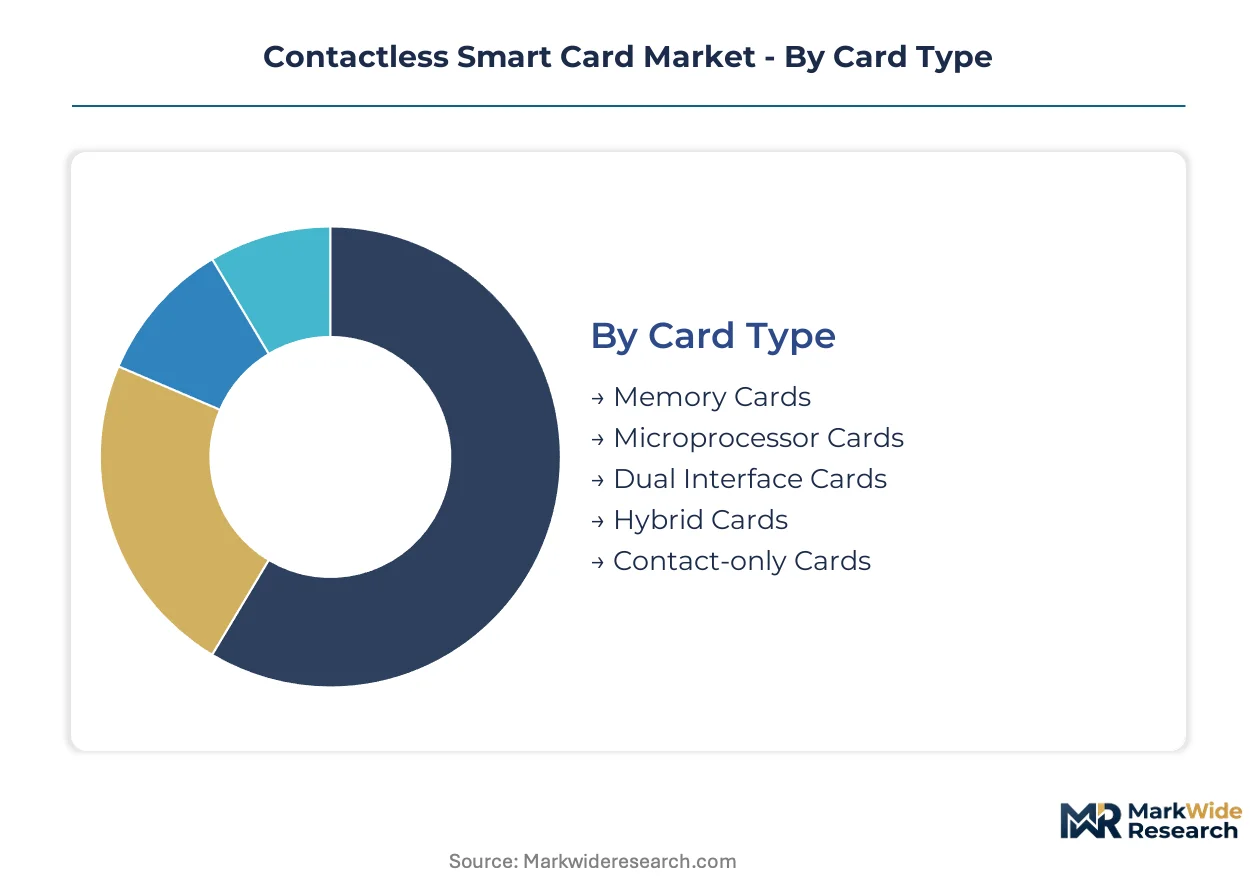
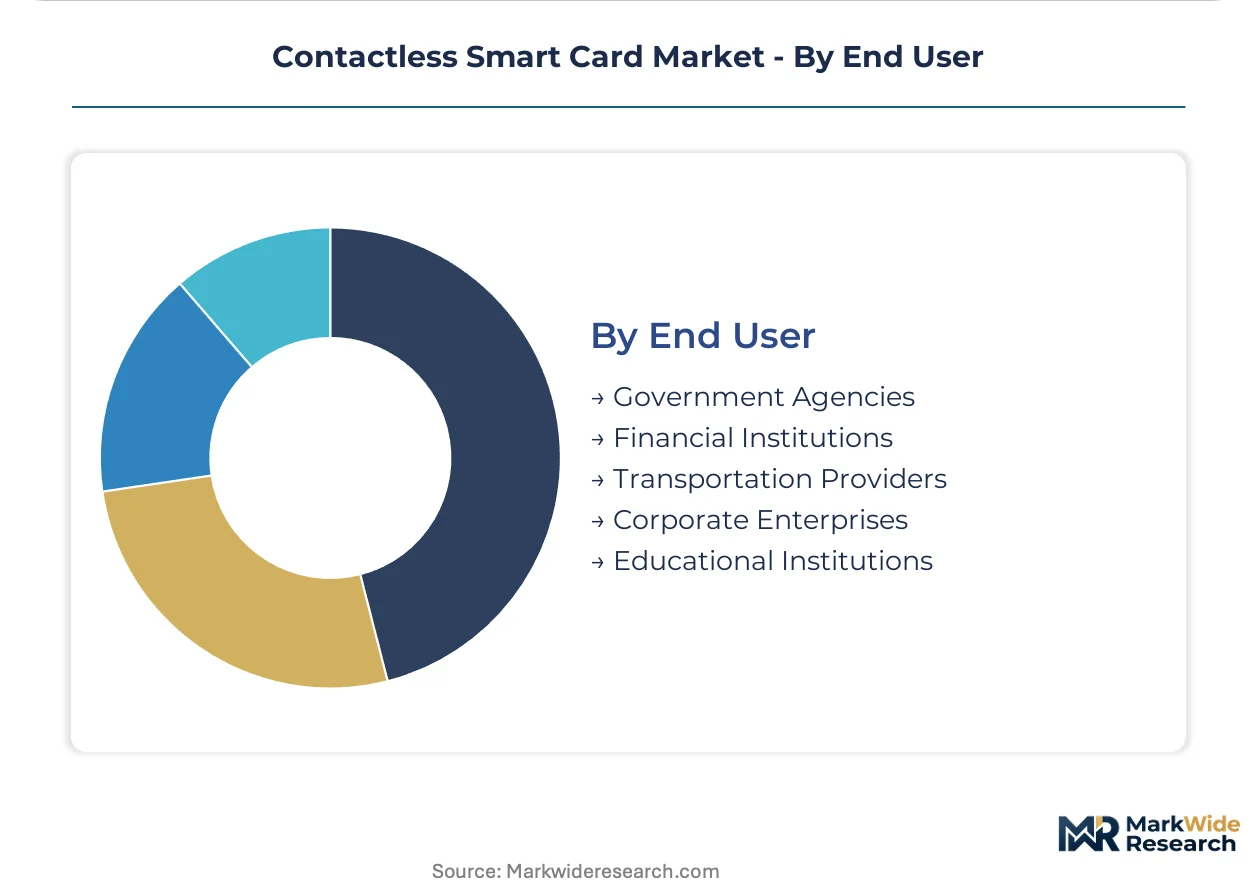
Segmentation in the contactless smart card market reveals how certification tiers, protocol compatibility, and end-user security mandates fragment procurement patterns. Buyers prioritize EMVCo compliance for financial deployments while transit operators optimize for read-range reliability at lower cryptographic thresholds.
Card Type:
Buyers select card architectures based on application complexity and lifecycle cost tradeoffs between upfront unit pricing and backend infrastructure requirements.
- Microprocessor Cards:These credentials embed dedicated secure microcontrollers running Java Card operating systems with public-key infrastructure support. Demand concentrates in government identity programs across Germany and France where ETSI-certified high-assurance credentials are mandatory for federal employee access.
- Dual Interface Cards:Single-chip designs support both contact and contactless protocols through shared secure elements. Financial institutions in the United States are migrating portfolios to these substrates as EMVCo specifications tighten contactless acceptance requirements at merchant terminals.
- Memory Cards:Simple EEPROM-based credentials store fixed data without processing capability. Municipal transit systems in China deploy these for low-cost single-trip ticketing where cryptographic mutual authentication remains unnecessary.
- Hybrid Cards:Dual-chip architectures isolate contact and contactless functions on separate silicon. Legacy infrastructure in Japan's transit networks sustains demand for these transitional form factors.
- Contact-only Cards:Physical gold-plated pads transmit data through direct reader insertion. Banking regulators in India continue issuing these for high-value corporate account authentication where air-gap security is preferred.
Volume sits with Memory Cards; growth tilts toward Dual Interface Cards.
Technology:
Protocol selection determines antenna design, power harvesting efficiency, and reader infrastructure compatibility across deployment environments.
- NFC:ISO/IEC 14443-compliant near-field communication operates at 13.56 MHz with 10-centimeter read ranges. Payment networks in South Korea mandate NFC controller certification for mobile wallet interoperability.
- Secure Element:Tamper-resistant silicon stores cryptographic keys in hardware-isolated environments. Government credential programs in the United States require FIPS 140-2 Level 3 certification for these components.
- MIFARE:NXP Semiconductors' proprietary protocol dominates transit ticketing with deterministic transaction timing under 100 milliseconds. Transport for London's Oyster system anchors global volume for this technology.
- RFID:Ultra-high-frequency variants extend read ranges beyond NFC limitations for asset tracking applications. Industrial logistics operators in Germany deploy these for supply chain visibility.
- Bluetooth Low Energy:Credential emulation via smartphone apps is gaining traction in corporate access control. Technology campuses in Singapore pilot these for frictionless building entry.
Secure Element commands premium positioning; NFC expands most quickly.
Application:
End-use function dictates security architecture, transaction speed requirements, and backend system integration complexity.
- Payment Solutions:EMVCo-certified credentials enable tap-to-pay at merchant terminals with dynamic cryptogram generation. Issuers in Brazil face mandatory contactless migration timelines set by the central bank.
- Identity Authentication:Biometric-match-on-card technologies are absorbing demand from border control agencies. The US Department of Homeland Security's PIV program specifies these for federal facility access.
- Access Management:Corporate campuses in Switzerland deploy multi-application credentials combining physical building entry with logical network authentication.
- Ticketing:Account-based fare collection is displacing card-centric models in Australian transit networks. Transport for New South Wales leads this infrastructure transition.
- Loyalty Programs:Retail coalitions in the United Arab Emirates embed payment and rewards functions on shared credentials. Mall operators in Dubai prioritize these for customer data integration.
Payment Solutions generate deepest margins; Identity Authentication shows steepest expansion trajectory.
End User:
Procurement authority and security certification requirements vary sharply across institutional buyer categories.
- Government Agencies:National ID programs and border control systems demand polycarbonate card bodies with embedded holograms. France's ANSM oversees medical professional credential standards that influence physical durability specifications.
- Financial Institutions:Commercial banks in Spain are consolidating card manufacturing contracts to capture volume discounts on dual-interface EMV portfolios.
- Transportation Providers:Transit authorities in Italy face ETSI interoperability mandates for cross-border rail fare systems. Trenitalia's procurement specifications are shaping regional supplier qualification.
- Corporate Enterprises:Multinational headquarters in the Netherlands standardize on converged physical-logical access credentials. ASML's campus security requirements drive demand for high-assurance multi-application platforms.
- Educational Institutions:University campuses in Canada deploy student ID credentials with stored-value transit functions. The University of Toronto's procurement anchors volume for combined payment-access substrates.
Financial Institutions dominate absolute volume; Government Agencies concentrate premium-tier demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polycarbonate resin supply from German chemical clusters anchors European card body manufacturing, while East Asian foundry capacity for secure element silicon concentrates procurement decisions across three continents.
United States
Federal employee credential programs and EMVCo payment mandates drive procurement volumes. The Department of Homeland Security's PIV specifications require FIPS 140-2 Level 3 certification for secure elements. Arizona-based manufacturing facilities process polycarbonate substrates for government ID contracts.
Germany
ETSI interoperability standards for transit systems create certification bottlenecks favoring pre-qualified suppliers. The country's national cybersecurity regulator enforces Common Criteria evaluation for high-assurance credentials. Munich and Stuttgart host polycarbonate card body production serving European government contracts.
China
Domestic payment rails and municipal transit convergence generate scale deployment opportunities for multi-application platforms. The Ministry of Industry and Information Technology oversees GB standards for contactless protocol compatibility. Shanghai and Shenzhen foundries expand wafer output for secure element chips.
Japan
Legacy transit infrastructure sustains demand for hybrid card architectures with dual-chip isolation. METI coordinates national ID program specifications with embedded hologram requirements. Tokyo and Osaka metropolitan networks anchor volume for FeliCa-compatible credentials.
India
The central bank's contactless payment mandates and transit regulator expansion into tier-two cities create infrastructure buildout demand. RBI specifications govern tokenization standards for tap-to-pay deployment. Bangalore and Hyderabad technology campuses pilot biometric-card hybrid credentials.
Contactless Smart Card Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biometric-card hybridization and post-quantum cryptographic upgrades. The vendor base stratifies across secure element fabricators, card body manufacturers, and system integrators with certification laboratory relationships. Three archetypes dominate: semiconductor foundries with captive secure element supply, polycarbonate specialists with embedded hologram capabilities, and diversified security conglomerates with government credential heritage. Competitive moves concentrate on EMVCo certification queue positioning and strategic partnerships with transit authority procurement teams.
Among diversified security conglomerates, Thales and Giesecke & Devrient exemplify archetypes leveraging aerospace-grade and polycarbonate specialization heritage respectively. NXP Semiconductors occupies a position representing integrated secure element and NFC controller supply. These three entities anchor distinct competitive vectors: Thales through high-assurance government contracts, Giesecke & Devrient through tamper-resistant physical substrates, and NXP through reduced external silicon dependency.
| Leading Market Players |
|---|
| HID Global |
| CPI Card Group |
| Thales |
| Samsung Electronics |
| Infineon Technologies |
| IDEMIA |
| NXP Semiconductors |
| Sony Corporation |
| Giesecke & Devrient |
| Others |
Cost & Logistics Intelligence
REACH chemical restrictions in Europe are forcing substrate suppliers to reformulate polycarbonate card bodies and eliminate halogenated flame retardants from lamination layers, gating qualified supply and concentrating premium-tier pricing access among manufacturers serving German and French government credential programs with ECHA-certified material stacks.
Pricing Analysis
Subscription-based credential provisioning is displacing perpetual-license models among large transit agencies seeking to unbundle hardware acquisition from software maintenance. Three-tier pricing structure across premium, standard, and economy levels separates EMVCo-certified payment credentials from ETSI transit cards from basic memory-card transit tickets. Cost compression in standard-tier dual-interface cards is intensifying because Transport for London and Transport for New South Wales have shifted toward multi-year service agreements with performance-linked renewals. Municipal transit systems in China show highest price sensitivity; government identity programs across Germany and France show lowest.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundries controlling wafer output for cryptographic chips, exposing card manufacturers to capacity crunches during demand spikes. Secure element silicon draws from Taiwan, South Korea, and China; polycarbonate card bodies source from German chemical clusters and Japanese polymer specialists. Supply chain risk centers on tariff exposure for semiconductor imports into European Union assembly facilities. Distribution runs through certified system integrators with EMVCo laboratory relationships and direct procurement contracts with transit authority technical departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
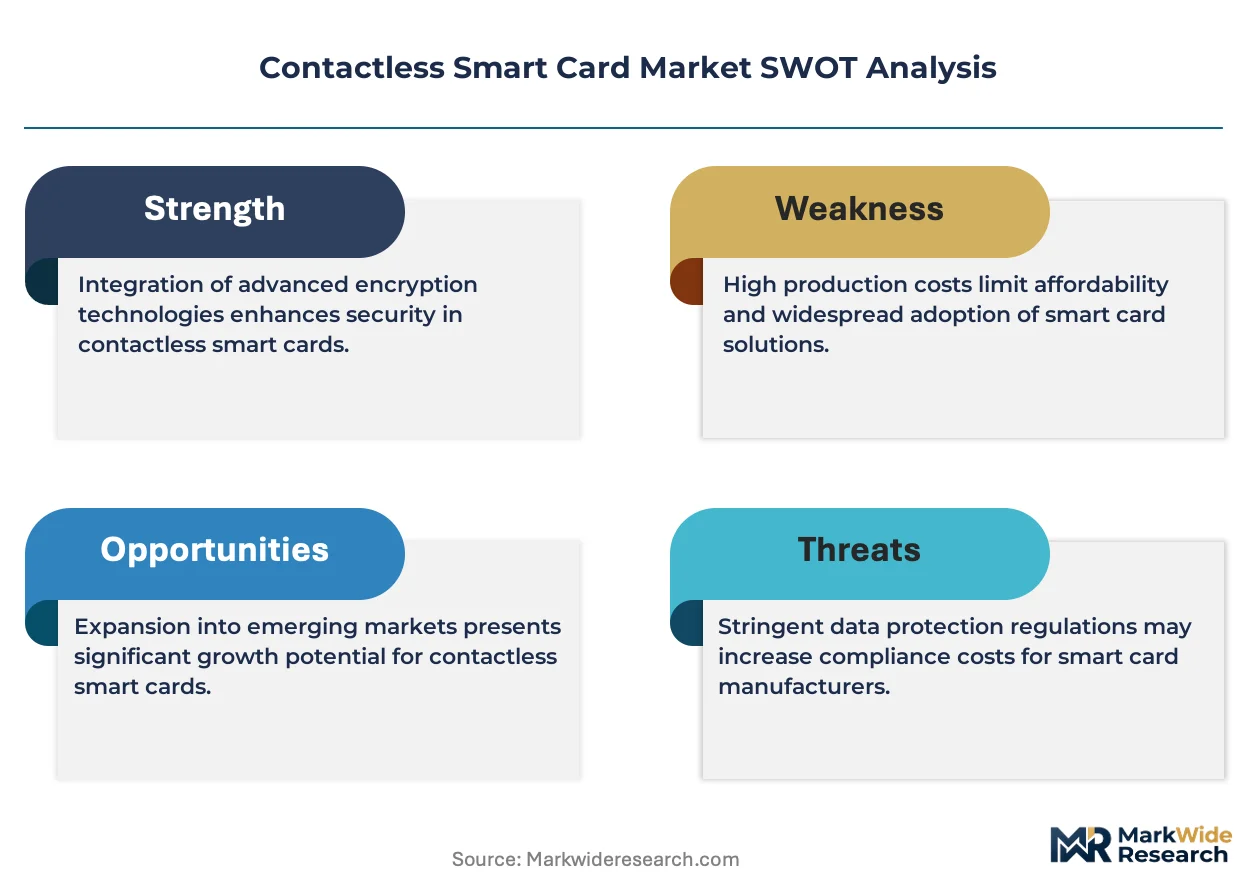
EMVCo certification bottlenecks are forcing consolidation as laboratory testing queues extend product launch timelines by quarters, squeezing weaker players lacking pre-qualified supplier status or established laboratory partnerships.
For Market Incumbents: Deploy certification queue positioning as the priority lever. Secure dedicated laboratory slots with EMVCo-accredited facilities to compress product launch timelines. Build backward integration into polycarbonate substrate production to reduce exposure to petrochemical feedstock price swings and REACH compliance recertification delays.
For New Entrants and Emerging Players: Transit authority procurement teams represent the most accessible channel partner type for credential platform vendors lacking financial network certification. Target India's tier-two urban centers where RBI contactless mandates and transit regulator expansion create infrastructure buildout demand without entrenched incumbent relationships. Pursue biometric-card hybridization for high-value transaction segments seeking step-up authentication as the go-to-market angle.
For Investors and Strategic Acquirers: Post-quantum cryptography migration timeline announcements from NIST are the leading indicator that hardware refresh cycles and firmware upgrade pathways will concentrate procurement authority among vendors with upgradeable secure element architectures. Position acquisition screening toward polycarbonate specialists with embedded hologram capabilities and ECHA-certified material stacks. Watch for quantum-resistant cryptography standard finalization as the inflection signal triggering replacement demand across federal credential programs.
| Strategic Initiative | Industry Significance |
|---|---|
| EMVCo Certification Investment | Pre-qualified laboratory relationships compress product launch timelines for payment network acceptance. |
| Backward Integration into Secure Element Supply | In-house wafer fabrication reduces dependency on East Asian foundry capacity during demand spikes. |
| Biometric Sensor Integration | Fingerprint-on-card modules absorb demand from border control agencies and high-value payment segments. |
| REACH-Compliant Material Reformulation | ECHA-certified polycarbonate stacks maintain access to German and French government credential contracts. |
| Multi-Application Platform Development | Converged transit-payment credentials capture procurement volumes from China's municipal infrastructure scaling. |
Research Approach
Document review covered EMVCo specification releases, ETSI interoperability mandates, and ECHA substance evaluations, complemented by interviews with secure element procurement managers at card manufacturers, transit authority technical directors, EMVCo laboratory certification leads, and polycarbonate substrate suppliers. Secondary validation drew from ISO/IEC standards documentation, FIPS 140-2 certification records, and customs trade data for secure element chip imports. Bottom-up unit shipment estimates from credential deployments across payment, transit, and government segments were cross-referenced against top-down semiconductor foundry capacity allocations.
Historical deployment trajectories in London, Singapore, and Shenzhen were cross-referenced against panel input from procurement directors at major transit authorities and payment network compliance officers. Segmentation modeling spanned card type architecture, protocol technology, end-use application, and institutional buyer category across the analysis window. CAGRs were derived from trend extrapolation of certification-driven replacement cycles and infrastructure convergence patterns. Forecast inputs incorporated ETSI mandate implementation schedules and RBI contactless expansion timelines for tier-two Indian cities.
Caveats apply where post-quantum cryptography standard finalization delays or East Asian foundry capacity constraints could materially shift the outlook for hardware refresh demand. Forecasts reflect assumptions about regulatory compliance timelines and transit infrastructure investment continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Cloud Encryption Software Market
Security Software
North America Secure Access Service Edge Market
Security Software
Sound Masking Systems Market
Security Software
Europe Encryption Software Market
Security Software
Software Protection Dongle Market
Security Software
Source Code Escrow Market
Security Software
Mobile Identity Management Market
Security Software
Security Information and Event Management Software Market
Security Software
Italy Endpoint Detection and Response Market
Security Software
Cybersecurity Software Market
Security Software
Asia Pacific Anti Money Laundering Solutions Market
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Hardware Encryption Market
Security Software
Content Protection and Watermarking Market
Security Software
Parental Control Software Market