
 Phone Antivirus Software Market | 2026-2036
Phone Antivirus Software Market Size, Share, and Industry Trends Forecast 2026-2036
Phone Antivirus Software Market Insights
The EU AI Act is expanding the compliance burden for mobile security vendors processing biometric and behavioral data across European devices. Kaspersky leverages its threat intelligence infrastructure to sustain enterprise-grade detection pipelines. Microsoft anchors consumer mindshare through native OS integration, while Palo Alto Networks competes on cloud-delivered mobile endpoint protection for corporate fleets.
Phone antivirus software comprises real-time scanning engines, signature databases, and behavioral monitoring layers designed to detect, quarantine, and neutralize malicious code on smartphone operating systems. These platforms execute continuous file system inspection, network traffic analysis, and application sandboxing to prevent data exfiltration, ransomware deployment, and unauthorized access to sensitive mobile transactions. Subscription-based offerings dominate recurring revenue pools as consumers accept auto-renewing protection models, while behavioral detection technology captures the fastest expansion trajectory as zero-day threats outpace signature-dependent approaches. Enterprise end users command premium pricing tiers due to mobile device management integration requirements and centralized policy enforcement.
The EU AI Act, GDPR, and ISO 27001 standards collectively reshape product architecture by mandating algorithmic transparency, data minimization protocols, and certified information security management systems for vendors serving regulated industries. The FCC in the United States and India's TRAI impose additional notification and consent frameworks around mobile data collection that antivirus platforms must embed. Stakeholders should monitor how fragmented sovereignty requirements across the European Union, United States, and India force architectural divergence in data routing and threat intelligence sharing.
Market Dynamics
Behavioral detection architectures are displacing signature-dependent scanning as zero-day mobile threats accelerate faster than database updates can propagate, forcing vendors to re-engineer core detection pipelines around on-device machine learning inference.
Growth Catalysts
- GDPR Article 32 mandates:Organizations processing biometric data on European smartphones must deploy encryption and breach detection capabilities, expanding enterprise security budgets.
- Mobile banking penetration:Financial services firms in India and Germany are mandating certified antivirus deployment for customer-facing transaction applications.
- On-device AI inference:Neural processing units in mid-tier smartphones now support real-time behavioral analysis without cloud latency.
Market Restraints
- Threat intelligence concentration:Three jurisdictions control the majority of high-fidelity mobile malware feeds, creating supply vulnerability.
- EU AI Act compliance costs:Algorithmic transparency requirements for behavioral detection engines impose documentation burdens that inflate R&D overhead.
- OS-native security substitution:Apple and Google are embedding scanning capabilities that reduce perceived need for third-party installation.
Strategic Opportunities
- TRAI data localization rules:India's mandate for domestic threat intelligence storage creates opening for locally-hosted security platforms.
- Zero-trust mobile architecture:Convergence of endpoint detection with identity verification is opening unified security procurement budgets.
- Small and medium enterprise gap:Underpenetrated German Mittelstand firms lack dedicated mobile security operations, creating managed service potential.
Industry Challenges
- ML model optimization talent:Scarce engineers capable of shrinking behavioral detection models to run within smartphone battery constraints.
- Multi-jurisdiction certification timelines:ISO 27001, SOC 2, and national encryption approvals create 14-18 month product launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phone Antivirus Software Market |
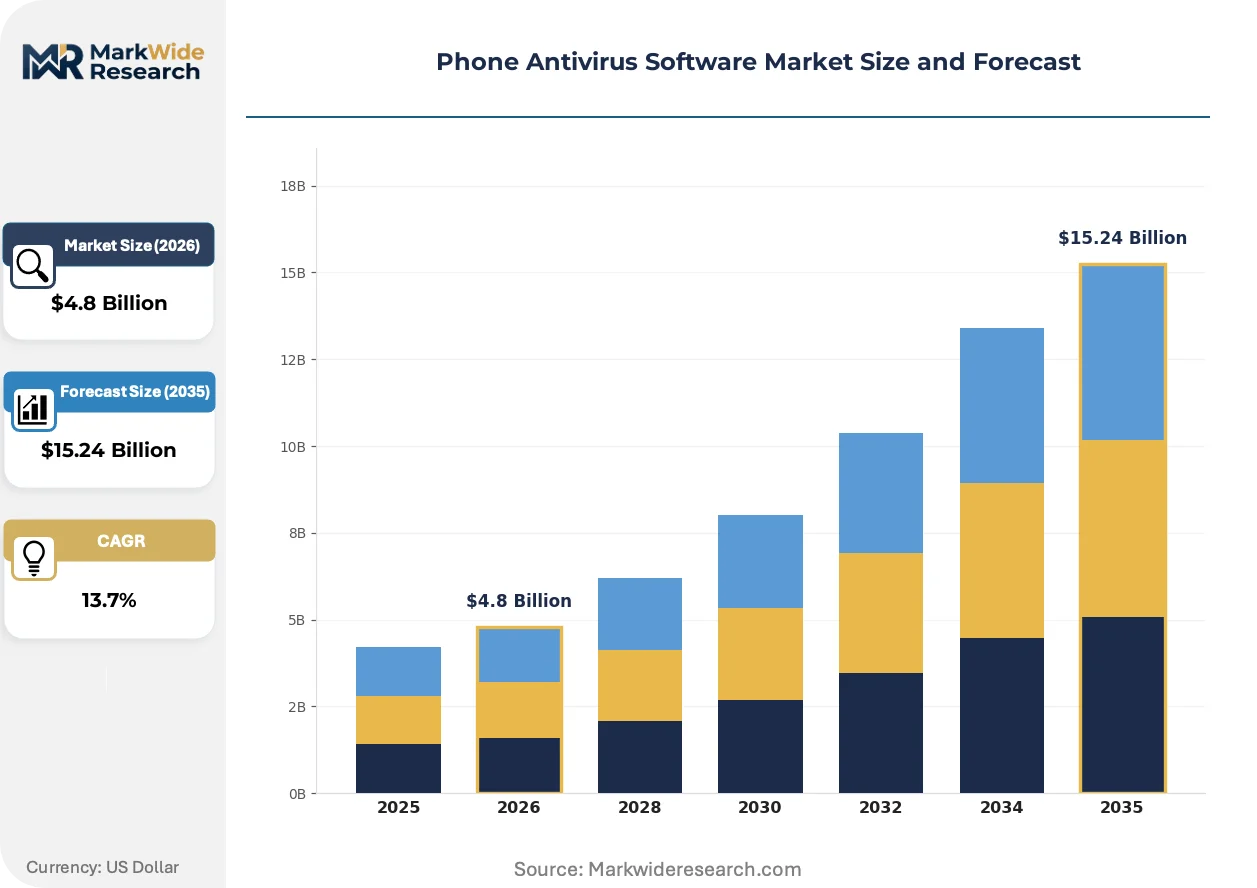
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Free, Subscription-Based, Premium, Enterprise Deployment: Cloud-Based, On-Premises, Hybrid, Local End User: Individual Users, Small Businesses, Corporations, Educational Institutions Technology: Machine Learning, Signature-Based, Heuristic Analysis, Behavioral Detection |
| Companies Covered | Kaspersky, Quick Heal, Bitdefender, SentinelOne, K7 Computing, Microsoft, Sophos, Palo Alto Networks, Trend Micro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phone Antivirus Software Market Trends and Innovations
Detection methodology is pivoting from reactive signature matching to predictive behavioral modeling, while regulatory fragmentation forces architectural specialization by geography.
On-device machine learning inference is consolidating mobile security architecture by eliminating round-trip latency to cloud analysis servers. Banking applications in India and Germany are deploying these engines to scan transactions without exposing sensitive data to external networks. This compression of the detection stack is reducing vendor dependency on centralized threat intelligence infrastructure.
The EU AI Act is mandating explainability documentation for any algorithm processing biometric or behavioral data on European devices. Vendors must now maintain audit trails showing how detection decisions reach quarantine verdicts. Enterprise procurement teams in Germany are prioritizing platforms with pre-certified algorithmic transparency modules.
Subscription fatigue is altering consumer acquisition economics as smartphone users resist adding recurring security charges to existing streaming and cloud storage bills. Freemium models with feature-gated premium tiers are displacing annual subscription pitches in United States app stores. This behavioral shift is compressing customer lifetime value projections for pure-play antivirus vendors.
Phone Antivirus Software Market Segmentation
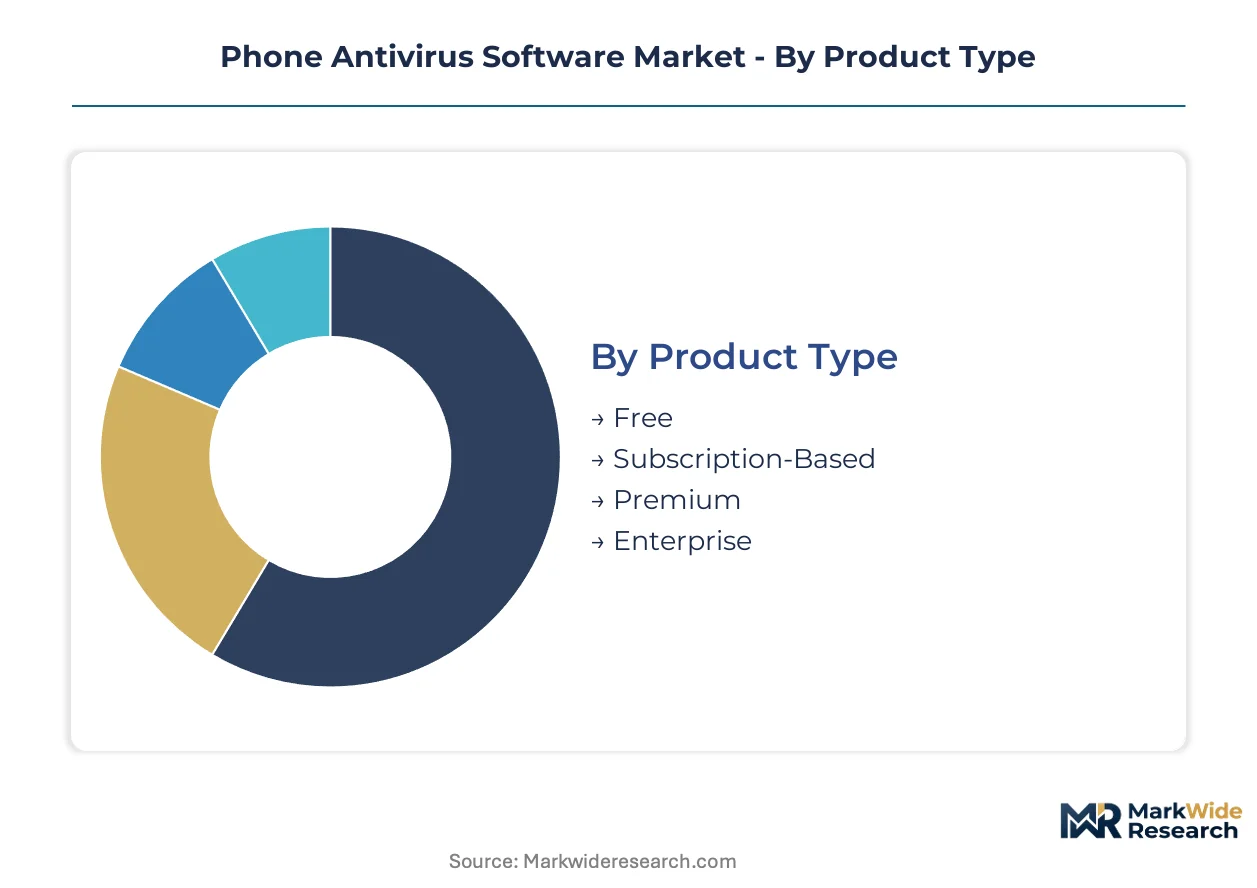
Segmentation in phone antivirus software reveals divergent buyer priorities across consumer, enterprise, and institutional channels. Pricing tolerance, deployment complexity, and detection methodology preferences split procurement patterns across these dimensions.
Product Type:
Cost tier determines acquisition friction and lifetime value potential across consumer and enterprise segments.
- Free:Ad-supported or feature-limited tiers build user bases for upsell conversion. Individual users in India and Germany accept functional constraints in exchange for baseline protection against banking trojans.
- Subscription-Based:Auto-renewing monthly or annual plans dominate recurring revenue architecture. Small businesses in the United States favor predictable budgeting over capital expenditure models.
- Premium:Identity theft insurance and VPN bundling differentiate paid consumer tiers. German Mittelstand firms purchase premium family plans for device fleet coverage.
- Enterprise:Mobile device management integration and centralized policy enforcement command pricing multiples. Financial services corporations in India mandate certified deployment for regulatory compliance.
Volume sits with Subscription-Based tiers; growth tilts toward Enterprise as mobile banking compliance requirements expand.
Deployment:
Latency sensitivity and data sovereignty rules shape infrastructure choices across regulated industries.
- Cloud-Based:Threat intelligence updates propagate instantly without device storage constraints. Corporations in the United States prioritize cloud delivery for distributed workforce protection.
- On-Premises:Dedicated hardware within enterprise data centers satisfies air-gapped security requirements. German financial institutions deploy on-premises scanning to satisfy GDPR data localization mandates.
- Hybrid:Split processing between edge devices and centralized servers balances speed with depth. Educational institutions in India adopt hybrid models to manage heterogeneous device populations.
- Local:Fully offline operation eliminates external data transmission entirely. Individual users in remote geographies rely on local deployment where connectivity is intermittent.
Commercial momentum clusters around Hybrid architectures; strict compliance environments sustain On-Premises demand.
End User:
Security maturity and procurement sophistication segment buyer behavior across the customer spectrum.
- Individual Users:Consumer-grade protection prioritizes one-tap installation and minimal configuration. App store ratings drive selection in the United States and Germany.
- Small Businesses:Managed service attachment replaces direct security operations. Indian small businesses lack dedicated IT staff and favor bundled telecommunications offerings.
- Corporations:Integration with existing endpoint detection and response stacks dominates evaluation criteria. Zero-trust architecture adoption in German enterprises is opening unified procurement budgets.
- Educational Institutions:Volume licensing and student privacy regulations shape purchasing. Indian universities face TRAI data localization requirements for campus device management.
Corporations anchor current revenue; Educational Institutions are climbing fastest as digital learning expands device density.
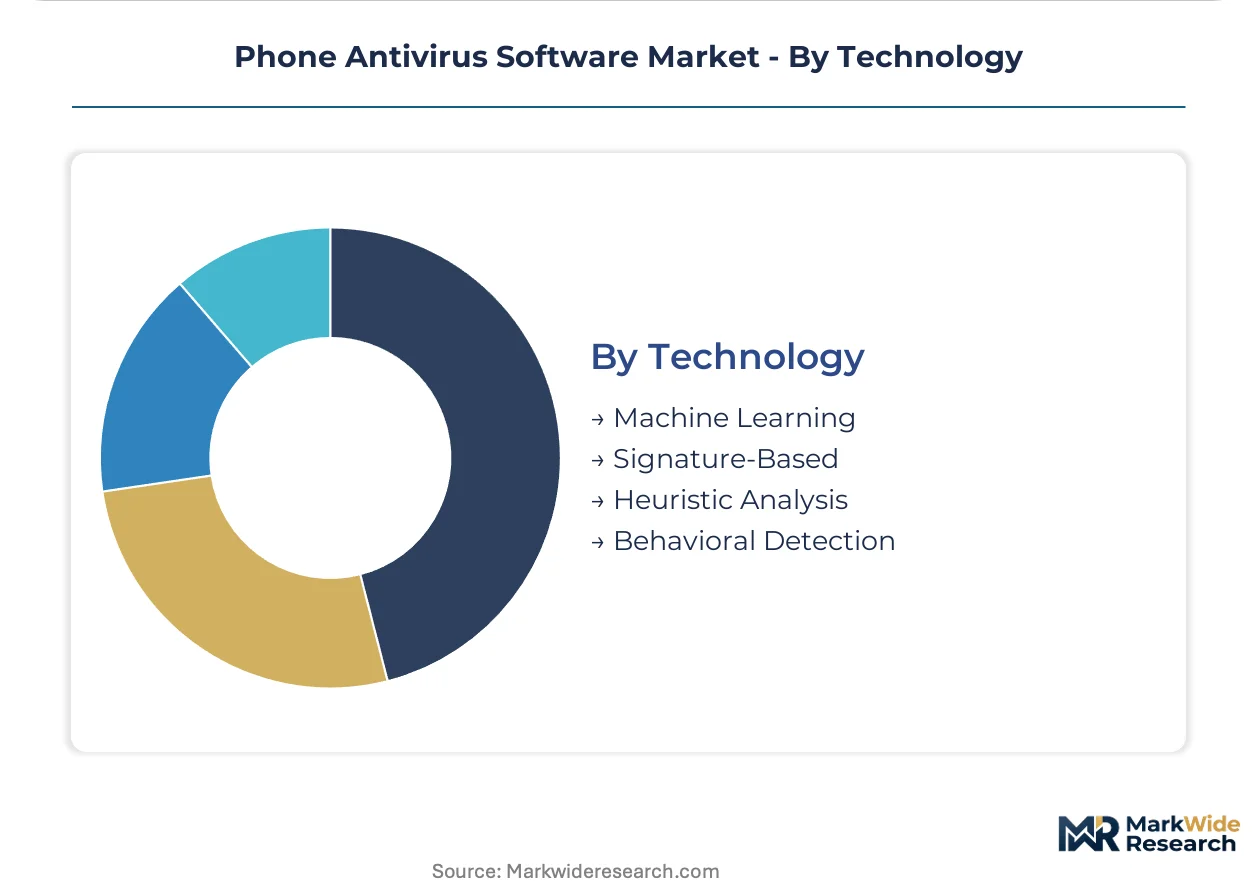
Technology:
Detection efficacy against evolving threat vectors determines competitive differentiation in core product architecture.
- Machine Learning:Neural models trained on malware corpora enable zero-day identification without signature updates. On-device inference in mid-tier smartphones eliminates cloud latency for Indian banking applications.
- Signature-Based:Hash matching against known malware databases delivers deterministic blocking with minimal false positives. Legacy deployments in the United States sustain this approach for baseline protection.
- Heuristic Analysis:Rule-based behavioral pattern matching identifies suspicious code structures without prior exposure. Small businesses favor heuristic methods for balanced resource consumption.
- Behavioral Detection:Real-time monitoring of application actions and network traffic reveals anomalous activity. EU AI Act documentation requirements are reshaping German enterprise procurement priorities toward explainable behavioral systems.
Signature-Based methods retain installed base dominance; Behavioral Detection is gaining share fastest as zero-day volume accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru anchors mobile security development activity, with Whitefield and Electronic City corridors hosting behavioral detection engineering centers serving Indian banking applications. The city's concentration of neural processing talent feeds on-device ML inference pipelines for smartphone antivirus platforms.
United States
Financial services firms in Manhattan and San Francisco drive enterprise mobile endpoint protection procurement for distributed workforce security. FCC notification frameworks govern data collection consent requirements for antivirus platforms serving American consumers. Seattle hosts cloud-delivered security engineering clusters where Microsoft anchors consumer mindshare through native OS integration advantages.
Germany
Mittelstand manufacturing firms across Bavaria and Baden-Württemberg are mandating certified antivirus deployment for mobile banking compliance. EU AI Act algorithmic transparency requirements reshape procurement priorities toward explainable behavioral detection systems. Frankfurt's financial district concentrates enterprise security operations centers integrating mobile device management with zero-trust architecture.
India
TRAI data localization mandates push domestic threat intelligence storage requirements for smartphone security vendors. Mumbai and Delhi-NCR banking corridors deploy on-device ML inference to scan transactions without external network exposure. Hyderabad's cybersecurity research institutes supply compressed behavioral detection models optimized for mid-tier smartphone battery constraints.
United Kingdom
London's fintech cluster demands mobile banking protection meeting GDPR Article 32 encryption and breach detection standards. The Information Commissioner's Office enforces consent frameworks around biometric data processing on British devices. Cambridge security research groups contribute heuristic analysis methodologies to European threat detection pipelines.
Phone Antivirus Software Market Competitive Landscape
The competitive structure tilts toward diversified cybersecurity conglomerates with endpoint protection heritage. Tier-one positions concentrate among vendors with threat intelligence infrastructure spanning multiple jurisdictions. Three archetypes dominate: native platform integrators leveraging OS distribution advantages, enterprise-focused specialists commanding premium pricing through MDM integration, and regional champions exploiting data sovereignty requirements. Competitive moves center on cloud architecture expansion and behavioral detection engine acquisitions.
Within the enterprise-specialist tier, Palo Alto Networks and SentinelOne occupy positions emphasizing cloud-delivered mobile endpoint protection for corporate fleets. Kaspersky anchors the threat intelligence archetype with infrastructure sustaining detection pipeline operations across European and Asian markets. Quick Heal and K7 Computing exemplify regional champions serving data localization mandates in South Asian jurisdictions. Microsoft represents the native integration archetype through embedded OS security capabilities that reshape consumer acquisition economics.
| Leading Market Players |
|---|
| Kaspersky |
| Quick Heal |
| Bitdefender |
| SentinelOne |
| K7 Computing |
| Microsoft |
| Sophos |
| Palo Alto Networks |
| Trend Micro |
| Others |
Pricing and Supply Chain Analysis
EU AI Act algorithmic transparency mandates gate qualified supply for behavioral detection engines and premium-tier pricing access. Vendors lacking certified documentation pipelines face exclusion from German enterprise procurement while compliant platforms command pricing multiples through explainable ML architecture.
Pricing Analysis
Value-based pricing anchored to breach prevention outcomes dominates enterprise tiers, with financial services firms in India and Germany paying premiums for transaction-level protection guarantees. Three-tier pricing structure across enterprise, premium consumer, and freemium levels separates MDM-integrated deployments from family plans and ad-supported baselines. Cost compression in consumer subscriptions intensifies because OS-native security substitutes reduce perceived third-party value. Small businesses exhibit highest price sensitivity, while regulated corporations show lowest elasticity due to compliance mandate enforcement.
Supply Chain Analysis
TRAI data localization rules in India and GDPR storage mandates across European Union member states reshape sourcing toward domestic threat intelligence infrastructure. Neural processing unit supply concentrates in Taiwan, South Korea, and United States, feeding on-device ML inference capabilities. Behavioral detection model training draws from labeled malware corpora, cloud compute clusters, and specialized ML optimization talent pools. Single-source vulnerability runs through concentrated NPU foundry capacity. Distribution runs through direct enterprise sales, telecommunications bundling, and app store marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ML model optimization talent scarcity props pricing for qualified behavioral detection pipelines. Certified engineering capacity constraints sustain vendor margin structures despite consumer-tier pressure.
For Market Incumbents: Acquire compressed behavioral detection model libraries optimized for mid-tier smartphone battery constraints. Kaspersky and Palo Alto Networks should deepen upstream control over threat intelligence feeds to offset single-source jurisdiction vulnerability. Certification investment in EU AI Act documentation pipelines defends enterprise positioning against emerging cloud-native entrants. For New Entrants and Emerging Players: Begin with managed security service offerings targeting German Mittelstand firms lacking dedicated mobile security operations. White-space concentration sits in hybrid deployment architectures for Indian educational institutions facing TRAI data localization requirements. Channel partnership with domestic telecommunications carriers provides lowest-friction customer acquisition in price-sensitive South Asian consumer segments. For Investors and Strategic Acquirers: Enterprise procurement teams prioritizing pre-certified algorithmic transparency modules is the leading indicator that explainable behavioral detection platforms will capture premium pricing expansion. Long-term viability favors vendors with vertically integrated threat intelligence infrastructure spanning multiple jurisdictions. Target acquisition archetype: regional champions with established data localization compliance serving India or European Union markets.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Behavioral Detection Firm | Compressed ML models for on-device inference address EU AI Act latency requirements without cloud exposure. |
| Geographic Expansion into TRAI-Compliant Infrastructure | Domestic threat intelligence storage in India satisfies data localization mandates for banking corridor deployment. |
| Platform Integration with Mobile Device Management Stacks | Unified zero-trust procurement budgets in German enterprises favor consolidated endpoint protection vendors. |
| Strategic Partnership with Neural Processing Unit Suppliers | Taiwanese and South Korean NPU allocation secures on-device ML pipeline capacity for mid-tier smartphone targeting. |
| Product Launch of Freemium Tier with VPN Bundling | Feature-gated conversion architecture counters subscription fatigue in United States consumer app stores. |
Research Methodology
Document review covered SEC filings from cybersecurity vendors, TRAI regulatory notifications, EU AI Act implementation guidance, and hyperscaler mobile security capex disclosures, complemented by interviews with CTOs at financial services firms, IT procurement officers in German manufacturing, platform engineers at Indian telecommunications carriers, and integration specialists serving educational institutions. Secondary validation drew from app store analytics databases, mobile threat intelligence feeds, and ISO 27001 certification registries. Bottom-up device deployment estimates triangulated against top-down enterprise security spending surveys.
Cross-referencing historical mobile banking adoption curves with panel input from security procurement committees anchored volume projections across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user organization size, detection technology type, and regional regulatory cluster. CAGRs derived from slope-consistency checks against smartphone penetration trajectories and mobile transaction volume expansion. Industry-specific inputs encompassed NPU availability forecasts and multi-jurisdiction certification timeline data.
Underlying measurement precision varies by segment; enterprise deployment figures carry tighter precision than individual consumer adoption estimates. Forecasts reflect assumptions around regulatory enforcement continuity, threat actor sophistication trajectories, and OS-native security capability advancement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Doorbell Camera Market
Security Software
Software Protection Dongle Market
Security Software
AD-Blocking Software Market
Security Software
Anomaly Detection Market
Security Software
North America Video Management System Market
Security Software
Device Vulnerability Management Market
Security Software
Global Security Orchestration Automation and Response (SOAR) Market
Security Software
Latin America Fraud Detection and Prevention Market
Security Software
Mobile Security Market
Security Software
Global Software-Defined Security Market
Security Software
Security Information and Event Management (SIEM) Market
Security Software
Europe Smart Doorbell Market
Security Software
Secure Flash Drive Market
Security Software
Battery-Powered Doorbell Camera Market
Security Software
Global Dynamic Application Security Testing Market
Security Software
Home Webcam Market