
 Direct Thermal Inks and Coating Market | 2026-2036
Direct Thermal Inks and Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Thermal Inks and Coating Market Outlook
Specialized formulator expertise is redrawing competitive boundaries in direct thermal chemistry. Flint Group leverages its pigment dispersion capabilities to sustain premium positioning in European label markets. Siegwerk Druckfarben anchors global supply through water-based thermal ink portfolios that comply with food-contact frameworks. Sun Chemical Corporation differentiates via UV-curable thermal coatings that reduce energy curing costs for high-speed presses.
Direct thermal inks and coatings comprise leuco dye-developer systems or pigmented receptor layers that undergo color change upon localized heat application, typically activated at temperatures between 60°C and 150°C by thermal printheads. These formulations serve commercial and industrial purposes where on-demand, maintenance-free marking replaces ribbon-fed or inkjet alternatives. Water-based thermal inks occupy the volume leadership position across labeling applications, while UV-curable coatings capture expanding share in premium packaging where rub resistance and gloss retention command price premiums. Solvent-based systems retain niche dominance in textile manufacturing transfer papers where substrate compatibility requirements resist aqueous substitution.
EPA oversight of volatile organic compound emissions constrains solvent-based thermal coating formulations in United States manufacturing facilities. ECHA REACH registrations govern leuco dye chemistries entering European converter supply chains, while FDA food-contact notifications determine which thermal receptor coatings may contact packaged consumables. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as legacy grease-resistant thermal barrier coatings face substitution pressure across multiple regulatory jurisdictions.
Market Dynamics
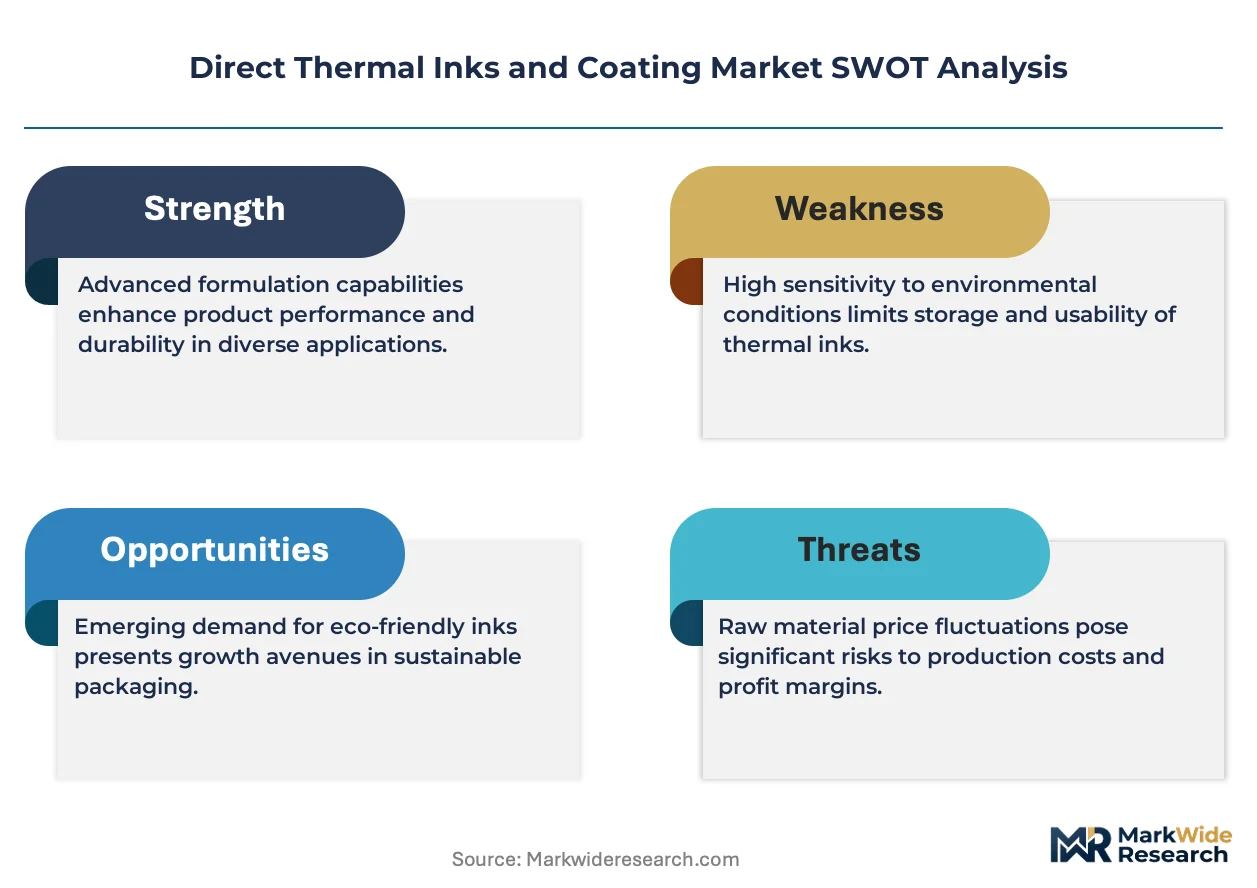
Water-based thermal ink formulations are capturing procurement volume from solvent systems as EPA VOC enforcement tightens and European REACH registrations restrict legacy chemistries, forcing converters to requalify coating portfolios.
Growth Catalysts
- E-commerce fulfillment labeling:Parcel sortation hubs in Germany and the Netherlands deploy direct thermal printers for last-mile tracking labels, driving ink procurement volumes at narrow-web converters.
- REACH substance restrictions:ECHA's evolving candidate list for SVHCs is accelerating substitution of bisphenol-A developer systems with alternative phenolic chemistries in European supply chains.
- Food-contact compliance:FDA notifications for thermal coatings in direct contact with fatty foods are opening shelf-ready meat and dairy packaging applications previously blocked by migration limits.
Market Restraints
- Leuco dye supply concentration:Three Japanese and Chinese chemical manufacturers control over 70% of crystal violet lactone and fluoran dye output, creating input vulnerability for Western formulators.
- UV-curable coating cost structure:Photoinitiator and oligomer prices remain elevated versus water-based alternatives, limiting adoption in cost-sensitive logistics labeling segments.
- Thermal paper substitution:Digital receipt and mobile ticketing platforms are compressing demand for traditional POS roll coatings in retail banking and transit verticals.
Strategic Opportunities
- Pharmaceutical serialization mandates:India's track-and-trace regulations under CDSCO are creating demand for high-resolution thermal barcodes on secondary packaging.
- Dual-carbon packaging goals:China's MIIT guidelines favoring solvent-free coating processes are accelerating water-based thermal ink qualification at domestic folding carton converters.
- Near-field communication integration:Hybrid labels combining printed antennas with thermal imaging layers are emerging in smart pharmaceutical packaging, requiring specialized receptor coating adhesion properties.
Industry Challenges
- Food-contact migration testing:Extended FDA extraction studies for new thermal coating chemistries add 18-24 months to product launch timelines, compressing R&D return windows.
- Printhead compatibility validation:OEM-specific thermal pulse profiles require formulators to maintain multiple coating viscosity grades, fragmenting production runs and complicating inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Thermal Inks and Coating Market |
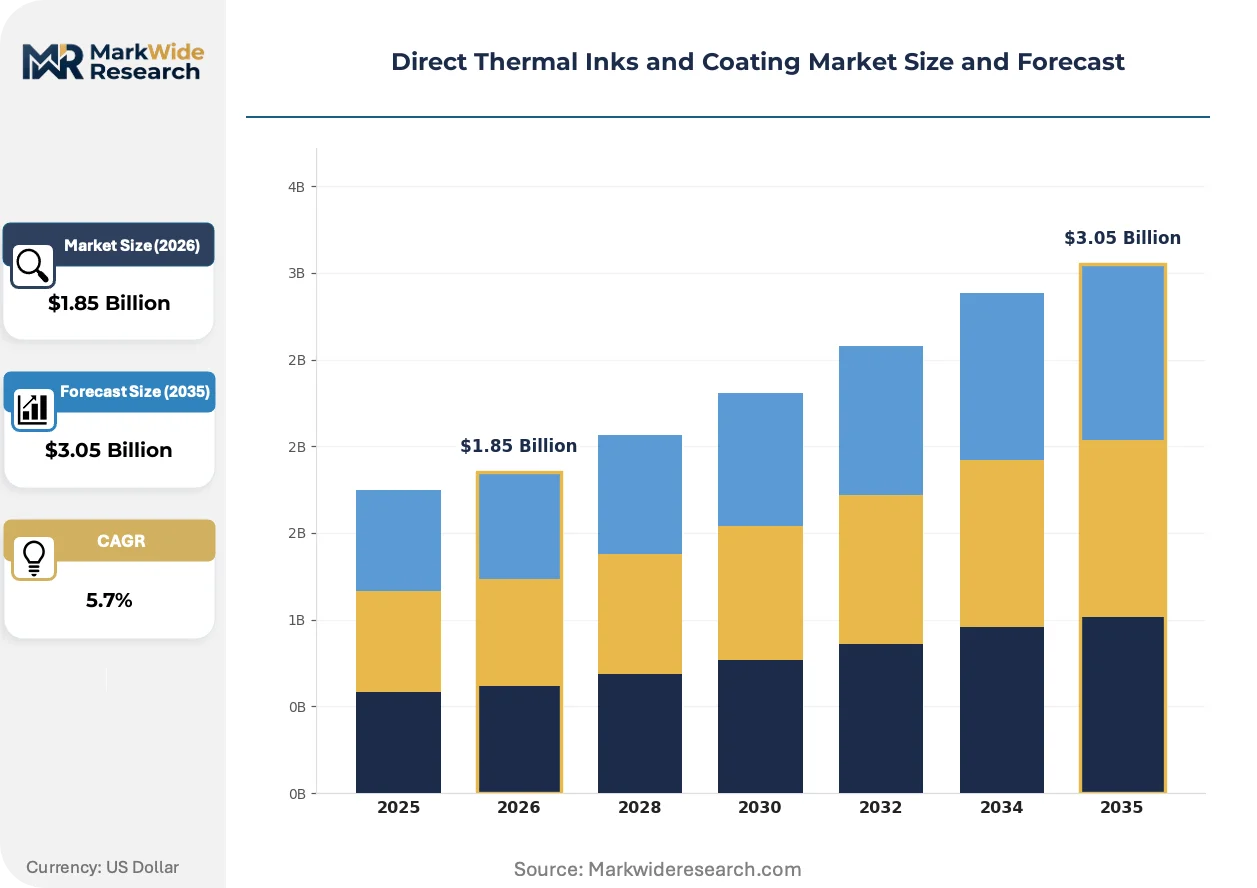
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
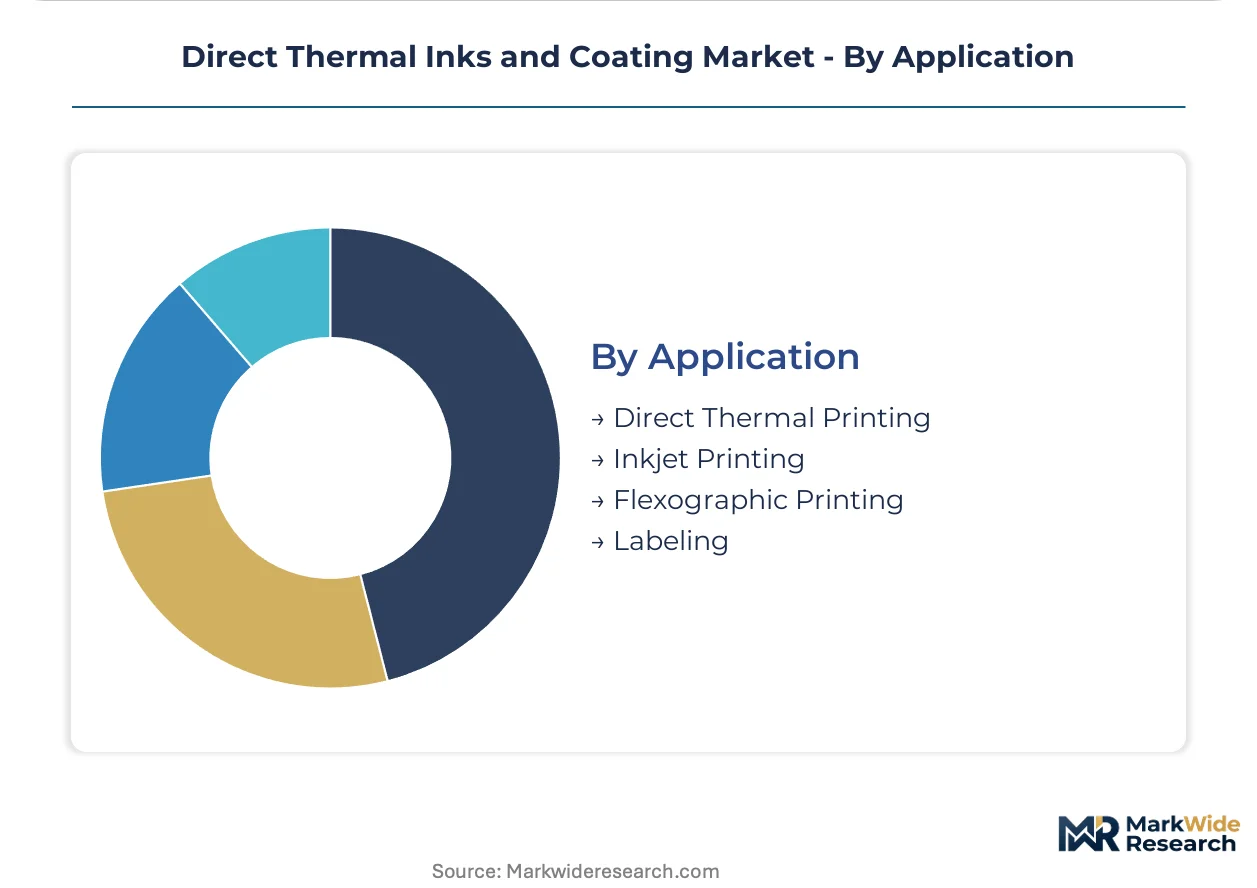
| Segmentation | Product Type: Inks, Coatings, Pigments, Dyes End User: Packaging Industry, Labeling Solutions, Textile Manufacturing, Food and Beverage Technology: Water-Based, Solvent-Based, UV-Curable, Hot Melt Application: Direct Thermal Printing, Inkjet Printing, Flexographic Printing, Labeling |
| Companies Covered | Flint Group, Siegwerk Druckfarben AG & Co. KGaA, ALTANA Coatings, Interactive Inks & Coatings, Sun Chemical Corporation, Ricoh Company, Oji Holdings, UPM Raflatac, DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Thermal Inks and Coating Market Strategic Shifts
Phenol-free developer systems, regulatory migration testing automation, and digital procurement platforms are restructuring how thermal coating specifications reach converter production floors.
Water-based phenol-free thermal coatings are displacing bisphenol-A developer systems in European retail receipt applications. German supermarket chains and French pharmacy networks now mandate phenol-free specifications in supplier tenders. This chemistry shift is compressing legacy formulation margins while rewarding early movers with locked-in annual volumes.
REACH Annex XIV authorization requirements for dibutyl phthalate and other plasticizer chemistries are forcing reformulation of thermal receptor layer binders. Coating manufacturers serving the European market must resubmit technical dossiers for modified acrylic and polyurethane dispersions. The textile transfer paper segment faces particular disruption as legacy solvent-based binders lose registration status.
Converter procurement teams are consolidating thermal ink suppliers to reduce qualification overhead. Large label converters in the United States now run competitive reverse auctions for annual coating volumes, replacing relationship-based purchasing. This behavior is most visible in the logistics labeling vertical, where 3PL providers centralize specifications across multiple regional print facilities.
Direct Thermal Inks and Coating Market Segmentation
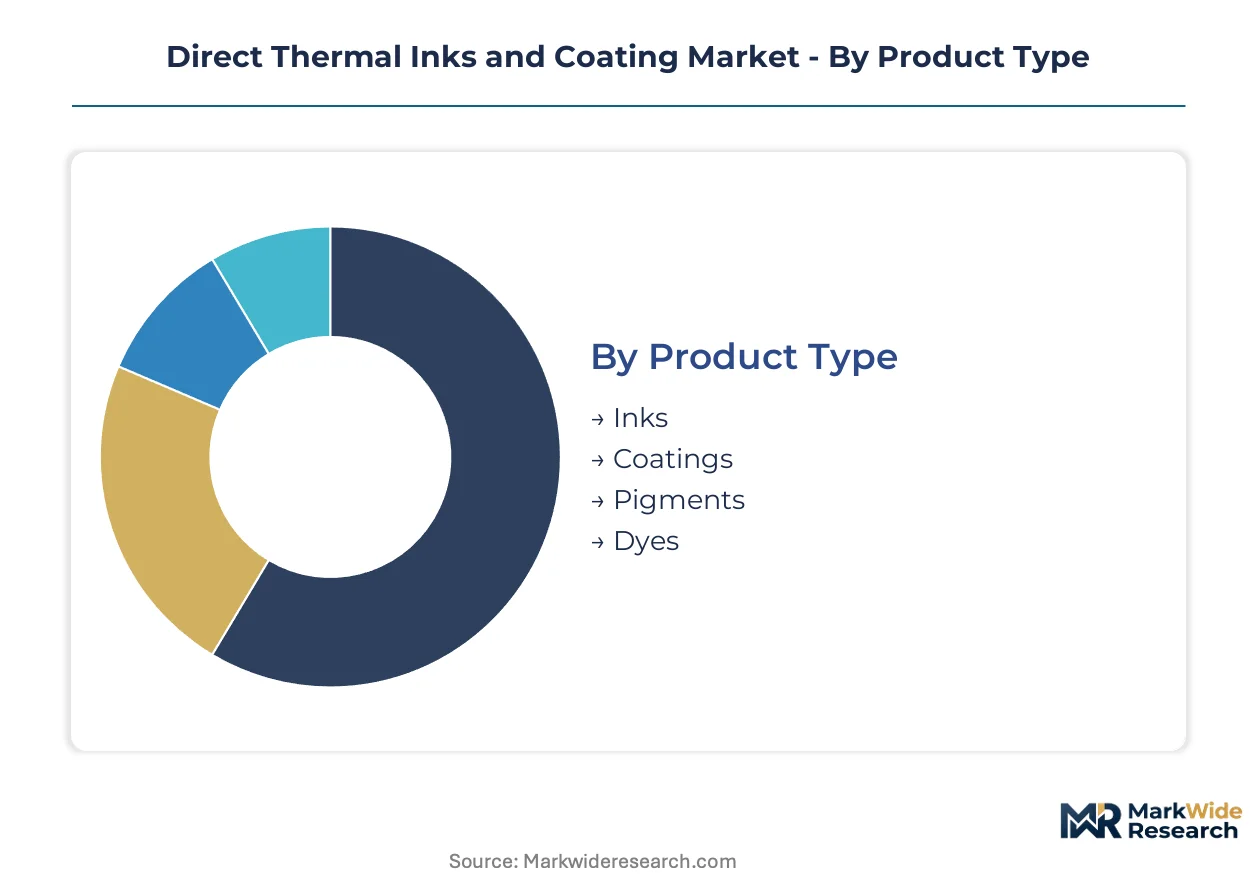
Segmentation in direct thermal chemistry reveals where substitution pressure concentrates and where regulatory compliance creates premium tiering. Understanding these fault lines guides procurement strategy and R&D allocation across converter supply chains.
Product Type:
Substitution pressure from digital receipt platforms and mobile ticketing is compressing demand for traditional coating categories while elevating specialized ink formulations.
- Inks:Leuco dye-developer systems activate at 60°C to 150°C through thermal printhead pulses. Water-based formulations dominate procurement volumes in German narrow-web flexo operations as EPA VOC enforcement tightens.
- Coatings:Phenol-free receptor layers are displacing bisphenol-A systems in European retail receipt applications. French pharmacy networks and German supermarket chains now mandate these specifications in supplier tenders.
- Pigments:Crystal violet lactone and fluoran derivatives face supply concentration risk from Japanese and Chinese chemical manufacturers controlling over 70% of global output.
- Dyes:Alternative phenolic chemistries are gaining qualification as ECHA REACH restrictions accelerate substitution timelines for legacy developer systems.
Inks retain volume leadership; coatings hold the steepest expansion curve as food-contact compliance opens new packaging applications.
End User:
Cost tier differentiation separates commodity logistics labeling from premium food-contact and pharmaceutical applications with stringent migration testing requirements.
- Packaging Industry:Shelf-ready labels with scannable barcodes drive procurement at brand owners demanding on-demand marking without ribbon-fed alternatives. FDA notifications for fatty food contact are unlocking meat and dairy segments previously blocked by migration limits.
- Labeling Solutions:Parcel sortation hubs in Germany and the Netherlands deploy direct thermal printers for last-mile tracking. 3PL providers centralize specifications across multiple regional print facilities.
- Textile Manufacturing:Solvent-based systems retain niche dominance in transfer papers where substrate compatibility resists aqueous substitution. REACH Annex XIV authorization requirements for plasticizer chemistries are forcing binder reformulation.
- Food and Beverage:Extended FDA extraction studies add 18-24 months to product launch timelines for new thermal coating chemistries, compressing R&D return windows.
Labeling Solutions generates the highest procurement volumes; Food and Beverage is climbing the fastest as compliance barriers fall.
Technology:
Supply concentration in photoinitiator and oligomer inputs is constraining cost-competitiveness of premium curing systems versus aqueous alternatives.
- Water-Based:Volume leadership position across labeling applications. China's MIIT guidelines favoring solvent-free processes are accelerating qualification at domestic folding carton converters.
- Solvent-Based:EPA oversight of VOC emissions constrains formulations in United States manufacturing facilities. Textile transfer papers face particular disruption as legacy binders lose REACH registration status.
- UV-Curable:Rub resistance and gloss retention command price premiums in premium packaging. Photoinitiator prices remain elevated versus water-based alternatives, limiting adoption in cost-sensitive logistics segments.
- Hot Melt:Specialized adhesion properties serve hybrid labels combining printed antennas with thermal imaging layers in smart pharmaceutical packaging.
Water-Based maintains procurement dominance; UV-Curable is gaining share fastest in premium segments where performance justifies cost premiums.
Application:
Customer type fragmentation between high-speed press operators and maintenance-free marking environments is reshaping formulation specifications.
- Direct Thermal Printing:Localized heat application replaces ribbon-fed or inkjet alternatives in commercial and industrial marking. OEM-specific thermal pulse profiles require formulators to maintain multiple coating viscosity grades.
- Inkjet Printing:Competing marking technology is compressing demand for traditional POS roll coatings in retail banking and transit verticals through digital receipt substitution.
- Flexographic Printing:Narrow-web press investments in Germany drive ink procurement volumes as converters expand production capacity.
- Labeling:India's CDSCO track-and-trace regulations are creating demand for high-resolution thermal barcodes on pharmaceutical secondary packaging.
Direct Thermal Printing anchors procurement volumes; Labeling is expanding most quickly under serialization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH registrations govern leuco dye chemistries entering European converter supply chains, while FDA food-contact notifications determine permissible thermal receptor coatings in packaged consumables across the United States. National regulators in Asia-Pacific jurisdictions are accelerating solvent-free coating qualifications through industrial policy mandates.
Germany
Narrow-web flexo press investments by label converters drive ink procurement volumes in Baden-Württemberg and North Rhine-Westphalia. KBA equipment specifications influence formulator coating viscosity grades for OEM thermal pulse profiles. The Stuttgart industrial cluster hosts multiple converter facilities requalifying water-based portfolios under tightened VOC thresholds.
United States
EPA enforcement of volatile organic compound emissions constrains solvent-based thermal coating formulations in manufacturing facilities. FDA notifications for fatty food contact are unlocking meat and dairy packaging applications previously blocked by migration limits. Chicago-area logistics hubs deploy direct thermal printers for parcel sortation, driving coating demand at regional label converters.
China
MIIT guidelines favoring solvent-free coating processes accelerate water-based thermal ink qualification at domestic folding carton converters. Dual-carbon packaging goals under national industrial policy pressure legacy chemistries. The Yangtze River Delta concentration of packaging manufacturers leads qualification timelines for phenol-free developer systems.
India
CDSCO track-and-trace regulations create demand for high-resolution thermal barcodes on pharmaceutical secondary packaging. Maharashtra and Gujarat host converter investments targeting serialization mandates for export markets. Mumbai-Pune industrial corridor facilities are expanding thermal coating capacity for domestic and international pharma label supply.
Japan
METI industrial standards influence thermal printhead compatibility specifications across Asia-Pacific supply chains. Japanese chemical manufacturers control substantial crystal violet lactone and fluoran dye output, creating supply concentration for Western formulators. Osaka-Kobe chemical industry cluster maintains leuco dye production capacity serving global thermal coating demand.
Direct Thermal Inks and Coating Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in direct thermal chemistry supply. The upper tier commands pigment dispersion capabilities and regulatory dossier depth that smaller formulators cannot replicate. Three strategic archetypes dominate: pigment-integrated multinationals, water-based food-contact specialists, and UV-curable coating innovators. Competitive moves concentrate on portfolio diversification into phenol-free formulations and strategic partnerships with narrow-web press OEMs for printhead compatibility validation.
Among European-anchored formulators, Flint Group and Siegwerk Druckfarben AG & Co. KGaA occupy positions reflecting pigment integration depth and water-based regulatory expertise respectively. Sun Chemical Corporation represents the UV-curable tier where rub resistance specifications command price premiums. These three exemplify how coating manufacturers align chemistry portfolios with diverging end-use compliance requirements across FDA food-contact and ECHA REACH frameworks.
| Leading Market Players |
|---|
| Flint Group |
| Siegwerk Druckfarben AG & Co. KGaA |
| ALTANA Coatings |
| Interactive Inks & Coatings |
| Sun Chemical Corporation |
| Ricoh Company |
| Oji Holdings |
| UPM Raflatac |
| DIC Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Japanese and Chinese leuco dye manufacturers shapes price floors for Western formulators while compressing margins on legacy bisphenol-A formulations. Scale concentration in crystal violet lactone production tightens input cost predictability and amplifies procurement leverage for integrated pigment producers serving European label converters.
Pricing Analysis
European water-based thermal inks trade at premiums to Asia-Pacific spot equivalents due to REACH compliance certification costs and KBA equipment validation requirements. Three-tier pricing structure across food-contact certified, industrial-grade, and economy logistics tiers separates pharmaceutical serialization coatings from commodity parcel labels. Cost compression in standard logistics grades is intensifying because 3PL reverse auctions consolidate annual volumes at narrow-web converters. Parcel sortation operators exhibit highest price sensitivity; meat and dairy packaging brand owners accept certified-premium tiers for FDA fatty-food contact compliance.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains just-in-time delivery of fluoran dye precursors to German flexo converter facilities. Manufacturing concentrates in Japan, China, and Germany; crystal violet lactone output feeds from Osaka-Kobe chemical clusters while water-based formulation capacity clusters in Baden-Württemberg. Raw material dependencies span leuco dye precursors, phenolic developer alternatives, and acrylic binder dispersions. Single-source vulnerability concentrates in Japanese dye manufacturers controlling over seventy percent of global crystal violet lactone supply. Distribution runs through converter-direct contracts with narrow-web press OEMs qualifying viscosity grades for specific thermal pulse profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment in FDA food-contact notifications and ECHA REACH dossiers creates formidable defensive moats for established formulators. Switching costs escalate as OEM printhead compatibility validation fragments production runs across multiple viscosity specifications.
For Market Incumbents: Compound regulatory dossier depth by accelerating phenol-free developer qualifications ahead of Annex XIV authorization deadlines. Expand backward integration into pigment dispersion capabilities to secure crystal violet lactone supply against Japanese manufacturer concentration. Lock in multi-year contracts with KBA and narrow-web press OEMs to validate proprietary coating viscosity grades and raise rival requalification barriers.
For New Entrants and Emerging Players: Lead with water-based phenol-free formulations targeting Indian pharmaceutical serialization mandates under CDSCO track-and-trace regulations. Penetrate Maharashtra and Gujarat converter investments where domestic folding carton capacity expands for export markets. Anchor go-to-market strategy through technical partnership with Mumbai-Pune industrial corridor facilities seeking solvent-free thermal coating alternatives.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among formulators with locked-in OEM validation cycles and multi-year pharmaceutical serialization contracts. Long-term viability over the projection horizon favors pigment-integrated specialists with captive leuco dye supply and REACH registration depth. Target acquisition archetype: mid-cap European formulators with water-based food-contact expertise and pending FDA notification pipelines. Monitor ECHA SVHC candidate list expansion as inflection signal for accelerated bisphenol-A substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Dispersion | Captive crystal violet lactone supply secures input cost predictability against Japanese manufacturer concentration. |
| Phenol-Free Formulation Launch | REACH Annex XIV compliance unlocks German supermarket and French pharmacy network procurement tenders. |
| OEM Printhead Validation Partnership | KBA thermal pulse profile certification raises rival requalification barriers across narrow-web flexo installations. |
| Indian CDSCO Serialization Qualification | Maharashtra pharmaceutical packaging demand creates high-margin thermal barcode coating volume. |
| Long-Term 3PL Supply Agreement | Centralized logistics labeling specifications across multi-facility parcel sortation networks stabilize annual volumes. |
Study Parameters
A spread of perspectives from narrow-web converter procurement managers, thermal printhead OEM technical directors, pharmaceutical packaging regulatory affairs leads, and leuco dye chemical plant managers converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA food-contact notification databases, ECHA REACH registration dossiers, SEC 10-K filings of coating manufacturers, and German KBA equipment specification sheets. Bottom-up thermal coating volume estimates triangulated against top-down packaging industry consumption models.
Segmentation dimensions modeled span product type, end-use industry, curing technology, and application method across the analysis window. CAGRs derived from regression analysis of historical procurement volumes projected against converter capacity expansion pipelines and regulatory substitution timelines. Forecast inputs incorporated pharmaceutical serialization mandate implementation schedules, MIIT solvent-free process guidelines, and ECHA SVHC candidate list evolution.
The analysis sits within stated boundaries; outcomes outside sustained EPA VOC enforcement, stable ECHA registration frameworks, and continued e-commerce logistics growth would require recalibration. Forecasts reflect assumptions on leuco dye supply concentration persistence and OEM printhead compatibility validation protocols. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Global Anti-Fog Additives Market
Chemicals & Materials
Solar Salt Market
Chemicals & Materials
Asia-Pacific Contact Adhesives Market
Chemicals & Materials
Nickel Superalloy Market
Chemicals & Materials
Paint Rollers Market
Chemicals & Materials
Additives for Metalworking Fluids Market
Chemicals & Materials
Cosmetics Contract Manufacturing Market
Chemicals & Materials
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Chemicals & Materials
Europe Citric Acid Market
Chemicals & Materials
North America Potassium Permanganate Market
Chemicals & Materials
Ocular Adhesives and Sealants Market
Chemicals & Materials
Quenched and Tempered Steel Market
Chemicals & Materials
Asia-Pacific Fluorosilicic Acid Market
Chemicals & Materials
Chemical Hardener Compounds Market
Chemicals & Materials
Global Industrial Foam Market
Chemicals & Materials
Electrostatic Liquid Cleaner Market