
 Glycerol Monostearate Market | 2026-2036
Glycerol Monostearate Market Size, Share, and Industry Trends Forecast 2026-2036
Glycerol Monostearate Market Outlook
Pharmaceutical companies is collapsing the historical dominance of food manufacturers as the primary buyer archetype for glycerol monostearate. Evonik Industries AG anchors its position through captive supply of pharmaceutical-grade emulsifiers across European manufacturing sites. Stepan Company differentiates via backward integration into fatty acid feedstocks that stabilize margin pools amid raw material volatility.
Glycerol monostearate is an ester of glycerin and stearic acid with a typical monoester content of 40-60 percent, functioning as a non-ionic surfactant, emulsifier, and stabilizer across food, pharmaceutical, and cosmetic systems. Food-grade glycerol monostearate dominates volume flows through entrenched demand in baking and confectionery applications where cost efficiency matters more than certification premiums. Pharmaceutical-grade material commands superior margins due to compendial compliance burdens and the concentrated purchasing power of drug manufacturers seeking excipient traceability.
The US FDA excipient guidelines, the EU REACH framework, and India's CDSCO pharmaceutical standards collectively elevate purity thresholds and documentation requirements for market access. These regulatory layers compel producers to maintain dual-track manufacturing protocols, separating food-grade and pharmaceutical-grade streams to avoid cross-contamination liability. Stakeholders must monitor how excipient master file harmonization between FDA and EMA alters competitive positioning for suppliers without pre-existing drug master file portfolios.
Market Dynamics
Pharmaceutical-grade certification requirements are compressing supplier margins while concentrating volume among producers with dual-track manufacturing capabilities. FDA, EMA, and CDSCO alignment on excipient master files is forcing capital deployment toward segregated production lines.
Growth Catalysts
- India's PLI pharmaceutical scheme:Domestic drug manufacturers are expanding capacity under production-linked incentives, pulling glycerol monostearate demand toward Indian excipient distributors.
- FDA excipient guideline updates:Tighter purity thresholds for tablet lubricants are locking out non-compliant suppliers and securing volume for certified producers.
- Sustained-release formulation expansion:Oral dosage form innovation in controlled-release matrices is elevating glycerol monostearate from commodity lubricant to functional excipient.
Market Restraints
- Stearic acid feedstock volatility:Palm oil and tallow price swings transmit directly to glycerol monostearate production economics, compressing margin predictability.
- European supply concentration:REACH-compliant manufacturing clusters in Germany and the Netherlands create geographic vulnerability to energy cost shocks.
- Polyethylene glycol substitution:PEG-based lubricants compete in non-sustained-release applications where certification premiums do not justify glycerol monostearate selection.
Strategic Opportunities
- Brazilian generic pharmaceutical expansion:ANVISA regulatory alignment with ICH standards opens pathway for excipient suppliers to penetrate Latin American drug manufacturing.
- Cosmetic emulsifier premiumization:Clean-label positioning in skincare formulations creates pull for vegetable-derived glycerol monostearate at price points above food-grade material.
- Continuous manufacturing adoption:Pharma facilities integrating direct compression lines require excipient flow properties that favor specific glycerol monostearate morphologies.
Industry Challenges
- Dual-track facility validation:Separating food-grade and pharmaceutical-grade production streams demands redundant quality systems and extended commissioning timelines.
- Excipient master file harmonization gaps:Divergent documentation requirements between FDA and EMA create compliance friction for suppliers seeking multi-regional drug manufacturer contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycerol Monostearate Market |
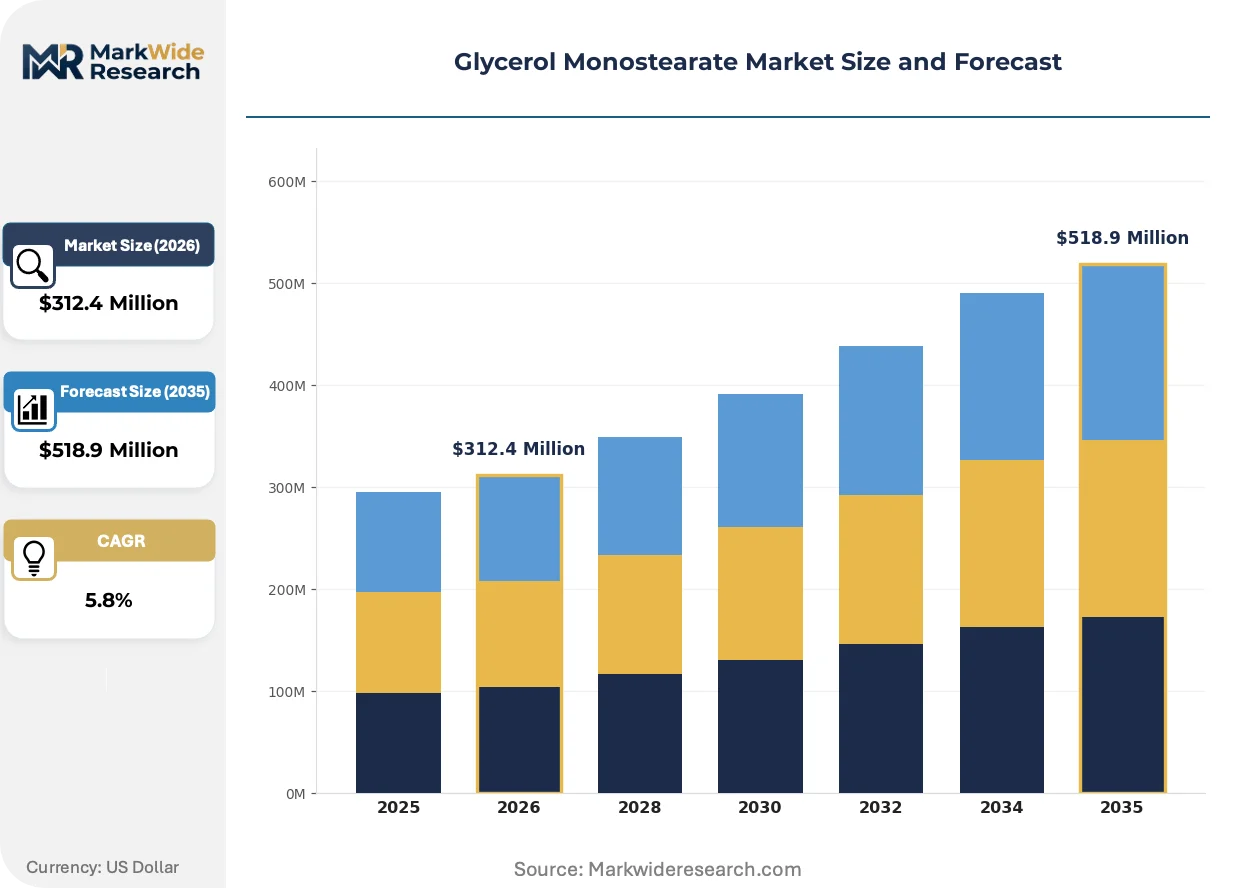
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Baking, Confectionery, Dairy Products, Cosmetics End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Producers, Industrial Users Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | Stepan Company, Lonza Group AG, Wilmar International Limited, Kao Corporation, Evonik Industries AG, BASF SE, Croda International Plc, Palsgaard Malaysia SDN BHD, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycerol Monostearate Market Strategic Shifts
Continuous processing technologies and regulatory convergence are compressing batch-to-batch variability tolerances while elevating traceability requirements across excipient supply chains.
Enzymatic esterification is miniaturizing reactor footprints for glycerol monostearate synthesis. Specialty chemical producers are adopting immobilized lipase systems to reduce solvent use and thermal degradation. This technology is miniaturizing capital requirements for regional-scale pharmaceutical-grade production, enabling distributed manufacturing closer to formulation facilities.
REACH Annex XVII restrictions on palm oil derivatives are compelling European suppliers to document chain-of-c custody for vegetable feedstocks. Manufacturers must now submit sustainability certifications alongside technical data packages. German and Dutch producers are responding by securing mass-balance certified stearic acid streams to maintain EMA drug master file eligibility.
Direct-to-manufacturer excipient procurement is consolidating previously fragmented distributor channels. Large pharmaceutical formulators are building preferred supplier programs that bypass regional chemical distributors. This pattern is most visible in India, where CDSCO-registered drug manufacturers are negotiating annual volume contracts with glycerol monostearate producers for sustained-release tablet lines.
Glycerol Monostearate Market Segmentation
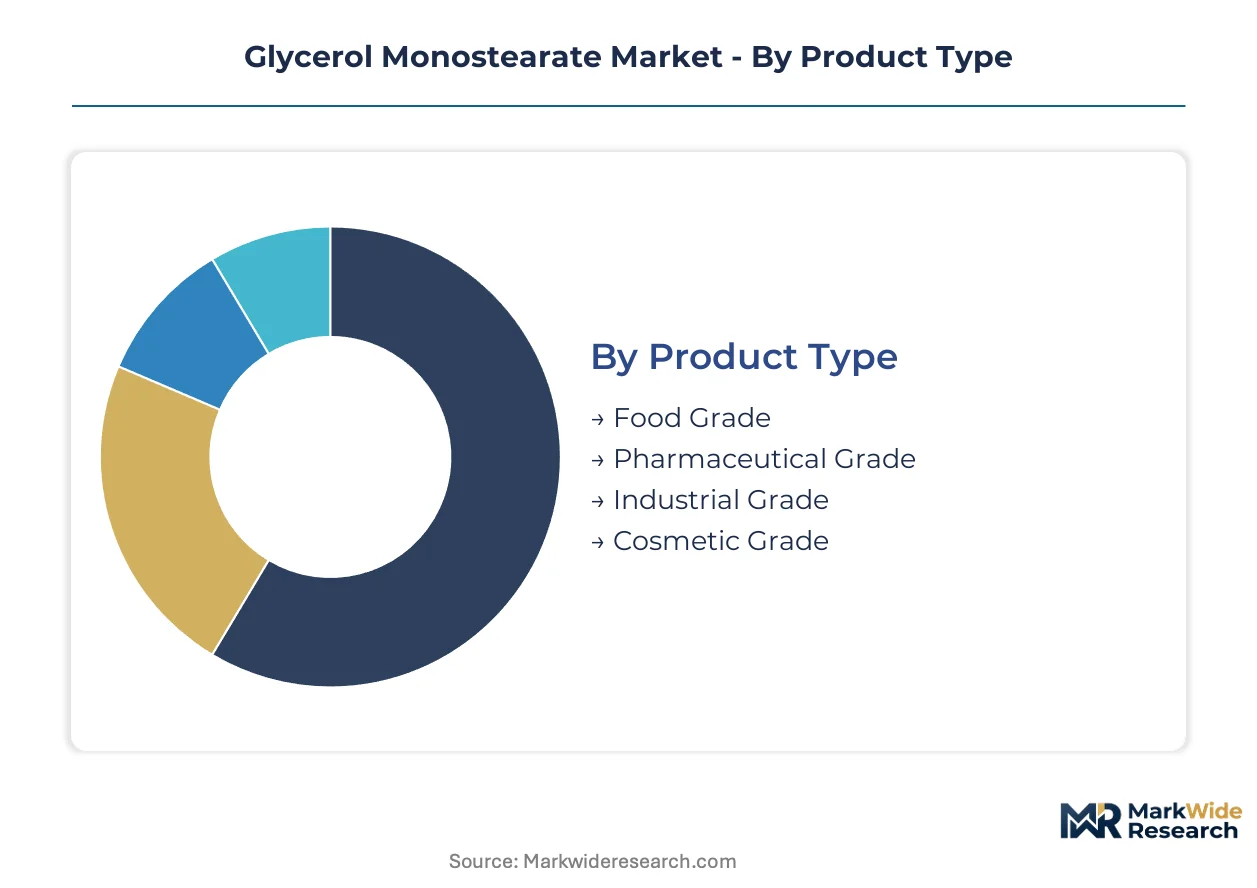
Segmentation in glycerol monostearate markets separates margin capture from volume throughput. Certification tiers and application-specific purity requirements create distinct competitive arenas with divergent pricing power and customer stickiness.
Product Type:
Margin pools concentrate in pharmaceutical-grade material where compendial compliance burdens limit supplier entry and sustain premium pricing.
- Pharmaceutical Grade:Compendial-grade material meeting USP-NF, EP, and JP monographs for tablet lubrication and sustained-release matrices. CDSCO-registered Indian drug manufacturers and FDA-inspected US facilities drive demand concentration as excipient master file requirements tighten supplier qualification.
- Food Grade:Standard monoester content of 40-60 percent serving baking emulsification and confectionery stabilization. Cost efficiency dominates procurement decisions among industrial bakeries and multinational food processors with limited certification premium tolerance.
- Cosmetic Grade:Vegetable-derived variants for clean-label skincare emulsification.
- Industrial Grade:Lower-purity material for polymer processing and lubricant applications.
Food grade holds installed capacity. Pharmaceutical grade is rotating up the share rankings.
Application:
Volume flows concentrate in established food processing channels while formulation innovation redirects growth toward pharmaceutical and cosmetic systems.
- Baking:Dough conditioning and crumb softening across industrial bread and pastry production. European REACH-compliant manufacturers and US commercial bakeries maintain steady offtake despite margin compression from commodity emulsifier competition.
- Cosmetics:Emulsion stabilization in skincare and color cosmetic formulations. Clean-label positioning and vegetable-source preference among premium beauty brands in France, Germany, and the US elevate pricing above food-grade benchmarks.
- Confectionery:Chocolate bloom inhibition and fat crystal modification.
- Dairy Products:Ice cream aeration and whipped topping stabilization.
Baking anchors current volume. Cosmetics is climbing the fastest among application segments.
End User:
Procurement patterns diverge between price-sensitive commodity buyers and compliance-focused pharmaceutical formulators with stringent traceability requirements.
- Pharmaceutical Companies:Sustained-release tablet manufacturers and generic drug producers seeking excipient lot traceability and drug master file support. India's PLI scheme beneficiaries and Brazilian ANVISA-registered facilities are expanding preferred supplier programs with direct producer contracts.
- Food Manufacturers:Industrial bakeries and confectionery processors prioritizing cost per unit and supply security over certification premiums. Multinational food corporations with centralized procurement drive consolidation among distributors.
- Cosmetic Producers:Premium skincare and color cosmetic formulators.
- Industrial Users:Polymer processors and lubricant compounders with specification flexibility.
Food manufacturers command current volume share. Pharmaceutical companies are gaining share fastest through direct procurement consolidation.
Distribution Channel:
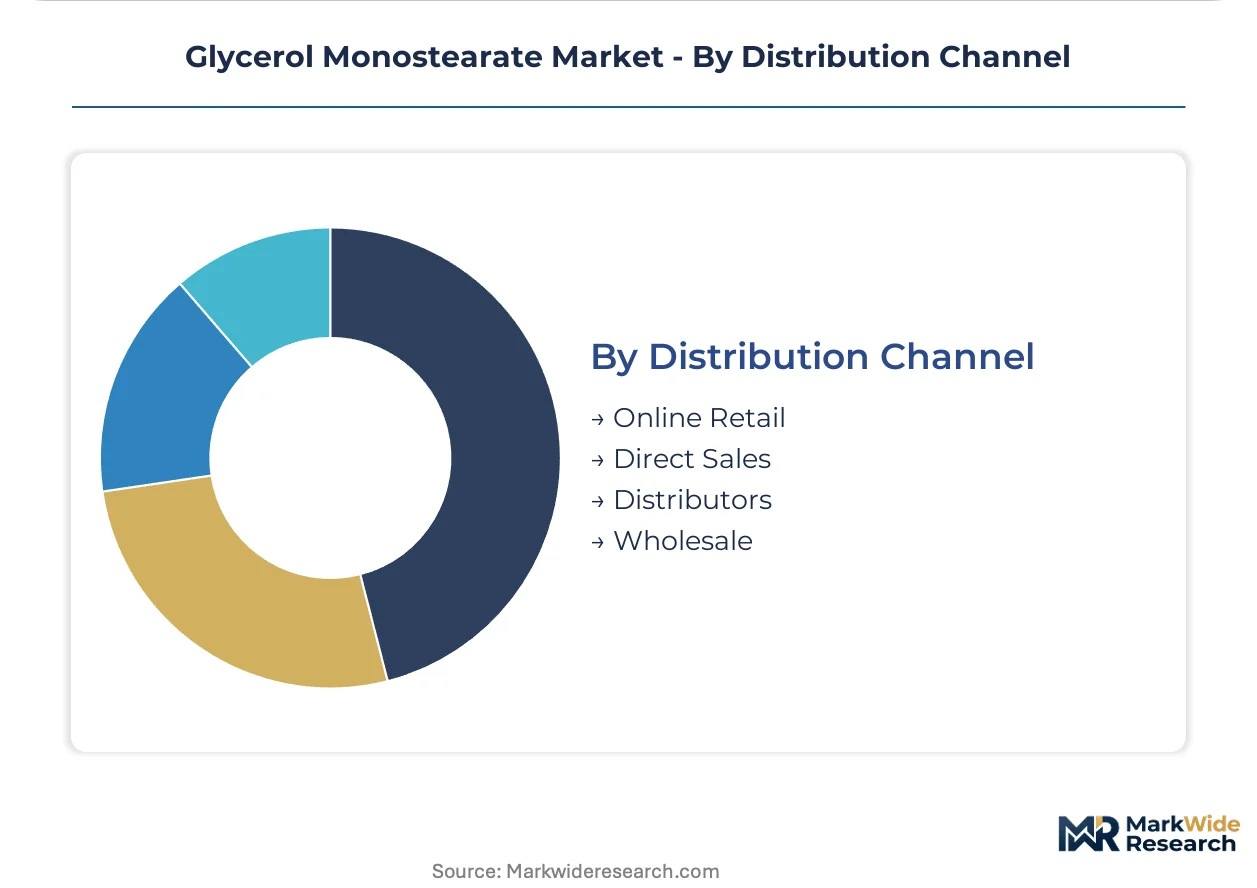
Channel economics reflect customer scale and compliance documentation intensity, with large formulators bypassing intermediaries.
- Direct Sales:Annual volume contracts between glycerol monostearate producers and pharmaceutical formulators requiring excipient master file support and audit access. CDSCO-registered Indian drug manufacturers and FDA-inspected US facilities favor this channel for sustained-release tablet lines.
- Distributors:Regional chemical distributors serving mid-tier food processors and cosmetic compounders with fragmented demand. REACH documentation and kosher-halal certification support justify margin retention for compliant intermediaries.
- Wholesale:Bulk volume aggregation for industrial-grade applications.
- Online Retail:Small-lot procurement for cosmetic startups and research-scale buyers.
Distributors retain food-grade volume. Direct sales is expanding most quickly as pharmaceutical procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Dutch chemical clusters host REACH-compliant manufacturing for pharmaceutical-grade material. Indian excipient demand accelerates under CDSCO-registered facility expansion. Brazilian ANVISA alignment with ICH standards opens Latin American generic pharmaceutical channels.
United States
FDA-inspected pharmaceutical facilities drive sustained-release tablet formulation demand. The FDA's updated excipient guidelines tighten purity thresholds for tablet lubricants. New Jersey and North Carolina drug manufacturing corridors concentrate direct procurement contracts with certified glycerol monostearate producers.
Germany
EMA drug master file requirements sustain premium pricing for compendial-grade material. REACH Annex XVII restrictions on palm oil derivatives force mass-balance certification documentation. Ludwigshafen and Marl chemical parks maintain segregated production lines for pharmaceutical and food-grade streams.
India
CDSCO-registered generic drug manufacturers expand capacity under the PLI pharmaceutical scheme. Domestic production-linked incentives accelerate local excipient consumption. Ahmedabad and Hyderabad pharmaceutical clusters negotiate annual volume contracts bypassing regional distributors.
China
NMPA pharmaceutical standards elevate documentation requirements for imported excipients. GB standards for food-grade emulsifiers maintain cost-competitive export flows. Shanghai and Jiangsu province chemical processors balance domestic pharmaceutical qualification with international food-grade volume.
Brazil
ANVISA regulatory alignment with ICH standards enables excipient supplier qualification for generic drug manufacturing. São Paulo and Rio de Janeiro pharmaceutical formulators build preferred supplier programs with direct producer relationships. Local generic expansion creates pull for certified lubricant materials.
Glycerol Monostearate Market Competitive Environment
Concentration sits with diversified chemical conglomerates possessing dual-track manufacturing capabilities. The supplier base stratifies across pharmaceutical-grade specialists, integrated oleochemical producers, and regional food-grade distributors. Strategic differentiation runs through backward integration into fatty acid feedstocks and captive supply of compendial-grade emulsifiers. Competitive moves center on segregated facility validation and excipient master file harmonization across FDA and EMA jurisdictions.
Among integrated oleochemical producers, Stepan Company and Wilmar International Limited exemplify scale-driven positions anchored in fatty acid feedstock control. Evonik Industries AG occupies the pharmaceutical-grade specialist tier with European manufacturing site concentration. BASF SE and Croda International Plc represent diversified chemical conglomerates balancing food-grade volume with pharmaceutical-grade certification investments.
| Leading Market Players |
|---|
| Stepan Company |
| Lonza Group AG |
| Wilmar International Limited |
| Kao Corporation |
| Evonik Industries AG |
| BASF SE |
| Croda International Plc |
| Palsgaard Malaysia SDN BHD |
| Cargill, Incorporated |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory buffers at German pharmaceutical-grade facilities compress working capital cycles while amplifying margin capture for REACH-certified producers serving EMA drug master file holders. This lead-time architecture concentrates pricing power with dual-track manufacturers capable of segregating food-grade and pharmaceutical-grade streams without cross-contamination liability.
Pricing Analysis
REACH and FDA excipient guidelines dictate the pricing tier structure across the glycerol monostearate market. Three-tier pricing separates pharmaceutical-grade material from food-grade and industrial-grade variants, with compendial compliance burdens sustaining premium capture for USP-NF and EP-certified suppliers. Price differentiation rests on certification level and volume scale, with annual contract buyers securing favorable terms versus spot purchasers. Cost compression in food-grade tiers is intensifying because palm oil and tallow feedstock volatility transmits directly to production economics. Industrial bakeries and confectionery processors exhibit highest price sensitivity, while pharmaceutical formulators prioritize excipient master file support over unit cost.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for European manufacturers dependent on Southeast Asian palm oil derivatives. Supply concentrates in Germany, the Netherlands, and India, with Ludwigshafen and Marl chemical parks hosting segregated production lines for pharmaceutical-grade material. Raw material dependencies center on stearic acid from palm oil and tallow sources, plus glycerin from biodiesel co-production. Single-source vulnerability runs through Malaysian and Indonesian palm oil supply chains exposed to sustainability certification disruptions. Distribution runs through direct sales channels for pharmaceutical formulators and regional chemical distributors serving fragmented food-grade demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic esterification technology is disrupting capital requirements for pharmaceutical-grade production, compressing barriers to entry for regional-scale manufacturers. This technological inflection accelerates under REACH Annex XVII sustainability mandates and FDA excipient guideline convergence.
For Market Incumbents: Secure mass-balance certified stearic acid streams to maintain EMA drug master file eligibility amid palm oil derivative restrictions. Stepan Company and Evonik Industries AG demonstrate how backward integration into fatty acid feedstocks stabilizes margin pools against raw material volatility. Incumbents must extend segregated facility validation timelines to accommodate dual-track quality system redundancy.
For New Entrants and Emerging Players: Lead with enzymatic esterification capabilities targeting Indian CDSCO-registered facilities expanding under PLI pharmaceutical incentives. Brazil's ANVISA-aligned generic drug manufacturing presents the most penetrable geography for excipient suppliers lacking established FDA or EMA relationships. A direct-to-manufacturer go-to-market angle bypasses entrenched distributor channels consolidating around multinational food processors.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because excipient master file harmonization between FDA and EMA concentrates volume among producers with pre-existing drug manufacturer relationships. Acquisition targets should display dual-track manufacturing capabilities and established preferred supplier programs with Indian or Brazilian pharmaceutical clusters. The signal to watch is CDSCO-registered facility expansion rates under production-linked incentive schemes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive stearic acid supply from palm oil or tallow sources insulates margin pools from feedstock volatility. |
| Dual-Track Facility Validation | Segregated production lines for pharmaceutical and food-grade streams unlock EMA and FDA excipient master file eligibility. |
| Enzymatic Esterification Adoption | Immobilized lipase systems reduce solvent use and enable distributed manufacturing closer to formulation facilities. |
| Direct-to-Manufacturer Contracts | Annual volume agreements with CDSCO-registered Indian drug manufacturers bypass distributor margin retention. |
| Mass-Balance Certification | REACH Annex XVII compliance documentation sustains access to European pharmaceutical-grade demand. |
Study Parameters
A spread of perspectives from plant managers at integrated oleochemical facilities, procurement leads at pharmaceutical formulators, technical R&D directors, and distribution channel partners converged on the working assumptions shaping this analysis. Primary interviews combined with secondary validation against customs and trade data, SEC 10-K filings, and CDSCO registration databases. Bottom-up capacity and consumption estimates triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include grade tier, end-use industry, and regional production hub. CAGRs were derived from trend extrapolation anchored in historical consumption patterns and projected capacity additions. Forecast inputs incorporated stearic acid feedstock price trajectories, pharmaceutical formulation technology shifts toward sustained-release matrices, and regulatory harmonization progress between FDA and EMA excipient master file requirements.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Oily Waste Cans Market
Oleochemicals
Global Palm Wax Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Partially Hydrogenated Oil Market
Oleochemicals
Asia-Pacific Oleochemicals Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Ethylhexyl Cocoate Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Alcohol Ethoxylates Market