
 United States Flexographic Printing Market | 2026-2036
United States Flexographic Printing Market Size, Share, and Industry Trends Forecast 2026-2036
United States Flexographic Printing Market Analytics
Midwestern press manufacturers is shifting toward servo-driven CI flexo configurations to shorten makeready times for shorter-run label orders. Mark Andy leverages its narrow-web digital-flexo hybrid platform to capture craft beverage label contracts across Wisconsin and Colorado. BOBST Group anchors North American corrugated board printing through its wide-format folder-gluer and flexo press integration. Heidelberg competes on packaging prepress automation, sustaining R&D intensity in direct laser engraving for photopolymer plates.
Flexographic printing employs raised rubber or photopolymer plates mounted on rotating cylinders to transfer fast-drying inks onto flexible substrates at speeds exceeding 500 feet per minute. The process dominates high-volume packaging production because it accommodates non-porous films, metallic boards, and absorbent papers with minimal substrate waste. Water-based ink formulations lead the technology segment due to EPA volatile organic compound restrictions, though UV-curable systems capture premium personal care and pharmaceutical label applications where rub resistance and gloss retention command margin premiums. Food packaging applications absorb the largest share of installed press capacity, driven by shelf-life extension requirements and brand-owner sustainability pledges.
FDA food contact notification rules govern ink migration limits for direct food packaging, while OSHA workplace exposure standards shape solvent handling protocols in older solvent-based installations. State-level extended producer responsibility legislation in California, Oregon, and Maine is forcing converters to document recyclability pathways and reduce multi-material laminate complexity. Stakeholders must monitor EPA rulemaking on per- and polyfluoroalkyl substance restrictions in grease-resistant food wraps, as these chemistry bans will force reformulation investments across the installed base within the next regulatory cycle.
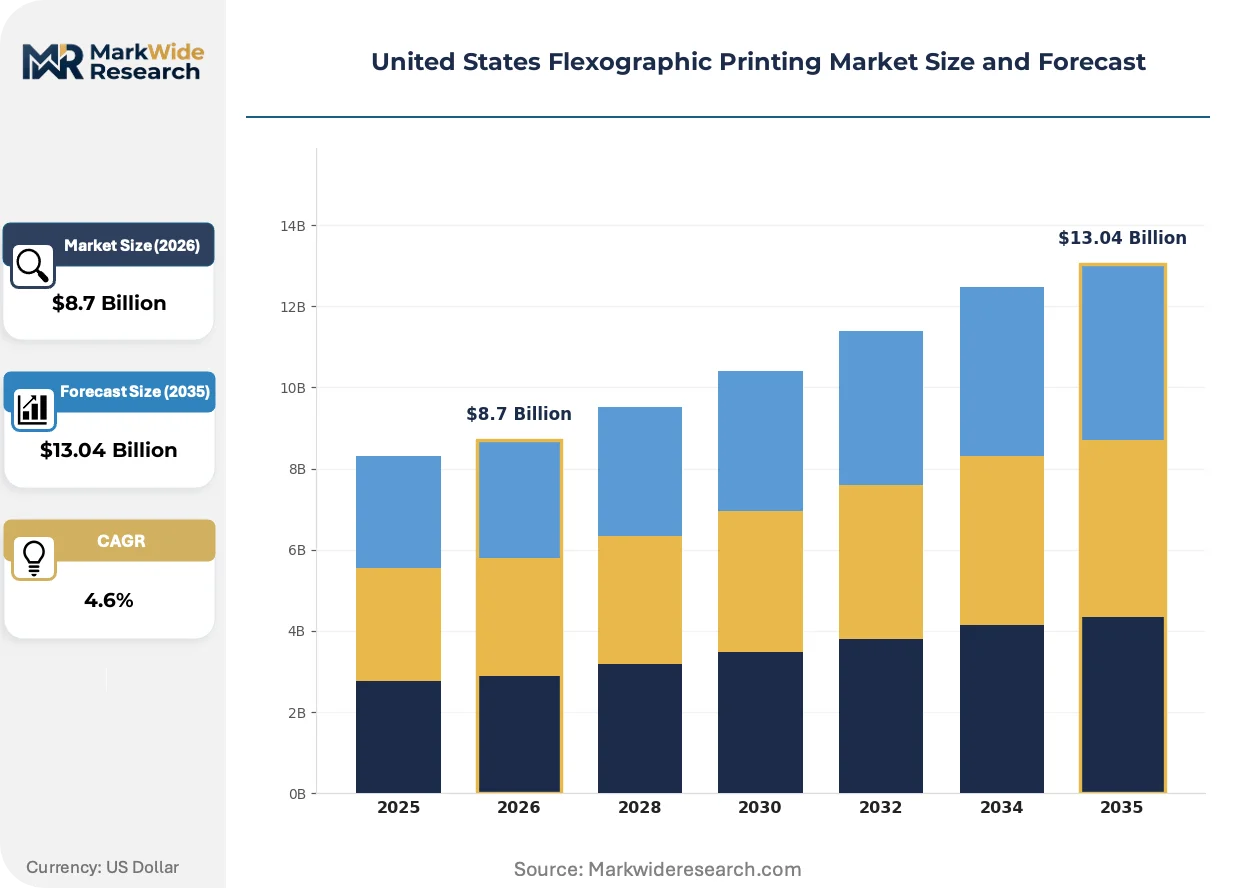
Market Dynamics
EPA volatile organic compound restrictions and state extended producer responsibility frameworks are forcing converters to retire solvent-based ink systems and absorb capital costs for water-based and UV-curable alternatives.
Growth Catalysts
- E-commerce secondary packaging surge:Online retail fulfillment centers across the Midwest and Southeast are demanding shelf-ready corrugated displays with high-graphic flexographic output.
- Water-based ink mandates:California, Oregon, and Maine extended producer responsibility laws require documented recyclability pathways, accelerating converter migration to compliant formulations.
- Servo-driven CI flexo adoption:Narrow-web label converters are deploying computer-integrated press configurations to compress makeready times for shorter production runs.
Market Restraints
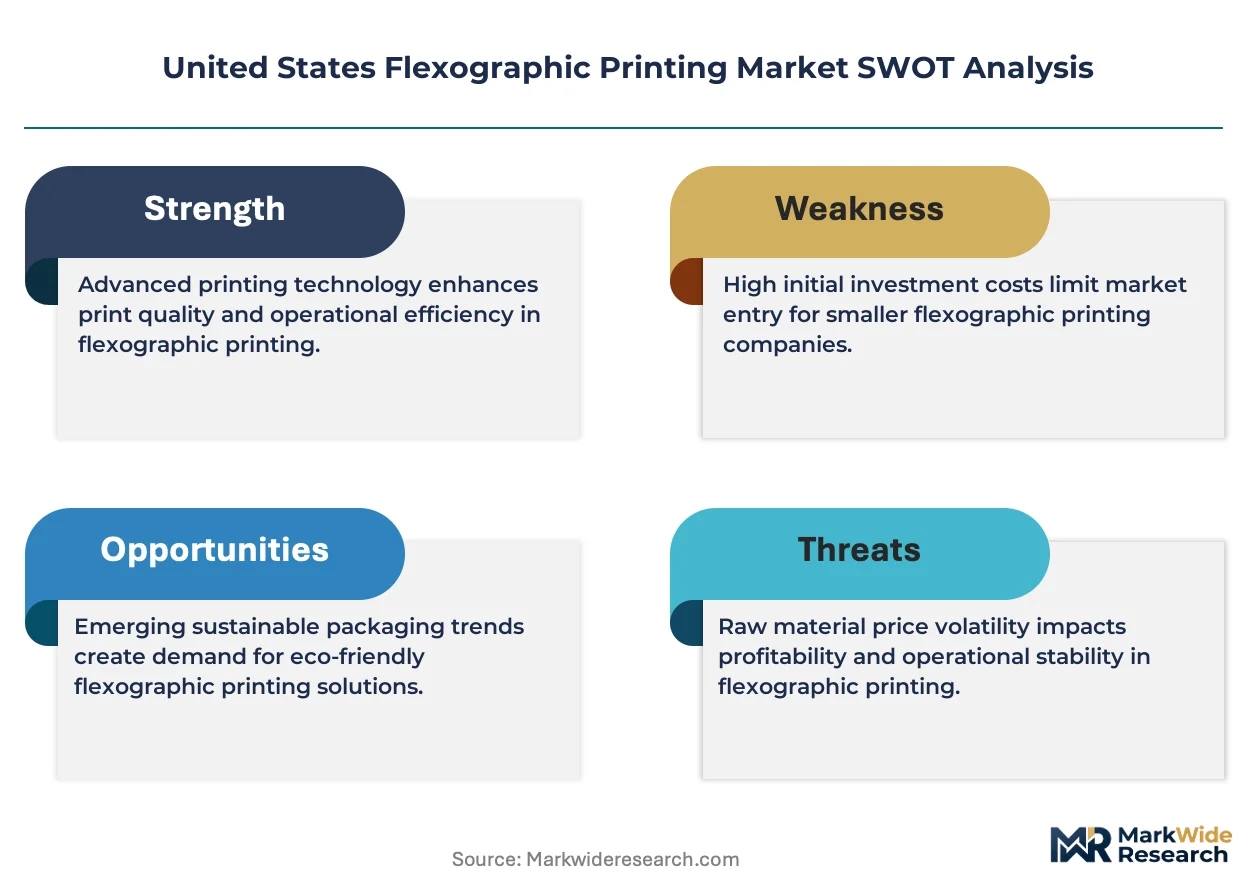
- Photopolymer plate cost volatility:Raw material supply for laser-engravable plates concentrates with a limited supplier base, squeezing converter margins during input price spikes.
- Per- and polyfluoroalkyl substance restrictions:Pending EPA rulemaking on PFAS chemistry bans in grease-resistant food wraps will force immediate reformulation investments across installed press capacity.
- Digital printing substitution:Toner and inkjet systems capture premium short-run label applications where variable data and versioning requirements dominate.
Strategic Opportunities
- Pharmaceutical label compliance:FDA food contact notification rules and rub-resistance specifications create premium positioning for UV-curable ink systems in drug packaging.
- Flexible packaging for perishables:Shelf-life extension requirements and brand-owner sustainability pledges are opening high-volume contracts for multi-layer film converters.
- Corrugated display automation:Integration of wide-format folder-gluer lines with inline flexo presses offers turnkey production for retail-ready point-of-purchase units.
Industry Challenges
- Direct laser engraving technician scarcity:Photopolymer plate production requires specialized prepress operators, and training pipelines have not kept pace with servo-press deployment rates.
- Legacy solvent-press stranded assets:Converters with substantial remaining depreciation on older equipment face compressed windows for ROI recovery before environmental compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Flexographic Printing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inks, Plate, Coatings, Presses End User: Packaging, Labels, Newspapers, Corrugated Technology: Water-Based, Solvent-Based, UV-Curable, Hybrid Application: Food Packaging, Beverage Packaging, Personal Care, Industrial |
| Companies Covered | BOBST Group, Heidelberg, DIC Corporation, Comexi Group Industries, Nilpeter, Siegwerk Group, Mark Andy, Windmoeller & Hoelscher, Flint Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Flexographic Printing Market Evolving Landscape
Press architecture and ink chemistry are converging around sustainability mandates and shorter production cycles, with automation investments outpacing conventional speed-and-feed upgrades across the installed base.
Servo-driven impression control systems are modularizing press configurations for rapid job changeovers. Craft beverage label converters in Wisconsin and Colorado are adopting these retrofits to handle SKU proliferation without dedicated press lines. The technology is modularizing converter asset utilization, allowing single presses to serve multiple end-use verticals that previously required segregated capacity.
EPA rulemaking on per- and polyfluoroalkyl substance restrictions is tightening migration limits for grease-resistant food wraps. Converters must document alternative chemistry pathways before compliance deadlines or risk production halts. Flexible packaging applications for fast-food and frozen meal segments are most exposed, with reformulation timelines compressing against regulatory enforcement windows.
Brand-owner sustainability scorecards are reshaping supplier qualification criteria. Major food and personal care manufacturers are unbundling print procurement from legacy packaging contracts, creating direct relationships with prequalified flexographic converters. This disintermediation is most visible in the Southeast, where corrugated and flexible packaging demand concentrates near population centers and distribution infrastructure.
United States Flexographic Printing Market Segmentation
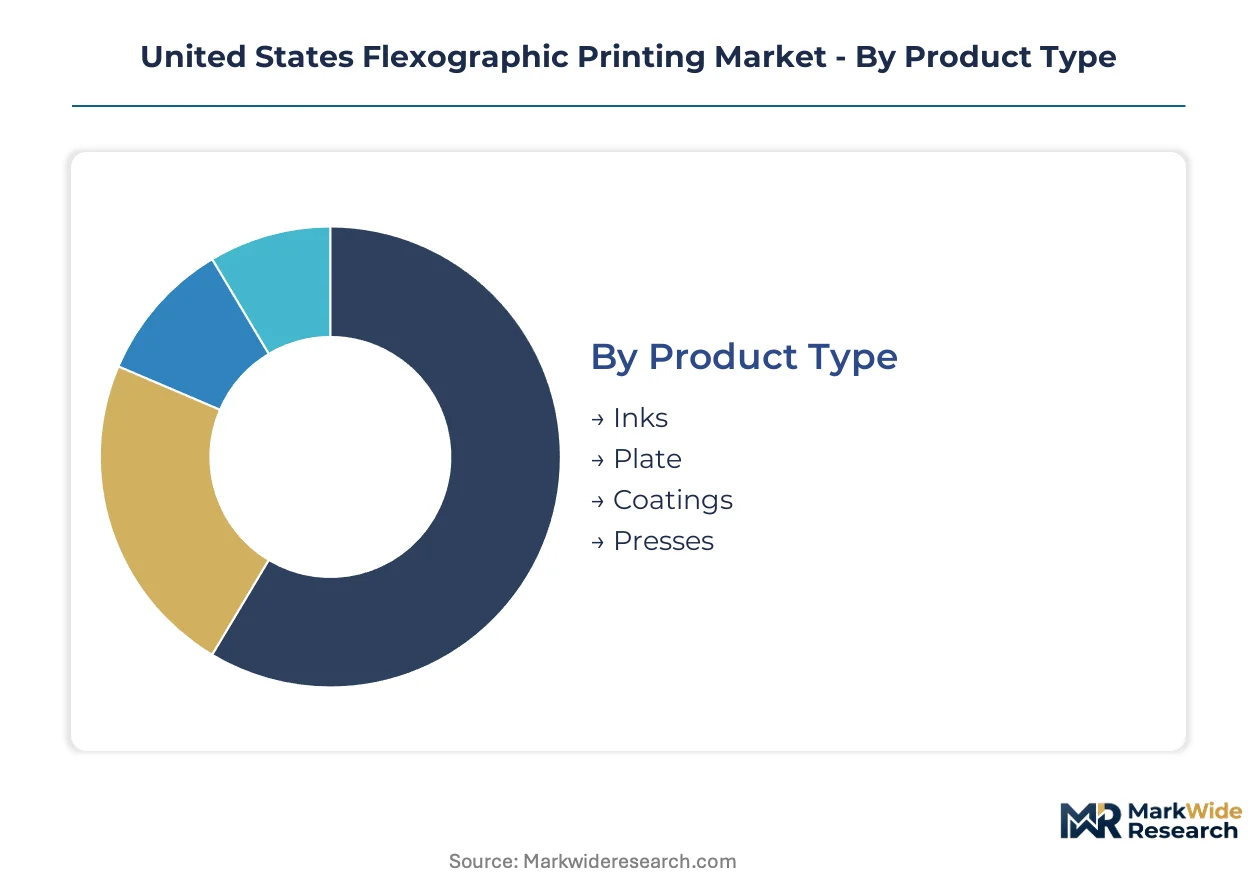
Flexographic printing segmentation reveals how converter investment priorities diverge across substrate types, regulatory exposure, and automation requirements. Understanding these splits exposes where capital deployment concentrates and which technology transitions carry the steepest compliance costs.
Product Type:
Raw material supply for photopolymer plates concentrates with a limited supplier base, creating margin volatility that ripples through converter procurement decisions.
- Inks:Water-based formulations dominate volume due to EPA volatile organic compound restrictions, while UV-curable systems command premium positioning in pharmaceutical and personal care applications where rub resistance and gloss retention justify higher unit costs. Midwestern and Southeastern food packaging converters are absorbing the largest ink formulation switchover costs as state extended producer responsibility deadlines approach.
- Presses:Servo-driven CI flexo configurations are modularizing asset utilization, allowing single presses to serve multiple end-use verticals that previously required segregated capacity. Wisconsin and Colorado craft beverage label converters are deploying these retrofits to compress makeready times for shorter production runs without dedicated press lines.
- Plate:Laser-engravable photopolymer plates require specialized prepress operators, and training pipelines have not kept pace with servo-press deployment rates across the installed base.
- Coatings:Barrier coatings face immediate reformulation pressure from pending EPA per- and polyfluoroalkyl substance restrictions in grease-resistant food wraps.
Presses absorb the bulk of installed capacity; inks are expanding most quickly as converters retire solvent-based systems ahead of compliance deadlines.
End User:
Customer procurement patterns are splitting between high-volume corrugated display contracts and shorter-run label work with versioning requirements.
- Packaging:Flexible packaging for perishable goods absorbs the largest share of technology investment, driven by shelf-life extension requirements and brand-owner sustainability pledges. Multi-layer film converters in the Southeast are securing high-volume contracts near population centers and distribution infrastructure.
- Corrugated:E-commerce secondary packaging demand concentrates in Midwest and Southeast fulfillment centers, where shelf-ready displays with high-graphic flexographic output are displacing plain brown box specifications.
- Labels:Narrow-web converters face digital printing substitution in premium short-run applications where variable data requirements dominate.
- Newspapers:Publication gravure and offset presses retain cost advantages for long-run newsprint, constraining flexographic penetration in this segment.
Packaging commands the majority of converter revenue; corrugated is climbing the fastest as retail-ready point-of-purchase specifications proliferate.
Technology:
Capital allocation is bifurcating between compliance-driven water-based retrofits and performance-driven UV installations.
- Water-Based:EPA emissions guidelines and state-level extended producer responsibility frameworks in California, Oregon, and Maine are forcing converters toward these formulations with documented recyclability pathways.
- UV-Curable:Instant curing enables higher substrate speeds and superior durability for personal care and pharmaceutical labels where FDA food contact notification rules govern migration limits.
- Solvent-Based:Legacy installations face stranded asset risk as environmental compliance deadlines compress remaining depreciation recovery windows.
- Hybrid:Digital-flexo platforms capture craft beverage and specialty food contracts requiring versioning flexibility without full digital press capital commitment.
Water-based systems hold the largest installed base; UV-curable is gaining share fastest in premium compliance-driven segments.
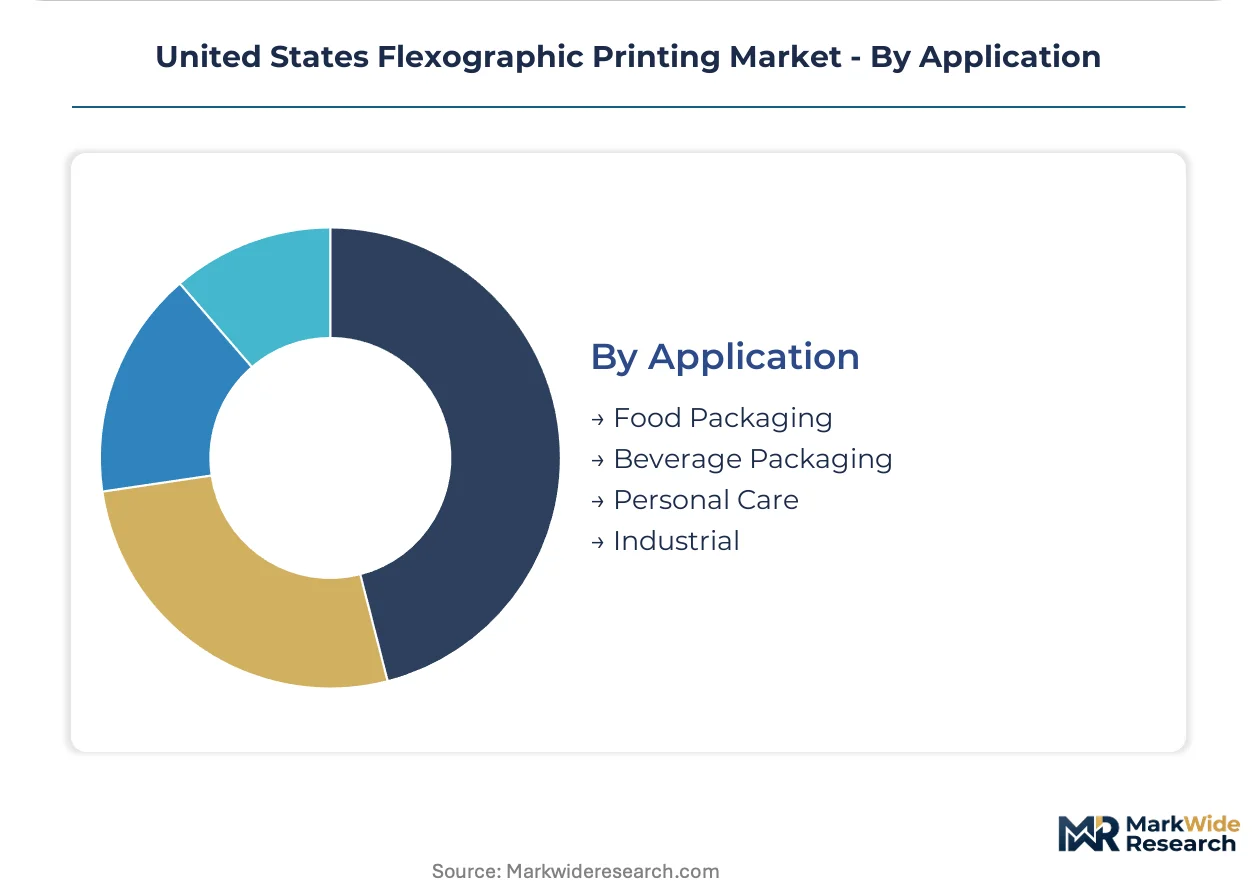
Application:
Regulatory exposure varies sharply across direct food contact, secondary containment, and industrial durability requirements.
- Food Packaging:Direct food contact applications face the tightest FDA migration limits and EPA chemistry restrictions, forcing reformulation investments across grease-resistant wraps and fast-food packaging segments.
- Beverage Packaging:Craft producers in Wisconsin and Colorado are unbundling print procurement from legacy packaging contracts, creating direct relationships with prequalified narrow-web converters.
- Personal Care:Rub-resistance specifications and brand-owner sustainability scorecards are reshaping supplier qualification criteria for premium positioning.
- Industrial:Durability requirements for outdoor and chemical-exposure applications sustain solvent-based and UV-heavy formulations despite environmental compliance pressure.
Food packaging dominates converter capacity allocation; beverage packaging is expanding most quickly as craft producer procurement patterns shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock corridors along the Gulf Coast anchor domestic photopolymer plate manufacturing, while Midwestern agricultural packaging demand and Southeastern e-commerce fulfillment infrastructure shape geographic investment patterns across the installed press base.
Southeast
E-commerce fulfillment centers in Georgia and Florida are driving shelf-ready corrugated display contracts that require high-graphic flexographic output. EPA emissions guidelines and state-level extended producer responsibility frameworks in neighboring states are pressuring converters toward water-based ink retrofits. Atlanta and Charlotte industrial clusters concentrate multi-layer film capacity for fast-food packaging applications facing pending PFAS chemistry restrictions.
Midwest
Food packaging converters across Illinois, Ohio, and Wisconsin are expanding flexographic capacity for perishable goods with shelf-life extension requirements. OSHA workplace exposure standards shape solvent handling protocols in older installations across Michigan and Indiana manufacturing corridors. Milwaukee and Denver craft beverage label markets are adopting servo-driven CI flexo configurations to compress makeready times for SKU proliferation.
California
Extended producer responsibility legislation mandates documented recyclability pathways, accelerating converter migration to compliant water-based formulations ahead of compliance deadlines. FDA food contact notification rules govern ink migration limits for direct food packaging applications serving Central Valley agricultural processors. Los Angeles and San Diego metropolitan areas concentrate flexible packaging demand for personal care and pharmaceutical label segments where UV-curable systems command premium positioning.
Pacific Northwest
Brand-owner sustainability pledges from Seattle and Portland headquartered food manufacturers are reshaping supplier qualification criteria for corrugated and flexible packaging converters. State environmental agencies enforce volatile organic compound restrictions that exceed federal EPA baselines, forcing faster solvent-based system retirements. Boise and Spokane industrial zones anchor specialty label production for craft food and beverage producers unbundling print procurement from legacy packaging contracts.
Northeast Corridor
Pharmaceutical packaging demand from New Jersey and Massachusetts drug manufacturers sustains premium UV-curable ink installations governed by FDA rub-resistance specifications. Legacy solvent-press installations in Pennsylvania and upstate New York face compressed depreciation recovery windows before environmental compliance deadlines. Boston and Philadelphia metropolitan clusters concentrate prepress automation investment for direct laser engraving of photopolymer plates.
United States Flexographic Printing Market Competitive Landscape
Global majors compete with regional champions across equipment integration and ink formulation segments, producing a tiered structure where scale-driven press manufacturers anchor wide-format corrugated automation while specialty ink suppliers capture premium compliance-driven niches. Market participants organize into three archetypes: integrated equipment-ink platforms, standalone press specialists, and formulation-focused chemical suppliers. Dominant competitive moves include servo-press technology licensing partnerships and vertical integration into photopolymer plate production to secure raw material supply.
Among integrated equipment specialists, BOBST Group and Heidelberg exemplify the wide-format automation archetype, while Mark Andy occupies a position within the narrow-web hybrid segment. These three companies represent divergent strategic postures across the corrugated-to-label spectrum, with each anchoring distinct customer procurement patterns in food packaging and beverage label verticals.
| Leading Market Players |
|---|
| BOBST Group |
| Heidelberg |
| DIC Corporation |
| Comexi Group Industries |
| Nilpeter |
| Siegwerk Group |
| Mark Andy |
| Windmoeller & Hoelscher |
| Flint Group |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up ink specialists have consolidated regional formulation capacity across the Ohio River Valley and Gulf Coast corridors, tightening pricing discipline on water-based systems while converters absorb reformulation costs ahead of EPA compliance deadlines. This ownership concentration feeds directly into supply behavior, as portfolio companies leverage captive distribution networks to bundle ink supply with technical service contracts.
Pricing Analysis
Service bundling separates turnkey formulation-plus-technical-support contracts from unbundled commodity ink supply, with the former commanding 15-25% premiums in pharmaceutical and personal care segments. Three-tier pricing structure across premium UV-curable, standard water-based, and economy solvent-based formulations reflects certification grade and after-sales intensity. Cost compression in standard water-based tiers is intensifying because Midwestern converters face simultaneous EPA and state extended producer responsibility deadlines. Narrow-web label converters exhibit highest price sensitivity due to digital printing substitution pressure, while corrugated display specialists prioritize graphic consistency over unit cost.
Supply Chain Analysis
Photopolymer plate resin supply rests on Japanese and German specialty chemical producers, with photoinitiator feedstocks drawing from Chinese and Indian pharmaceutical intermediate manufacturers. Raw material dependencies concentrate on acrylate monomers, nitrocellulose binders, and laser-engravable elastomer compounds. Single-source vulnerability in photoinitiator supply creates exposure to pharmaceutical sector demand spikes that divert chemical intermediate allocation. Distribution runs through converter-direct relationships with integrated equipment-ink platforms, bypassing traditional chemical distributor networks for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States flexographic printing market functions as a cost-of-compliance story where EPA volatile organic compound restrictions and pending per- and polyfluoroalkyl substance rulemaking erect barrier-to-entry moats for converters with certified water-based and UV-curable installations.
For Market Incumbents: Hedge stranded asset exposure in legacy solvent-press capacity by accelerating depreciation recovery through short-run label contract capture before environmental compliance deadlines force retirement. Prioritize backward integration into photopolymer plate production to secure raw material supply against laser-engravable resin price volatility. Channel control through direct brand-owner relationships insulates against disintermediation pressure from sustainability scorecard procurement unbundling. For New Entrants and Emerging Players: Begin with narrow-web hybrid press configurations serving craft beverage and specialty food producers in Wisconsin and Colorado, where SKU proliferation and versioning requirements outpace digital press capital commitment thresholds. The most penetrable segment lies in corrugated display automation for e-commerce fulfillment centers across Georgia and Florida, where turnkey folder-gluer integration contracts remain undersupplied. A go-to-market angle anchored in EPA pre-certification and documented recyclability pathways accelerates supplier qualification with sustainability-focused brand owners. For Investors and Strategic Acquirers: Distressed-cycle entries favor Midwestern narrow-web converters with servo-driven CI flexo retrofits and established FDA food contact notification compliance records, as legacy solvent-press operators face compressed depreciation recovery windows. Long-term viability across the analysis window hinges on water-based formulation expertise and direct laser engraving prepress automation capabilities. The signal to watch is EPA final rulemaking on per- and polyfluoroalkyl substance restrictions, which will trigger immediate reformulation investment spikes and potential production halts for non-compliant grease-resistant food wrap capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Ink Retrofit Program | EPA compliance deadlines in California, Oregon, and Maine force accelerated capital deployment. |
| Servo-Driven CI Flexo Adoption | Wisconsin and Colorado craft beverage converters compress makeready times for SKU proliferation. |
| Photopolymer Plate Backward Integration | Captive resin supply secures margins against Japanese and German specialty chemical price volatility. |
| Corrugated Display Automation Integration | Georgia and Florida e-commerce fulfillment centers demand turnkey folder-gluer and flexo press lines. |
| Direct Laser Engraving Prepress Investment | Specialized technician scarcity constrains servo-press deployment rates across the installed base. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving flexographic press operators, ink formulation chemists, corrugated procurement managers, and prepress automation specialists. EPA rulemaking dockets, FDA food contact notification databases, and state extended producer responsibility legislative archives provided regulatory trajectory validation. Bottom-up press installation counts and top-down converter revenue estimates were reconciled through triangulation.
Data-stream reconciliation across equipment shipment records, ink formulation volume disclosures, and end-use packaging demand surveys shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include substrate type, ink chemistry technology, end-use vertical, and regional regulatory cluster. CAGRs were derived from installed capacity expansion rates and formulation switchover timelines, with e-commerce corrugated demand and pharmaceutical label compliance specifications serving as primary demand-side forecast inputs.
Underlying measurement precision varies by segment; water-based ink volume estimates carry tighter precision than emerging UV-curable niche applications due to supplier concentration and disclosure consistency. Forecasts reflect assumptions around EPA rulemaking finalization timing and state extended producer responsibility enforcement intensity. A small set of regulatory triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
North America Printing Inks Market
Printing Inks
Waterborne Ink Market
Printing Inks
Ink Resins Market
Printing Inks
United States Printing Inks Market
Printing Inks
Global Printing Toners Market
Printing Inks
Food Grade Inks Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Functional Printing Market
Printing Inks
Global Printing Blanket Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
Food Marking Inks Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Printing Inks Market
Printing Inks
Plant Oil Based Printing Inks Market