
 Semaglutide API Market | 2026-2036
Semaglutide API Market Size, Share, and Industry Trends Forecast 2026-2036
Semaglutide API Market Insights
Multi-source peptide procurement is hardening as semaglutide sponsors diversify beyond single-origin supply. Bachem leverages its large-scale solid-phase synthesis infrastructure to anchor European supply security. Dr. Reddy's Laboratories sustains cost-competitive fermentation-to-synthesis capabilities from Indian manufacturing bases. Teva controls generic API qualification pathways that position it for post-patent volume shifts.
Semaglutide active pharmaceutical ingredient denotes the synthetic GLP-1 receptor agonist peptide sequence, manufactured through recombinant DNA technology or solid-phase peptide synthesis with minimum 98.5% purity and stringent endotoxin limits for parenteral administration. The injection product type dominates current volume as prescribers prefer once-weekly subcutaneous dosing for metabolic disease management. Subcutaneous formulation demand is accelerating fastest among delivery modes, while oral tablet absorption enhancer complexity preserves premium margin pools for lyophilized vial packaging. Homecare end-user channels are expanding as self-administration training protocols reduce clinic dependency.
FDA peptide drug substance guidance and EMA chemistry-manufacturing-controls requirements enforce batch-to-batch consistency that shapes supplier qualification timelines. China's NMPA GB standards for recombinant peptide production and India's CDSCO active substance master file protocols add layered compliance obligations for cross-border API shipments. Stakeholders must monitor regulatory divergence between US and Chinese peptide impurity specifications to avoid dual-qualification cost escalation.
Market Dynamics
Peptide API procurement is consolidating around multi-year supply agreements as branded drug sponsors lock in fermentation and solid-phase synthesis capacity ahead of patent cliffs. This concentration dynamic is compressing qualification timelines and elevating purity thresholds across contract manufacturing networks.
Growth Catalysts
- GLP-1 expansion into obesity management:Metabolic disease protocols now prioritize once-weekly injectable therapies, pulling API volume into chronic care channels previously served by small-molecule diabetes treatments.
- FDA peptide drug substance guidance:Tightened endotoxin and impurity specifications for parenteral peptide products are accelerating sponsor investment in qualified synthetic manufacturing infrastructure.
- China's NMPA GB standards harmonization:Recombinant peptide production protocols aligned with ICH Q7 are reducing cross-border shipment delays for API entering Chinese formulation facilities.
Market Restraints
- Specialized raw material concentration:Protected amino acid derivatives and resin substrates for solid-phase synthesis flow through limited European and Japanese chemical suppliers, creating input cost volatility.
- Single-source fermentation risk:Recombinant DNA production of long-acting analogs depends on proprietary E. coli or yeast strain banks held by a concentrated set of contract development organizations.
- Lyophilized vial capacity scarcity:Aseptic fill-finish infrastructure for peptide parenterals is concentrated in Switzerland and Germany, extending lead times for finished dosage form release.
Strategic Opportunities
- Indian CDSCO active substance master file pathway:Domestic peptide synthesis capabilities coupled with streamlined DMF filing procedures position Indian manufacturers for post-patent generic API volume.
- Oral tablet absorption enhancer convergence:SNAC-based formulation technology paired with synthetic peptide engineering opens chronic administration channels beyond injection-dependent patient populations.
- Homecare self-administration training:Nurse educator networks and digital injection coaching platforms are displacing clinic-based dosing for metabolic disease management in the United States.
Industry Challenges
- Peptide chemist talent scarcity:Solid-phase synthesis scale-up expertise and analytical method development for complex impurities remain concentrated among retiring European-trained specialists.
- Dual-qualification cost escalation:Divergent FDA and NMPA impurity specification limits force sponsors to maintain separate reference standard libraries and stability protocols for trans-Pacific shipments.
- Legacy small-molecule facility retrofitting:Converting antibiotic or hormone API plants to peptide-grade cleanroom standards requires complete HVAC and water system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semaglutide API Market |
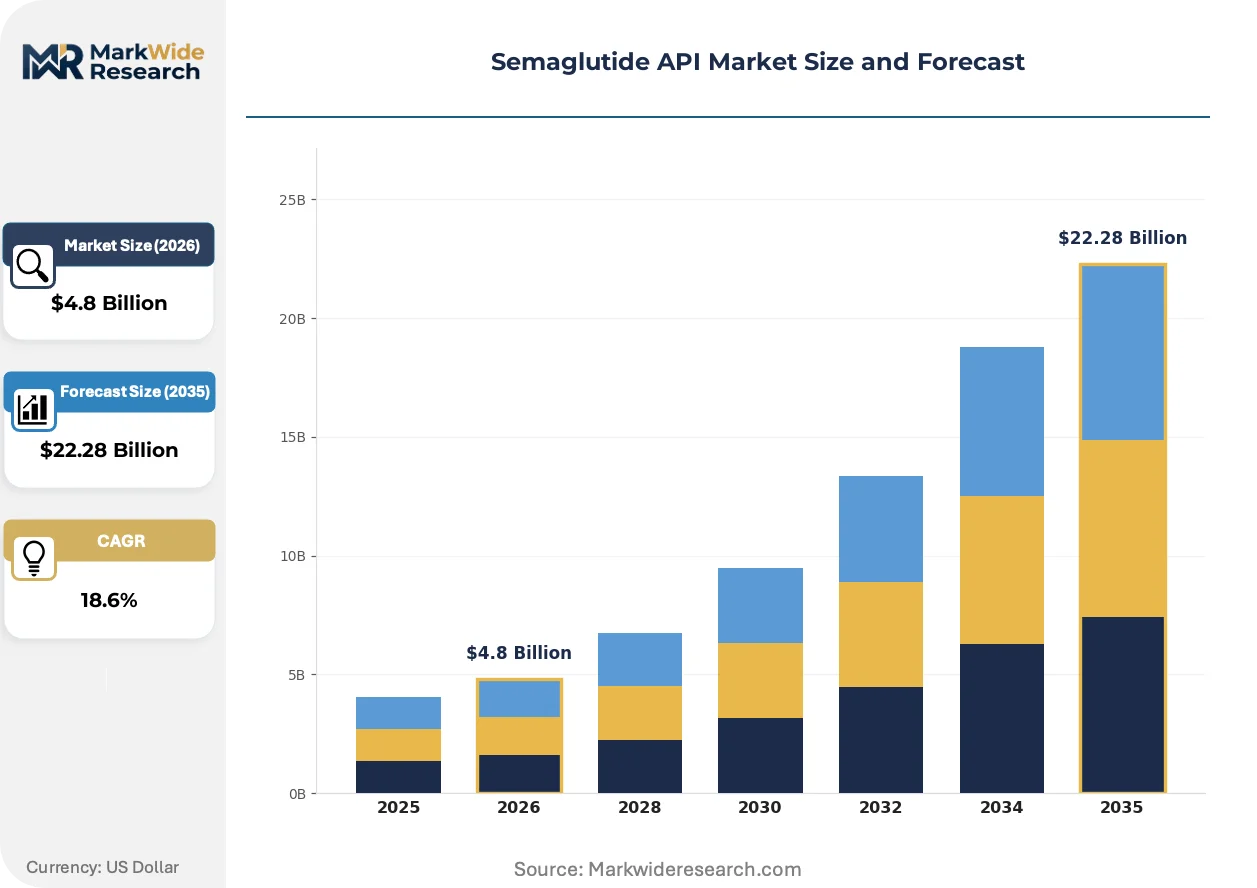
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Tablet, Pen, Dispenser End User: Hospitals, Clinics, Homecare, Pharmacies Formulation: Oral, Subcutaneous, Liquid, Lyophilized Packaging Type: Vial, Pre-filled Syringe, Cartridge, Ampoule |
| Companies Covered | Dr. Reddy's Laboratories, Anthem Biosciences, Bachem, Viruj Pharmaceutical, Zabcbio, AmbioPharm, Teva, ZPC Peptide, Rochem International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semaglutide API Market Trends and Innovations
Continuous manufacturing and real-time release testing are displacing batch-oriented peptide synthesis workflows. These shifts are compressing cycle times while elevating process analytical technology investment across contract manufacturing networks.
Recombinant DNA technology for semaglutide precursor production is converging with automated solid-phase synthesis finishing steps. European CDMOs are adopting this hybrid approach to balance yield efficiency with structural precision. The technology convergence is enabling single-site production of multi-kilogram peptide batches that previously required geographic fragmentation between fermentation and synthesis specialists.
EMA chemistry-manufacturing-controls requirements for peptide drug substances are tightening documentation standards for starting material provenance. Sponsors must now trace protected amino acids to specific chemical manufacturers and batch records. Oral semaglutide tablet sponsors face the steepest compliance burden as absorption enhancer complexity multiplies critical quality attribute tracking.
Hospital and clinic procurement of semaglutide API is consolidating through specialty distributor networks that bundle cold-chain logistics with inventory management. These channel intermediaries are displacing direct manufacturer relationships for mid-sized health systems. The United States exhibits the most pronounced consolidation as pharmacy benefit managers extend their influence into medical benefit injectable purchasing.
Semaglutide API Market Segmentation
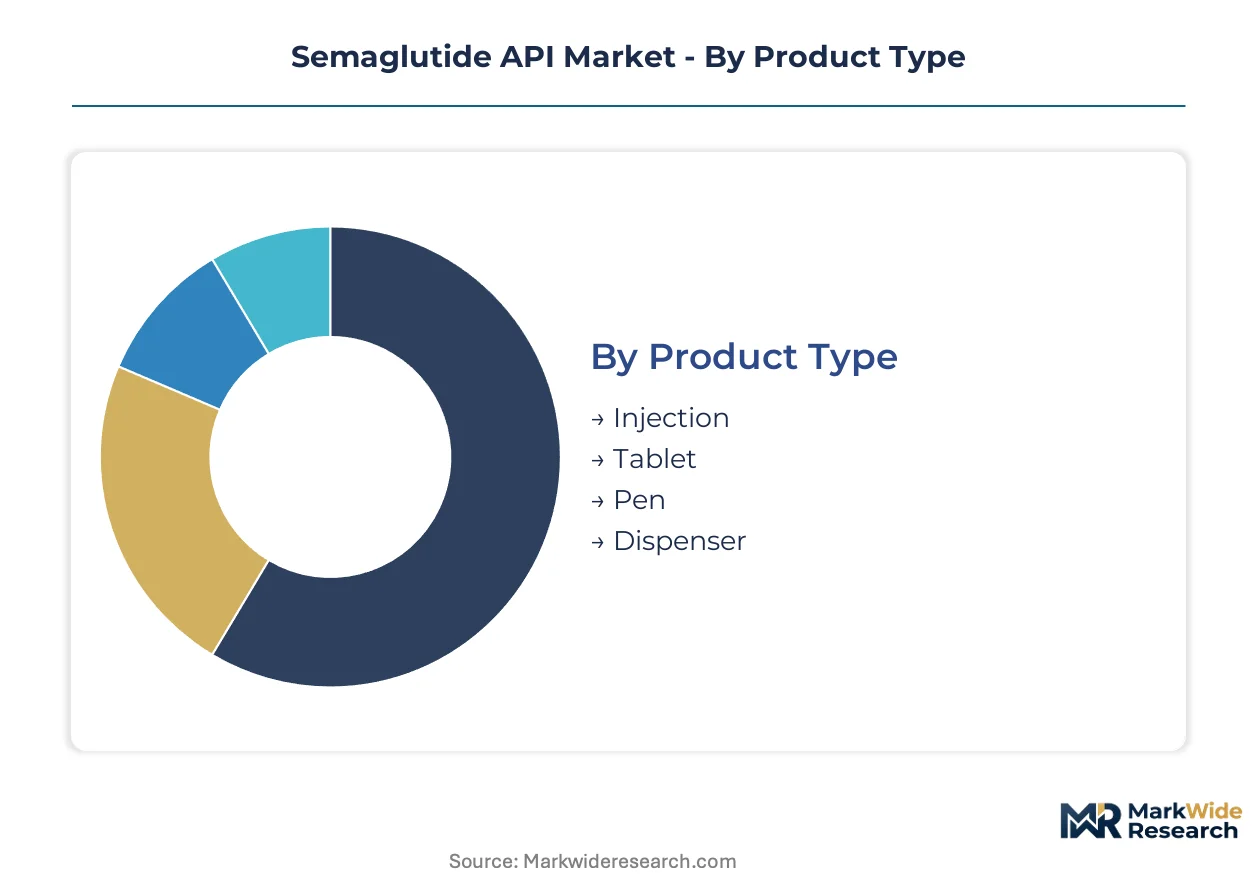
Semaglutide API procurement patterns diverge sharply across delivery modalities and care settings. Manufacturers must align synthetic peptide capacity with formulation complexity, as subcutaneous injection demands divergent purity protocols from oral tablet production.
Product Type:
Standalone injection systems dominate current procurement volumes, while integrated pen and dispenser formats embed dosing technology directly into patient-facing devices.
- Injection:Once-weekly subcutaneous formulations require 98.5% minimum peptide purity with stringent endotoxin limits for parenteral administration. Demand concentrates in United States metabolic disease clinics where prescribers prioritize dosing adherence through simplified regimens.
- Tablet:Oral absorption depends on SNAC-based enhancer technology co-formulated with synthetic peptide sequences. China's NMPA GB standards for recombinant peptide production are accelerating sponsor qualification of domestic formulation facilities for this complex dosage form.
- Pen:Integrated injection devices combine API cartridge with automated dosing mechanisms for self-administration.
- Dispenser:Multi-dose reservoir systems support institutional settings with centralized preparation protocols.
Volume placements concentrate in Injection; the faster expansion belongs to Tablet.
End User:
Cost tier stratification separates institutional procurement from direct-to-patient channels, with reimbursement structures dictating API allocation across care settings.
- Hospitals:Inpatient metabolic protocols and surgical weight management programs drive bulk API procurement through group purchasing organizations. EMA chemistry-manufacturing-controls requirements enforce batch-to-batch consistency that shapes supplier qualification timelines for European hospital networks.
- Homecare:Self-administration training protocols and cold-chain direct-to-patient delivery are displacing clinic-based dosing. United States pharmacy benefit managers extend influence into medical benefit injectable purchasing for this channel.
- Clinics:Outpatient endocrinology practices serve as the primary initiation point for chronic GLP-1 therapy.
- Pharmacies:Retail dispensing channels handle prescription fulfillment for established patients on maintenance dosing.
Hospital procurement commands the largest absolute volumes; Homecare channels are climbing the fastest as self-administration protocols mature.
Formulation:
Application urgency separates acute metabolic management from chronic obesity protocols, with route of administration determining API structural specifications.
- Subcutaneous:Long-acting peptide analogs with fatty acid side-chain modifications enable weekly dosing through albumin binding. FDA peptide drug substance guidance on parenteral impurity thresholds drives sponsor investment in qualified synthetic manufacturing infrastructure.
- Oral:Absorption enhancer complexity preserves premium margin pools as SNAC co-formulation requires specialized analytical method development. India's CDSCO active substance master file protocols add layered compliance obligations for cross-border API shipments targeting this formulation type.
- Liquid:Ready-to-use solutions reduce reconstitution errors in institutional settings.
- Lyophilized:Freeze-dried peptide stability enables extended shelf life for temperature-sensitive biologics.
Subcutaneous formulations anchor current production volumes; Oral delivery systems are gaining share fastest as formulation technology converges.
Packaging Type:
Supply concentration in aseptic fill-finish infrastructure creates bottlenecks that differentiate premium vial supply from commodity cartridge availability.
- Pre-filled Syringe:Single-use injection systems eliminate dosing measurement errors for homecare patients. Switzerland and Germany host concentrated lyophilized vial capacity that extends lead times for this packaging format.
- Vial:Multi-dose containers serve institutional settings with pharmacy-controlled compounding protocols. Bachem's large-scale solid-phase synthesis infrastructure anchors European supply security for vial-based API demand.
- Cartridge:Pen-compatible reservoirs integrate with reusable injection devices.
- Ampoule:Break-seal glass containers support emergency and field deployment scenarios.
Pre-filled Syringe volumes dominate patient-facing dispensing; Vial packaging maintains institutional preference where pharmacy oversight persists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Branded drug sponsors concentrate multi-year API procurement in the United States and China, while European peptide synthesis infrastructure anchors supply security for trans-Atlantic shipments. India's fermentation-to-synthesis capabilities and Switzerland's aseptic fill-finish capacity complete the geographic mosaic of semaglutide active pharmaceutical ingredient production.
United States
Metabolic disease clinics in the United States drive the highest absolute volumes of once-weekly injectable semaglutide API procurement. FDA peptide drug substance guidance enforces stringent endotoxin and impurity thresholds for parenteral peptide products. The Greater Boston corridor hosts concentrated contract development organizations specializing in solid-phase peptide synthesis scale-up.
China
Domestic formulation facilities for oral semaglutide tablets are accelerating sponsor qualification under harmonized NMPA GB standards. China's NMPA has aligned recombinant peptide production protocols with ICH Q7 to reduce cross-border shipment delays. The Yangtze River Delta region clusters large-scale fermentation capacity for GLP-1 receptor agonist precursor production.
Germany
European hospital networks enforce batch-to-batch consistency requirements that shape supplier qualification timelines for semaglutide API. EMA chemistry-manufacturing-controls documentation standards for starting material provenance tighten traceability obligations. The Rhine-Main metropolitan area concentrates aseptic fill-finish infrastructure for lyophilized peptide parenterals.
Switzerland
Premium-margin peptide API production for self-administration devices flows through Swiss manufacturing bases with established cold-chain logistics. Swissmedic oversight of biologics manufacturing maintains alignment with EMA impurity specifications. The Basel region anchors European supply security for multi-kilogram peptide batches requiring geographic proximity to formulation specialists.
India
Cost-competitive fermentation capabilities position Indian manufacturers for post-patent generic API volume shifts. CDSCO active substance master file protocols add layered compliance obligations for cross-border shipments targeting oral tablet formulation. The Hyderabad-Bengaluru corridor sustains domestic peptide synthesis capacity coupled with streamlined DMF filing procedures.
Semaglutide API Market Competitive Landscape
Multi-year supply agreement concentration dominates the current landscape as branded drug sponsors lock in fermentation and solid-phase synthesis capacity ahead of patent cliffs. The vendor base organizes around three strategic archetypes: European CDMOs with hybrid recombinant-synthesis capabilities, Indian manufacturers with cost-optimized fermentation infrastructure, and specialized peptide synthesis houses with large-scale SPPS installations. Capacity expansion and strategic partnership formation constitute the dominant competitive moves as sponsors seek to diversify beyond single-origin supply.
Within the European CDMO tier, Bachem exemplifies large-scale solid-phase synthesis infrastructure anchoring regional supply security. Among Indian manufacturers, Dr. Reddy's Laboratories occupies a position representing cost-competitive fermentation-to-synthesis capabilities. Teva sits within the generic API qualification pathway archetype, positioning for post-patent volume shifts through established regulatory filing procedures.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories |
| Anthem Biosciences |
| Bachem |
| Viruj Pharmaceutical |
| Zabcbio |
| AmbioPharm |
| Teva |
| ZPC Peptide |
| Rochem International |
| Others |
Pricing and Supply Chain Analysis
Protected amino acid derivatives originating from European and Japanese chemical suppliers cascade through three pricing tiers before reaching formulation sponsors, with FDA-tier certification commanding premium multiples over standard-grade peptide inputs destined for research-use-only channels.
Pricing Analysis
High-volume fermentation-based API procurement anchors the mid-market, while precision solid-phase synthesis batches capture premium margins through 98.5% purity guarantees and endotoxin documentation. Price differentiation separates GMP-certified European CDMO supply from Indian cost-optimized fermentation output, with the former embedding Swissmedic-aligned impurity testing costs. Cost compression in standard-grade peptide intermediates is intensifying because Chinese manufacturers are expanding recombinant capacity under harmonized NMPA GB standards. Hospital group purchasing organizations exhibit the sharpest price sensitivity due to bundled procurement mandates, whereas specialty distributors serving homecare channels absorb margin erosion through cold-chain service premiums.
Supply Chain Analysis
FDA and EMA peptide drug substance qualification gates concentrate viable API supply in Switzerland, Germany, and India, where CDMOs maintain simultaneous compliance with dual-hemisphere impurity specifications. The production network draws from protected amino acid feedstock held by Japanese and European chemical specialists, with resin substrates for solid-phase synthesis flowing through limited German suppliers. Single-source vulnerability pervades proprietary E. coli strain banks held by concentrated contract development organizations. Distribution runs through specialty pharmaceutical distributors that bundle cold-chain logistics with inventory management for mid-sized health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semaglutide API procurement is hardening into a vertical-integration race as sponsors pursue captive fermentation capacity to secure supply continuity ahead of patent cliffs.
For Market Incumbents: Anticipate margin compression from Indian manufacturers qualifying under streamlined CDSCO active substance master file protocols by locking multi-year supply agreements with European CDMOs possessing hybrid recombinant-synthesis capabilities. Prioritize backward integration into protected amino acid precursor production to reduce exposure to Japanese and German chemical supplier concentration. For New Entrants and Emerging Players: Begin with oral tablet absorption enhancer convergence as the most penetrable white space, where SNAC co-formulation complexity preserves premium margins beyond injection-commoditized segments. Target Chinese domestic formulation facilities accelerating under NMPA GB standards harmonization, leveraging local fermentation capacity in the Yangtze River Delta region. Pursue qualification partnerships with Swiss aseptic fill-finish specialists as the differentiated go-to-market anchor. For Investors and Strategic Acquirers: FDA peptide drug substance guidance revisions tightening endotoxin thresholds are the leading indicator that synthetic manufacturing infrastructure scarcity will deepen. Long-term viability favors vertically integrated assets spanning fermentation through finished dosage form release, with European CDMOs possessing EMA-aligned documentation standards representing the optimal acquisition archetype. Watch for NMPA impurity specification divergence from FDA limits as the signal warranting dual-qualification cost model reassessment.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Multi-kilogram peptide batch production at single sites reduces geographic fragmentation between fermentation and synthesis specialists. |
| Regulatory Approval Pathway | Simultaneous FDA and NMPA active substance master file filings compress cross-border shipment qualification timelines. |
| Long-term Supply Agreement | Branded drug sponsors lock in solid-phase synthesis capacity ahead of patent cliffs to secure volume allocation. |
| Backward Integration | Captive protected amino acid production reduces input cost volatility from concentrated European and Japanese chemical suppliers. |
| Joint Venture | Swiss-Indian partnerships combine aseptic fill-finish expertise with cost-competitive fermentation infrastructure for oral tablet output. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced against primary interviews with peptide synthesis directors, regulatory affairs leads at CDMOs, hospital procurement managers, and formulary access specialists. FDA peptide drug substance guidance documents, EMA chemistry-manufacturing-controls submissions, NMPA GB standard protocols, and CDSCO active substance master file records supplied compliance benchmarks. Bottom-up capacity assessments at contract manufacturing facilities were triangulated against top-down prescription volume projections across metabolic disease channels.
Granularity-level modeling tracked product type, formulation complexity, end-user channel, and geographic regulatory cluster throughout the projection horizon. Subcutaneous injection purity protocols, oral tablet absorption enhancer specifications, and lyophilized vial packaging requirements were modeled as distinct value pools. CAGRs were derived from prescription volume trajectories in obesity management and type 2 diabetes populations, cross-referenced against API procurement patterns from disclosed supply agreements.
Patent litigation outcomes, NMPA-FDA impurity specification divergence, and E. coli strain bank contamination events are the dominant revision risks to forecast assumptions. A model refresh is warranted upon material change in regulatory alignment between US and Chinese peptide drug substance standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
Apixaban Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Injectable Drugs Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Hepatitis C Drug Market