
 Fluidized Bed Reactors Market | 2026-2036
Fluidized Bed Reactors Market Size, Share, and Industry Trends Forecast 2026-2036
Fluidized Bed Reactors Market Analytics
EPA Maximum Achievable Control Technology standards for hazardous air pollutants is restructuring capital planning across chemical processing facilities, compelling operators to replace legacy fixed-bed systems with fluidized bed alternatives that offer superior thermal uniformity and lower emissions profiles. Glatt Process Technology GmbH leverages its deep specialization in pharmaceutical granulation and coating systems to anchor premium positioning in regulated drug manufacturing environments. Buhler AG sustains broad geographic coverage through integrated drying and calcination platforms serving food and minerals clients across European and Asian production hubs.
Fluidized bed reactors suspend solid particulate material in an upward-flowing gas or liquid stream, creating a turbulent bed that achieves exceptional heat and mass transfer rates with typical operating temperatures ranging from 300°C to 1,100°C depending on the process chemistry. This configuration serves as the core unit operation for catalytic cracking, combustion, gasification, and pharmaceutical granulation where precise temperature control directly determines product quality and yield. Circulating fluidized bed systems dominate utility-scale power and petrochemical applications due to their capacity for continuous solids recirculation and fuel flexibility, while bubbling bed configurations occupy niche positions in batch pharmaceutical processing where containment and cleanability govern equipment selection. Granulation technology within pharmaceutical end-user segments represents the fastest-expanding margin pool as contract manufacturers invest in contained fluidized bed lines to meet FDA and EMA containment guidelines for potent active pharmaceutical ingredients.
FDA Current Good Manufacturing Practice regulations for pharmaceutical equipment validation, combined with EMA guidelines on containment strategy for highly potent compounds, create dual compliance thresholds that filter out smaller equipment fabricators lacking documented quality management systems. China's NMPA implementation of Good Manufacturing Practice Annex 1 revisions for sterile manufacturing further extends regulatory reach into biopharmaceutical fluidized bed drying operations, reshaping supplier qualification protocols for multinational drug companies. Stakeholders must monitor evolving emissions thresholds from EPA and MEE while calibrating R&D spending toward modular reactor skids that reduce on-site installation complexity and accelerate regulatory commissioning timelines.
Market Dynamics
EPA Maximum Achievable Control Technology standards for hazardous air pollutants compel chemical processors to replace legacy fixed-bed systems with fluidized bed alternatives that deliver superior thermal uniformity and lower emissions profiles. This regulatory pressure cascades through capital planning cycles, favoring reactor configurations with documented emissions performance and modular installation architectures.
Growth Catalysts
- Pharmaceutical containment mandates:FDA Current Good Manufacturing Practice regulations and EMA guidelines on highly potent compound containment drive contract manufacturers toward contained fluidized bed lines with validated cleanability protocols.
- Germany's industrial decarbonization:The country's chemical processing cluster invests in fluidized bed gasification and combustion systems to meet EU Green Deal emissions reduction trajectories while maintaining process intensity.
- Continuous processing adoption:Circulating fluidized bed technology enables petrochemical operators to shift from batch to continuous catalytic cracking, improving yield consistency and reducing thermal cycling damage to reactor vessels.
Market Restraints
- Specialized refractory material costs:High-purity alumina and silicon carbide linings required for thermal shock resistance at 1,100°C operating regimes face supply concentration among limited specialty ceramic producers.
- Validation documentation burdens:FDA and EMA equipment qualification requirements for pharmaceutical applications impose 18-24 month commissioning timelines that deter mid-scale fabricators from entering regulated end-use segments.
- Fixed-bed substitution in niche applications:Microchannel reactor technology captures select high-value pharmaceutical synthesis applications where extreme temperature precision outweighs fluidized bed throughput advantages.
Strategic Opportunities
- India's API manufacturing expansion:The country's pharmaceutical sector under CDSCO oversight is retrofitting drying and granulation capacity to serve export markets requiring FDA-equivalent containment standards.
- Biopharmaceutical fluidized bed drying:China's NMPA Annex 1 revisions for sterile manufacturing create qualified supplier opportunities for contained reactor systems in vaccine and biologic production.
- Modular skid architectures:Pre-fabricated reactor units with integrated controls reduce on-site installation complexity and accelerate regulatory commissioning for multi-site pharmaceutical operators.
Industry Challenges
- Multiphase flow modeling expertise:Computational fluid dynamics simulation of turbulent bed behavior requires specialized talent pools concentrated among academic research centers and Tier 1 engineering firms.
- Legacy system integration:Brownfield chemical facilities face mechanical and control interface mismatches when retrofitting fluidized bed units into existing fixed-bed infrastructure with decades-old distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluidized Bed Reactors Market |
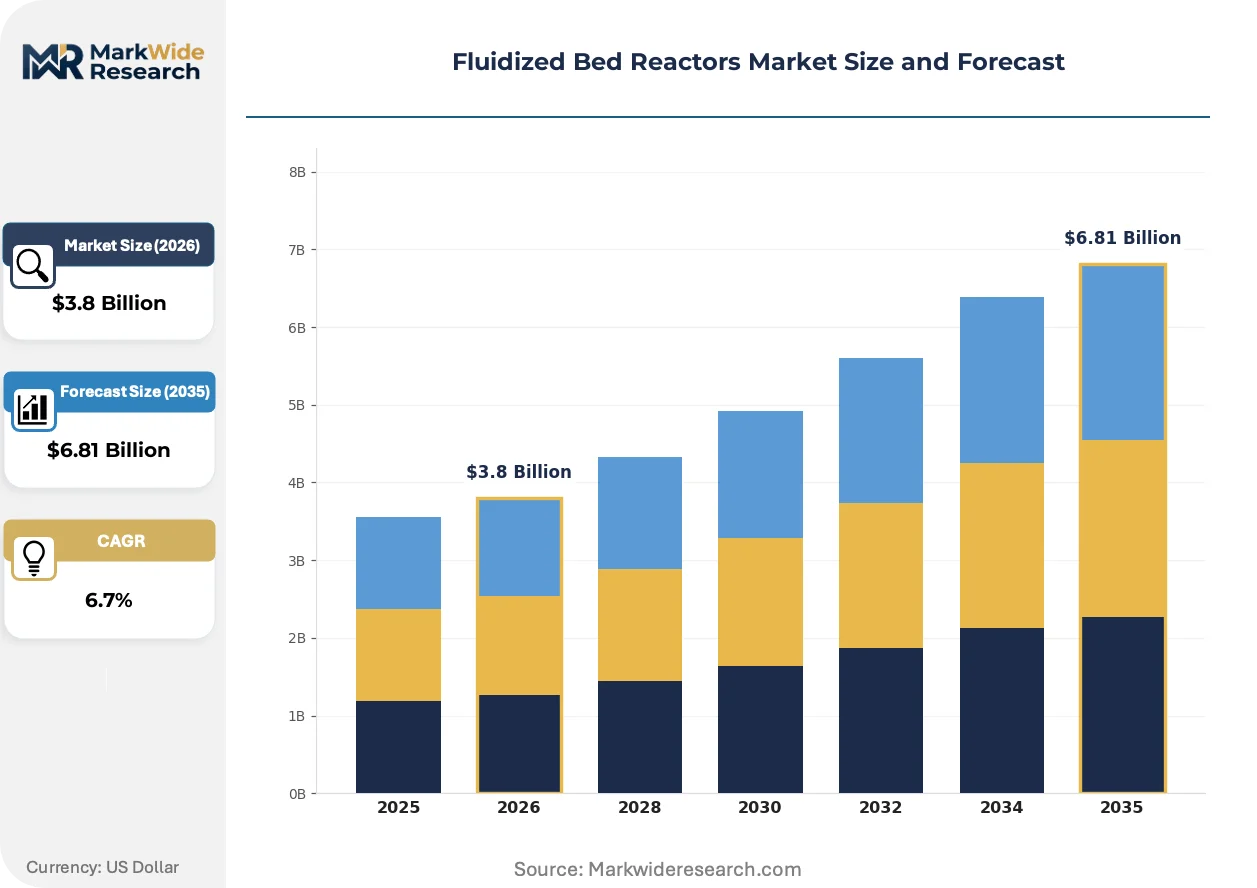
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Bubbling, Circulating, Moving Bed, Spouted Bed Application: Chemical Processing, Pharmaceuticals, Food Processing, Waste Treatment End User: Chemical Plants, Pharmaceutical Companies, Food Industries, Research Labs Technology: Drying, Granulation, Coating, Calcination |
| Companies Covered | ThyssenKrupp KH Mineral SAS, Hazemag & EPR GmbH, Andritz AG, Envirogen Group, Anivi Ingenieria SA, Glatt Process Technology GmbH, GEA Process Engineering A S, Carrier Europe SCA, Buhler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluidized Bed Reactors Market Evolving Landscape
Reactor engineering is converging with digital twin capabilities and advanced materials science to compress design validation cycles and extend operating envelopes. Equipment suppliers now embed predictive maintenance algorithms and real-time emissions monitoring to differentiate in regulated procurement environments.
Additive-manufactured reactor internals with complex gas distributor geometries are absorbing market share from conventional drilled-plate designs in pharmaceutical granulation applications. Contract manufacturers in Switzerland and Germany adopt these components to achieve particle size distribution precision required for controlled-release oral solid dosage forms. The technology is absorbing premium positioning in FDA-regulated environments where batch reproducibility determines supplier qualification status.
REACH authorization requirements for persistent organic pollutants in chemical processing catalysts are forcing reformulation of traditional cracking catalysts toward zeolite-based alternatives with lower environmental persistence. European petrochemical operators face 2026-2028 sunset dates for legacy catalyst systems, accelerating fluidized bed reactor reconfiguration projects. The regulation most affects fluid catalytic cracking units in Germany and the Netherlands, where operators pre-qualify catalyst suppliers against evolving ECHA substance restrictions.
After-sales service unbundling is fragmenting traditional equipment procurement relationships as pharmaceutical buyers separate reactor hardware from validation documentation and ongoing technical support. Large contract manufacturers in India and China now source bare vessels from fabricators while retaining specialized engineering consultancies for FDA and EMA qualification packages. This pattern concentrates margin capture among documentation specialists and erodes bundled pricing power for integrated equipment suppliers.
Fluidized Bed Reactors Market Segmentation
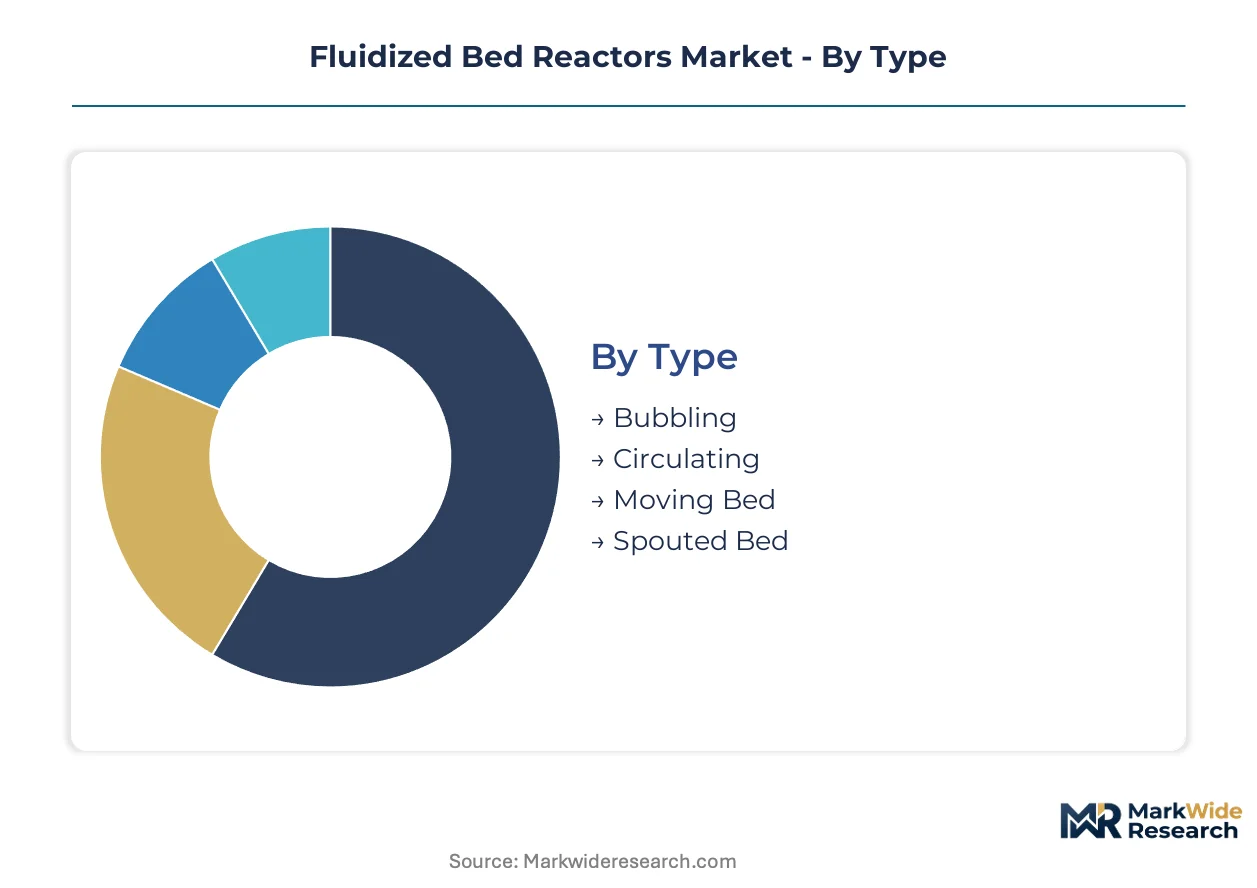
Fluidized bed reactor configurations vary dramatically in integration complexity, from standalone batch units for pharmaceutical containment to fully embedded continuous systems in petrochemical complexes. Segmentation reveals where capital concentrates versus where technology is displacing legacy alternatives.
Type:
Standalone bubbling bed systems serve discrete batch operations, while circulating configurations embed into continuous process trains with extensive upstream and downstream equipment.
- Bubbling:Gas passes through a distributor plate at velocities sufficient to fluidize particles without entrainment, creating a dense turbulent bed ideal for uniform heat transfer. Demand clusters in pharmaceutical manufacturing across Germany and Switzerland, where FDA and EMA containment mandates for potent active pharmaceutical ingredients favor contained batch processing with validated cleanability protocols.
- Circulating:High gas velocities transport solids through a riser and external recirculation loop, enabling continuous operation with fuel flexibility across coal, biomass, and waste feedstocks. Utility-scale power operators in China deploy these systems under MEE emissions standards that reward thermal uniformity and lower NOx profiles compared to pulverized coal alternatives.
- Moving Bed:Solids descend by gravity against upward gas flow in structured zones, offering precise residence time control for catalytic processes with defined reaction kinetics.
- Spouted Bed:A central high-velocity jet creates a fountain-like particle circulation pattern, serving agricultural drying and coarse particle processing where standard fluidization mechanics prove ineffective.
Volume placements concentrate in Circulating systems; the faster expansion belongs to Bubbling configurations in pharmaceutical contract manufacturing.
Application:
Cost tier separation distinguishes commodity chemical processing from regulated pharmaceutical environments where validation documentation commands substantial price premiums.
- Chemical Processing:Catalytic cracking, combustion, and gasification operations in petrochemical complexes rely on fluidized beds for thermal efficiency and feedstock flexibility. Capital deployment tracks EPA Maximum Achievable Control Technology compliance timelines, with operators replacing fixed-bed units to meet hazardous air pollutant standards.
- Pharmaceuticals:Granulation and coating operations for oral solid dosage forms require contained fluidized bed lines with documented cleanability under FDA Current Good Manufacturing Practice regulations. Swiss and German contract manufacturers absorb premium pricing for systems pre-qualified against EMA containment guidelines for highly potent compounds.
- Food Processing:Drying and agglomeration of powders, grains, and nutritional ingredients employs gentle fluidization to preserve heat-sensitive compounds and functional properties.
- Waste Treatment:Thermal destruction of hazardous and municipal waste streams exploits fluidized bed temperature uniformity to achieve complete combustion with minimal residual ash.
Revenue concentration sits with Chemical Processing; margin expansion is steepest in Pharmaceuticals where regulatory qualification creates supplier stickiness.
End User:
Customer type determines procurement sophistication, from multinational pharmaceutical quality systems to research laboratory flexibility requirements.
- Chemical Plants:Integrated petrochemical and specialty chemical operators specify fluidized beds for continuous catalytic processes with decades-long asset horizons. Brownfield integration challenges dominate capital planning, as legacy distributed control systems require mechanical and interface modifications to accommodate modern reactor units.
- Pharmaceutical Companies:Multinational drug manufacturers and contract development organizations demand pre-validated equipment packages with documented installation and operational qualification under FDA and EMA frameworks. India's API manufacturing expansion under CDSCO oversight is retrofitting drying capacity to serve export markets requiring FDA-equivalent containment standards.
- Food Industries:Nutrition and ingredient processors prioritize hygienic design and rapid product changeover for diversified SKU portfolios.
- Research Labs:Academic and pilot-scale facilities require modular, skid-mounted units with broad operating envelope flexibility for process development and catalyst screening.
Procurement scale peaks at Chemical Plants; the fastest share gains are occurring among Pharmaceutical Companies as outsourcing consolidates manufacturing footprint.
Technology:
Maturity gradients separate established drying operations from emerging coating applications where precision requirements enable technology premiums.
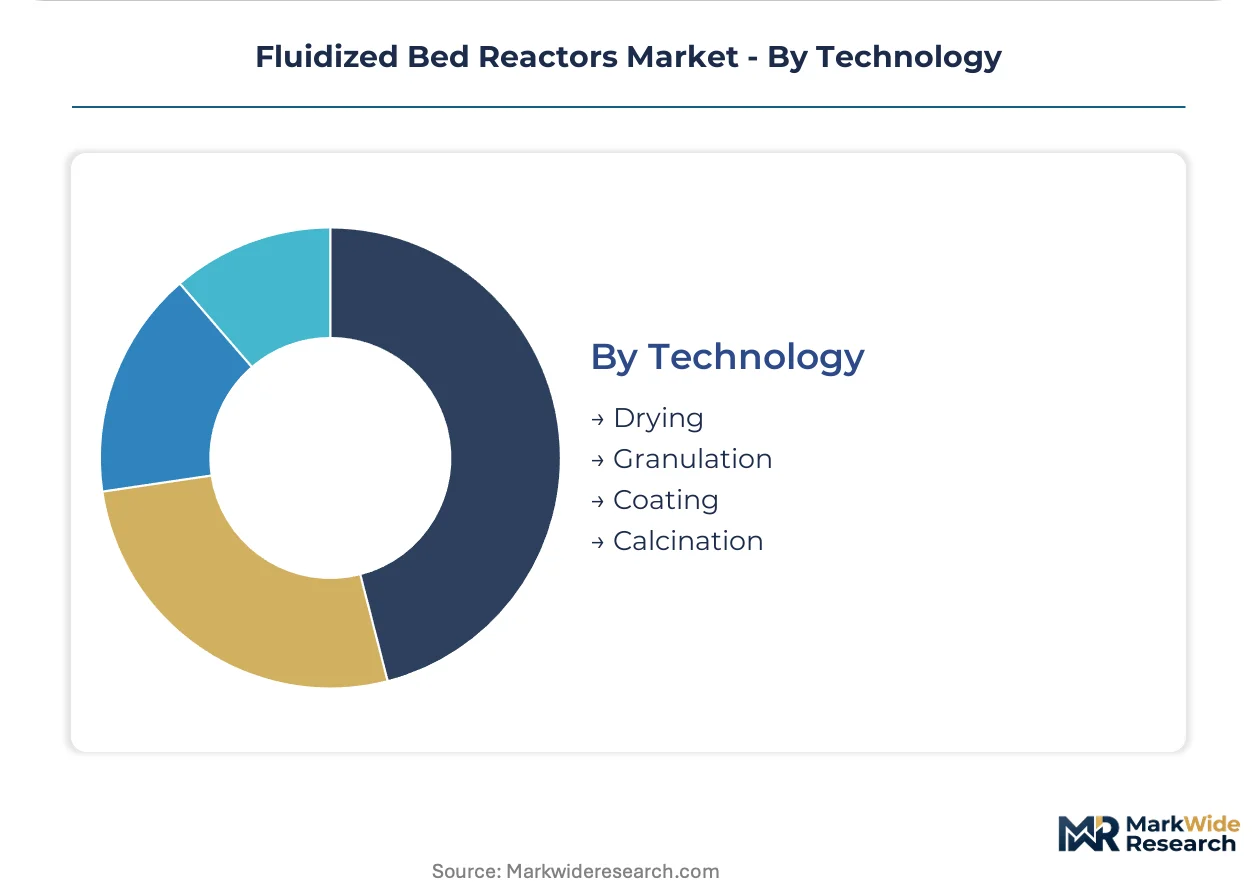
- Drying:Removal of moisture or solvents from particulate solids through heated fluidizing gas represents the most deployed fluidized bed operation. China's NMPA Annex 1 revisions for sterile manufacturing are reshaping supplier qualification for biopharmaceutical drying systems.
- Granulation:Agglomeration of fine powders into uniform granules through binder addition and controlled liquid distribution achieves precise particle size distribution for controlled-release drug formulations. Additive-manufactured gas distributor geometries are displacing conventional drilled plates in Swiss and German facilities where batch reproducibility determines FDA qualification status.
- Coating:Application of functional polymer films onto granules or tablets for taste masking, moisture protection, or controlled release represents the most technically demanding fluidized bed operation.
- Calcination:High-temperature thermal decomposition of minerals and catalyst precursors at 800-1,100°C requires specialized refractory linings and heat recovery integration.
Installed base dominance rests with Drying; the steepest expansion trajectory is occurring in Granulation as controlled-release oral solid dosage forms gain therapeutic preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in India and China's Yangtze River Delta concentrate fluidized bed reactor investment through tax incentives and streamlined environmental permitting. Germany's industrial clusters and Switzerland's pharmaceutical hubs anchor European demand. The United States maintains chemical processing leadership through Gulf Coast petrochemical complexes.
Germany
Chemical processing decarbonization and pharmaceutical contract manufacturing drive fluidized bed reactor procurement in the Rhine-Ruhr and Bavarian industrial corridors. EU Green Deal emissions trajectories compel operators to replace legacy fixed-bed systems with fluidized bed alternatives. The Leverkusen-Düsseldorf chemical cluster hosts multiple catalytic cracking retrofits under ECHA REACH catalyst reformulation deadlines.
China
Utility-scale power generation and petrochemical expansion absorb circulating fluidized bed systems across Shandong and Jiangsu provinces. MEE emissions standards for thermal power plants reward thermal uniformity and lower NOx profiles compared to pulverized coal alternatives. The Ningbo-Zhoushan petrochemical base commissions continuous catalytic cracking units to serve polymer export markets.
India
API manufacturing expansion and sterile pharmaceutical drying operations concentrate demand in Maharashtra and Gujarat Special Economic Zones. CDSCO oversight aligns domestic GMP standards with FDA export requirements, compelling containment system upgrades. The Hyderabad-Visakhapatnam pharmaceutical corridor retrofits fluidized bed granulation capacity for controlled-release oral solid dosage production.
Switzerland
Precision pharmaceutical granulation and coating operations sustain premium equipment demand across Basel and Zurich manufacturing hubs. Swissmedic regulations for highly potent compound containment validate specialized reactor configurations. The Basel biopharmaceutical cluster adopts additive-manufactured gas distributors to achieve particle size distribution precision for FDA-regulated markets.
United States
Petrochemical complex expansion and hazardous air pollutant compliance reshape capital planning across Texas and Louisiana Gulf Coast facilities. EPA Maximum Achievable Control Technology standards drive fixed-bed replacement with fluidized bed systems offering documented emissions performance. The Houston Ship Channel chemical corridor integrates modular reactor skids to accelerate commissioning timelines under consolidated environmental permits.
Fluidized Bed Reactors Market Competitive Landscape
German and Swiss producers anchor the premium-tier equipment segment; Chinese and Indian fabricators hold volume positions in standardized reactor configurations. Market structure reflects a bifurcated supplier base where regulatory qualification capabilities separate documented quality system holders from commodity fabricators. Three archetypes dominate: integrated process technology conglomerates with pharmaceutical validation expertise, specialized drying and calcination equipment builders, and regional engineering fabricators serving chemical processing brownfield retrofits. Competitive dynamics center on modular skid architectures that compress installation timelines and strategic partnerships with catalyst suppliers to bundle reactor-catalyst packages.
Within the pharmaceutical-specialist tier, Glatt Process Technology GmbH and Buhler AG exemplify integrated equipment-validation service providers with established FDA and EMA qualification track records. Hazemag & EPR GmbH represents the industrial minerals and chemical processing archetype with heavy-duty reactor fabrication capabilities. ThyssenKrupp KH Mineral SAS anchors the multinational conglomerate position, leveraging cross-divisional engineering resources for large-scale petrochemical and power generation deployments. These three company structures illustrate how geographic origin and corporate form factor into procurement segmentation across regulated versus commodity end-use environments.
| Leading Market Players |
|---|
| ThyssenKrupp KH Mineral SAS |
| Hazemag & EPR GmbH |
| Andritz AG |
| Envirogen Group |
| Anivi Ingenieria SA |
| Glatt Process Technology GmbH |
| GEA Process Engineering A S |
| Carrier Europe SCA |
| Buhler AG |
| Others |
Value Network & Pricing Analysis
Specialized refractory material costs for high-purity alumina and silicon carbide linings trace a direct path from limited specialty ceramic producers in Germany and Japan through to premium pricing tiers for pharmaceutical-grade bubbling bed systems, while standardized circulating configurations for Chinese utility operators absorb commodity-grade inputs at compressed margins.
Pricing Analysis
Short lead-time premiums of 15-25% apply to pre-validated pharmaceutical skids with documented FDA installation qualification packages, whereas spot inventory of bare vessels without validation documentation trades at standard contract rates. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-contained granulation lines with additive-manufactured distributors from mid-tier Indian API drying systems and economy-grade chemical processing retrofits. Price differentiation hinges on EMA containment certification tier and after-sales service bundling, with unbundling trends eroding integrated supplier pricing power. Cost compression in the economy tier is intensifying because Chinese fabricators are absorbing commodity circulating bed volumes without validation service attachments.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston maintain finished reactor inventory for chemical processing brownfield retrofits, with hub-and-spoke patterns radiating to Gulf Coast petrochemical corridors and Rhine-Ruhr industrial clusters. Manufacturing concentrates in Germany for pharmaceutical-specialist equipment, China for utility-scale circulating systems, and India for mid-tier API manufacturing retrofits. Raw material flows draw from Norwegian silicon carbide for high-temperature linings, Chinese rare earth catalyst precursors, and specialty steel from Japanese mills. Single-source vulnerability sits with European REACH-authorized catalyst suppliers facing sunset deadlines. Distribution runs through engineering-procurement-construction contractors for large petrochemical deployments and direct OEM relationships for pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as equipment suppliers pursue captive catalyst formulation capabilities to bundle reactor-catalyst packages and defend margin erosion from unbundled procurement patterns.
For Market Incumbents: Lock in catalyst supplier exclusivity agreements before REACH reformulation deadlines consolidate supplier pools, and acquire specialized engineering consultancies in India to capture unbundled validation documentation revenue. Microchannel reactor technology threatens high-value pharmaceutical synthesis niches where temperature precision outweighs fluidized bed throughput. Backward integration into additive-manufactured gas distributor production anchors batch reproducibility advantages in FDA-regulated environments. For New Entrants and Emerging Players: Additive-manufactured reactor internals with complex distributor geometries offer a technology-first wedge into Swiss and German pharmaceutical granulation markets where particle size distribution precision commands supplier qualification status. India's CDSCO-aligned API manufacturing expansion presents the most penetrable geography, with modular skid architectures for multi-site pharmaceutical operators offering the clearest go-to-market angle against entrenched European incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized drying equipment fabricators in India with CDSCO qualification track records and established FDA export relationships. Long-term viability over a five-to-ten-year window rests on regulatory qualification capabilities rather than commodity fabrication scale. The signal to watch is NMPA Annex 1 enforcement intensity in China's biopharmaceutical corridor, which would accelerate contained system demand and validate premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Formulation | Bundles reactor-catalyst packages under REACH reformulation deadlines affecting German crackers. |
| Modular Skid Architecture Deployment | Compresses commissioning timelines for Indian pharmaceutical operators under CDSCO oversight. |
| Additive Manufacturing Capability Acquisition | Captures particle precision requirements for FDA-regulated Swiss granulation contracts. |
| Validation Documentation Unbundling Response | Defends margin erosion from Indian contract manufacturers sourcing bare vessels separately. |
| Regional Distribution Center Expansion | Reduces lead times for Houston Ship Channel chemical corridor brownfield retrofits. |
Research Methodology
Trade databases, ECHA substance restriction filings, and SEC equipment supplier disclosures formed the secondary backbone, supplemented by primary interviews with pharmaceutical plant engineers, chemical processing procurement leads, EPC contractors, and aftermarket service heads. Bottom-up and top-down triangulation validated volume estimates across reactor configurations and application segments.
Bottom-up modeling anchored installed base counts by configuration type, while top-down cross-checks referenced capital expenditure patterns across petrochemical and pharmaceutical end-use industries. Segmentation dimensions included reactor type, application, end-user category, technology, and regional regulatory cluster. CAGRs were derived from regression analysis of historical replacement cycles and projected compliance-driven retrofit timelines, with specific inputs from EPA MACT enforcement schedules and EMA containment guideline revision patterns.
Several conditions sit outside the modeled scope, including unannounced regulatory deadline shifts, breakthrough microchannel reactor scale-up, and extreme commodity volatility in specialty ceramic feedstocks. Forecasts reflect documented assumptions about compliance timeline adherence and technology substitution elasticities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
Well Stimulation Materials Sales Market
Industrial Chemicals
Global Itaconic Acid Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Mining Chemicals Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Global Ethiprole Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
Thermally Stable Antiscalant Market