
 Diisononyl Adipate (DINA) Market | 2026-2036
Diisononyl Adipate (DINA) Market Size, Share, and Industry Trends Forecast 2026-2036
Diisononyl Adipate (DINA) Market Intelligence
China is reconfiguring Asia-Pacific supply dynamics through new adipic acid and esterification capacity additions in Ningbo and Shanghai. BASF SE leverages backward integration into adipic acid to secure feedstock margins across European compounding operations. Evonik Industries AG sustains specialty-grade DINA output for medical and food-contact applications with tight viscosity specifications. Eastman Chemical Company anchors North American supply through Kingsport, Tennessee manufacturing, while KLJ Group competes on volume flexibility for South Asian cable and wire jacketing customers.
Diisononyl adipate is a C9-branched dialkyl ester of adipic acid, synthesized through esterification of adipic acid with isononanol, yielding a colorless oily liquid with viscosity around 15-25 mPa·s at 25°C and a pour point below -60°C. Its primary industrial purpose centers on plasticizing polyvinyl chloride and synthetic rubber compounds where low-temperature flexibility and migration resistance prove critical. Plasticizers dominate value capture due to PVC compounding scale, while coatings applications in automotive refinish and industrial maintenance represent the fastest-growing consumption pool as VOC regulations tighten. Waterborne formulation types are gaining share in European and North American construction adhesives, though solvent-based systems still occupy margin-rich niche segments in aerospace sealants.
REACH registration requirements and the EU F-Gas Regulation indirectly steer plasticizer selection toward non-phthalate alternatives including DINA in HVAC and automotive systems. The US EPA and FDA maintain separate jurisdiction over industrial chemical use versus food-contact applications, creating a dual compliance burden for suppliers serving both channels. China's MEE enforces GB standards on plasticizer emissions from coating and adhesive manufacturing, raising technical barriers for imported material. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation timelines and certificate-of-analysis requirements.
Market Dynamics
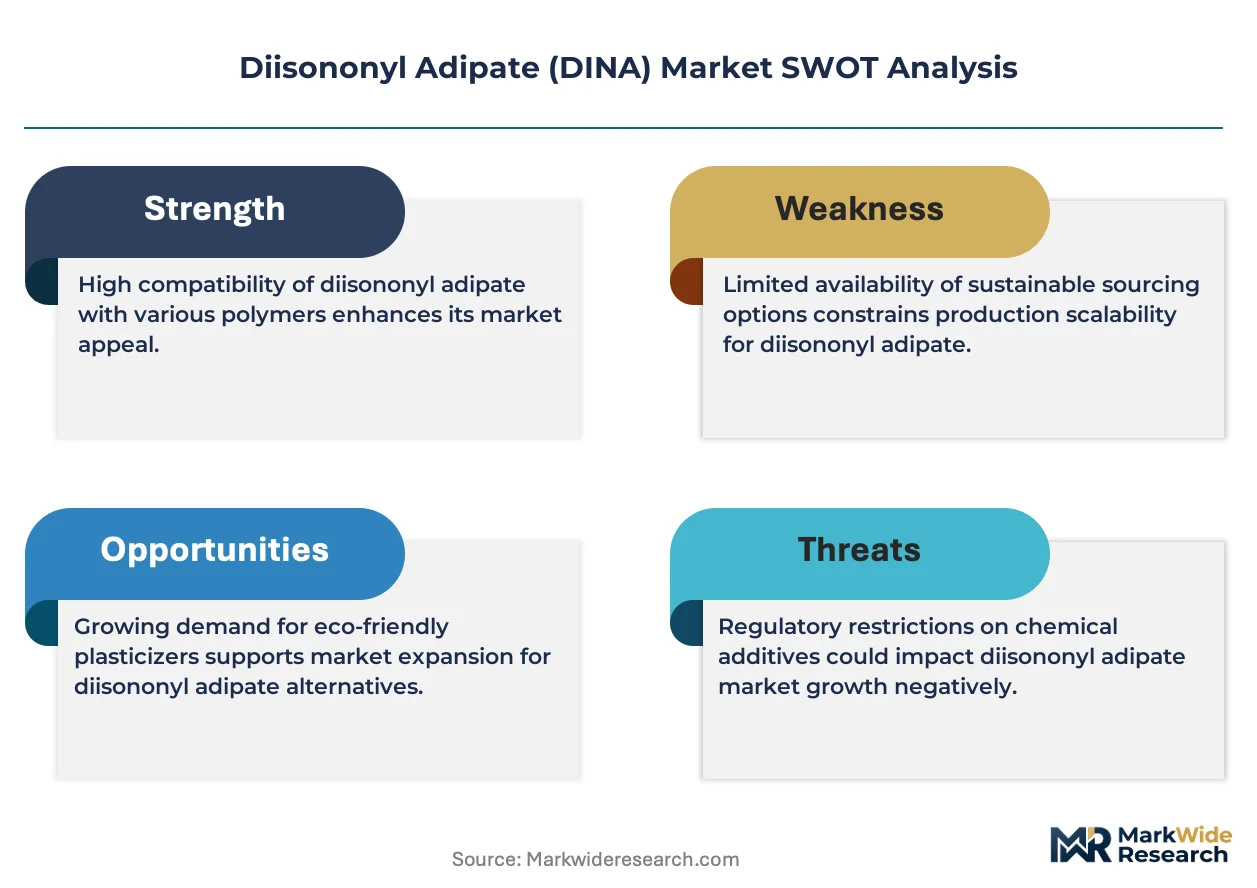
REACH restrictions on phthalate plasticizers are redirecting compounder procurement toward adipate esters, restructuring formulation chemistry across European automotive and construction supply chains while tightening feedstock control among integrated adipic acid producers.
Growth Catalysts
- REACH Phthalate Bans:ECHA restrictions on DEHP and DINP in consumer goods are forcing PVC compounders toward DINA as a technically viable drop-in replacement with comparable low-temperature performance.
- Automotive Interior Specifications:OEMs in Germany and the US are expanding DINA adoption in dashboard and door panel PVC formulations to meet volatile organic compound emission targets.
- Adipic Acid Capacity Expansion:New esterification investments in Ningbo and Shanghai are improving Asia-Pacific supply security and reducing regional import dependence.
Market Restraints
- Cyclohexane Feedstock Volatility:Adipic acid production depends on benzene-derived cyclohexane, exposing DINA margins to petrochemical price swings without long-term offtake contracts.
- European Supply Concentration:BASF SE and Evonik Industries AG control integrated adipic acid-to-ester production in Germany, creating bottleneck risk for non-captive compounders.
- Bio-Based Plasticizer Competition:Epoxidized soybean oil and citrate esters are capturing food-contact and medical device segments where renewable credentials outweigh performance trade-offs.
Strategic Opportunities
- India Cable and Wire Jacketing:KLJ Group volume flexibility positions suppliers to capture infrastructure electrification demand as BIS standards tighten phthalate limits.
- Waterborne Coating Formulations:VOC regulations in the EU and US are accelerating DINA adoption in low-emission automotive refinish and industrial maintenance coatings.
- Medical-Grade Certification:Tight viscosity specifications for food-contact and healthcare applications create margin-rich specialty segments resistant to commodity substitution.
Industry Challenges
- Dual Jurisdiction Compliance:Suppliers serving both industrial and food-contact channels must simultaneously satisfy EPA industrial chemical rules and FDA migration limits, doubling certification timelines.
- Esterification Asset Utilization:Batch-to-continuous process conversion requires capital deployment for heat integration and catalyst recovery systems without guaranteed offtake scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diisononyl Adipate (DINA) Market |
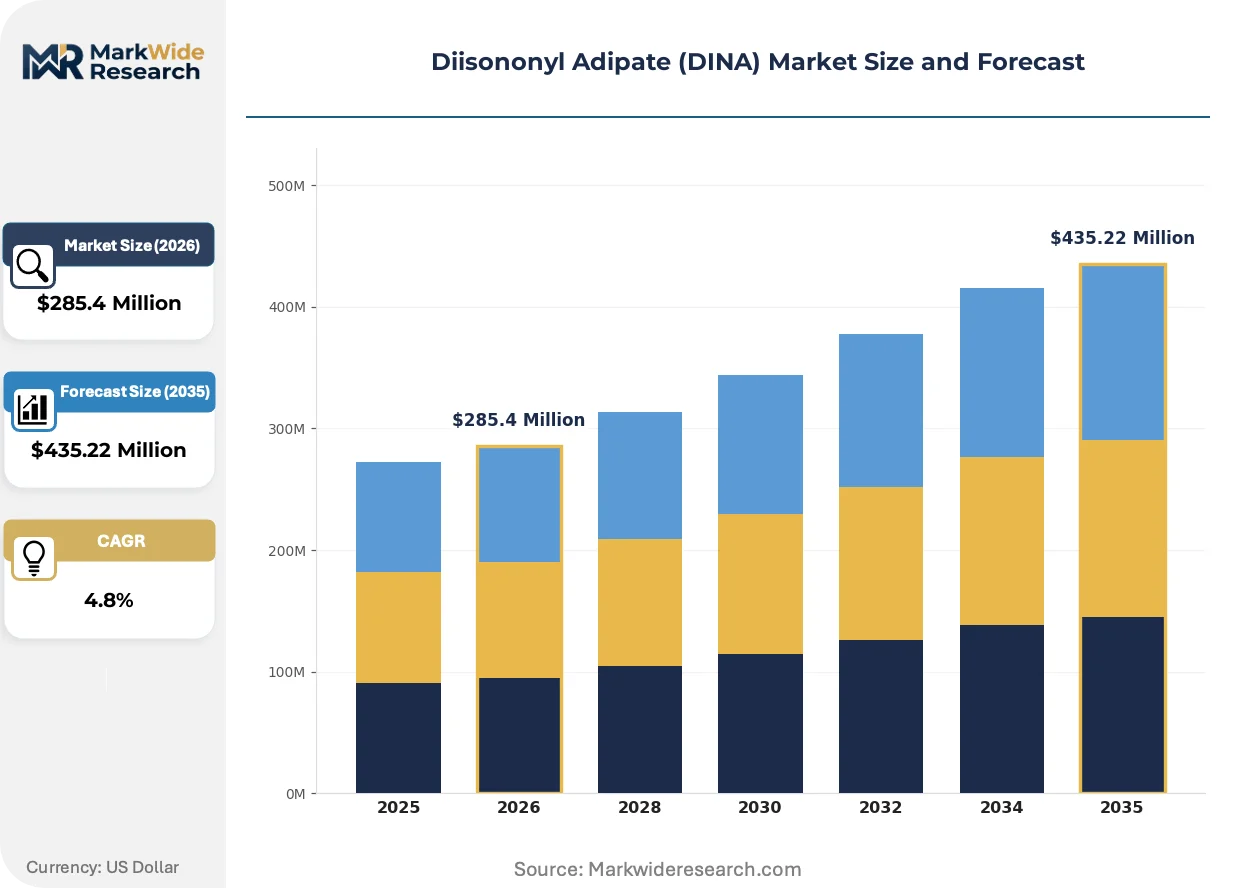
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Coatings, Adhesives, Sealants End Use Industry: Automotive, Construction, Packaging, Consumer Goods Formulation Type: Waterborne, Solvent-based, Hot-melt, UV-cured Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | BASF SE, ExxonMobil Chemical, Evonik Industries AG, Eastman Chemical Company, NAN YA PLASTICS CORPORATION, KLJ Group, Polynt S.p.A., Mitsubishi Chemical Corporation, LG Chem Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diisononyl Adipate (DINA) Market Strategic Shifts & Innovations
Digital formulation platforms are compressing R&D cycles for plasticizer substitution, while regulatory divergence between jurisdictions is fragmenting product specifications and forcing regional SKU proliferation.
Continuous adipic acid production technology is virtualizing traditional batch esterification economics. BASF SE and emerging Chinese producers are adopting catalytic direct oxidation routes that reduce energy intensity and byproduct formation. Automotive OEMs are qualifying output from these assets for interior applications faster than conventional supply. The technology is virtualizing capital barriers that previously protected regional incumbents.
ECHA's F-Gas Regulation and accompanying REACH amendments are tightening migration limits for plasticizers in HVAC systems and refrigeration gaskets. Compounders serving European appliance manufacturers must reformulate with non-phthalate alternatives or exit certified supplier lists. Medical device and food-contact segments are experiencing the most acute compliance pressure due to combined EFSA and EMA jurisdiction.
Specification-driven procurement is consolidating buyer power among tier-one automotive and cable compounders. Long-term offtake agreements with fixed viscosity bands are displacing spot market purchasing for standard-grade material. German and US Gulf Coast compounders are driving this shift to secure supply continuity amid feedstock volatility.
Diisononyl Adipate (DINA) Market Segmentation
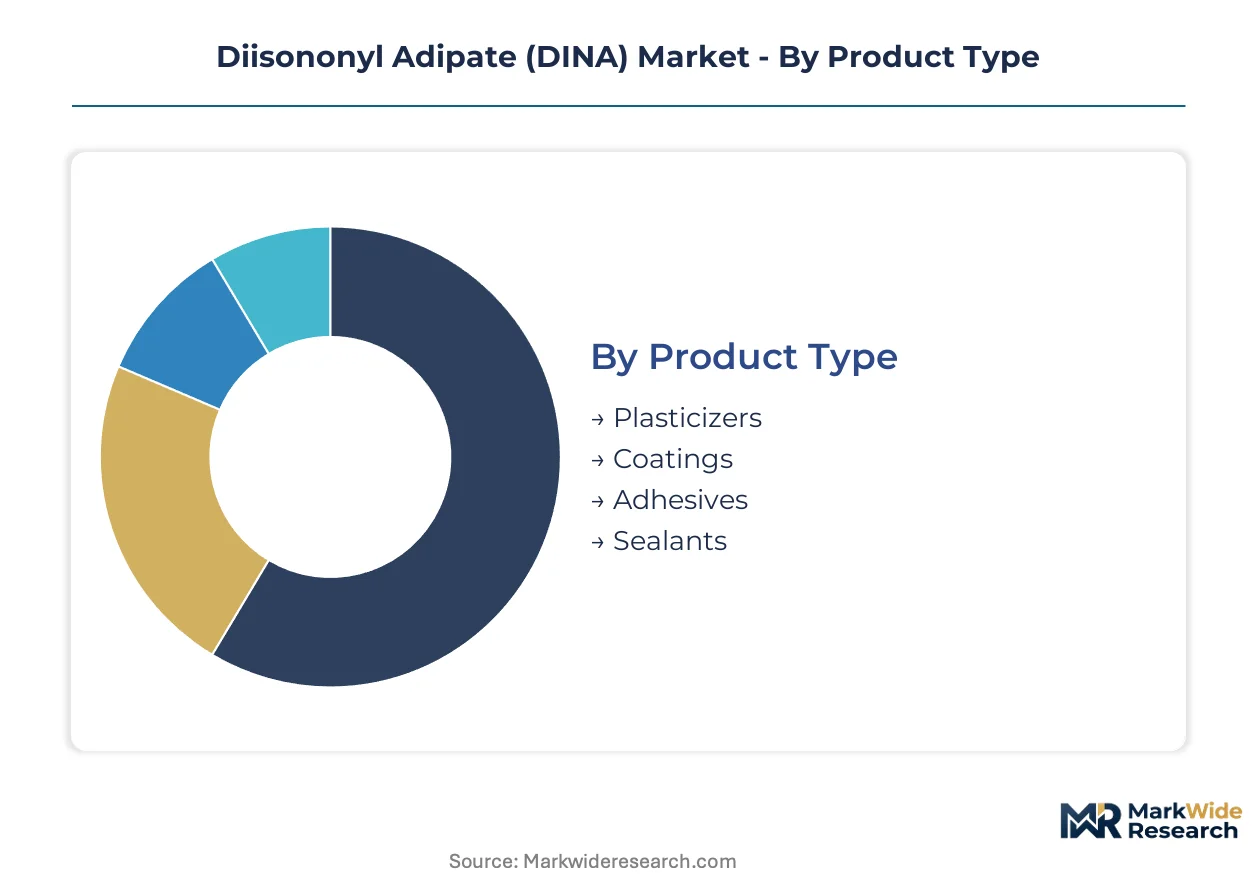
DINA demand fragments across formulation chemistries and procurement channels that reset at different velocities. Plasticizer compounders lock in annual contracts while coating formulators rotate SKU mixes quarterly. Understanding these cycle-time differentials exposes where inventory risk concentrates versus where specification shifts create immediate volume swings.
Product Type:
Plasticizer procurement cycles run 12-18 months with automotive OEMs, while coating and adhesive formulators reset specifications every 6-9 months responding to VOC regulatory deadlines.
- Plasticizers:C9-branched dialkyl ester formulations for PVC compounding dominate tonnage, with viscosity specifications of 15-25 mPa·s at 25°C. Automotive interior applications in Germany and the US are expanding procurement as REACH phthalate bans force reformulation of dashboard and door panel compounds.
- Coatings:Automotive refinish and industrial maintenance applications represent the steepest expansion trajectory as EU and US VOC regulations tighten. Waterborne formulations are displacing solvent systems in European construction adhesives, though aerospace sealants retain margin-rich solvent-based demand.
- Adhesives:Construction and packaging laminates use DINA for low-temperature flexibility. BIS standards in India are tightening phthalate limits for cable jacketing adhesives.
- Sealants:HVAC gaskets and refrigeration systems under ECHA F-Gas Regulation migration limits. EFSA jurisdiction adds compliance burden for food-contact sealant applications.
Plasticizers anchor the volume base while coatings gain share at the steepest rate.
End Use Industry:
Automotive qualification timelines stretch 24-36 months for interior specifications, while construction procurement responds within 6-12 months to building code revisions.
- Automotive:Dashboard, door panel, and wiring harness PVC compounds. OEMs in Germany specify DINA to meet volatile organic compound emission targets.
- Construction:Flooring, wall coverings, and roofing membranes. Ningbo and Shanghai capacity additions are improving Asia-Pacific supply security for regional construction demand.
- Packaging:Food-contact films and laminates requiring tight viscosity specifications. FDA migration limits create dual compliance burden with EPA industrial chemical rules.
- Consumer Goods:Toys, sporting equipment, and household flexible PVC articles. ECHA restrictions on DEHP and DINP are redirecting compounder procurement toward adipate esters.
Automotive commands the longest qualification cycles while construction delivers the most volatile demand swings.
Formulation Type:
Waterborne systems require 18-24 month reformulation investments, whereas UV-cured and hot-melt platforms adapt specifications within 6-12 months.
- Waterborne:Low-emission coatings for European automotive refinish and construction adhesives. MEE enforcement of GB standards on plasticizer emissions raises technical barriers for imported material into China.
- Solvent-based:Aerospace sealants and specialty industrial maintenance coatings where performance trade-offs outweigh VOC concerns. Margin-rich niche segments resist commodity substitution.
- Hot-melt:Packaging adhesives and assembly applications. Rapid specification cycling responds to seasonal packaging demand fluctuations.
- UV-cured:High-speed coating lines for wood and plastic substrates. Fastest formulation adaptation to regulatory changes.
Waterborne formulations concentrate investment risk while UV-cured platforms offer the fastest specification pivot.
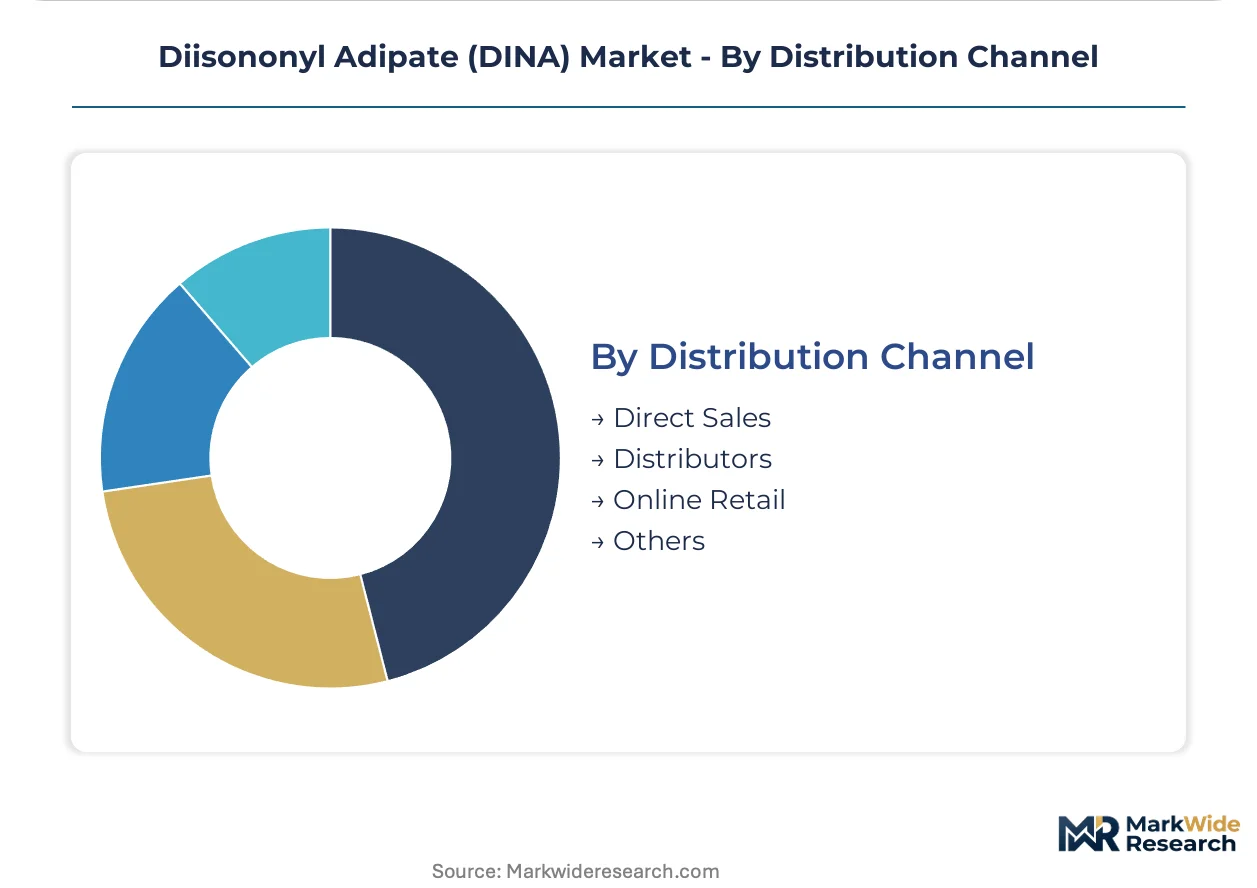
Distribution Channel:
Direct sales relationships reset on 3-5 year contracts with automotive tier-ones, while distributor inventories turn every 60-90 days.
- Direct Sales:Long-term offtake agreements with fixed viscosity bands for automotive and cable compounders. German and US Gulf Coast buyers are consolidating procurement to secure supply continuity amid cyclohexane feedstock volatility.
- Distributors:Volume flexibility for South Asian cable and wire jacketing customers. KLJ Group competes through distributor networks serving infrastructure electrification demand.
- Online Retail:Small-lot specialty grades for R&D and formulation testing. Digital platforms are compressing procurement cycles for plasticizer substitution trials.
- Others:Agent-based procurement for regional compounders without direct supplier relationships.
Direct sales lock in the volume base while distributor channels capture the most rapid demand inflections.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA regulations on phthalate migration are restructuring procurement patterns across Germany. BASF SE and Evonik Industries AG maintain integrated adipic acid-to-ester production in Ludwigshafen and Marl, securing captive feedstock margins for European compounders.
Germany
Automotive OEMs in Stuttgart and Munich are expanding DINA adoption in dashboard PVC formulations to meet volatile organic compound emission targets. REACH restrictions on DEHP and DINP are redirecting compounder procurement toward adipate esters. The Rhine-Ruhr industrial corridor concentrates integrated production, with BASF SE leveraging backward integration into adipic acid.
United States
Eastman Chemical Company anchors North American supply through Kingsport, Tennessee manufacturing for automotive and construction applications. EPA industrial chemical rules and FDA migration limits create dual compliance burden for suppliers serving both channels. The US Gulf Coast compounders are consolidating procurement to secure supply continuity amid cyclohexane feedstock volatility.
China
New adipic acid and esterification capacity additions in Ningbo and Shanghai are improving Asia-Pacific supply security. MEE enforcement of GB standards on plasticizer emissions raises technical barriers for imported material. The Yangtze River Delta is reconfiguring regional supply dynamics through domestic capacity expansion.
India
KLJ Group competes on volume flexibility for South Asian cable and wire jacketing customers as infrastructure electrification accelerates. BIS standards are tightening phthalate limits for cable jacketing adhesives. Maharashtra and Gujarat industrial corridors are capturing reformulation demand from construction and automotive sectors.
Japan
Mitsubishi Chemical Corporation maintains specialty-grade output for medical and food-contact applications with tight viscosity specifications. METI guidelines on chemical emissions are steering formulation chemistry toward non-phthalate alternatives. The Chubu region around Nagoya concentrates precision chemical manufacturing for healthcare segments.
Diisononyl Adipate (DINA) Market Key Industry Players
Capability concentration sits with integrated chemical majors; scale advantage sits with regional compounders and distributors. The market structures around three tiers: backward-integrated adipic acid producers, specialty esterification houses, and volume-flexible regional suppliers. Two dominant competitive moves are shaping rivalry: captive feedstock integration to secure margin control, and long-term offtake agreements with fixed viscosity specifications to lock in automotive tier-one relationships.
Within the integrated chemical major tier, BASF SE and Evonik Industries AG exemplify producers with captive adipic acid supply. Eastman Chemical Company occupies a position anchoring North American supply through Tennessee-based manufacturing. KLJ Group represents the volume-flexible regional archetype competing through distributor networks for South Asian infrastructure demand.
| Leading Market Players |
|---|
| BASF SE |
| ExxonMobil Chemical |
| Evonik Industries AG |
| Eastman Chemical Company |
| NAN YA PLASTICS CORPORATION |
| KLJ Group |
| Polynt S.p.A. |
| Mitsubishi Chemical Corporation |
| LG Chem Ltd |
| Others |
Cost & Logistics Intelligence
Rhine-Ruhr freight corridors linking Ludwigshafen to Rotterdam and Antwerp transmit cyclohexane cost volatility directly into DINA pricing tiers, while port congestion at Hamburg and Bremerhaven amplifies the spread between integrated German producers and import-dependent compounders across Southern Europe.
Pricing Analysis
European DINA quotations carry a 12-18% premium over Asia-Pacific spot markets due to REACH compliance certification and captive adipic acid supply. Three-tier pricing structure across medical-grade, automotive-specification, and standard industrial levels separates viscosity-certified material from commodity esters. Cost compression in standard-grade segments is intensifying because Ningbo capacity additions are expanding exportable surplus. Construction compounders in India exhibit the highest price sensitivity, while German automotive tier-ones accept premium positioning for supply continuity guarantees.
Supply Chain Analysis
Export-control restrictions on advanced esterification catalysts and continuous-process technology limit technology transfer to non-integrated producers, preserving capability concentration among Western chemical majors. Manufacturing gravity centers on Germany, China, and the United States, with adipic acid supply drawing from benzene-derived cyclohexane and isononanol feedstocks. Single-source vulnerability concentrates around BASF SE and Evonik Industries AG control of European adipic acid-to-ester assets. Distribution runs through long-term offtake agreements with automotive OEMs and spot-market distributor networks for regional cable compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital formulation platforms are transforming DINA procurement into an interoperability-driven ecosystem where API-connected compounders access real-time viscosity certification data, collapsing traditional specification cycles and rewarding first-movers with integrated data infrastructure.
For Market Incumbents: Pre-empt bio-based plasticizer substitution by accelerating medical-grade certification investments and locking automotive tier-ones into 5-year viscosity-band contracts before citrate esters achieve comparable low-temperature performance. Secure captive isononanol supply through backward integration or long-term offtake agreements with C9 alcohol producers.
For New Entrants and Emerging Players: Waterborne coating formulators in Southeast Asia represent the most penetrable entry point, as VOC regulatory deadlines in Thailand and Vietnam outpace local esterification capacity. Target infrastructure electrification cable jacketing in India through KLJ Group's distributor relationships, leveraging volume flexibility against integrated majors' rigid contract structures.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized esterification assets and stranded adipic acid capacity. Position holdings around 5-10 year regulatory compliance windows as REACH phthalate bans deepen and ECHA F-Gas migration limits tighten. Monitor EMA medical-device guidance revisions as the critical inflection signal for specialty-grade margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | BASF SE secures feedstock margins against cyclohexane volatility through captive cyclohexane oxidation. |
| Medical-Grade Certification Investment | Evonik Industries AG captures margin-rich healthcare segments with tight viscosity specifications under EMA jurisdiction. |
| Waterborne Formulation Partnership | Coating suppliers align with EU VOC regulatory deadlines in automotive refinish applications. |
| Long-Term Supply Agreement | German automotive tier-ones lock supply continuity amid Ningbo capacity expansion uncertainty. |
| Continuous Process Technology Licensing | Catalytic direct oxidation routes reduce energy intensity and byproduct formation for qualifying OEMs. |
Research Approach
Initial hypotheses were tested against primary input from PVC compounding plant managers, automotive OEM procurement leads, coating formulator R&D directors, and specialty chemical distribution channel partners and refined through secondary validation against customs trade data, Cefic plasticizer demand reports, SEC 10-K chemical segment disclosures, and ECHA REACH registration databases. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down adipic acid capacity allocations.
Demand-supply-balance modeling across the projection horizon incorporated segmentation by viscosity grade tier, end-use industry vertical, formulation chemistry type, and regional production hub cluster. CAGRs were derived from regression analysis of historical consumption intensity ratios against automotive production and construction output indices, with adipic acid feedstock cost pass-through elasticity and REACH regulatory phase-in schedules as key forecast inputs.
Practitioners should monitor ECHA amendment timelines, MEE GB standard enforcement intensity, and bio-based plasticizer performance breakthroughs for early signals of forecast deviation. Material shifts in automotive interior material specifications away from PVC or accelerated citrate ester adoption in food-contact segments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
North America Aerosol Cans Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Salicylate Market