
 Diisobutyl Adipate Market | 2026-2036
Diisobutyl Adipate Market Size, Share, and Industry Trends Forecast 2026-2036
Diisobutyl Adipate Market Analytics
Personal care is recalibrating demand patterns for diisobutyl adipate as formulators seek low-viscosity emollients with favorable spreadability profiles. BASF leverages its integrated adipic acid chain to secure feedstock cost advantages across European personal care markets. Lanxess anchors its position through specialized plasticizer grades that serve automotive interior specifications. Hallstar differentiates via technical service depth in cosmetic ester applications, sustaining premium positioning against commodity suppliers.
Diisobutyl adipate is a dibasic ester synthesized from adipic acid and isobutanol, characterized by a molecular weight near 258 g/mol and a pour point below -60°C that ensures fluidity across temperature extremes. Manufacturers employ esterification with acid catalysis followed by distillation to achieve the high purity grades required for cosmetic and food-contact applications. The plasticizer segment dominates volume consumption as PVC compounding for automotive interiors and construction films absorbs the majority of adipate ester output. Cosmetics applications represent the fastest-expanding category, with personal care brands driving specification upgrades that pull higher-purity grades through distributor networks. Food packaging applications occupy a narrower but defensible margin pool, where migration limits set by food safety regulators create certification barriers for new entrants.
REACH registration requirements in Europe and FDA food-contact notifications in the United States shape product standards and market access conditions for diisobutyl adipate suppliers. China's SAMR oversees cosmetic ingredient safety assessments, adding a third compliance layer for multinational producers seeking unified product registrations. BIS certification in India introduces additional testing protocols for imported specialty esters used in pharmaceutical coatings. Stakeholders must monitor regulatory divergence on migration limits and purity benchmarks, as compliance investments will determine which suppliers retain formulation approval across key consuming regions.
Market Dynamics
REACH registration deadlines and FDA food-contact notification requirements are compressing supplier margins as purity thresholds tighten across personal care and packaging applications, forcing ester manufacturers to recalibrate distillation investments or exit cosmetic-grade segments entirely.
Growth Catalysts
- Cosmetic formulation upgrades:Personal care brands in Germany and France are specifying low-viscosity emollients for premium skincare lines, pulling high-purity adipate grades through specialized distributor networks.
- REACH compliance deadlines:ECHA registration requirements for adipate esters are consolidating supply among registrants with complete dossiers, creating preferential access for compliant producers.
- Automotive interior specifications:PVC compounding for vehicle cabin applications in China is absorbing specialized plasticizer grades with enhanced migration resistance profiles.
Market Restraints
- Adipic acid feedstock volatility:Cyclohexane oxidation routes expose producers to benzene derivative price swings that compress ester margins unpredictably.
- Supplier concentration in East Asia:Bulk dibasic ester output concentrates among integrated Chinese petrochemical complexes, creating import dependency for European compounders.
- Phthalate substitution limits:Technical performance gaps in certain PVC applications prevent complete displacement of legacy plasticizers despite regulatory pressure.
Strategic Opportunities
- Indian pharmaceutical coatings:BIS certification requirements for imported specialty esters create first-mover advantages for producers completing local testing protocols.
- Bio-based adipic acid routes:Fermentation-derived feedstocks from agricultural waste streams are opening premium positioning for renewable-content ester grades.
- Direct-to-formulator digital channels:Specialty chemical platforms are disintermediating traditional distributor networks for mid-volume cosmetic ingredient procurement.
Industry Challenges
- Cross-regional registration coordination:Harmonizing REACH, FDA, and SAMR cosmetic ingredient filings demands specialized regulatory affairs capacity that stretches mid-tier producers.
- Legacy equipment retrofit costs:Achieving cosmetic-grade purity specifications often requires molecular distillation investments that challenge capital allocation priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diisobutyl Adipate Market |
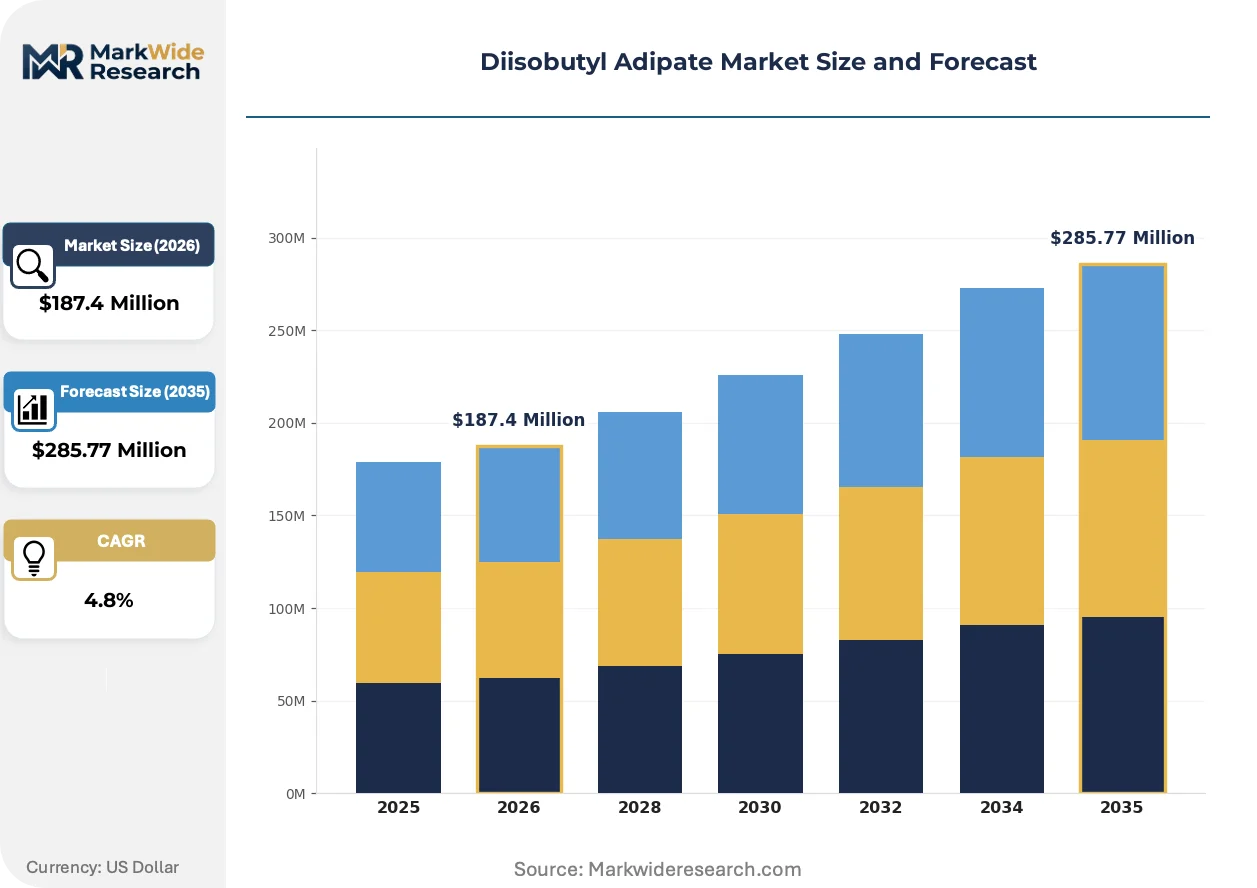
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Coatings, Adhesives, Cosmetics Application: Automotive Interiors, Textile Treatments, Food Packaging, Personal Care End Use Industry: Automotive, Construction, Pharmaceuticals, Agriculture Delivery Mode: Direct Supply, Distributor Networks, E-commerce, B2B Sales |
| Companies Covered | BASF, Lanxess, KAO, Hallstar, DEZA, Domus Chem, Varteco, Eastman Chemical Company, Qianyang Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diisobutyl Adipate Market Evolving Landscape
Continuous esterification reactor designs and membrane separation technologies are compressing production timelines for high-purity grades, while regulatory data requirements are shifting competitive advantage toward integrated producers with in-house analytical capabilities.
Membrane-assisted reactive distillation is rewriting process economics for cosmetic-grade diisobutyl adipate by enabling simultaneous reaction and purification in a single unit operation. German specialty chemical producers are retrofitting batch plants with continuous skid-mounted systems to reduce solvent carryover below 50 ppm. This technology is compressing capital requirements for new entrants while raising purity benchmarks that commodity ester lines cannot meet.
EU F-Gas Regulation phase-down schedules are indirectly pressuring adipate ester applications in refrigeration sealants and gaskets, as formulators seek low-GWP alternatives with compatible plasticizer migration profiles. Automotive HVAC component suppliers are reformulating elastomer compounds to maintain flexibility across temperature extremes without fluorinated refrigerant interactions. The regulatory friction is most acute in German and French automotive supply chains, where OEM sustainability scorecards now weight chemical footprint metrics.
Specification-driven procurement is consolidating buyer power among multinational personal care brands with unified global ingredient standards. Regional formulators in Southeast Asia are losing access to premium ester grades as suppliers prioritize accounts with volume commitments and technical service depth. This concentration is most visible in cosmetic manufacturing clusters around Shanghai and São Paulo, where distributor inventories of high-purity grades have tightened measurably.
Diisobutyl Adipate Market Segmentation
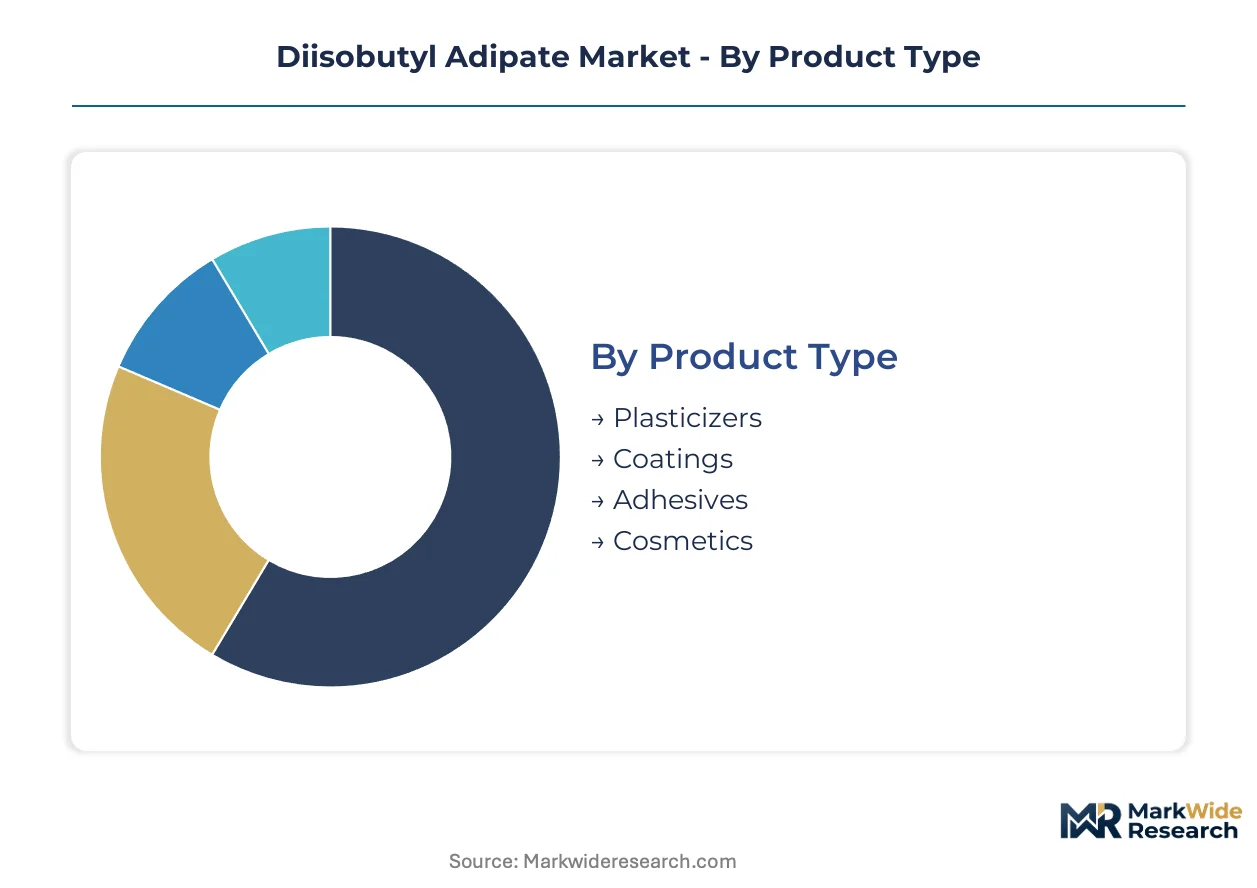
Diisobutyl adipate specifications diverge sharply across end-use requirements, with automotive and cosmetic applications demanding incompatible purity thresholds and viscosity profiles. Suppliers must maintain parallel production lines or sacrifice margin by over-processing commodity grades for premium segments.
Product Type:
Customization intensity varies from standardized bulk plasticizer formulations to highly specified cosmetic grades requiring molecular distillation certification.
- Plasticizers:PVC compounding absorbs the majority of volume, with automotive interior specifications demanding low-volatility grades that resist migration under elevated cabin temperatures. Chinese automotive OEMs are consolidating procurement around suppliers with integrated adipic acid production.
- Cosmetics:Personal care brands specify sub-50 ppm solvent residue thresholds for facial emollient applications, pulling material through specialized distributor networks in Germany and France. REACH registration completeness determines supplier access to premium formulation accounts.
- Coatings:Industrial paint formulations employ adipate esters as coalescing agents, with construction film applications dominating volume.
- Adhesives:Pressure-sensitive tape manufacturers leverage low-temperature fluidity for freezer-grade bonding applications.
Most installed capacity flows through Plasticizers. Expansion is steepest in Cosmetics.
Application:
Volume concentration follows automotive supply chain density, while margin distribution favors regulated consumer-facing segments with certification barriers.
- Automotive Interiors:PVC dashboard and door panel compounding specifies migration-resistant plasticizer grades that maintain flexibility across temperature cycling. Tier-1 suppliers in Germany enforce lot-level purity documentation.
- Personal Care:Skincare formulators in France specify low-viscosity emollients with favorable spreadability coefficients for premium product lines. SAMR cosmetic ingredient filings in China add compliance complexity for multinational brands.
- Food Packaging:FDA food-contact notifications and EU migration limits create dual-certification requirements for flexible film applications.
- Textile Treatments:Synthetic fiber lubrication employs technical-grade esters with less stringent purity thresholds than cosmetic applications.
Procurement volume concentrates in Automotive Interiors. Value expansion is most rapid in Personal Care.
End Use Industry:
Customer technical service requirements scale with formulation complexity, from standardized construction procurement to pharmaceutical coating validation protocols.
- Automotive:OEM sustainability scorecards now weight chemical footprint metrics, pressuring suppliers to document carbon intensity across the adipic acid value chain.
- Construction:PVC film and sheeting manufacturers purchase plasticizer grades in bulk tanker quantities with limited specification differentiation.
- Pharmaceuticals:Tablet coating applications require BIS certification in India and complete supply chain documentation for EU GMP compliance.
- Agriculture:Mulch film and greenhouse sheeting employ technical-grade esters with shorter specification lists than food-contact applications.
Automotive channels absorb the highest absolute volumes. Pharmaceuticals is climbing the fastest as coating validation standards tighten.
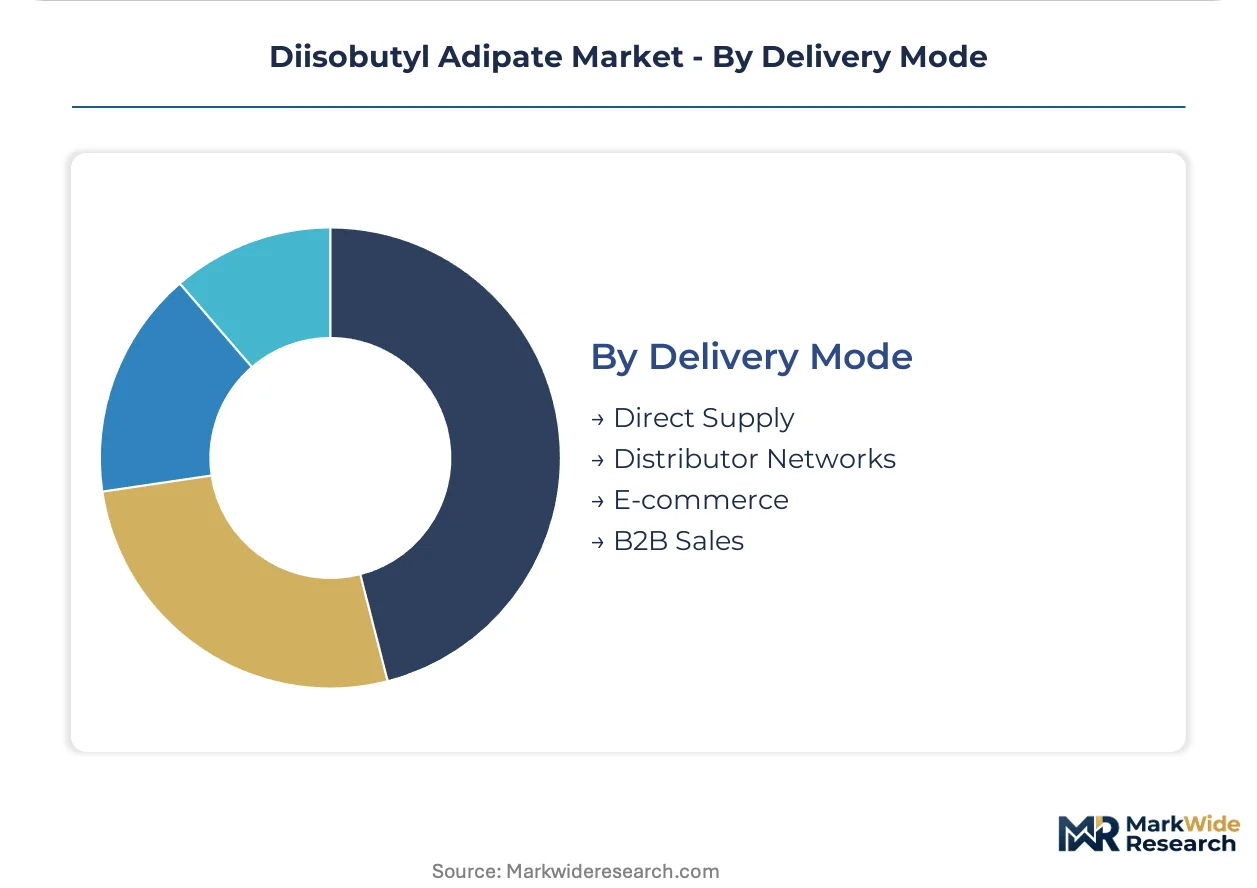
Delivery Mode:
Channel selection reflects customer scale and technical service intensity, with direct relationships dominating high-volume accounts and digital platforms emerging for mid-tier procurement.
- Direct Supply:Integrated petrochemical producers serve automotive compounders and major construction film manufacturers through dedicated logistics contracts with tanker-level minimums.
- Distributor Networks:Specialty chemical distributors maintain inventory positions for cosmetic and pharmaceutical customers requiring smaller lot sizes and technical support.
- B2B Sales:Long-term supply agreements with price adjustment mechanisms dominate construction and automotive procurement, reducing spot market exposure.
- E-commerce:Digital platforms are disintermediating traditional distribution for mid-volume cosmetic ingredient procurement, particularly among independent formulators.
Contracted B2B relationships handle the majority of tonnage. E-commerce is gaining share fastest among independent personal care manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as adipate ester manufacturers migrate capacity toward jurisdictions with streamlined chemical registration frameworks and lower compliance costs.
China
Specialty chemical producers in Jiangsu and Shandong provinces are scaling dibasic ester output to serve domestic automotive interior compounding and regional coating markets. SAMR cosmetic ingredient safety assessments add compliance complexity for multinational brands seeking unified product registrations. Manufacturing clusters around Shanghai and Ningbo concentrate high-purity grade production for personal care export markets.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg enforce lot-level purity documentation for PVC dashboard and door panel applications. ECHA REACH registration requirements for adipate esters consolidate supply among registrants with complete dossiers. Specialty chemical producers in the Ruhr region retrofit batch plants with continuous skid-mounted systems to meet cosmetic-grade specifications.
United States
Personal care formulators in New Jersey and California specify low-viscosity emollients for premium skincare lines, pulling high-purity grades through specialized distributor networks. FDA food-contact notification requirements compress supplier margins as purity thresholds tighten. Construction film manufacturers in the Gulf Coast states purchase plasticizer grades in bulk tanker quantities.
India
Pharmaceutical coating applications in Maharashtra and Gujarat require BIS certification for imported specialty esters, creating first-mover advantages for producers completing local testing protocols. CDSCO oversight of excipient quality adds regulatory layering for tablet coating validation. Industrial clusters in Ahmedabad and Mumbai absorb technical-grade esters for textile treatment applications.
France
Skincare formulators in the Île-de-France region specify low-viscosity emollients with favorable spreadability coefficients for premium product lines. ANSM cosmetic safety assessments align with EU-wide REACH frameworks while maintaining national notification requirements. The cosmetics manufacturing corridor between Paris and Lyon concentrates demand for sub-50 ppm solvent residue grades.
Diisobutyl Adipate Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated petrochemical producers scale adipic acid derivative output to capture downstream ester margins. The vendor base organizes into three tiers: multinational chemical conglomerates with captive feedstock supply, regional specialty ester producers serving cosmetic and pharmaceutical niches, and commodity distributors handling bulk plasticizer volumes. Strategic archetypes include backward-integrated adipic acid operators, formulation-focused technical service providers, and import-dependent regional compounders. Geographic expansion and portfolio diversification represent the dominant competitive moves as players seek registration coverage across multiple jurisdictions.
Among integrated chemical conglomerates, BASF anchors the premium tier through its Ludwigshafen-based adipic acid chain, while Lanxess occupies a position serving automotive interior specifications. Hallstar exemplifies the technical-service archetype, sustaining positioning through cosmetic ester application depth. These three entities represent distinct strategic postures: captive feedstock control, automotive specification anchoring, and formulation partnership depth.
| Leading Market Players |
|---|
| BASF |
| Lanxess |
| KAO |
| Hallstar |
| DEZA |
| Domus Chem |
| Varteco |
| Eastman Chemical Company |
| Qianyang Tech |
| Others |
Value Network & Pricing Analysis
Benzene derivative price indices cascade through adipic acid conversion costs into three distinct pricing tiers for diisobutyl adipate, with integrated producers capturing margin advantages that commodity ester manufacturers cannot match. Feedstock volatility from cyclohexane oxidation routes compresses margins at the standard-grade level while cosmetic and pharmaceutical certifications sustain premium positioning.
Pricing Analysis
Distributor markups of 15-25 percentage points separate bulk plasticizer procurement from cosmetic-grade spot purchases, with technical service depth commanding additional premiums in personal care channels. Three-tier pricing structure across premium, standard, and economy levels reflects purity thresholds rather than volume scale alone. Price differentiation hinges on REACH registration completeness and FDA food-contact notification status. Cost compression in standard plasticizer grades is intensifying because Chinese integrated producers are flooding regional coating markets. Construction film manufacturers exhibit highest price sensitivity, while pharmaceutical coating buyers prioritize certification over unit cost.
Supply Chain Analysis
REACH, FDA, and SAMR cosmetic ingredient filings function as qualification gates that filter supplier access to premium formulation accounts, consolidating procurement around registrants with complete dossiers. Manufacturing concentrates in China, Germany, and the United States, with Jiangsu and Shandong provinces anchoring bulk dibasic ester output. The supply chain draws from adipic acid, isobutanol, and specialized catalyst inputs. Single-source vulnerability runs through integrated Chinese petrochemical complexes that feed both domestic automotive compounders and export markets. Distribution runs through direct tanker contracts for automotive OEMs and specialty chemical distributors for cosmetic formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Personal care specification upgrades toward sub-50 ppm solvent residue thresholds signal a late-cycle quality story, with formulators paying premiums for distillation-certified grades that commodity lines cannot deliver.
For Market Incumbents:Hedge against adipic acid feedstock volatility through backward integration into cyclohexane supply or long-term offtake agreements with benzene derivative producers. Prioritize molecular distillation capacity additions in the Ruhr region to defend cosmetic-grade margins against Chinese integrated producers. ECHA registration deadlines threaten to displace non-compliant suppliers from European personal care channels.
For New Entrants and Emerging Players:The 40-60 percentage point spread between premium cosmetic grades and technical plasticizer tiers offers white-space entry for specialized ester producers with membrane-assisted reactive distillation capabilities. Target Indian pharmaceutical coating applications where BIS certification creates first-mover advantages for local testing protocol completion. Deploy direct-to-formulator digital channels to disintermediate traditional distributor networks among independent personal care manufacturers.
For Investors and Strategic Acquirers:Asymmetric upside sits with regional specialty ester producers possessing complete REACH dossiers and established technical service relationships in cosmetic applications. Five-to-ten year viability favors producers with demonstrated formulation partnership depth over commodity volume players. Watch for ECHA substance evaluation outcomes on adipate esters as the inflection signal for regulatory-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | Captive feedstock supply insulates margin from benzene derivative price swings in Ludwigshafen and Shanghai clusters. |
| Molecular Distillation Capacity Addition | Cosmetic-grade purity certification unlocks premium positioning in German and French skincare formulation networks. |
| REACH Registration Completion | Full dossier submission secures preferential supplier access to ECHA-compliant personal care procurement channels. |
| Direct-to-Formulator Digital Platform | Disintermediation of specialty chemical distributors captures mid-volume cosmetic ingredient procurement growth. |
| Bio-Based Adipic Acid Partnership | Fermentation-derived feedstock from agricultural waste streams opens renewable-content positioning for sustainability-scorecarded automotive OEMs. |
Research Methodology
Multiple input streams — executive interviews with specialty ester plant managers, procurement leads at PVC compounding facilities, and cosmetic formulation directors — were reconciled against customs trade data, Cefic sector reports, and SEC 10-K chemical segment disclosures. Primary fieldwork with distribution channel partners and technical R&D directors at personal care manufacturers validated purity threshold specifications. Bottom-up volume modeling across plasticizer, cosmetic, and pharmaceutical grades was cross-checked against top-down adipic acid derivative consumption estimates.
Data-stream reconciliation enabled segmentation across grade tier, end-use industry, and regional production hub dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections tied to automotive interior build rates and personal care formulation upgrade cycles. Analysis incorporated SAMR cosmetic ingredient filing timelines and FDA food-contact notification approval trajectories as regulatory pacing inputs.
Caveats apply where ECHA substance evaluation outcomes, benzene derivative price spikes, or Chinese environmental enforcement actions could materially shift the outlook. Forecasts reflect assumptions about REACH registration continuity and automotive OEM sustainability scorecard weightings. A model refresh is warranted upon material change in adipic acid feedstock cost structures or regulatory migration limit revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Bromocyclopentane Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Releasing Agents Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market
Specialty Chemicals
Cubeb Oil Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market