
 Middle East Smart Card Market | 2026-2036
Middle East Smart Card Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Smart Card Market Foresight
EMV certification tier is collapsing the gap between legacy magnetic-stripe infrastructure and next-generation payment ecosystems across Gulf banking networks. Thales Group leverages its regional certification laboratories to accelerate chip personalization timelines for Middle Eastern issuers. IDEMIA anchors the government identity segment through national ID and e-passport contracts with Gulf Cooperation Council states. Giesecke+Devrient specializes in polycarbonate card bodies that withstand desert climate degradation.
A smart card integrates an embedded microprocessor or memory chip within a standardized ISO/IEC 7816-compliant substrate, enabling cryptographic authentication, secure data storage, and offline transaction processing through electrical contact pads or radio-frequency coupling. Contactless variants operating at 13.56 MHz now dominate transportation and access-control deployments across Dubai Metro and Riyadh bus networks. The financial services application segment generates the deepest margin pools due to EMV compliance mandates and premium personalization requirements. Government end users represent the fastest-growing demand channel as Saudi Arabia, UAE, and Qatar digitize citizen service delivery.
The Saudi Arabian Monetary Authority enforces Payment Services Provider regulations that mandate chip-based card issuance, while the UAE Central Bank's stored value facility rules shape prepaid card architecture. SAMR's technical regulations in China influence component sourcing for regional assemblers importing secure modules. Stakeholders must monitor evolving Gulf data-localization requirements that could redirect card personalization away from European fabs toward domestic facilities.
Market Dynamics
Contactless EMV migration across Gulf banking networks is collapsing the legacy magnetic-stripe infrastructure, forcing wholesale replacement cycles that compress issuer procurement timelines and reshape personalization capacity planning.
Growth Catalysts
- SAMA Payment Services Provider regulations:The Saudi Arabian Monetary Authority mandates chip-based card issuance, creating binding compliance deadlines that pull forward replacement demand across retail banking portfolios.
- Polycarbonate substrate adoption:Desert climate degradation of PVC card bodies is accelerating migration to polycarbonate materials that withstand thermal cycling and UV exposure in outdoor payment terminals.
- E-government digitization:National ID and e-passport programs across Gulf Cooperation Council states are expanding secure element volumes beyond traditional financial applications.
Market Restraints
- Secure module import dependency:SAMR technical regulations in China constrain component sourcing flexibility, exposing regional assemblers to supply interruption risks during customs clearance delays.
- Personalization infrastructure concentration:European fabs currently process the majority of Gulf-issued card personalization, creating vulnerability to data-localization policy pivots that could invalidate existing supply arrangements.
- Legacy terminal interoperability gaps:Hybrid contact-contactless chip architectures require dual-interface certification that extends deployment timelines for smaller issuers with constrained IT integration resources.
Strategic Opportunities
- Domestic personalization facilities:Evolving Gulf data-localization requirements are redirecting card personalization toward Saudi Arabia and UAE-based facilities, creating first-mover advantages for regional infrastructure investors.
- Transportation-open-loop convergence:Dubai Metro and Riyadh bus network deployments demonstrate interoperability between transit fare collection and retail payment acceptance, opening cross-vertical credential consolidation.
- Biometric-card hybridization:Fingerprint sensor integration into payment card bodies is converging with existing EMV certification pathways, enabling premium product differentiation for affluent Gulf consumer segments.
Industry Challenges
- EMV certification timeline compression:Thales Group regional laboratories face queue congestion as multiple issuers pursue simultaneous chip personalization validation, stretching technical staff capacity.
- Desert climate qualification protocols:Polycarbonate card body suppliers must demonstrate extended thermal cycling performance under Gulf-specific humidity and sand exposure conditions that exceed standard ISO test parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Smart Card Market |
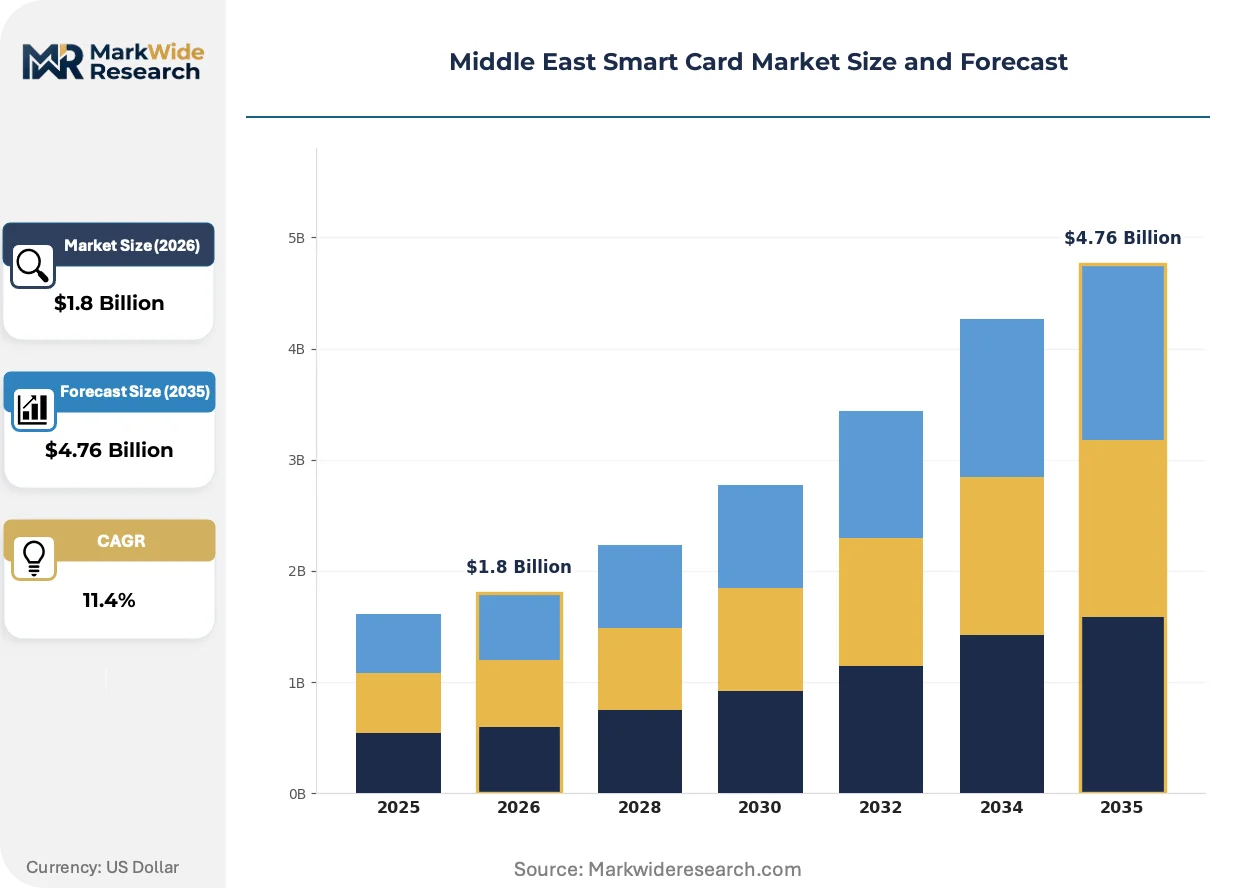
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Contact, Contactless, Dual Interface, Smart Hybrid Application: Telecommunications, Financial Services, Transportation, Healthcare Material: Polyvinyl Chloride, Polycarbonate, ABS, PET End User: Government, Banking, Retail, Corporate |
| Companies Covered | Thales Group, IDEMIA, Infineon Technologies AG, HID Global Corporation, Eviden, Giesecke+Devrient, Texas Instruments, Atos, EASTCOMPEACE, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Smart Card Market Shifts & Advancements
Dual-interface card architectures are collapsing the distinction between contact-based banking credentials and contactless transit passes, creating unified payment ecosystems that span retail, transportation, and access-control domains.
Biometric payment cards with embedded fingerprint sensors are fragmenting the traditional PIN-entry authentication model. UAE retail banks are piloting these credentials for high-net-worth account holders who prioritize transaction speed over cost minimization. The technology is fragmenting issuer product portfolios into tiered authentication offerings that segment customers by risk tolerance and spending velocity rather than account type alone.
UAE Central Bank stored value facility rules are reshaping prepaid card architecture across digital wallet integrations. The regulations mandate segregated fund safeguarding that complicates fintech-bank partnership structures. Prepaid issuers are responding by consolidating technology stacks to reduce compliance audit surface area.
Transportation procurement patterns across Dubai Metro and Riyadh bus networks are consolidating around open-loop acceptance that eliminates closed-system card issuance. Municipal transit authorities are displacing proprietary fare media with direct EMV contactless tap-to-ride, reducing credential management overhead. This shift is most visible in Saudi Arabia, where Riyadh bus network modernization is embedding payment acceptance into station infrastructure rather than maintaining separate transit card distribution.
Middle East Smart Card Market Segmentation
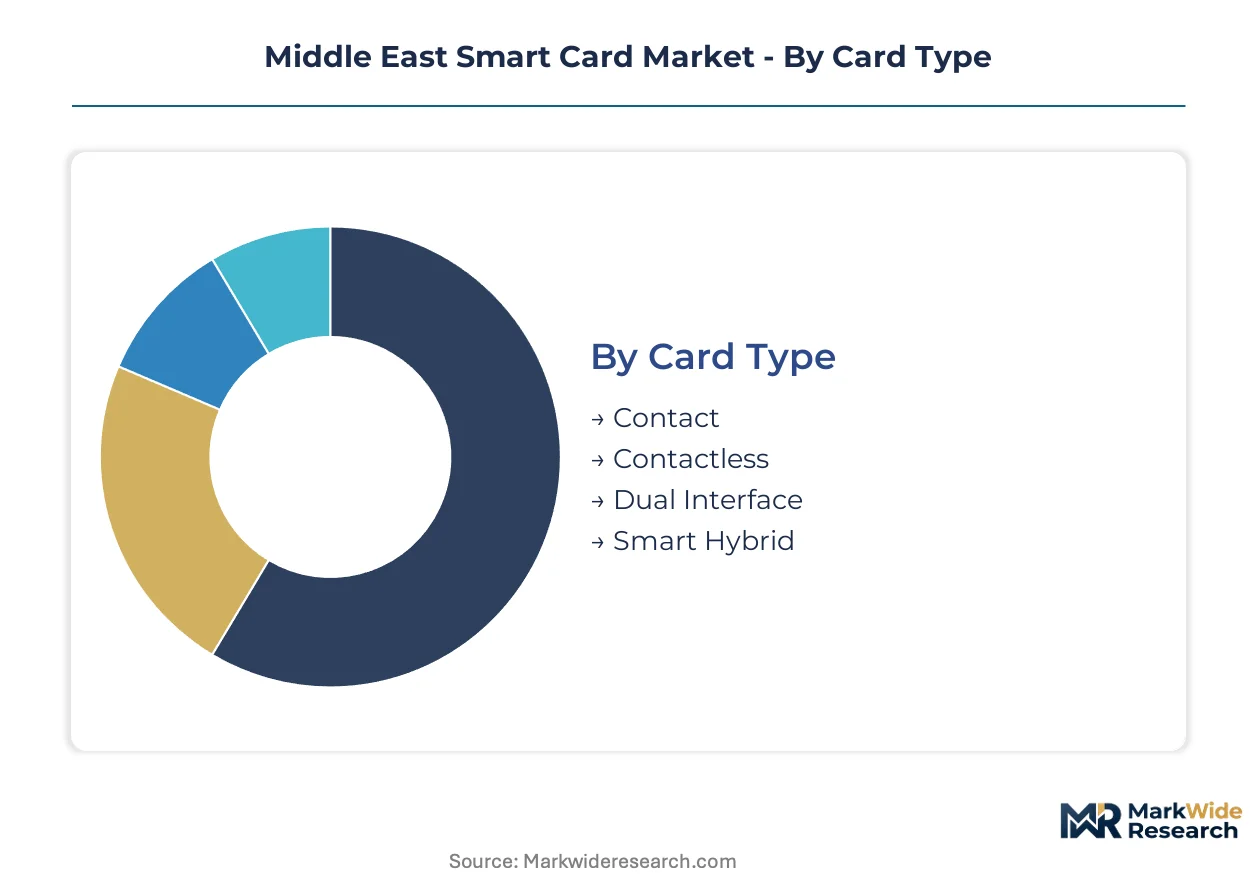
Smart card segmentation in the Middle East reflects divergent compliance pathways across Saudi SAMA mandates and UAE Central Bank chip-and-PIN standards. Each category channels procurement toward distinct substrate specifications, interface architectures, and personalization security tiers.
Card Type:
SAMA and UAE Central Bank regulations differentiate certification requirements between contact-based EMV compliance and contactless tap-to-pay deployments.
- Contact:ISO/IEC 7816-compliant electrical interface with physical contact pads for chip-to-terminal communication. Banking networks across Saudi Arabia concentrate procurement here for ATM compatibility and EMV certification continuity.
- Contactless:13.56 MHz RF coupling enabling tap-to-transact functionality without physical insertion. Dubai Metro and Riyadh bus networks drive volume as transit authorities displace proprietary fare media.
- Dual Interface:Hybrid chip architecture supporting both contact and contactless protocols through shared secure element.
- Smart Hybrid:Multi-application credential combining payment, access control, and identity verification in single substrate.
Established volume favors Contact; emerging adoption favors Contactless.
Application:
Margin structures vary sharply across these verticals, with financial services commanding premium personalization fees and transportation standardizing on commodity specifications.
- Telecommunications:Subscriber identity modules and UICC platforms for mobile network authentication. Gulf operators prioritize remote provisioning capabilities.
- Financial Services:EMV payment credentials with cryptographic authentication and offline transaction processing. SAMA mandates and UAE Central Bank rules enforce chip-based issuance timelines.
- Transportation:Transit fare collection credentials operating in open-loop EMV environments. Dubai Metro's tap-to-ride infrastructure anchors regional deployment patterns.
- Healthcare:Patient identification and insurance eligibility verification cards. Saudi national health digitization programs expand secure element volumes.
Financial Services captures dominant margin pools; Transportation climbs the fastest as open-loop convergence eliminates closed-system overhead.
Material:
Desert climate exposure creates material selection criteria exceeding standard ISO test parameters across Gulf deployment environments.
- Polyvinyl Chloride:Legacy substrate with cost advantages but thermal cycling vulnerability. Outdoor payment terminals in Saudi Arabia accelerate displacement.
- Polycarbonate:Thermoplastic polymer with superior UV resistance and dimensional stability under thermal stress. Giesecke+Devrient specializes in formulations qualified for Gulf humidity and sand exposure conditions.
- ABS:Acrylonitrile butadiene styrene blend offering intermediate durability at moderate cost points.
- PET:Polyethylene terephthalate substrate for reduced environmental footprint and recyclability compliance.
Polycarbonate gains share fastest as issuers prioritize field reliability; PVC retains residual volume in cost-sensitive prepaid segments.
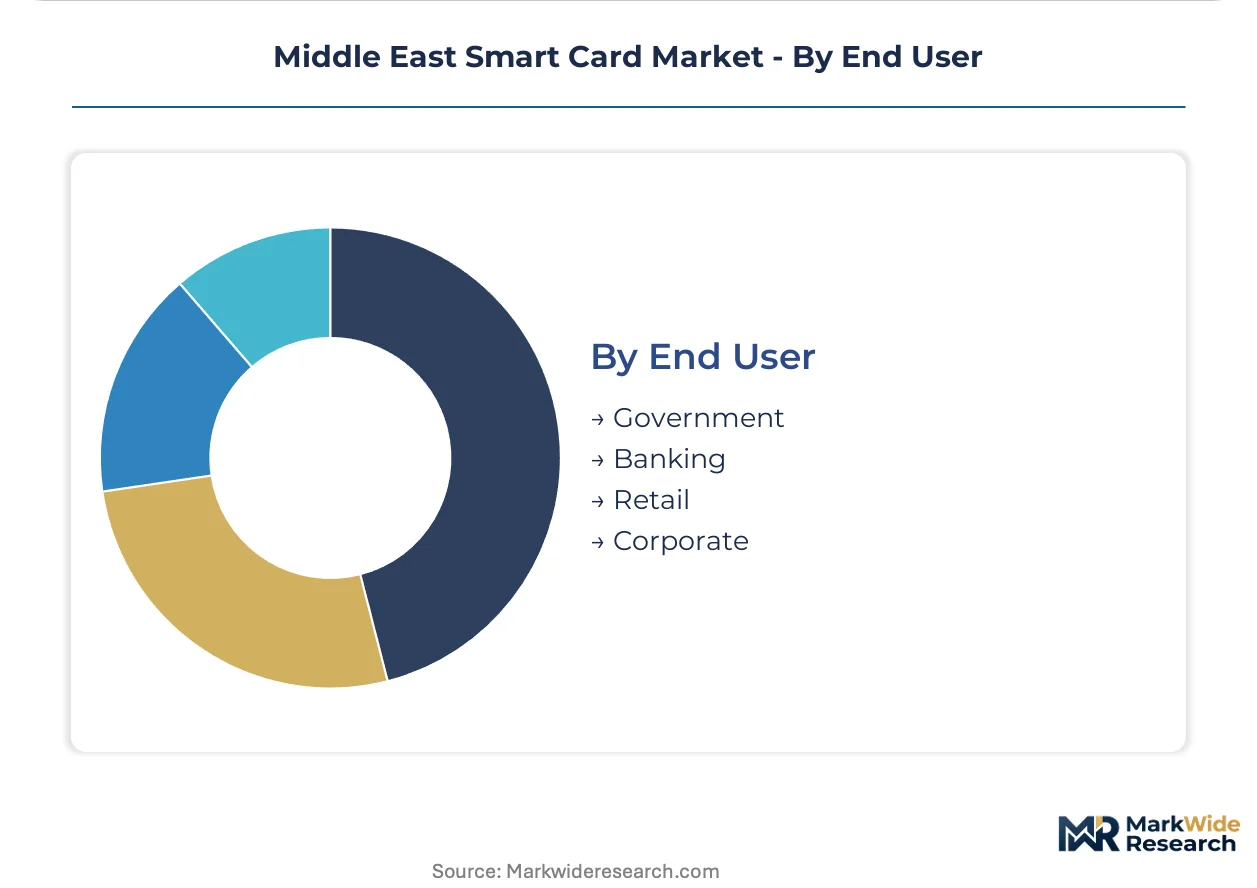
End User:
Procurement authority concentration shapes personalization security requirements and domestic facility investment decisions.
- Government:National ID, e-passport, and citizen service delivery credentials. Gulf Cooperation Council states expand secure element volumes through digitization mandates.
- Banking:Retail payment card issuance under SAMA and UAE Central Bank compliance frameworks. Chip personalization timelines compress as EMV migration accelerates.
- Retail:Merchant loyalty programs and private-label payment credentials with standardized security tiers.
- Corporate:Enterprise access control and secure facility credentials with custom cryptographic profiles.
Banking anchors current procurement volume; Government represents the steepest expansion trajectory as national ID programs scale across Saudi Arabia, UAE, and Qatar.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for secure modules and personalization infrastructure concentrates supply risk in European fabs, while Saudi Arabia and the UAE accelerate domestic facility investments to rebalance trade flows and satisfy data-localization mandates.
Saudi Arabia
The Saudi Arabian Monetary Authority enforces Payment Services Provider regulations mandating chip-based card issuance across retail banking portfolios. SAMA compliance deadlines compress procurement timelines for EMV migration programs. Riyadh anchors national ID digitization and transit open-loop deployment through Riyadh bus network modernization.
United Arab Emirates
UAE Central Bank chip-and-PIN standards and stored value facility rules reshape prepaid card architecture across digital wallet integrations. Dubai Metro's tap-to-ride infrastructure demonstrates transit-retail payment convergence. Dubai and Abu Dhabi concentrate government identity contracts and biometric card pilot programs for high-net-worth segments.
Qatar
National digitization programs expand secure element volumes beyond traditional financial applications into citizen service delivery credentials. Qatar Central Bank regulations align with Gulf Cooperation Council technical standards for payment security. Doha hosts expanding personalization capacity to serve domestic e-government procurement.
Kuwait
Banking sector EMV compliance timelines lag Saudi and UAE trajectories, creating deferred replacement demand across magnetic-stripe legacy infrastructure. Central Bank of Kuwait directives gradually mandate chip-based issuance standards. Kuwait City financial district concentrates issuer procurement decision-making for retail payment portfolios.
Oman
Transportation authority procurement patterns follow UAE open-loop models, embedding payment acceptance into municipal transit infrastructure. Central Bank of Oman regulations adopt phased chip migration timelines aligned with regional compliance frameworks. Muscat anchors government identity program expansion and transit modernization initiatives.
Middle East Smart Card Market Competitive Landscape
Listed leaders compete with private specialists across certification laboratory capacity and government contract access. The vendor base concentrates around three strategic tiers: diversified technology conglomerates with regional fabrication presence, pure-play secure element specialists, and component substrate manufacturers with climate-qualified formulations. Competitive moves center on domestic personalization facility partnerships and polycarbonate material qualification programs.
Within the diversified technology tier, Thales Group and IDEMIA exemplify archetypes combining certification laboratory networks with government identity contract portfolios. Giesecke+Devrient occupies a distinct position among substrate specialists, representing the polycarbonate formulation segment addressing Gulf climate degradation requirements. These three entities anchor competitive positioning across the compliance-driven procurement landscape.
| Leading Market Players |
|---|
| Thales Group |
| IDEMIA |
| Infineon Technologies AG |
| HID Global Corporation |
| Eviden |
| Giesecke+Devrient |
| Texas Instruments |
| Atos |
| EASTCOMPEACE |
| Others |
Supply & Pricing Matrix
Polycarbonate substrate migration from legacy PVC is redrawing procurement geography toward climate-qualified material suppliers while compressing margin structures for card body manufacturers competing on thermal cycling performance rather than commodity resin costs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Middle East smart card market. Price differentiation hinges on EMV certification grade and polycarbonate formulation qualification under Gulf humidity protocols. Pricing pressure stems from SAMA-mandated chip migration compressing issuer procurement timelines. Cost-sensitive prepaid segments exhibit highest price sensitivity; biometric-enabled premium cards for UAE high-net-worth segments show lowest.
Supply Chain Analysis
Inventory lead times for secure modules stretch when SAMR technical regulations in China trigger customs clearance delays at regional ports. Supply concentrates in Germany, France, and China for secure element fabrication, polycarbonate resin, and chip module assembly respectively. The chain rests on microcontroller wafer supply from Taiwan, polycarbonate substrate from European chemical producers, and personalization equipment from German precision engineering. Single-source vulnerability pervades European personalization fabs processing Gulf-issued cards. Distribution runs through regional banking technology integrators and government procurement authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East smart card market sits in early-cycle expansion as government digitization mandates across Saudi Arabia, UAE, and Qatar accelerate secure element volumes beyond traditional financial applications.
For Market Incumbents: Secure domestic personalization facility partnerships in Saudi Arabia and the UAE ahead of data-localization policy pivots. Anchor polycarbonate formulation advantages through extended thermal cycling qualification under Gulf-specific humidity and sand exposure conditions. Capacity concentration in European fabs represents the primary threat to existing supply arrangements. For New Entrants and Emerging Players: EMV certification fast-track through Thales Group regional laboratories offers entry into compressed procurement timelines for Saudi banking issuers. Target Kuwait's deferred EMV replacement demand where Central Bank of Kuwait directives lag Saudi and UAE trajectories. Pursue transit-open-loop convergence opportunities in Oman and Qatar municipal networks as proprietary fare media displacement accelerates. For Investors and Strategic Acquirers: The market sits at a compliance-pull phase that favors substrate specialists with climate-qualified formulations and certification laboratory networks. Long-term viability centers on biometric-card hybridization and domestic personalization infrastructure. Acquisition target archetype: polycarbonate material suppliers with Gulf-specific qualification protocols. Watch biometric payment card pilot scale in UAE retail banking as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Personalization Facility Investment | Positions suppliers ahead of Gulf data-localization mandates redirecting card personalization from European fabs. |
| Polycarbonate Formulation Qualification | Giesecke+Devrient's climate-specific thermal cycling protocols address desert degradation exceeding standard ISO parameters. |
| Biometric Sensor Integration Partnership | Enables premium product differentiation for UAE high-net-worth segments prioritizing transaction speed. |
| Transit-Open-Loop Certification | Dubai Metro and Riyadh bus network deployments demonstrate retail payment convergence eliminating closed-system overhead. |
| Secure Module Sourcing Diversification | Mitigates SAMR regulatory exposure constraining component import flexibility for regional assemblers. |
Research Methodology
Cross-validation between primary fieldwork and secondary documentation anchors the qualitative findings in this study. Interviews with chip personalization engineers, banking technology procurement managers, government identity program directors, and transit authority technology officers combined with regulatory filings from SAMA, UAE Central Bank, and Qatar Central Bank, trade customs data for secure module imports, and industry association technical standards. Bottom-up issuer procurement tracking and top-down secure element volume estimates provide triangulation.
Sensitivity analysis across polycarbonate adoption rates, EMV migration timelines, and biometric card penetration shapes the analytical framework. Segmentation dimensions include card type architecture, application vertical, substrate material grade, and end-user procurement authority. CAGRs derive from issuer replacement cycle modeling and government contract award trajectories. Forecast inputs incorporate SAMA compliance deadline enforcement and Gulf data-localization policy evolution.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or supply chain reconfiguration would require recalibration. Forecasts reflect documented assumptions regarding polycarbonate displacement velocity and certification laboratory capacity expansion. Supply interruption risks from SAMR customs delays or European fab concentration could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
AQI App Market
Digital Solutions
On-Shelf Availability Solutions Market
Digital Solutions
Global Media (Video) Processing Solutions Market
Digital Solutions
Global Content Moderation Solutions Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Physical-Digital Integration Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Conference Room Solutions Market
Digital Solutions
Industrial Operational Intelligence Solution Market