
 Container Orchestration Market | 2026-2036
Container Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
Container Orchestration Market Intelligence
The premium managed Kubernetes tier is repositioning around sovereign cloud requirements and dedicated control planes, while commodity offerings compete on per-node pricing and bundled compute credits. Google sustains technology leadership through open-source stewardship of the Kubernetes project and deep integration with its cloud-native stack. Microsoft anchors enterprise adoption by embedding Azure Kubernetes Service within broader productivity and identity ecosystems. Amazon Web Services competes through operational scale, offering the broadest regional footprint and granular cost optimization tooling.
Container orchestration automates the deployment, scaling, and management of containerized applications across clustered hosts, using declarative configuration files to specify desired state and self-healing controllers to maintain it. The primary industrial purpose is to abstract infrastructure complexity, enabling development teams to ship code faster while platform engineering groups enforce governance, security, and resource efficiency. Public cloud deployment dominates volume, though private and hybrid configurations capture disproportionate margin as regulated industries demand data residency and air-gapped operations. Security solutions within the solution segment represent the fastest-expanding margin pool, driven by software supply chain integrity mandates and runtime threat detection requirements.
The US Federal Risk and Authorization Management Program and the European Union's Cybersecurity Act shape product roadmaps by requiring certified cloud services and documented supply chain provenance for government workloads. India's BIS cloud standards and data localization directives under the Digital Personal Data Protection Act create additional compliance layers for vendors seeking public-sector contracts. Stakeholders must monitor divergence between sovereign cloud requirements and hyperscale platform standardization, as this tension will determine which vendors can serve regulated verticals without fragmenting their engineering investments.
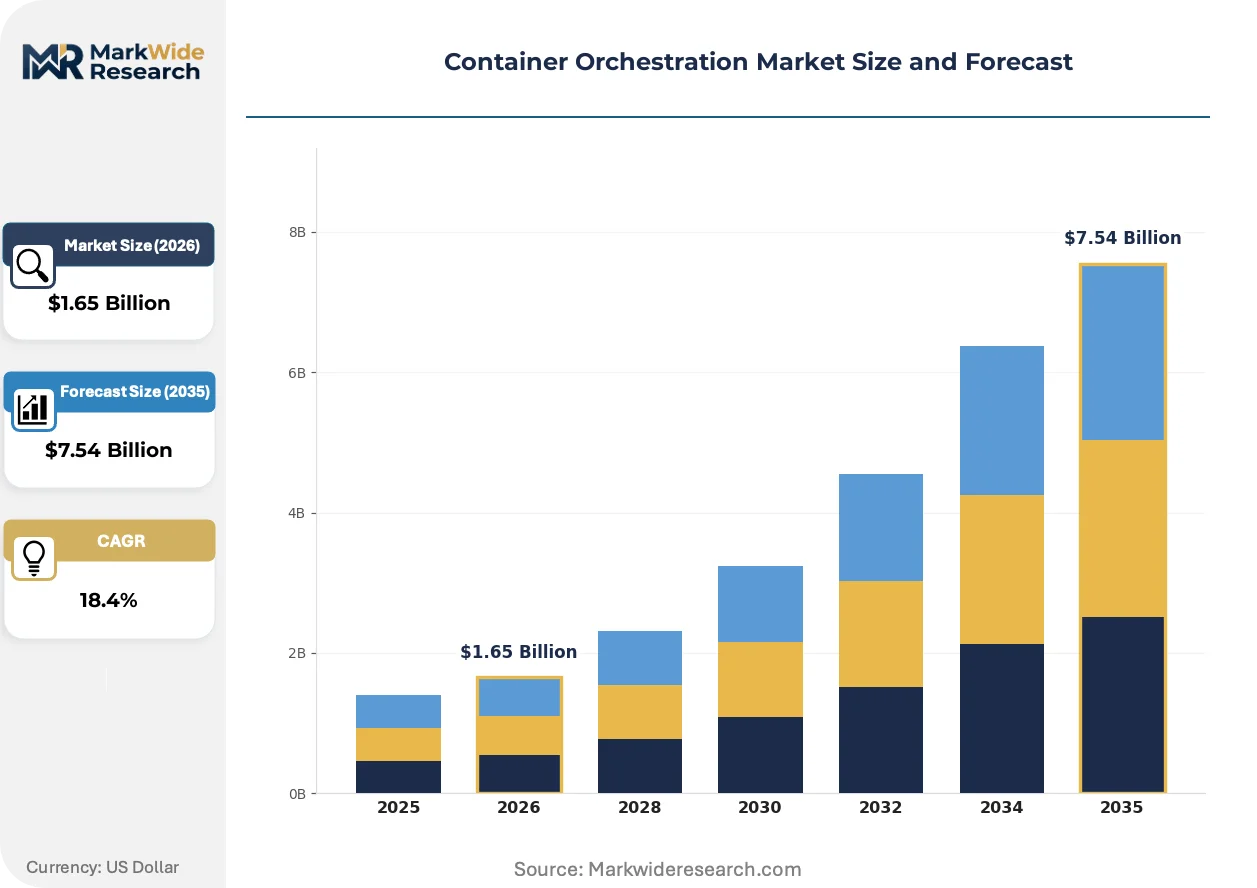
Market Dynamics
Kubernetes is modularizing enterprise infrastructure procurement, forcing vendors to unbundle control planes from compute and storage while sovereign cloud mandates fragment previously standardized deployment patterns.
Growth Catalysts
- Software supply chain integrity mandates:The US Federal Risk and Authorization Management Program requires certified orchestration platforms for government workloads, accelerating procurement of compliant managed services.
- Financial services modernization:Banks and insurers are containerizing legacy core systems to reduce infrastructure provisioning time from weeks to minutes.
- Edge computing expansion:Manufacturing and telecommunications sectors deploy lightweight Kubernetes distributions to orchestrate workloads at distributed sites with intermittent connectivity.
Market Restraints
- Specialized talent scarcity:Platform engineering expertise concentrates in hyperscale cloud hubs, inflating compensation costs for enterprises outside these clusters.
- Control plane dependency:Managed service providers in the United States dominate upstream Kubernetes contributions, creating single-source risk for critical security patches.
- Legacy integration friction:Mainframe and monolithic application estates resist containerization without extensive refactoring investment.
Strategic Opportunities
- Air-gapped sovereign deployments:India's BIS cloud standards and data localization directives under the Digital Personal Data Protection Act create demand for domestically hosted control planes.
- Runtime security convergence:Container orchestration platforms are absorbing eBPF-based threat detection, collapsing separate security tool procurement decisions.
- Platform engineering toolchains:Internal developer portals built atop Kubernetes APIs represent untapped wallet share within existing enterprise accounts.
Industry Challenges
- Certification timeline compression:FedRAMP authorization cycles stretch 12-18 months, delaying revenue recognition for vendors targeting public-sector verticals.
- Multi-cluster governance complexity:Enterprises operating hundreds of Kubernetes clusters struggle to enforce consistent policy across heterogeneous environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Orchestration Market |
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $7.54 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Solution: Container Management, Container Runtime, Networking, Security End User: Enterprises, Startups, Government, Managed Service Providers Service Type: Consulting, Training, Support, Maintenance |
| Companies Covered | Amazon Web Services, Google, Microsoft, Docker, Red Hat, Cisco Systems, Oracle, SUSE, Rancher Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Orchestration Market Strategic Shifts & Innovations
Platform engineering is displacing traditional DevOps operating models, with internal developer portals and self-service infrastructure APIs becoming the primary interface between development teams and underlying orchestration capabilities.
GitOps workflows are modularizing application deployment patterns across financial services and telecommunications verticals. Platform teams at major European banks adopt declarative configuration management to reduce deployment failure rates and audit operational changes. This shift is compressing vendor differentiation around control plane reliability rather than proprietary deployment abstractions.
The European Union's Cybersecurity Act mandates Common Criteria certification for cloud services processing sensitive government data, forcing orchestration vendors to document supply chain provenance and undergo third-party security evaluation. German automotive manufacturers and French defense contractors now require certified platforms, filtering vendor eligibility before technical evaluation begins.
Consumption-based pricing models are displacing per-node licensing for managed Kubernetes services. Enterprise buyers in the United States negotiate committed-use discounts tied to broader cloud spend rather than standalone orchestration contracts. This bundling is visible most acutely in healthcare and retail verticals where platform decisions are subordinated to enterprise-wide cloud procurement frameworks.
Container Orchestration Market Segmentation
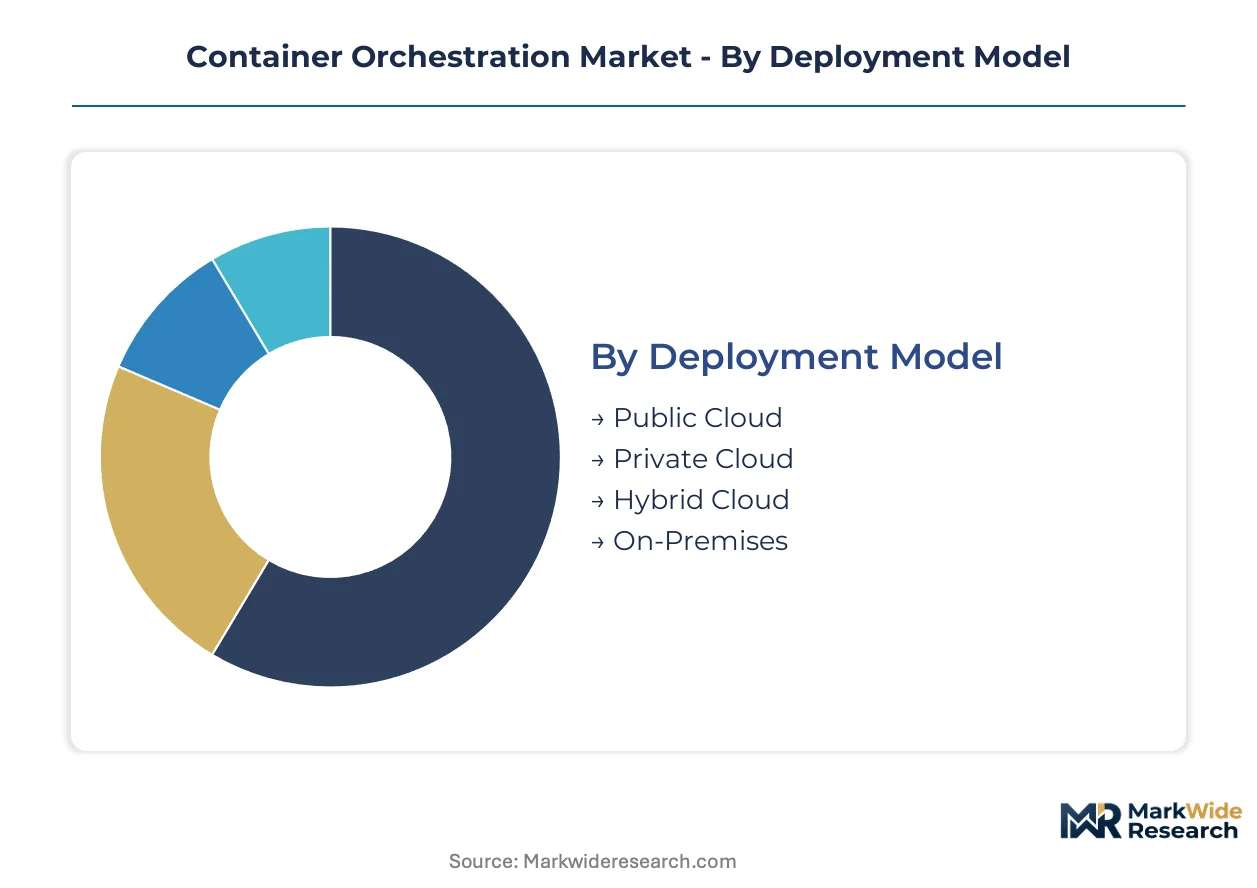
Container orchestration procurement splits across infrastructure ownership models and service delivery layers, with each segment carrying distinct margin profiles and compliance obligations. Understanding these divisions clarifies where platform engineering investments concentrate versus where commoditization pressures dominate.
Deployment Model:
Upgrade cycles for container infrastructure vary dramatically by deployment model, with cloud-native migrations displacing legacy virtualization estates and forcing parallel procurement tracks.
- Public Cloud:Hyperscale managed Kubernetes services eliminate control plane operational burden through fully hosted control planes and automated node lifecycle management. Demand concentrates in the United States among financial services firms modernizing legacy core systems, driven by FedRAMP authorization requirements for government-facing workloads and the need to compress infrastructure provisioning from weeks to minutes.
- Hybrid Cloud:Split orchestration across on-premises clusters and hyperscale burst capacity maintains data residency for regulated workloads while capturing cloud elasticity for variable demand. German automotive manufacturers and French defense contractors now require Common Criteria certification before technical evaluation, filtering vendor eligibility through documented supply chain provenance mandates under the European Union's Cybersecurity Act.
- Private Cloud:Dedicated infrastructure stacks serve air-gapped environments with complete tenant isolation and custom hardware configurations.
- On-Premises:Self-managed Kubernetes distributions deploy to bare-metal servers in manufacturing facilities with intermittent connectivity.
Volume placements concentrate in Public Cloud; the faster expansion belongs to Hybrid Cloud.
Solution:
Cost tiering within the solution stack separates commodity runtime components from premium security and management layers that capture disproportionate margin.
- Security:Runtime threat detection and software supply chain integrity tools represent the fastest-expanding margin pool, absorbing eBPF-based monitoring and collapsing separate security procurement decisions. India's BIS cloud standards and data localization directives under the Digital Personal Data Protection Act create compliance layers for vendors seeking public-sector contracts.
- Container Management:Control plane operations, cluster lifecycle automation, and multi-cluster governance form the core orchestration value proposition. Platform engineering teams at major European banks adopt declarative GitOps workflows to reduce deployment failure rates and audit operational changes.
- Container Runtime:Low-level execution engines for container image instantiation and resource isolation.
- Networking:Service mesh and cluster communication fabrics enabling microservice discovery.
Management tools anchor current spending; security solutions are climbing the fastest.
End User:
Customer type determines procurement velocity, with enterprise frameworks subordinating platform decisions to broader cloud spend commitments while government verticals impose certification bottlenecks.
- Enterprises:Large organizations negotiate committed-use discounts tied to enterprise-wide cloud procurement frameworks rather than standalone orchestration contracts, visible most acutely in United States healthcare and retail verticals. Internal developer portals built atop Kubernetes APIs represent untapped wallet share within existing accounts.
- Government:Public-sector procurement requires certified orchestration platforms with documented supply chain provenance, stretching FedRAMP authorization cycles to 12-18 months and delaying revenue recognition. The US Federal Risk and Authorization Management Program shapes product roadmaps by mandating compliant managed services for federal workloads.
- Startups:Venture-backed technology companies prioritize per-node pricing and bundled compute credits over sovereign cloud features.
- Managed Service Providers:Third-party operators deliver multi-tenant orchestration with value-added support layers.
Enterprise commitments dominate absolute volume; government verticals show the steepest expansion trajectory.
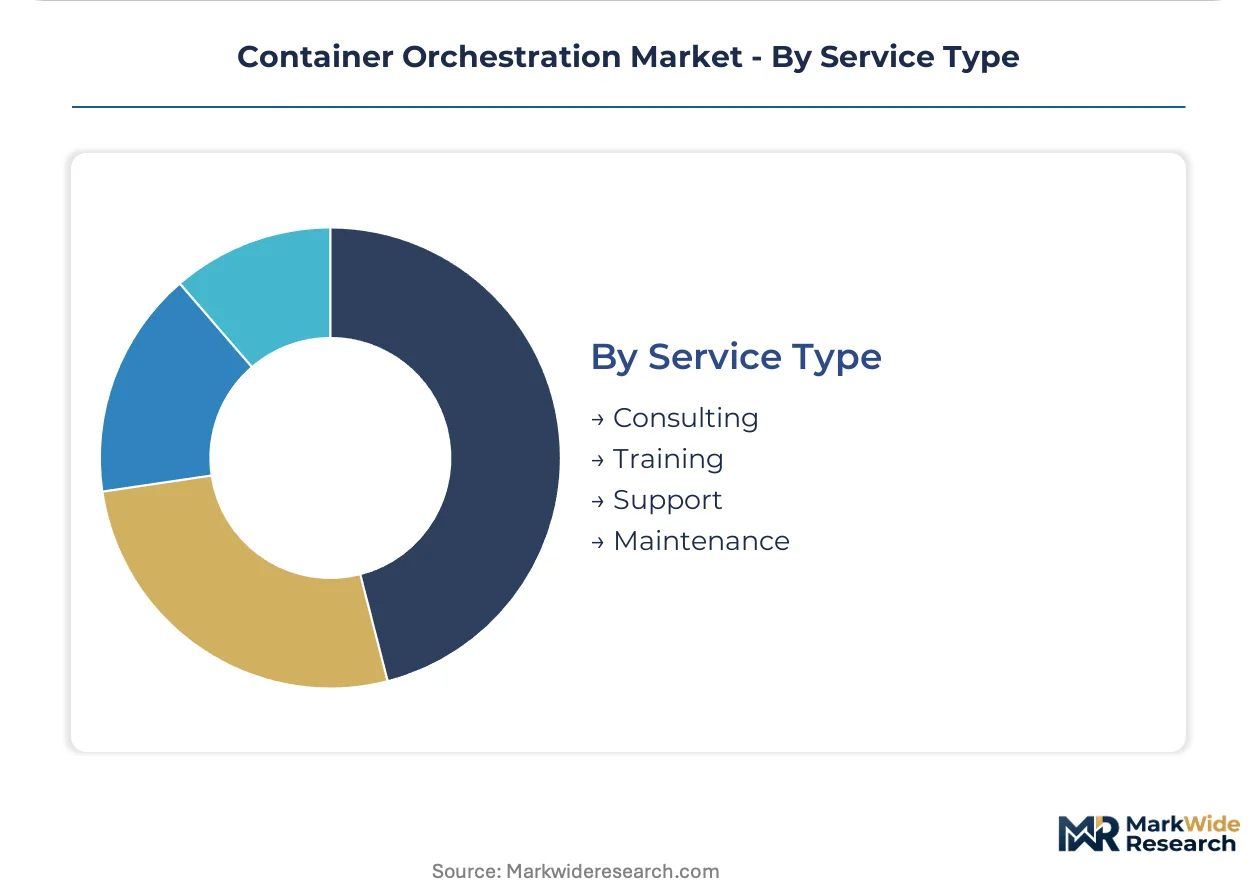
Service Type:
Service delivery maturity separates transactional training engagements from embedded support relationships that extend customer lifetime value.
- Consulting:Professional services for cluster architecture design, migration planning, and platform engineering organizational transformation. Financial services firms in the United States engage consultants to containerize legacy mainframe estates resistant to refactoring without extensive investment.
- Support:Ongoing technical assistance and escalation management for production orchestration environments. Specialized platform engineering expertise concentrates in hyperscale cloud hubs, inflating compensation costs for enterprises outside these clusters.
- Training:Certification programs and skill development for Kubernetes administration and application modernization.
- Maintenance:Patch management, version upgrades, and control plane health monitoring services.
Support engagements capture recurring revenue density; consulting services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors hyperscale cloud infrastructure development, housing engineering headquarters that shape upstream Kubernetes contributions and downstream managed service roadmaps.
United States
Financial services modernization and federal cloud procurement drive managed Kubernetes adoption. FedRAMP authorization requirements stretch vendor certification cycles to 12-18 months. The San Francisco Bay Area concentrates platform engineering talent pools that command premium compensation.
Germany
Automotive manufacturers and defense contractors demand Common Criteria certified orchestration platforms. The EU Cybersecurity Act mandates documented supply chain provenance for sensitive government workloads. Munich engineering clusters enforce strict data residency requirements for connected vehicle platforms.
India
Public-sector digital transformation programs accelerate sovereign cloud procurement. BIS cloud standards and Digital Personal Data Protection Act localization directives create compliance layers. Bangalore technology corridors host domestic control plane development for air-gapped government deployments.
United Kingdom
Financial services firms containerize legacy core systems to compress infrastructure provisioning timelines. The National Cyber Security Centre shapes vendor eligibility through cloud security certification frameworks. London fintech clusters adopt GitOps workflows to audit operational changes.
Japan
Manufacturing and telecommunications sectors deploy lightweight Kubernetes distributions for edge computing sites with intermittent connectivity. METI industrial digitization programs subsidize platform engineering organizational transformation. Tokyo enterprise buyers negotiate committed-use discounts tied to broader cloud procurement frameworks.
Container Orchestration Market Key Industry Players
Capital-heavy hyperscale cloud providers compete with asset-light open-source distributors and specialized platform engineering consultancies. The vendor base concentrates around three strategic tiers: fully managed control plane operators, enterprise distribution maintainers, and edge-optimized lightweight distributors. Consolidation pressures favor providers with upstream project stewardship and embedded identity ecosystems. Competitive moves center on sovereign cloud feature development and runtime security absorption.
Among hyperscale infrastructure operators, Amazon Web Services, Google, and Microsoft occupy positions that exemplify the fully managed tier. These entities anchor enterprise procurement decisions through regional footprint scale, open-source project governance, and productivity ecosystem integration respectively. Their market presence shapes pricing benchmarks and certification requirements that cascade to downstream specialists.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Docker |
| Red Hat |
| Cisco Systems |
| Oracle |
| SUSE |
| Rancher Labs |
| Others |
Cost & Logistics Intelligence
Financial services procurement teams in the United States negotiate committed-use discounts tied to enterprise-wide cloud spend rather than standalone orchestration contracts, compressing per-node pricing into bundled compute credit frameworks. This buyer concentration forces vendors to absorb control plane operational costs while competing on regional footprint scale and certification velocity.
Pricing Analysis
Value-based pricing anchored to workload uptime guarantees and FedRAMP authorization status separates premium managed Kubernetes tiers from commodity offerings. Three-tier pricing structure across sovereign cloud, enterprise-grade, and developer tiers reflects certification investment and dedicated control plane isolation. Cost compression in the commodity tier intensifies as hyperscalers bundle orchestration into broader infrastructure commitments. Startups exhibit highest price sensitivity, while government verticals prioritize authorization timelines over per-unit economics.
Supply Chain Analysis
Common Criteria and FedRAMP certification gating concentrates qualified control plane engineering in Seattle, San Francisco Bay Area, and Bangalore technology corridors. Upstream Kubernetes contributions draw from hyperscale cloud provider engineering headquarters, open-source foundation governance bodies, and specialized platform engineering consultancies. Single-source vulnerability runs through managed service providers dominating upstream security patch distribution. Distribution runs through direct hyperscale cloud procurement channels and embedded enterprise productivity ecosystem sales motions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
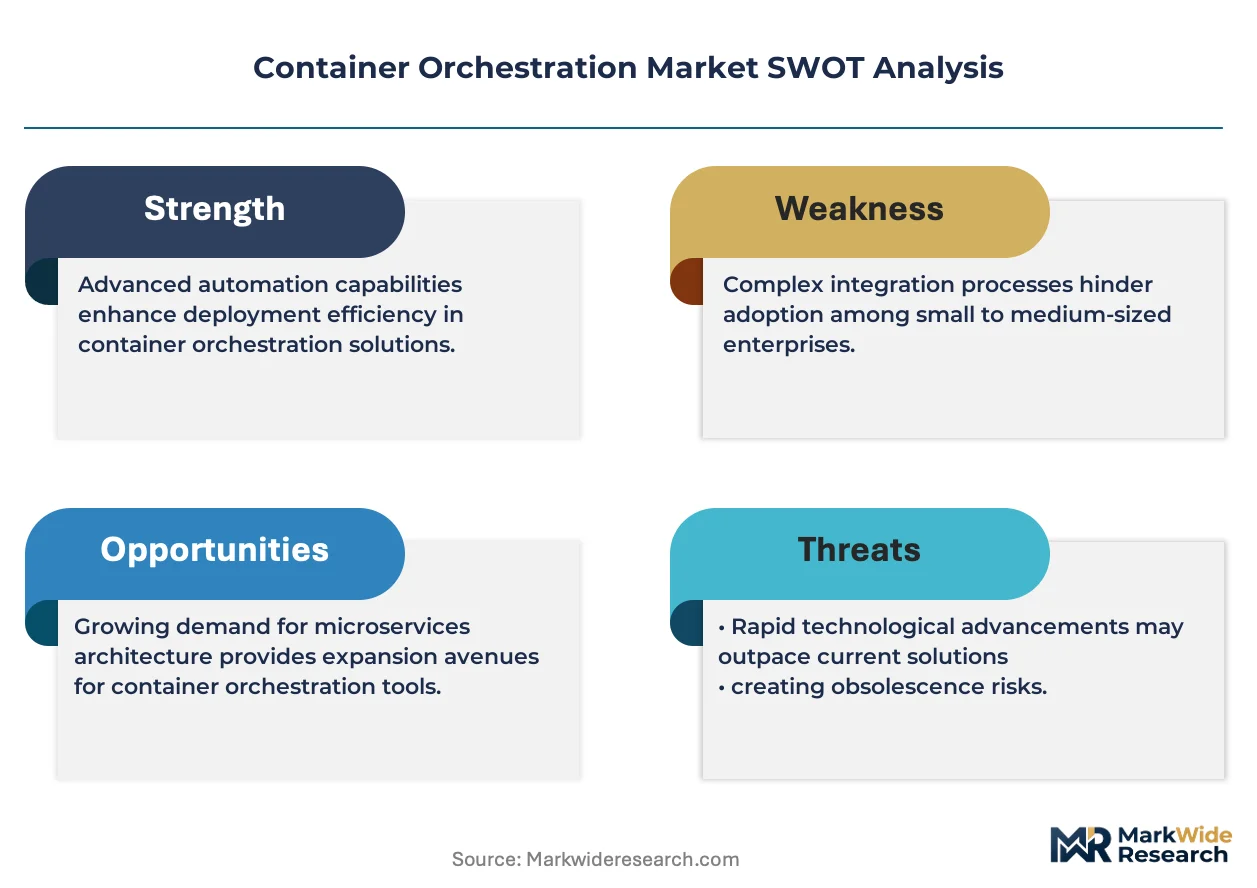
Container orchestration is consolidating around hyperscale cloud providers with upstream project stewardship, as sovereign cloud mandates and certification barriers eliminate asset-light competitors lacking engineering depth or authorization timelines.
For Market Incumbents: Anticipate multi-cluster governance complexity eroding customer retention as enterprises struggle to enforce consistent policy across heterogeneous environments. Invest in internal developer portal capabilities and air-gapped sovereign deployment architectures to defend against specialized platform engineering consultancies. Prioritize FedRAMP authorization pipeline acceleration to capture public-sector procurement cycles stretching 12-18 months. For New Entrants and Emerging Players: India's BIS cloud standards and Digital Personal Data Protection Act localization directives open a window for domestically hosted control plane development serving air-gapped government deployments. Target lightweight Kubernetes distributions for manufacturing edge sites with intermittent connectivity, where hyperscale managed services lack deployment flexibility. Lead with runtime security convergence offerings that absorb eBPF-based threat detection into orchestration platforms. For Investors and Strategic Acquirers: The window for entry favors platform engineering consultancies with demonstrated sovereign cloud deployment expertise and established government certification relationships. Long-term viability hinges on upstream Kubernetes contribution access and embedded customer workflow integration. Monitor FedRAMP authorization timeline compression as the inflection signal indicating regulatory barrier reduction and competitive entry opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Feature Development | Enables compliance with India's BIS standards and EU data residency mandates for government contracts. |
| Runtime Security Platform Integration | Absorbs eBPF-based threat detection to collapse separate security procurement decisions at European banks. |
| Internal Developer Portal Launch | Captures untapped wallet share within existing enterprise accounts through self-service infrastructure APIs. |
| Edge-Optimized Distribution Development | Serves Japanese manufacturing and telecommunications sites with intermittent connectivity requirements. |
| Certification Acceleration Investment | Compresses FedRAMP authorization cycles to capture US public-sector procurement before competitors. |
Research Approach
SEC filings from hyperscale cloud providers, open-source foundation contribution metrics, and government procurement databases formed the secondary backbone. Primary interviews with platform engineering directors, Kubernetes maintainers, federal cloud procurement officers, and financial services infrastructure architects provided operational validation. Bottom-up cluster deployment estimates and top-down cloud infrastructure spend analysis were triangulated to anchor market sizing.
Historical trendline analysis of managed Kubernetes service launches, certification timeline patterns, and enterprise containerization project pipelines informed the projection framework. Segmentation modeling spanned deployment model, solution layer, end-user type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure modernization budget allocation trends across financial services and government verticals.
The model assumes a particular technology adoption path; alternative pathways for lightweight edge distributions or serverless container platforms would alter the outlook. Forecasts reflect assumptions regarding certification timeline stability and hyperscaler bundling persistence. A model refresh is warranted upon material change in sovereign cloud mandate enforcement or upstream Kubernetes governance structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
Global Data Catalog Market
Digital Solutions
Online Home Service Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Hiking Apps Market
Digital Solutions
Global Tag Management System Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
IT Asset Management (ITAM) Software Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
China Digital Twin Market
Digital Solutions
IT Asset Management Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Global Logistics Software Market
Digital Solutions
Contactless Ticketing Solutions Market