
 Online Dating Application Market | 2026-2036
Online Dating Application Market Size, Share, and Industry Trends Forecast 2026-2036
Online Dating Application Market Intelligence
The EU AI Act is decoupling algorithmic matchmaking from opaque profiling practices across European platforms. Bumble leverages geographic expansion into emerging markets to sustain user base diversification. Hinge anchors its competitive stance through relationship-oriented positioning that differentiates from swipe-based alternatives. Tinder dominates casual user acquisition through brand strength and channel control in North American and Asian urban centers.
Online dating applications constitute software platforms that employ recommendation algorithms, geolocation services, and real-time communication protocols to facilitate romantic or social connections between users. These systems process behavioral signals, preference matrices, and demographic filters to generate compatibility scores and curate potential matches. The monetization strategy segment reveals subscription models capturing the deepest margin pools while freemium architectures drive volume penetration in price-sensitive demographics. Platform segmentation shows mobile applications leading usage intensity, though hybrid deployments are gaining traction among users seeking cross-device continuity. User type dynamics indicate serious relationship seekers generating higher lifetime value than casual cohorts despite lower absolute enrollment.
FCC oversight of telecommunications infrastructure affects video call functionality reliability, while GDPR and the EU AI Act impose consent documentation and algorithmic transparency obligations on operators serving European users. India's TRAI guidelines on digital communications intersect with platform data localization requirements, creating compliance complexity for multinational providers. Stakeholders must monitor evolving biometric authentication standards and age verification mandates as regulatory bodies tighten identity assurance protocols.
Market Dynamics
Algorithmic transparency mandates from the EU AI Act are forcing platforms to reengineer recommendation architectures and disclose automated decision-making logic to users. This regulatory pressure is reshaping competitive moats across the industry.
Growth Catalysts
- Video-first communication protocols:Real-time streaming infrastructure investments by telecommunications carriers in India and Brazil are expanding addressable user bases beyond text-based interfaces.
- GDPR-compliant consent frameworks:European platforms that architect granular data permissions are capturing privacy-conscious user segments that abandon opaque alternatives.
- Young professional cohort expansion:Urban employment density in São Paulo, Mumbai, and Dallas is concentrating time-constrained users seeking efficient matching algorithms.
Market Restraints
- Biometric authentication infrastructure costs:Liveness detection and facial verification systems require substantial capital deployment for age assurance compliance.
- Data localization mandates:India's TRAI guidelines and Russia's sovereign internet policies fragment cloud architectures and multiply operational footprints.
- Trust erosion from synthetic media:Generative AI-produced profile imagery degrades platform integrity and increases manual moderation burdens.
Strategic Opportunities
- Voice-native interfaces:Audio-first matching protocols are penetrating Brazilian and Mexican markets where literacy barriers limit text-based adoption.
- AI Act algorithmic auditing services:Third-party verification of recommendation fairness creates B2B revenue streams for compliance-technology vendors.
- Community-based sub-platforms:Niche interest graphs for religious, professional, or hobbyist cohorts reduce customer acquisition costs compared to mass-market positioning.
Industry Challenges
- Machine learning operations talent scarcity:Platform operators compete with fintech and autonomous vehicle sectors for recommendation-system engineers.
- Cross-border data transfer friction:Schrems II litigation and adequacy decision uncertainty complicate European-US data pipeline maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Dating Application Market |
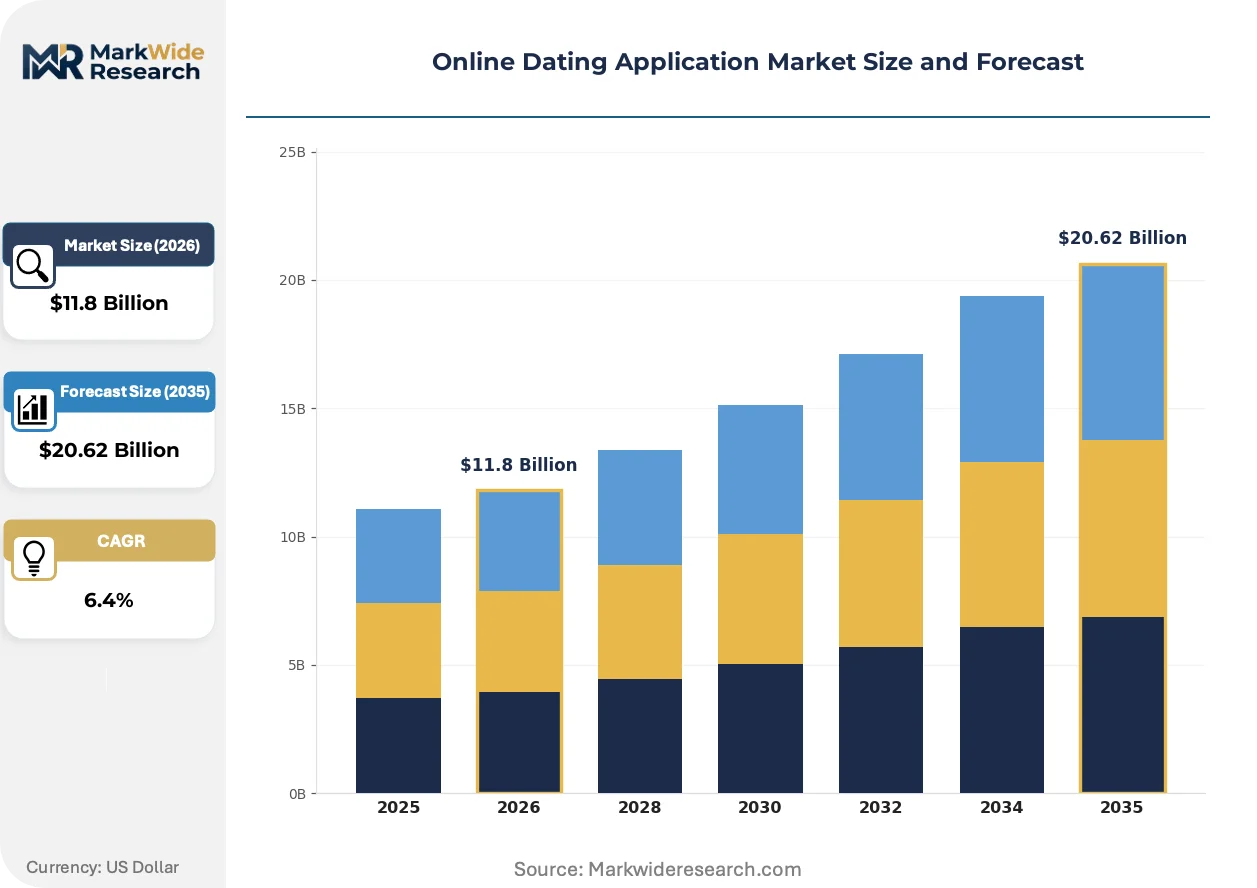
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | User Type: Casual Users, Serious Relationships, LGBTQ+, Professionals Monetization Strategy: Freemium, Subscription, Ads, In-app Purchases Platform: Mobile App, Web-based, Hybrid, Desktop Functionality: Chat Features, Video Calls, Match Algorithms, Profiles |
| Companies Covered | Match.com, Grindr, Tinder, eHarmony, Plenty of Fish, Bumble, OkCupid, Happn, Hinge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Dating Application Market Strategic Shifts & Innovations
Behavioral signal processing is migrating from explicit preference declarations to passive interaction pattern analysis. Platforms are racing to infer compatibility from dwell time, message rhythm, and feature engagement rather than stated criteria.
Large language model-powered conversation assistance is consolidating user retention through real-time icebreaker suggestions and dialogue coaching. Young professionals in Chicago and Singapore adopt these tools fastest, compressing the path from match initiation to in-person meeting. The technology is consolidating competitive differentiation around perceived user success rates rather than raw match volume.
The EU AI Act's prohibition on emotion recognition in biometric categorization systems is forcing European platforms to strip sentiment analysis from video call features. Operators serving France and Germany must document algorithmic logic for compatibility scoring and provide human review options for contested decisions. Serious relationship-seeking segments in these markets are migrating toward platforms with published transparency reports.
Subscription fatigue among urban millennials is fragmenting payment willingness across micro-transaction and token-based models. Casual users in Los Angeles and London now prefer per-feature unlocking over recurring commitments, while serious seekers maintain subscription loyalty for advanced filtering. This bifurcation is pressuring revenue architecture standardization across North American and Western European markets.
Online Dating Application Market Segmentation
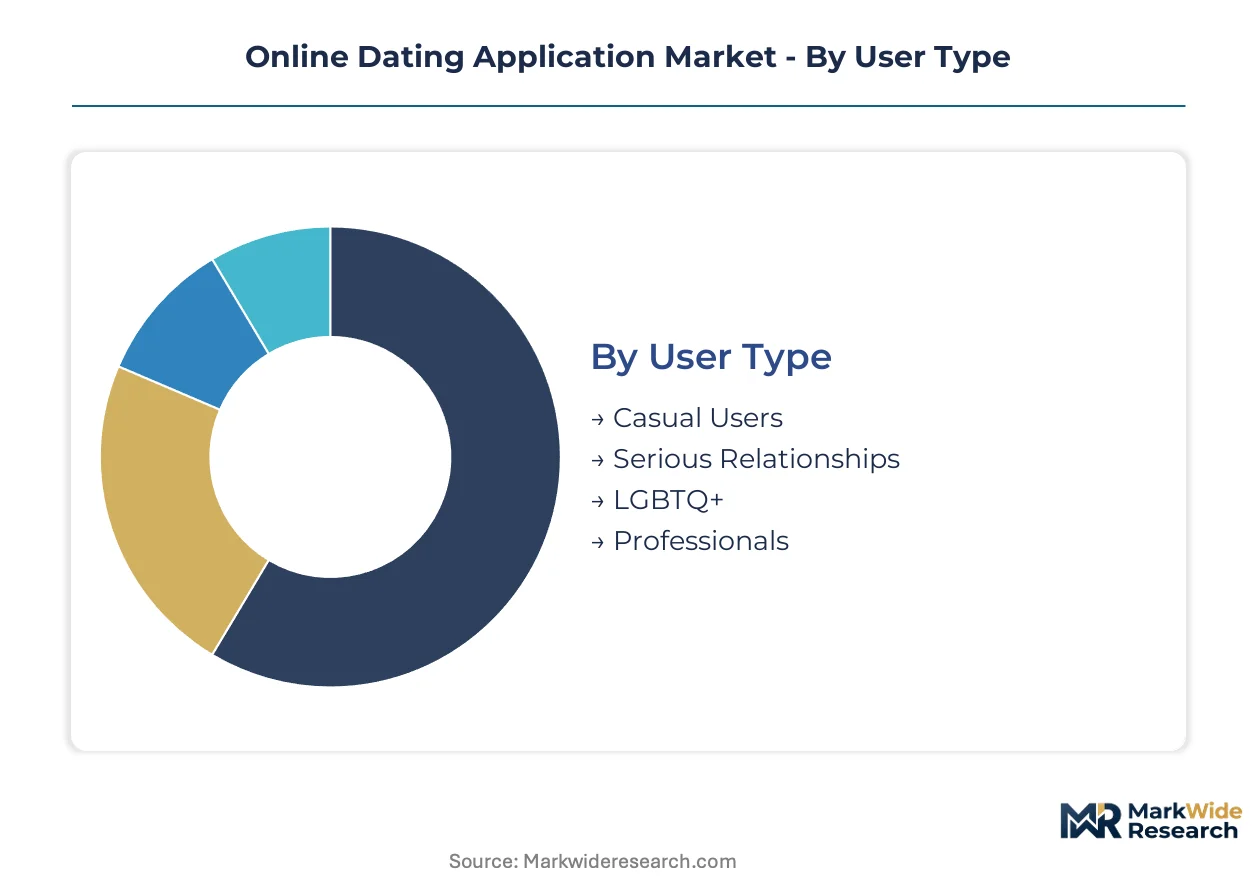
Online dating applications segment across user motivation, revenue architecture, device preference, and core functionality. These dimensions determine customer lifetime value, engineering resource allocation, and regulatory exposure for platform operators.
User Type:
Upgrade cycles vary dramatically by relationship intent, with casual cohorts churning fastest and professional segments demanding premium feature refreshes.
- Serious Relationships:Users seeking long-term partnerships engage most intensively with compatibility questionnaires and verification protocols. Demand concentrates in Dallas, Mumbai, and São Paulo where urban employment density compresses courtship timelines. These subscribers sustain the highest lifetime value despite lower absolute enrollment.
- Casual Users:This cohort prioritizes interface velocity and immediate match volume over depth of screening. North American and Asian urban centers generate the densest usage clusters, though GDPR-compliant European alternatives are capturing privacy-conscious defectors from opaque platforms.
- LGBTQ+:Niche safety features and community verification drive platform selection within this segment.
- Professionals:Time-constrained users in Chicago and Singapore adopt AI-assisted conversation tools fastest, compressing path-to-meeting intervals.
Serious relationship seekers sit at the top of the lifetime value ranking, with professionals climbing the fastest.
Monetization Strategy:
Revenue architecture stratifies by customer price sensitivity, with subscription models capturing margin pools and freemium driving volume in emerging markets.
- Subscription:Recurring revenue models fund advanced filtering, unlimited messaging, and priority profile placement. Young professionals in Los Angeles and London maintain loyalty here despite broader subscription fatigue, while São Paulo and Mumbai users treat premium tiers as efficiency investments.
- Freemium:Base functionality with paywalled enhancements penetrates price-sensitive demographics in Brazil and India. TRAI-guided data localization requirements in India fragment cloud cost structures for operators serving this tier.
- Ads:Impression-based revenue sustains zero-cost user acquisition in high-volume, low-conversion cohorts.
- In-app Purchases:Micro-transaction and token-based unlocking fragments payment willingness among casual urban millennials.
Subscription models dominate revenue concentration, with in-app purchases expanding most quickly as casual users reject recurring commitments.
Platform:
Device preference reflects connectivity infrastructure maturity and cross-device continuity expectations across user demographics.
- Mobile App:Smartphone-native interfaces lead usage intensity globally, with Brazilian and Mexican markets driving voice-native adoption where literacy barriers limit text-based matching. FCC telecommunications oversight affects video call reliability on these platforms.
- Hybrid:Cross-device continuity deployments gain traction among serious relationship seekers who value seamless transition between mobile discovery and desktop profile management.
- Web-based:Browser-accessible platforms serve users with storage-constrained devices or institutional download restrictions.
- Desktop:Legacy installations persist among older demographics preferring full-keyboard profile composition.
Mobile applications command the volume leadership position, with hybrid deployments gaining share fastest as cross-device expectations harden.
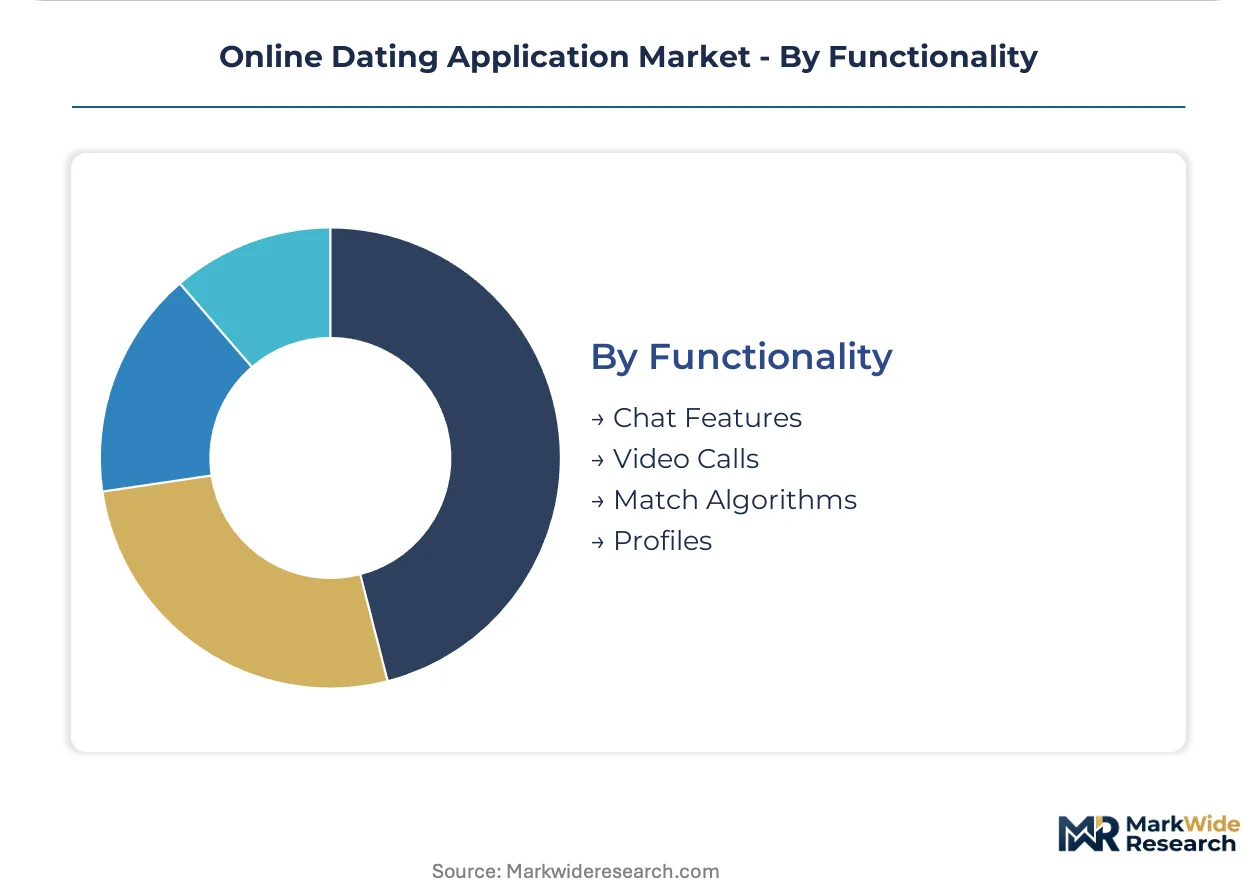
Functionality:
Feature investment priorities diverge between markets emphasizing real-time intimacy and those prioritizing algorithmic curation.
- Video Calls:Real-time streaming infrastructure investments by telecommunications carriers in India and Brazil expand addressable bases beyond text interfaces. EU AI Act prohibitions on emotion recognition in biometric categorization force European platforms to strip sentiment analysis from these features.
- Match Algorithms:Recommendation systems process behavioral signals, preference matrices, and demographic filters to generate compatibility scores. GDPR and EU AI Act mandates require disclosure of automated decision-making logic to users.
- Chat Features:Large language model-powered conversation assistance consolidates retention through real-time icebreaker suggestions.
- Profiles:Identity verification and liveness detection requirements escalate capital deployment for age assurance compliance.
Match algorithms anchor competitive differentiation, with video calls expanding most quickly as infrastructure investments mature in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young professionals in São Paulo, Mumbai, and Dallas concentrate demand for efficient matching algorithms. Urban employment density compresses courtship timelines across these metropolitan clusters. Platform operators tailor feature sets to time-constrained cohorts seeking rapid compatibility assessment.
United States
FCC telecommunications oversight shapes video call reliability for platform operators serving urban millennials in Los Angeles and Chicago. Subscription fatigue fragments payment willingness toward micro-transaction models among casual users. Dallas anchors serious relationship-seeking demand where premium tier loyalty persists despite broader churn patterns.
Brazil
Telecommunications carrier investments in real-time streaming infrastructure expand addressable bases beyond text-based interfaces. ANVISA guidelines intersect with platform data handling requirements for health-adjacent verification features. São Paulo drives voice-native adoption where literacy barriers limit traditional profile composition.
India
TRAI guidelines on digital communications create compliance complexity for multinational providers serving price-sensitive demographics. Data localization mandates fragment cloud architectures and multiply operational footprints for freemium-tier operators. Mumbai concentrates young professional demand where premium tiers function as efficiency investments.
Germany
GDPR enforcement reshapes data consent architectures with granular permission requirements. EU AI Act mandates force disclosure of automated decision-making logic for algorithmic matchmaking systems. Berlin anchors privacy-conscious user segments migrating toward platforms with published transparency reports.
United Kingdom
Ofcom oversight of digital communications infrastructure affects platform reliability standards for London-based users. Subscription fatigue among urban millennials drives experimentation with token-based unlocking models. The capital's density sustains hybrid deployment adoption for cross-device continuity seekers.
Online Dating Application Market Key Industry Players
Capital-heavy producers compete with asset-light designers across divergent monetization architectures. The vendor base stratifies between subscription-dependent incumbents and freemium-native challengers seeking volume penetration. Three archetypes dominate: swipe-based casual platforms, relationship-oriented differentiated services, and niche community-verified alternatives. Geographic expansion and algorithmic transparency investments constitute the dominant competitive vectors reshaping positioning.
Within the relationship-oriented tier, Hinge and eHarmony occupy positions emphasizing compatibility depth over match velocity. Bumble exemplifies the geographic expansion archetype through emerging market penetration strategies. Among swipe-based alternatives, Tinder anchors the casual user acquisition segment through brand strength in North American and Asian urban centers. Match.com sits within the portfolio-consolidation archetype, representing multi-brand operator structures that diversify across user motivation segments. These named entities illustrate strategic positioning patterns rather than exhaust market coverage.
| Leading Market Players |
|---|
| Match.com |
| Grindr |
| Tinder |
| eHarmony |
| Plenty of Fish |
| Bumble |
| OkCupid |
| Happn |
| Hinge |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up platform operators concentrate supply-side control over cloud infrastructure and recommendation-engine talent pools, translating capital discipline into subscription pricing power across North American and European markets. This ownership structure feeds pricing stratification between premium subscription tiers and freemium volume plays while shaping geographic deployment priorities for data center capacity.
Pricing Analysis
Bundled all-access subscriptions versus unbundled micro-transaction unlocking splits the market between recurring revenue loyalty and per-feature flexibility. Three-tier pricing structure across premium, standard, and economy levels anchors the dominant model, with premium tiers differentiated by advanced filtering and AI-assisted conversation tools. Cost compression in the freemium tier intensifies because telecommunications carriers in India and Brazil demand revenue-sharing for video infrastructure. Casual urban millennials exhibit highest price sensitivity, while serious relationship seekers maintain lowest sensitivity due to perceived efficiency returns.
Supply Chain Analysis
Cloud computing capacity rests on hyperscaler infrastructure concentrated in the United States, Ireland, and Singapore, with edge node expansion accelerating in São Paulo and Mumbai. Platform operators draw from GPU clusters for recommendation training, real-time streaming protocols for video features, and liveness detection APIs for age verification. Single-source vulnerability in facial recognition SDKs creates concentration risk for compliance-dependent operators. Distribution runs through mobile app stores and direct-to-consumer web channels, with platform fees compressing net margins on in-app purchase flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates compound competitive advantage for platforms investing in explainable recommendation systems, creating structural demand for compliance-technology integration. This regulatory milestone reshapes capital allocation toward audit-ready architectures.
For Market Incumbents: Deploy algorithmic auditing capabilities as a defensive moat against emerging challengers exploiting GDPR-compliant positioning. Incumbents should consolidate channel control through exclusive telecommunications partnerships in India and Brazil while investing in voice-native interfaces to capture literacy-constrained demographics. Synthetic media detection R&D represents essential capacity addition to defend platform integrity against generative AI profile fraud. For New Entrants and Emerging Players: Voice-first matching protocols in Brazilian and Mexican markets offer the most penetrable white-space for asset-light challengers. Niche community-verified sub-platforms targeting religious, professional, or hobbyist cohorts reduce customer acquisition costs versus mass-market positioning. A direct-to-mobile distribution strategy bypassing established app store gatekeepers enables faster iteration on culturally localized feature sets. For Investors and Strategic Acquirers: Telecommunications carriers seeking vertical integration into digital services represent the most active acquirer in this space. Five-to-ten year viability hinges on regulatory compliance infrastructure as a durable competitive asset. Acquisition targets should demonstrate published transparency reports and EU AI Act audit readiness. The signal to watch is Schrems II litigation outcomes affecting transatlantic data pipeline economics.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Investment | EU AI Act compliance creates defensible positioning in European markets against opaque alternatives. |
| Voice-Native Interface Development | Brazilian and Mexican market penetration accelerates where literacy barriers limit text-based matching. |
| Telecommunications Partnership | Carrier alliances in India and Brazil secure preferential video streaming infrastructure access. |
| Community-Verified Sub-Platform Launch | Niche interest graphs reduce acquisition costs compared to undifferentiated mass-market positioning. |
| Synthetic Media Detection Integration | Generative AI profile fraud mitigation preserves platform integrity and moderates manual review burdens. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined through structured interviews and secondary validation. Conversations with platform product managers, regulatory compliance officers, telecommunications infrastructure planners, and dating application users informed demand-side and supply-side dynamics. Secondary sources include SEC filings from listed operators, TRAI and FCC regulatory dockets, EU AI Act implementation guidance, and mobile application analytics from Sensor Tower. Bottom-up user cohort modeling and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition separates user growth from monetization intensity shifts across the projection horizon. Segmentation dimensions modeled include user motivation archetype, revenue architecture, device preference, and core functionality investment. CAGRs derive from cohort-based lifetime value projections and geographic penetration curves. Forecast inputs incorporate telecommunications infrastructure investment timelines and biometric authentication regulatory rollout schedules.
The model assumes a particular technology adoption path; alternative pathways for emotion recognition in video features would alter the outlook given EU AI Act prohibitions. Forecasts reflect assumptions about GDPR enforcement consistency and data localization mandate expansion. Regulatory acceleration or relaxation in India, Brazil, or European markets represents the primary revision trigger. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
Service Orchestration Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
Express Digitizer Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
Mobile Campaign Management Platform Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
India Digital Twin Market
Digital Solutions
United States Contract Manufacturing Services Market