
 Cloud-Based Product Lifecycle Management (PLM) Market | 2026-2036
Cloud-Based Product Lifecycle Management (PLM) Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud-Based Product Lifecycle Management (PLM) Market Outlook
The capital-intensity divergence between hyperscale platform operators and specialized configuration houses is redrawing competitive boundaries in cloud PLM. Dassault Systèmes leverages its 3DEXPERIENCE platform to anchor high-complexity aerospace and automotive programs with deep digital-twin integration. Siemens sustains position through Teamcenter X and its captive industrial software ecosystem, while Aras competes with an open-model architecture that reduces lock-in for mid-market manufacturers.
Cloud-based Product Lifecycle Management constitutes a software architecture that centralizes product data, engineering workflows, and cross-functional collaboration across distributed teams through browser-accessible platforms, typically employing multi-tenant SaaS delivery with API-first integration frameworks to synchronize CAD, simulation, and supply chain systems. Its primary commercial purpose is compressing design-to-manufacturing cycles while maintaining revision control and compliance traceability. Public cloud deployments dominate volume among consumer goods and retail adopters seeking elastic capacity, whereas hybrid cloud configurations capture the steepest growth trajectory as aerospace and automotive manufacturers balance latency-sensitive engineering workstations with centralized data governance. ERP integration represents the most contested margin pool, since connecting PLM instances to SAP SE or Oracle financial and procurement modules requires substantial professional services and recurring integration maintenance.
FDA 21 CFR Part 11 requirements for electronic records in medical device development shape validation protocols for cloud PLM vendors serving regulated industries, while the EU AI Act imposes conformity obligations on AI-embedded design automation tools. ISO 27001 and SOC 2 Type II certifications have become baseline market-access credentials rather than differentiators. Stakeholders must weigh sovereign cloud mandates against the interoperability limitations of region-locked data residency architectures.
Market Dynamics
Cloud-native PLM architectures are fragmenting the traditional enterprise software stack as aerospace and automotive manufacturers demand sovereign data residency alongside real-time engineering collaboration. This structural tension between centralized governance and distributed execution is forcing vendors to rebuild platform foundations.
Growth Catalysts
- EU AI Act Conformity Obligations:Manufacturers embedding AI-driven generative design tools must demonstrate audit trails and risk management protocols, creating mandatory upgrade cycles for legacy PLM instances.
- Hybrid Cloud Configurations:German automotive OEMs and their tiered supplier networks are migrating engineering workstations to edge-connected environments that synchronize with centralized data lakes.
- Digital Thread Integration:Aerospace programs require continuous bidirectional data flow between CAD, simulation, and manufacturing execution systems, compressing design validation cycles.
Market Restraints
- ERP Integration Complexity:Connecting PLM platforms to SAP SE or Oracle financial modules demands substantial professional services expenditure and recurring maintenance overhead.
- Region-Locked Data Residency:Sovereign cloud mandates in France, Germany, and Switzerland fragment platform architectures and limit vendor economies of scale.
- Validation Protocol Rigor:FDA 21 CFR Part 11 requirements for electronic records impose multi-month certification timelines on medical device PLM deployments.
Strategic Opportunities
- Mid-Market Manufacturing:Open-model architectures reduce vendor lock-in for industrial equipment producers in Italy and Spain seeking modular PLM adoption paths.
- AI-Embedded Design Automation:Convergence of machine learning inference with parametric modeling enables generative engineering workflows for consumer electronics development.
- Sovereign Cloud Infrastructure:Gaia-X compliant data spaces in Germany and France create procurement channels for defense and public sector manufacturing programs.
Industry Challenges
- Multi-Tenant Security Architecture:SaaS PLM vendors must isolate intellectual property across competing OEM tenants while maintaining sub-second query performance for large assemblies.
- Skills Scarcity in Cloud Migration:System integrators face shortages of engineers proficient in both legacy CAD data structures and Kubernetes-orchestrated container environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud-Based Product Lifecycle Management (PLM) Market |
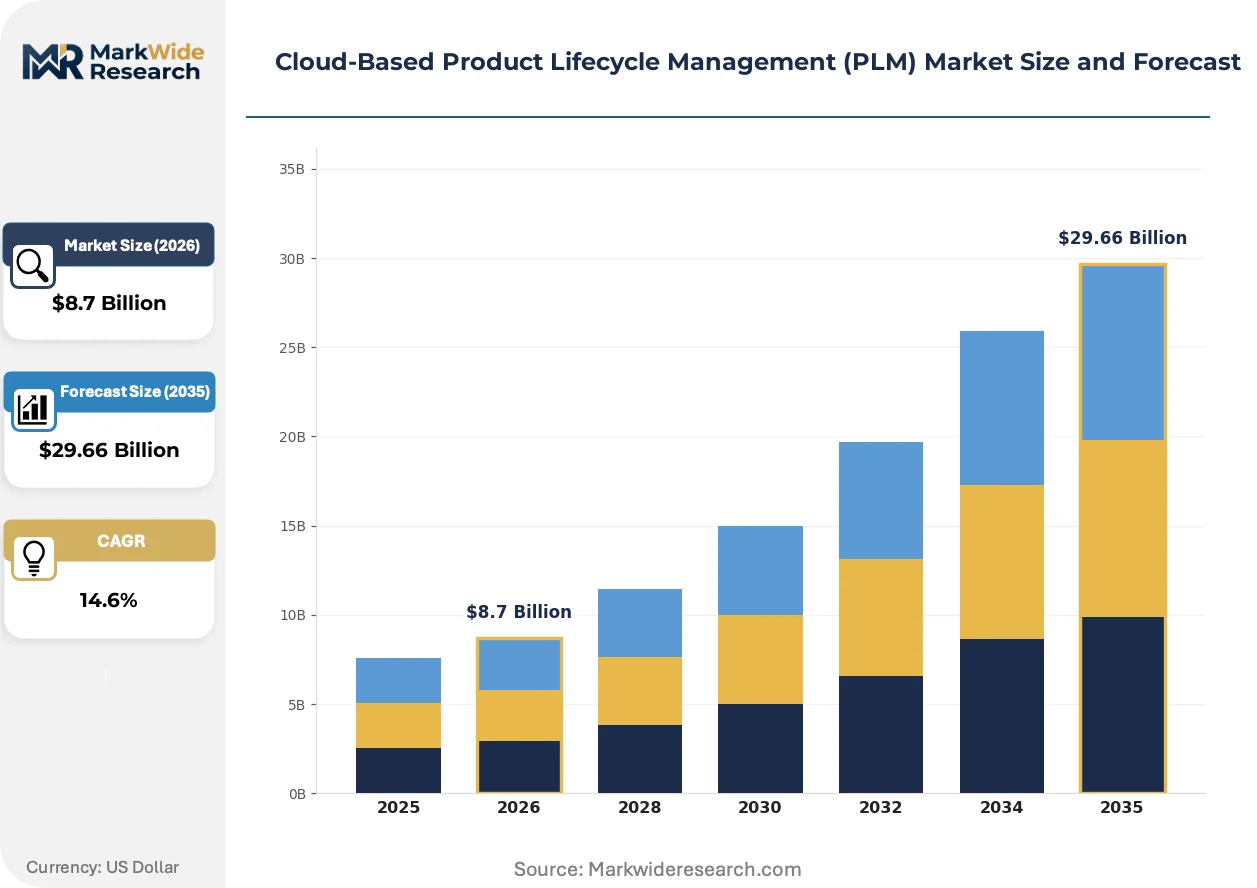
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Collaboration Tools, Data Management, Compliance Management, Analytics Services End User: Manufacturers, Retailers, Aerospace, Consumer Goods Integration Level: Standalone Solutions, ERP Integration, IoT Integration, Custom Integration |
| Companies Covered | Dassault Systèmes, Siemens, PTC Inc., Autodesk, Inc., SAP SE, Oracle, ANSYS, Inc., Aras, Infor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud-Based Product Lifecycle Management (PLM) Market Strategic Shifts
Browser-accessible engineering platforms are collapsing the boundary between design authoring and manufacturing planning. Three developments are compressing traditional software procurement and deployment models.
API-first integration frameworks are fragmenting the monolithic PLM stack into composable microservices. Automotive suppliers in Stuttgart and Munich are adopting modular data connectors that synchronize CAD revisions directly with supplier quality management portals. This architectural shift is fragmenting vendor control over the full engineering workflow, enabling best-of-breed tool selection.
CSRD sustainability reporting mandates in the European Union require granular material traceability across product lifecycles. PLM platforms must now embed carbon accounting modules that track embodied emissions from raw material extraction through end-of-life recycling. German automotive OEMs are retrofitting existing deployments to capture supplier sustainability certifications at the component level.
Subscription consumption models are displacing perpetual license structures in mid-market manufacturing segments. Industrial machinery producers in Northern Italy are purchasing seat-based access to simulation and visualization tools rather than maintaining dedicated on-premise servers. This behavioral shift concentrates procurement authority within finance functions rather than engineering IT departments.
Cloud-Based Product Lifecycle Management (PLM) Market Segmentation
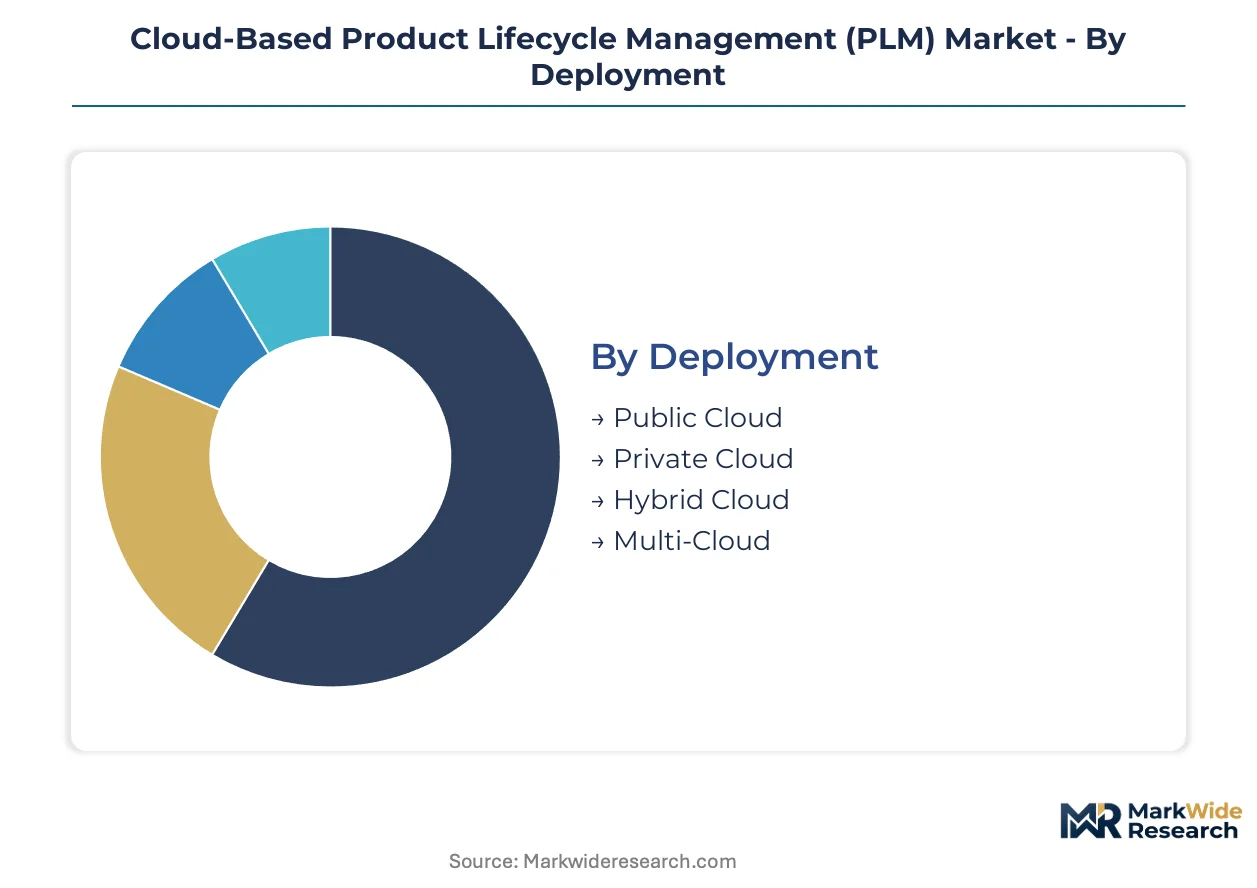
Cloud PLM segmentation reveals how deployment architectures, solution depth, and integration intensity fragment procurement patterns across manufacturing verticals. Each dimension carries distinct margin structures and vendor competitive dynamics.
Deployment:
Substitution pressure runs strongest against single-tenant private cloud configurations as sovereign cloud mandates and latency requirements reshape infrastructure choices.
- Public Cloud:Multi-tenant SaaS platforms deliver elastic compute capacity through browser-accessible interfaces. Consumer goods manufacturers in the United States and retail adopters dominate this segment, driven by seasonal demand spikes and minimal data sovereignty constraints. Public Cloud retains volume leadership; Hybrid Cloud holds the steepest expansion curve.
- Hybrid Cloud:Edge-connected engineering workstations synchronize with centralized data lakes, balancing latency-sensitive CAD operations with governance requirements. German automotive OEMs and their tiered supplier networks are migrating to this architecture to satisfy GDPR and EU AI Act compliance while preserving real-time collaboration.
- Private Cloud:Single-tenant dedicated infrastructure serves defense contractors and medical device manufacturers with stringent isolation mandates. The FDA's 21 CFR Part 11 validation protocols and ITAR restrictions in the United States sustain niche demand despite higher total cost of ownership.
- Multi-Cloud:Distributed workloads span AWS, Azure, and sovereign cloud providers to mitigate vendor lock-in and satisfy data residency requirements. French aerospace programs and Swiss precision manufacturers deploy this architecture to navigate fragmented regulatory landscapes.
Hybrid Cloud captures the steepest expansion trajectory as manufacturers reconcile governance mandates with engineering velocity.
Solution Type:
Margin concentration follows integration depth, with standalone collaboration tools facing commoditization pressure from embedded platform capabilities.
- Data Management:Centralized product data repositories with revision control, BOM management, and digital thread orchestration form the technical core of PLM value. Aerospace programs in France and Germany require these capabilities to maintain configuration traceability across multi-year development cycles.
- Collaboration Tools:Real-time co-authoring, markup, and supplier portal access enable distributed engineering teams. These capabilities are embedding into broader platform suites, compressing standalone pricing power.
- Compliance Management:Automated audit trails, electronic signatures, and regulatory submission packaging address FDA, EMA, and EU AI Act requirements. Medical device manufacturers in Ireland and the Netherlands prioritize this functionality to accelerate market authorization timelines.
- Analytics Services:Predictive maintenance, design optimization, and carbon accounting modules leverage machine learning inference. CSRD sustainability reporting mandates in the European Union are accelerating procurement of embodied emissions tracking capabilities.
Data Management commands the largest revenue share; Analytics Services is climbing fastest as AI-embedded workflows mature.
End User:
Application complexity determines pricing architecture, with aerospace and medical device verticals sustaining premium tiers against price-sensitive consumer goods procurement.
- Manufacturers:Industrial machinery and automotive producers constitute the foundational demand base, spanning mid-market machinery builders in Northern Italy to tier-one automotive suppliers in Stuttgart.
- Aerospace:Airframe and propulsion system developers require digital-twin integration and multi-decade configuration management. Boeing suppliers in Washington state and Airbus ecosystems in Toulouse drive specialized functional requirements.
- Consumer Goods:Electronics and apparel brands prioritize speed-to-market and supplier collaboration over engineering complexity. This segment exhibits the shortest sales cycles and highest price elasticity.
- Retailers:Private-label product development teams leverage PLM for sourcing coordination and sustainability certification tracking. European fashion retailers are retrofitting platforms to capture CSRD-mandated supply chain disclosures.
Manufacturers anchor volume demand; Aerospace generates the highest per-seat revenue realization.
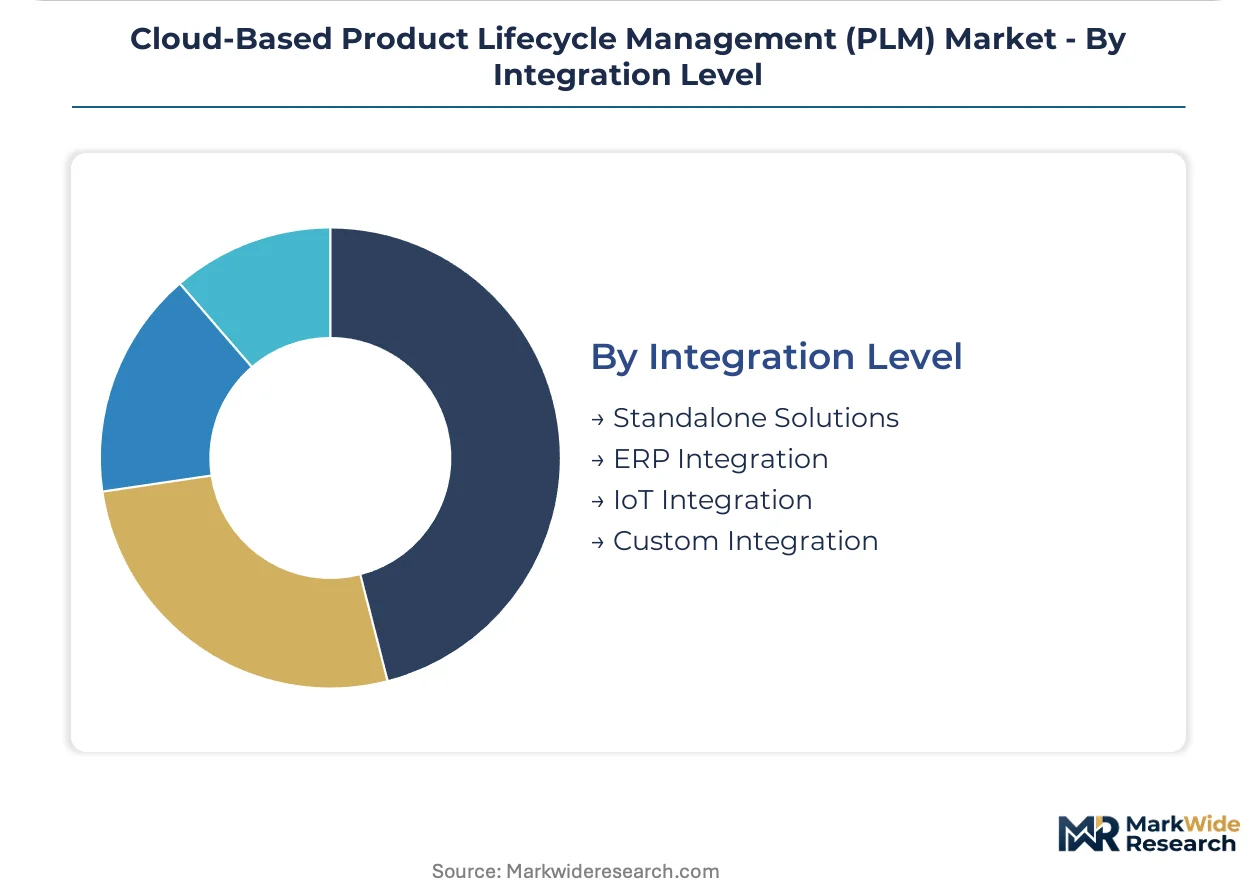
Integration Level:
Professional services intensity escalates with integration depth, fragmenting margin capture between platform vendors and systems integrators.
- ERP Integration:Synchronization with SAP SE and Oracle financial, procurement, and manufacturing modules demands substantial implementation services. This category concentrates recurring integration maintenance revenue and customer switching costs.
- IoT Integration:Bidirectional data flow between PLM platforms and manufacturing execution systems enables closed-loop quality feedback. Automotive OEMs in Bavaria deploy these connections to compress design validation cycles.
- Standalone Solutions:Discrete PLM deployments without external system connectivity serve pilot programs and niche engineering functions. Limited expansion potential constrains vendor lifetime value.
- Custom Integration:Bespoke API development and middleware configuration address legacy system coexistence requirements. Defense and public sector programs in France and Germany sustain this segment through Gaia-X compliant procurement channels.
ERP Integration dominates services revenue; IoT Integration is expanding most quickly as digital thread architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and France where aerospace and automotive OEMs mandate sovereign cloud architectures, while volume procurement dominates in the United States where public cloud elasticity serves consumer goods manufacturers with minimal data residency constraints.
United States
FDA 21 CFR Part 11 validation requirements and ITAR restrictions sustain demand for private cloud configurations among defense contractors and medical device developers. The FAA oversees electronic records protocols for aerospace suppliers in Washington state and Southern California. Boeing's supplier ecosystem in Seattle anchors specialized digital-twin integration deployments.
Germany
GDPR compliance and the EU AI Act's conformity obligations are accelerating migration from legacy on-premise stacks to hybrid cloud environments. KBA automotive safety regulations intersect with Gaia-X sovereign cloud procurement mandates for public sector programs. Stuttgart and Munich host tier-one automotive supplier networks synchronizing edge-connected engineering workstations with centralized data lakes.
France
ANSM medical device traceability requirements and CNIL data protection rulings shape validation protocols for regulated industries. CSRD sustainability reporting mandates drive retrofitting of carbon accounting modules across aerospace supply chains. Toulouse anchors Airbus ecosystem demand for multi-decade configuration management and digital thread architectures.
Switzerland
Swissmedic pharmaceutical quality regulations and federal data residency laws sustain premium pricing for isolated single-tenant infrastructure. Precision manufacturers in Basel and Zurich deploy multi-cloud architectures spanning AWS, Azure, and sovereign providers to navigate fragmented regulatory landscapes. Medical technology clusters require sub-second query performance for large assembly IP isolation.
United Kingdom
Post-Brexit regulatory divergence from EU MDR frameworks creates parallel certification pathways for medical device PLM deployments. The MHRA oversees electronic records validation for pharmaceutical development programs. London's financial services manufacturing and Cambridge's life sciences clusters exhibit divergent procurement patterns between compliance-heavy and speed-to-market priorities.
Cloud-Based Product Lifecycle Management (PLM) Market Competitive Environment
Concentration sits with diversified industrial software conglomerates that anchor high-complexity aerospace and automotive programs through captive ecosystem integration. The vendor base stratifies across three tiers: hyperscale platform operators with deep digital-twin capabilities, open-model specialists reducing lock-in for mid-market manufacturers, and ERP-integrated suites capturing professional services revenue. Dominant competitive moves include strategic partnerships with sovereign cloud providers and portfolio diversification into AI-embedded design automation.
Within the diversified industrial software tier, Dassault Systèmes, Siemens, and PTC Inc. occupy positions defined by ecosystem depth and vertical integration breadth. Dassault Systèmes exemplifies the platform-centric archetype through its 3DEXPERIENCE architecture. Siemens represents the captive industrial software model with Teamcenter X and adjacent automation portfolios. PTC Inc. sits within the CAD-origin expansion pattern, extending parametric modeling heritage into cloud-native delivery. These three anchors illustrate how geographic origin—French, German, and American respectively—correlates with regulatory compliance specialization and regional procurement channel access.
| Leading Market Players |
|---|
| Dassault Systèmes |
| Siemens |
| PTC Inc. |
| Autodesk, Inc. |
| SAP SE |
| Oracle |
| ANSYS, Inc. |
| Aras |
| Infor |
| Others |
Value Chain & Pricing Dynamics
FDA 21 CFR Part 11 validation protocols gate both vendor qualification and price differentiation in regulated PLM deployments, compressing margins for non-compliant suppliers while enabling premium capture by certified platform operators serving medical device and aerospace programs.
Pricing Analysis
Configured-to-order pricing commands substantial premiums over standard SaaS tiers in cloud PLM procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration depth and compliance certification, with aerospace and medical device manufacturers exhibiting lowest price sensitivity due to validation requirements. Cost compression in mid-market manufacturing segments is intensifying because subscription consumption models displace perpetual licenses, transferring procurement authority to finance functions. Consumer goods and retail adopters demonstrate highest price elasticity, prioritizing elastic capacity over sovereign cloud features.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for hardware-dependent private cloud deployments. Platform development concentrates in the United States, Germany, and France, with sovereign cloud infrastructure sourcing from domestic providers in each jurisdiction. Supply chains draw from specialized semiconductor components for edge-connected engineering workstations, API middleware licensing, and Gaia-X compliant data center capacity. Single-source vulnerability runs through hyperscale cloud provider dependencies for multi-tenant SaaS architectures. Distribution runs through direct enterprise sales teams and systems integrator partnerships for complex ERP integration deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward automotive OEM procurement consortiums consolidating supplier negotiations, fragmenting pricing autonomy for standalone PLM vendors.
For Market Incumbents: Compound ecosystem lock-in through deeper digital-twin integration and captive automation portfolio bundling. Vertical integration into sovereign cloud infrastructure addresses EU AI Act conformity obligations while raising switching costs. Defend against open-model challengers by embedding AI-driven generative design tools directly into core platform workflows. For New Entrants and Emerging Players: Lead with modular API-first architectures targeting mid-market industrial machinery producers in Italy and Spain seeking reduced vendor lock-in. White-space opportunity sits with CSRD sustainability reporting compliance modules for European fashion retailers retrofitting supply chain disclosure capabilities. Go-to-market leverage centers on seat-based simulation tool subscriptions displacing on-premise server maintenance. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward sovereign cloud specialists with Gaia-X compliance credentials. Long-term viability favors platform operators capable of bridging hybrid cloud configurations for German automotive supplier networks. Acquisition target archetype: mid-scale configuration houses with established FDA validation protocols. Signal to monitor: defense sector procurement channel expansion through national sovereign cloud mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Gaia-X compliance unlocks German defense and public sector procurement channels. |
| AI-Embedded Design Automation | FDA validation protocols for AI-driven tools create mandatory upgrade cycles. |
| ERP Integration Specialist Acquisition | SAP SE and Oracle synchronization expertise captures recurring services revenue. |
| Carbon Accounting Module Launch | CSRD mandates drive retrofit demand across European aerospace supply chains. |
| Mid-Market Subscription Expansion | Seat-based access models displace perpetual licenses in Northern Italy machinery. |
Study Parameters
Two parallel data streams informed the analysis: structured conversations with CTOs, IT procurement officers, platform engineers, and integration specialists at aerospace OEMs and automotive suppliers; and secondary validation through SEC filings, hyperscaler capex disclosures, EMA submission databases, and Gaia-X compliance registries. Bottom-up sizing triangulated deployment model adoption curves against top-down macroeconomic manufacturing output indicators.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning deployment architecture, solution type depth, end-user vertical, and integration complexity tier. CAGRs derived from regression analysis against historical cloud migration velocity and regulatory compliance cycle timing. Industry-specific forecast inputs incorporated EU AI Act implementation schedules and FDA 21 CFR Part 11 validation protocol adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained sovereign cloud infrastructure investment and stable cross-border data flow regimes would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and automotive OEM consolidation patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Change Management Software Market
Digital Solutions
Digital Notepad Market
Digital Solutions
Workflow Content Automation (WCA) Market
Digital Solutions
Utility Bill Management System Market
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Inventory Management Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
Japan Online Gambling Market
Digital Solutions
Crew Management Systems Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Cloud Based Manufacturing Market