
 US Supply Chain Management Software Market | 2026-2036
US Supply Chain Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
US Supply Chain Management Software Market Analytics
FDA Drug Supply Chain Security Act (DSCSA) compliance deadlines are broadening the cost-of-entry calculus for supply chain software vendors serving life sciences. Oracle leverages its vertically integrated cloud infrastructure to dominate pharmaceutical serialization workflows. Manhattan Associates anchors warehouse execution systems through deep retail channel control. Kinaxis differentiates via concurrent planning architectures that sustain aerospace and defense contract volatility.
US Supply Chain Management Software encompasses modular applications that orchestrate procurement, inventory positioning, transportation routing, and demand sensing across multi-echelon networks, typically integrating via API layers with ERP systems and IoT sensor feeds. Cloud-Based deployment models lead adoption curves as manufacturers exit capital-intensive on-premises maintenance cycles. Demand Planning functionality captures disproportionate R&D investment as tariff volatility and nearshoring imperatives force probabilistic scenario modeling. SaaS delivery within Transportation Management is maturing fastest among Third-Party Logistics providers seeking variable-cost structures.
FDA DSCSA requirements, NHTSA autonomous vehicle data logging standards, and FERC interstate pipeline scheduling rules each compel sector-specific audit trails and real-time traceability modules. USDA food safety modernization pressures are accelerating lot-tracking granularity demands among protein distributors and cold-chain operators. Stakeholders must weigh whether to build compliant data architectures in-house or absorb vendor-specific subscription premiums as regulatory scope expands.
Market Dynamics
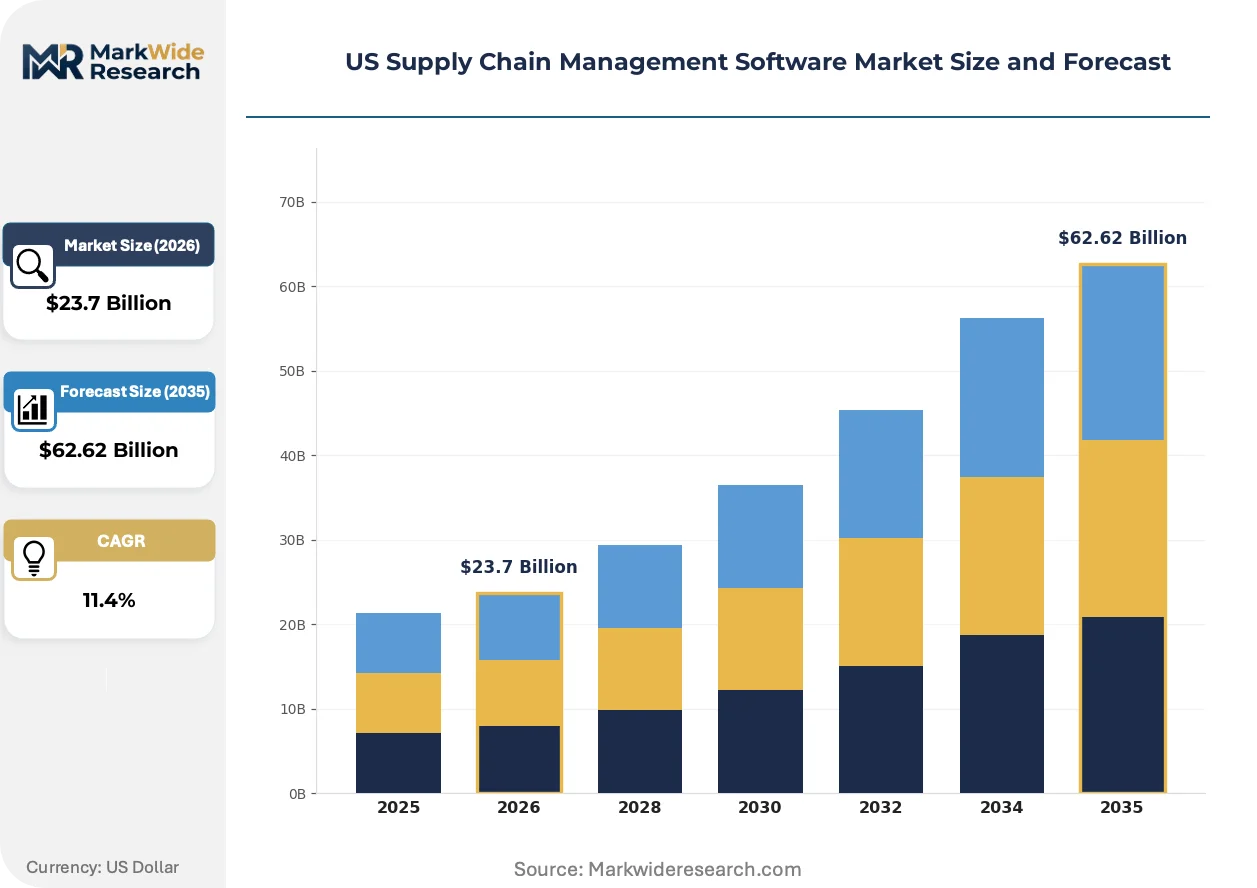
Cloud migration among Midwest automotive suppliers is concentrating demand for inventory management modules, while pharmaceutical distributors expand procurement automation to satisfy FDA track-and-trace mandates. These parallel pressures are restructuring vendor competitive calculus across deployment models and vertical specializations.
Growth Catalysts
- FDA DSCSA serialization mandates:Pharmaceutical distributors must achieve unit-level traceability by 2023 enforcement deadlines, forcing wholesale replacement of legacy track-and-stack systems with API-enabled verification architectures.
- Automotive supplier cloud concentration:Tier-1 and Tier-2 manufacturers in Michigan, Ohio, and Indiana are exiting on-premises ERP maintenance cycles, creating concentrated demand for SaaS inventory modules with EDI-native supplier portals.
- Tariff volatility scenario modeling:Discrete manufacturers facing Section 301 duty uncertainty are adopting probabilistic demand planning to stress-test inventory positioning against multi-country sourcing disruptions.
Market Restraints
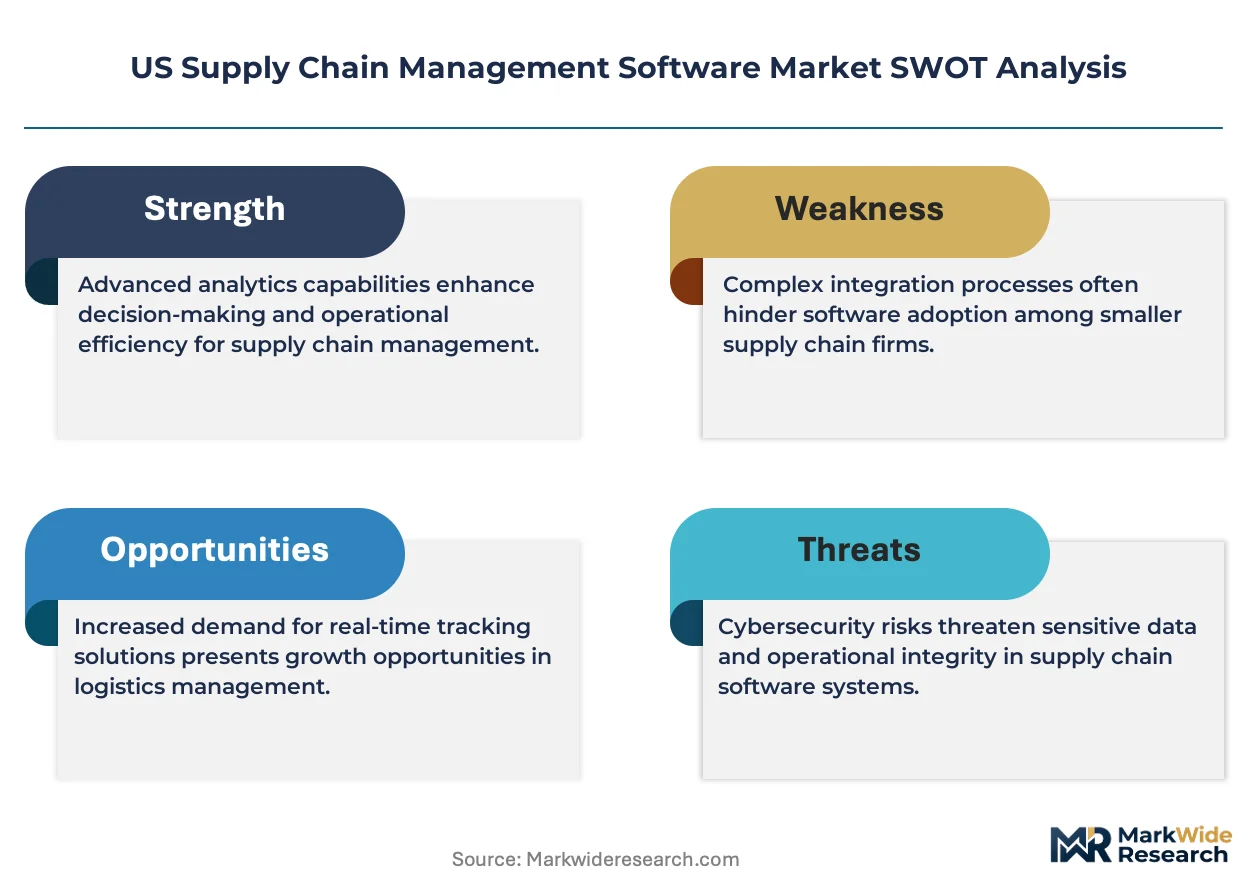
- Implementation cost compression:Mid-market manufacturers face six-figure minimum viable deployments for cloud TMS platforms, squeezing adoption below enterprise tiers despite subscription pricing.
- Legacy ERP entrenchment:SAP and Oracle on-premises installations at defense contractors create integration friction that extends procurement automation timelines by 18-24 months.
- Technical debt in serialization:Pharmaceutical wholesalers with 1990s-era warehouse management systems require full-stack replacement rather than modular upgrade to achieve DSCSA compliance.
Strategic Opportunities
- Southeast manufacturing corridor expansion:Battery and EV component facilities in Tennessee, South Carolina, and Georgia present greenfield deployment opportunities without legacy system migration burdens.
- USDA FSMA lot-tracking granularity:Protein distributors and cold-chain operators face modernization pressure that creates entry points for specialized traceability modules with temperature-logging integration.
- AI-driven demand sensing convergence:Machine learning inference at the edge is merging with traditional statistical forecasting, enabling real-time demand signal processing for automotive just-in-sequence suppliers.
Industry Challenges
- SCM-ERP integration complexity:Best-of-breed warehouse execution systems require custom API development to synchronize with SAP S/4HANA and Oracle Fusion Cloud, extending implementation cycles.
- Specialized talent scarcity:Supply chain data scientists with concurrent planning and constraint-based optimization expertise command premium compensation that mid-market vendors cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Supply Chain Management Software Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Inventory Management, Order Fulfillment, Demand Planning, Transportation Management Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS End User: Manufacturers, Wholesalers, Retailers, Third-Party Logistics Functionality: Reporting & Analytics, Supplier Collaboration, Risk Management, Procurement |
| Companies Covered | Oracle, Kinaxis, Blue Yonder, o9 Solutions, e2open, Manhattan Associates, FourKites, Descartes Systems Group, SAP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Supply Chain Management Software Market Evolving Landscape
Digital twin architectures are absorbing capital allocation from traditional forecasting investments as manufacturers seek real-time network simulation capabilities. This shift is compressing the competitive window for vendors without physics-based modeling engines.
Digital twin technology is absorbing development resources from conventional demand planning suites by enabling multi-echelon inventory simulation with granular node-level stress testing. Automotive OEMs in Detroit and Chattanooga are piloting these systems for supplier risk quantification. The technology is absorbing market share from static safety-stock calculators by compressing scenario iteration cycles from weeks to hours.
NHTSA autonomous vehicle data logging standards are mandating immutable audit trails for sensor fusion and decision telemetry, forcing supply chain software vendors to embed blockchain-verified traceability modules. Tier-1 AV component suppliers must demonstrate chain-of-custody documentation from semiconductor wafer through vehicle assembly. The regulation is absorbing compliance investment that would otherwise flow to pure-play logistics optimization.
Subscription-based transportation procurement is displacing annual freight contracts among third-party logistics providers seeking variable-cost exposure to rate volatility. Large retail consolidators in the Inland Empire and Dallas-Fort Worth are unbundling dedicated fleet commitments in favor of dynamic capacity marketplaces. This behavioral shift is absorbing margin from asset-heavy carriers while rewarding software platforms with real-time freight-matching algorithms.
US Supply Chain Management Software Market Segmentation
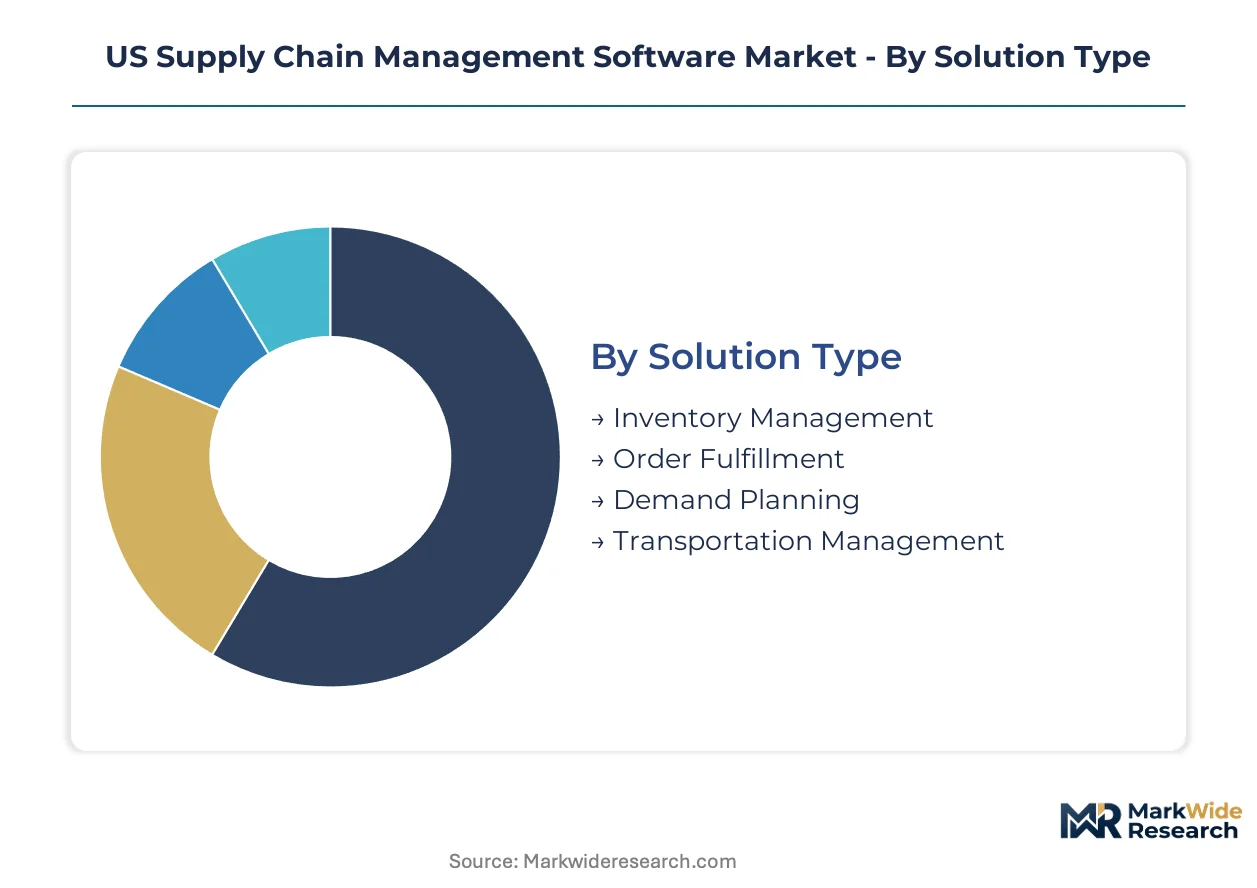
US supply chain software procurement decisions increasingly hinge on migration timelines from legacy ERP architectures rather than greenfield capability evaluation. Distributors and manufacturers weigh modular replacement against full-stack overhaul as FDA, NHTSA, and USDA compliance deadlines compress implementation windows.
Solution Type:
Replacement-cycle timing varies sharply across functional modules, with compliance-driven segments commanding premium implementation resources.
- Inventory Management:Real-time positioning systems with IoT sensor integration and automated reorder point calculation. Midwest automotive suppliers in Michigan and Ohio are consolidating demand here as they exit on-premises ERP maintenance cycles and adopt SaaS-native stock visibility.
- Transportation Management:Route optimization platforms with carrier procurement, freight audit, and dynamic capacity matching. Third-party logistics providers in the Inland Empire and Dallas-Fort Worth are absorbing this functionality fastest as they unbundle dedicated fleet commitments for variable-cost structures.
- Order Fulfillment:Wave planning and pick-path optimization for warehouse execution environments.
- Demand Planning:Statistical forecasting engines with scenario modeling for tariff volatility and nearshoring disruptions.
Volume placements concentrate in Inventory Management; the faster expansion belongs to Transportation Management.
Deployment Model:
Cost-tier stratification separates capital-intensive perpetual licenses from subscription-based operational expenditures.
- Cloud-Based:Multi-tenant architectures with API-native ERP integration and automatic security patching. Tier-1 and Tier-2 automotive manufacturers across Indiana, Ohio, and Michigan are migrating here to eliminate data center overhead and accelerate supplier portal deployment.
- SaaS:Pre-configured vertical templates with usage-based pricing and rapid implementation methodologies. Pharmaceutical distributors facing FDA DSCSA serialization mandates are prioritizing this model to compress compliance timelines without custom development.
- On-Premises:Single-tenant installations with full data sovereignty and customization depth.
- Hybrid:Sensitive workloads on-premises with burst capacity to public cloud infrastructure.
Revenue concentration sits with Cloud-Based deployments; SaaS is climbing the fastest as compliance deadlines force accelerated procurement.
End User:
Application-specific requirements diverge between asset-heavy operators and coordination-centric intermediaries.
- Third-Party Logistics:Multi-client visibility platforms with cross-dock optimization and freight-matching marketplaces. Providers serving retail consolidators are expanding fastest as dynamic capacity procurement displaces annual contract structures.
- Manufacturers:Shop-floor integration with MES systems and supplier collaboration portals for just-in-sequence delivery.
- Wholesalers:Lot-level traceability with temperature logging for cold-chain integrity and FDA audit readiness.
- Retailers:Omnichannel fulfillment with ship-from-store and buy-online-pickup-in-store orchestration.
Third-Party Logistics commands the largest implementation spend; Manufacturers are gaining share fastest amid reshoring facility construction.
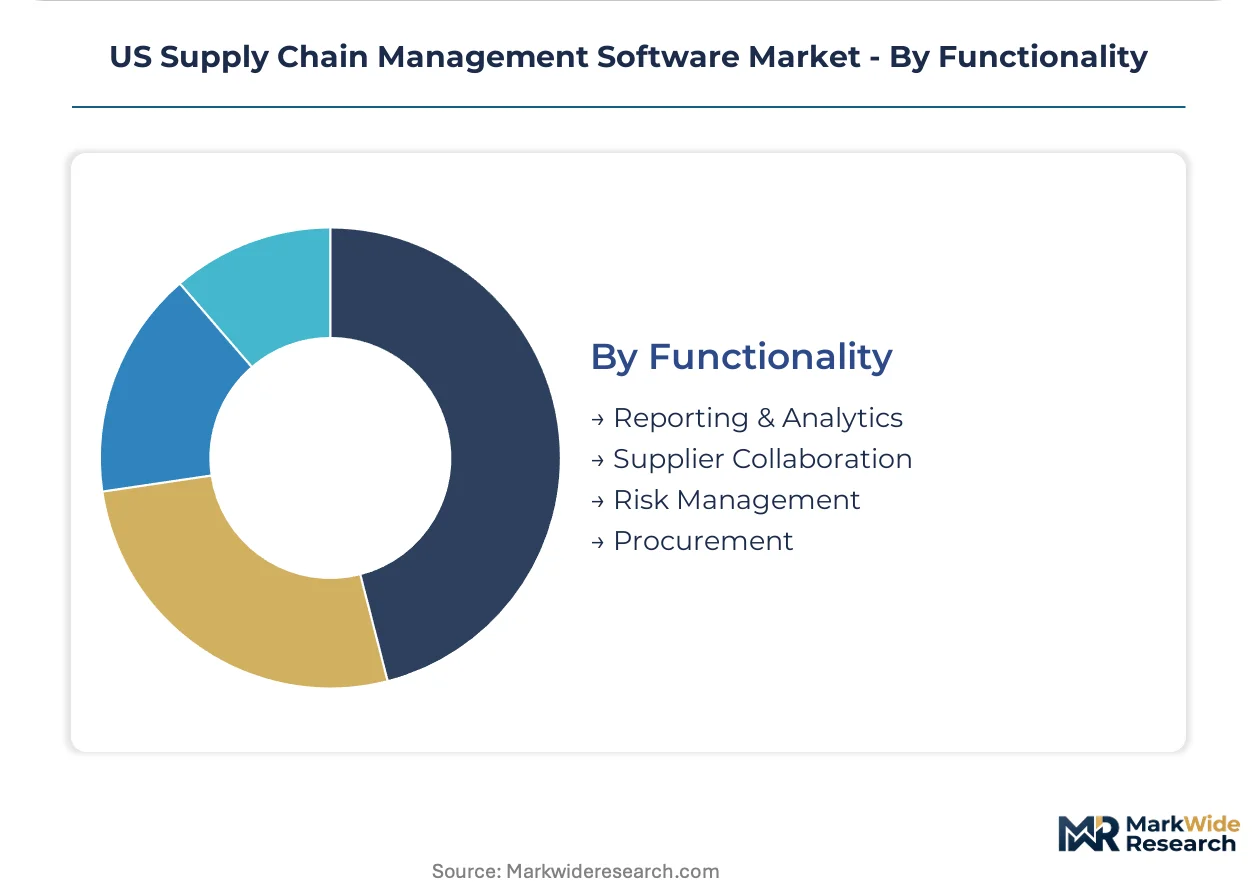
Functionality:
Margin structures favor predictive and collaborative modules over retrospective reporting tools.
- Risk Management:Multi-tier supplier monitoring with geopolitical alerting and financial health scoring. Aerospace and defense contractors are absorbing these capabilities to sustain contract volatility and NHTSA autonomous vehicle data logging compliance.
- Supplier Collaboration:Forecast sharing, capacity commitment, and VMI programs through EDI-native portals.
- Reporting & Analytics:Dashboard visualization with drill-down capabilities for operational KPIs.
- Procurement:Sourcing automation with contract lifecycle management and spend analytics.
Risk Management captures premium pricing; Supplier Collaboration is expanding most quickly as tariff uncertainty forces probabilistic scenario modeling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zone tax incentives across the Southeast are concentrating new facility investment and driving software procurement decisions for greenfield supply chain deployments.
Southeast (Tennessee/South Carolina/Georgia)
Battery and EV component manufacturing facilities are expanding rapidly. USDA FSMA lot-tracking requirements are pressuring protein distributors to modernize cold-chain visibility. Atlanta anchors freight-matching platform adoption among third-party logistics providers serving the Port of Savannah corridor.
Midwest (Michigan/Ohio/Indiana)
Tier-1 and Tier-2 automotive suppliers are exiting on-premises ERP maintenance cycles. NHTSA autonomous vehicle data logging standards are mandating immutable audit trails for component traceability. Detroit and Chattanooga are piloting digital twin architectures for supplier risk quantification.
Southwest (Texas/Arizona)
Nearshoring manufacturing from Mexico is accelerating cross-border transportation management demand. FERC interstate pipeline scheduling rules are compelling energy sector audit trail investments. Dallas-Fort Worth retail consolidators are unbundling dedicated fleet commitments for dynamic capacity marketplaces.
Northeast (New York/New Jersey/Pennsylvania)
Pharmaceutical distribution hubs face FDA DSCSA serialization enforcement deadlines. Port congestion at New York-New Jersey is driving real-time container tracking investments. Philadelphia cold-chain operators are absorbing temperature-logging integration for protein traceability compliance.
West Coast (California/Washington)
Omnichannel retail fulfillment complexity is forcing ship-from-store orchestration upgrades. EPA emissions reporting requirements are shaping transportation routing optimization priorities. Los Angeles and Long Beach port automation is concentrating demand for warehouse execution systems with EDI-native supplier portals.
US Supply Chain Management Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment models and vertical specializations. Oracle leverages vertically integrated cloud infrastructure to dominate pharmaceutical serialization workflows, while Manhattan Associates anchors warehouse execution systems through deep retail channel control. Kinaxis exemplifies the concurrent planning architecture segment sustaining aerospace and defense contract volatility. Strategic moves concentrate on API-native ERP integration partnerships and compliance-driven vertical template development.
Within the pharmaceutical serialization tier, Oracle and Kinaxis occupy positions shaped by FDA DSCSA mandate timing. SAP represents the legacy ERP entrenchment archetype creating integration friction that extends procurement automation timelines. Among cloud-native specialists, Blue Yonder and o9 Solutions exemplify demand planning investments capturing tariff volatility scenario modeling requirements.
| Leading Market Players |
|---|
| Oracle |
| Kinaxis |
| Blue Yonder |
| o9 Solutions |
| e2open |
| Manhattan Associates |
| FourKites |
| Descartes Systems Group |
| SAP |
| Others |
Value Network & Pricing Analysis
FDA DSCSA serialization mandates for pharmaceutical distributors are compressing procurement timelines and forcing vendors to absorb compliance costs into subscription tiers, restructuring how software providers price against implementation urgency.
Pricing Analysis
Short lead-time premiums dominate competitive positioning as pharmaceutical distributors face 2023 enforcement deadlines for unit-level traceability. The market runs on a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by FDA certification tier and customization depth for legacy ERP integration. Cost compression in mid-market SaaS tiers is intensifying because implementation minimums remain six-figure despite subscription packaging. Third-party logistics providers demonstrate highest price sensitivity due to margin pressure from dynamic capacity marketplaces, while defense contractors show lowest sensitivity given contract pass-through mechanisms.
Supply Chain Analysis
Freight cost volatility across Pacific container routes is reshaping vendor delivery economics for cloud infrastructure hardware. Supply concentrates in Taiwan for semiconductor components, Ireland for European data center operations, and Singapore for Asia-Pacific cloud nodes. Raw material dependencies span silicon wafers, rare earth magnets for server cooling, and lithium-ion backup power systems. Single-source vulnerability in advanced chip fabrication creates exposure to geopolitical disruption. Distribution runs through hyperscaler partner networks with regional fulfillment centers anchoring deployment velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Implementation capacity constraints among certified integration specialists are propping pricing power for vendors with established FDA compliance templates.
For Market Incumbents: Anticipate margin erosion from cloud-native entrants by deepening vertical integration into pharmaceutical serialization workflows and accelerating API-native ERP partnerships. Priority lever: channel control through pre-certified implementation networks that compress client onboarding cycles. For New Entrants and Emerging Players: Capture whitespace in Southeast battery manufacturing corridors where greenfield deployments lack legacy system migration burdens. Most penetrable segment: mid-market protein distributors facing USDA FSMA lot-tracking mandates with temperature-logging requirements. Go-to-market angle: pre-configured vertical templates with rapid implementation methodologies. For Investors and Strategic Acquirers: The window for entry favors concurrent planning architecture specialists with aerospace and defense contract volatility expertise. Long-term viability hinges on sustained R&D differentiation against hyperscaler bundling. Acquisition target archetype: specialized traceability module developers with FDA audit trail validation. Signal to watch: NHTSA autonomous vehicle data logging standard expansion beyond Tier-1 suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native ERP partnerships with SAP S/4HANA compress implementation cycles for defense contractors. |
| Acquisition of Specialist Firm | Blockchain-verified traceability modules address NHTSA immutable audit trail mandates for AV components. |
| Geographic Expansion | Southeast manufacturing corridors in Tennessee and Georgia offer greenfield deployment opportunities. |
| Strategic Partnership | Hyperscaler alliances secure cloud infrastructure capacity for pharmaceutical serialization workloads. |
| Product Launch | Digital twin architectures with physics-based modeling engines displace static safety-stock calculators. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and FDA DSCSA guidance documents formed the secondary backbone, supplemented by primary interviews with supply chain software CTOs, IT procurement officers at Tier-1 automotive suppliers, pharmaceutical distribution operations leads, and third-party logistics platform engineers. Bottom-up and top-down triangulation validated segment sizing across deployment models and vertical specializations.
Bottom-up unit economics anchored the analytical lens, with top-down macro validation across deployment model, organization size, vertical, and integration complexity dimensions. CAGRs derived from modeled adoption curves and replacement-cycle timing. Industry-specific inputs included FDA enforcement timeline phasing and NHTSA regulatory expansion trajectories.
The model holds under steady regulatory enforcement schedules; deviation in compliance deadline extensions or tariff regime shifts would shift replacement-cycle timing. Forecasts reflect documented assumptions about cloud migration velocity and legacy ERP entrenchment patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Account Based Marketing Market
Digital Solutions
Australia System Integration Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Enterprise Data Management Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Business Transcription Market
Digital Solutions
Enterprise Imaging Solutions Market
Digital Solutions
Europe Online Dating Services Market
Digital Solutions
Cloud Video Conferencing Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Global Transport Management Software Market