
 Global Capacity Management Market | 2026-2036
Global Capacity Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Capacity Management Market Analysis
Hyperscale data center construction across Northern Virginia is recalibrating enterprise expectations for real-time infrastructure visibility. Broadcom leverages its semiconductor-to-software portfolio to anchor high-density computing environments. IBM Corporation competes through hybrid cloud orchestration platforms that span mainframe and distributed architectures. VMware specializes in multi-cloud workload placement, sustaining relevance as enterprises diversify beyond single-vendor stacks.
Capacity management governs the measurement, allocation, and optimization of compute, storage, and network resources across physical and virtualized infrastructure, typically operating through agent-based collectors and predictive analytics engines that forecast utilization thresholds 30-90 days forward. Cloud-based deployment now captures the fastest expansion as organizations retire capital-intensive on-premises forecasting tools in favor of consumption-modeled alternatives. Within end-user verticals, telecommunications operators represent the most mature segment, having deployed capacity planning since the circuit-switched era, while manufacturing lags in adoption despite accelerating Industry 4.0 sensor density.
FCC guidelines on network reliability and the EU Digital Operational Resilience Act impose baseline stress-testing requirements that directly expand demand for automated capacity forecasting tools. India's TRAI mandates periodic quality-of-service reporting that compels telecom providers to maintain granular resource visibility. Enterprises must evaluate whether their current tooling can ingest containerized and serverless metrics before vendor consolidation eliminates point-solution alternatives.
Market Dynamics
Cloud-native observability stacks are displacing agent-based infrastructure monitoring as enterprises consolidate telemetry streams from Kubernetes clusters, serverless functions, and edge devices into unified control planes.
Growth Catalysts
- EU Digital Operational Resilience Act:Financial institutions across the European Union must implement automated capacity stress-testing by 2025, mandating predictive tooling for critical ICT infrastructure.
- Telecommunications quality mandates:India's TRAI requires granular quality-of-service reporting that compels operators to maintain real-time resource visibility across network slices.
- Hyperscale data center expansion:Northern Virginia's Ashburn-Loudoun corridor now hosts over 70% of US internet traffic, forcing enterprise tenants to demand sub-minute capacity reallocation capabilities.
Market Restraints
- Semiconductor supply concentration:Advanced AI accelerators from TSMC's foundries face 18-month allocation queues, constraining on-premises predictive analytics hardware deployments.
- Legacy integration debt:Mainframe capacity planning tools from the 1990s persist in banking infrastructure, creating API friction that blocks cloud-native telemetry ingestion.
- Skills fragmentation:Site reliability engineering expertise concentrates in San Francisco, Seattle, and Bangalore, leaving secondary markets dependent on managed service intermediaries.
Strategic Opportunities
- Indonesia's digital infrastructure push:The government's data localization requirements for financial services create greenfield demand for sovereign cloud capacity orchestration.
- Convergence of digital twins with capacity planning:Siemens and GE are embedding predictive resource models into manufacturing execution systems, opening industrial verticals previously served by generic IT tools.
- Outcome-based managed capacity services:Telecommunications operators in Germany now procure infrastructure elasticity as guaranteed SLA contracts rather than licensed software, reshaping vendor pricing architectures.
Industry Challenges
- Container metrics standardization gaps:Prometheus and OpenTelemetry instrumentation inconsistencies force engineering teams to maintain parallel collection pipelines, inflating operational overhead.
- Cross-border data residency friction:Divergent interpretations of GDPR Article 44 and China's PIPL block unified capacity visibility across multinational footprints, fragmenting control plane architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Capacity Management Market |
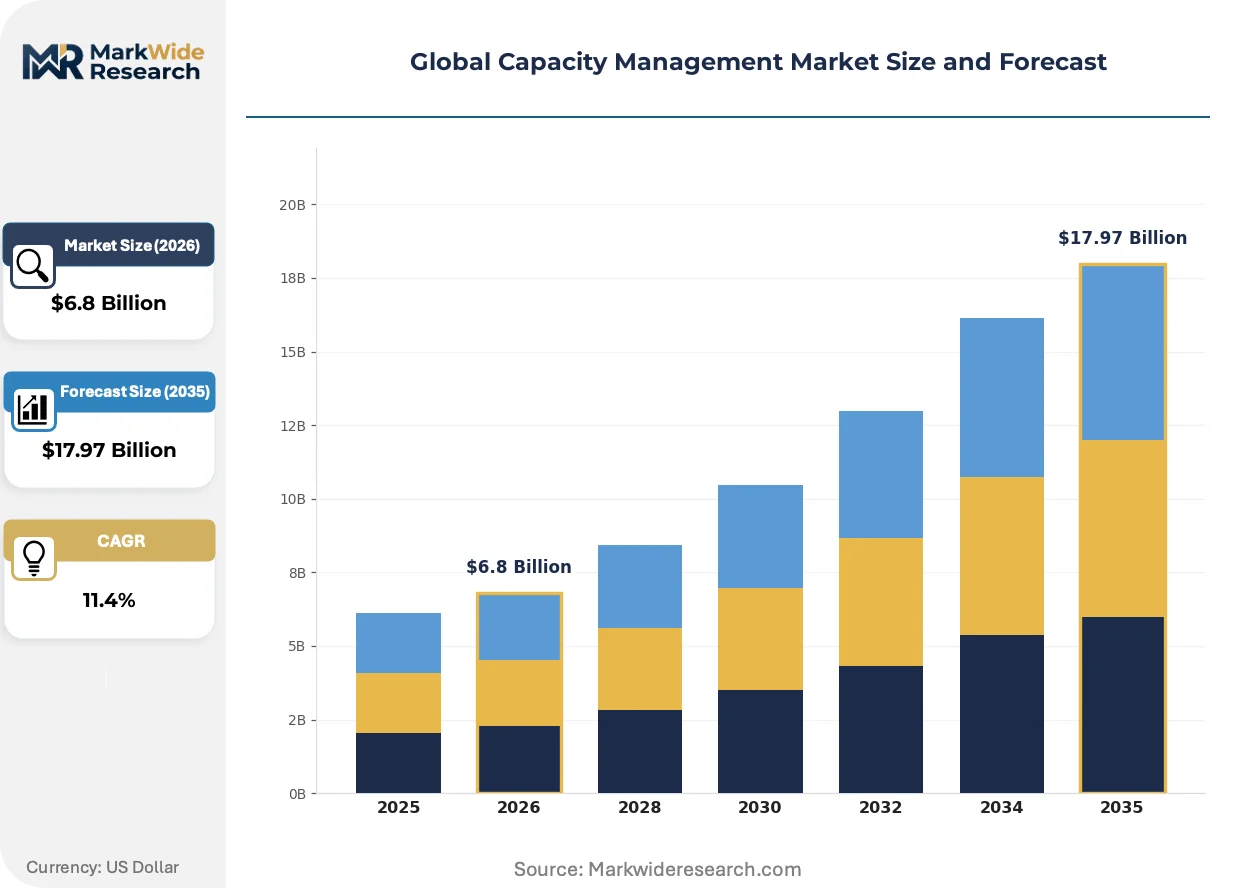
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Telecommunications, IT Services, Manufacturing, Utilities Solution: Software, Hardware, Consulting, Support Services Application: Load Balancing, Resource Allocation, Performance Monitoring, Capacity Planning |
| Companies Covered | Broadcom, ServiceNow, IBM Corporation, Cisco Systems, Oracle Corporation, BMC Software, VMware, NetApp, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Capacity Management Market Emerging Trajectories
Artificial intelligence inference workloads are rewriting capacity forecasting methodologies as burst patterns defy traditional 30-day linear projection models.
eBPF kernel instrumentation is converging with zero-trust security policies to enable continuous resource telemetry without agent deployment overhead. Cloud-native enterprises in fintech and ad-tech verticals are adopting this stack within 12-month refresh cycles. The technology is converging with confidential computing attestation requirements, compressing vendor consolidation timelines as point solutions lose procurement viability.
The EU AI Act's risk classification framework imposes documentation burdens on high-risk AI systems that indirectly mandate granular infrastructure provenance tracking. Model training pipelines must now demonstrate compute resource lineage for audit purposes. German automotive manufacturers and French banking consortiums are responding by embedding capacity metadata into MLOps workflows, creating procurement specifications that favor integrated platform vendors over specialized forecasting tools.
Telecommunications operators are unbundling network capacity planning from traditional OSS/BSS procurement, establishing direct relationships with cloud-native observability vendors. This disintermediation bypasses incumbent equipment manufacturers who previously controlled forecasting tool selection. The pattern is most visible in South Korea and Japan, where SK Telecom and NTT Docomo have issued RFPs specifying open API-first architectures that exclude legacy vendor stacks from evaluation.
Global Capacity Management Market Segmentation
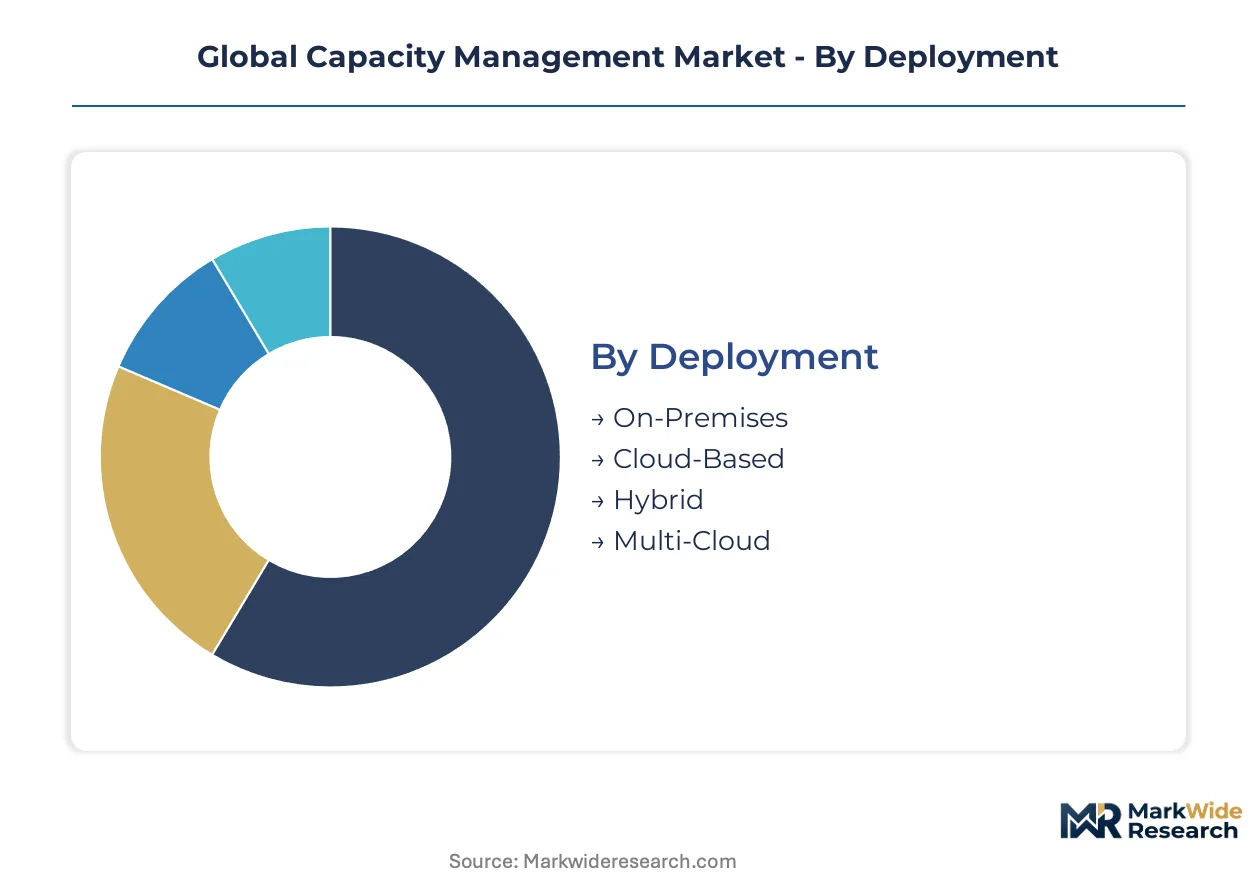
Capacity management procurement diverges sharply across deployment models and operational maturity levels. Financial institutions under EU Digital Operational Resilience Act mandates favor cloud-native architectures with automated stress-testing capabilities. Manufacturing verticals still anchor significant revenue in on-premises hardware despite accelerating cloud migration.
Deployment:
Cloud-based deployments trigger streamlined compliance pathways under India's TRAI quality mandates and EU AI Act documentation requirements, while on-premises installations demand extensive hardware certification cycles.
- Cloud-Based:Consumption-modeled delivery eliminates capital forecasting tool retirement cycles. German telecommunications operators now procure infrastructure elasticity as guaranteed SLA contracts rather than licensed software, compressing vendor consolidation timelines.
- On-Premises:Agent-based collectors and predictive analytics engines operate through dedicated hardware stacks. Mainframe capacity planning tools from the 1990s persist in banking infrastructure, creating API friction that blocks cloud-native telemetry ingestion.
- Hybrid:Orchestration platforms span mainframe and distributed architectures, bridging legacy debt with modern visibility requirements.
- Multi-Cloud:Workload placement tools sustain relevance as enterprises diversify beyond single-vendor stacks, though cross-border data residency friction fragments control plane architectures.
Cloud-based sits at the top of the volume ranking, with multi-cloud climbing the fastest.
End User:
Telecommunications operators command the highest per-customer spend due to circuit-switched era legacy investments and modern 5G slice orchestration demands.
- Telecommunications:The most mature segment, having deployed capacity planning since the circuit-switched era. India's TRAI mandates periodic quality-of-service reporting that compels providers to maintain granular resource visibility across network slices.
- IT Services:Hyperscale data center tenants in Northern Virginia's Ashburn-Loudoun corridor demand sub-minute capacity reallocation capabilities, forcing real-time infrastructure visibility investments.
- Manufacturing:Industrial automation and automotive manufacturing in Germany drive sophisticated capacity planning investments, though adoption lags despite accelerating Industry 4.0 sensor density.
- Utilities:Grid modernization and distributed energy resource integration create intermittent forecasting challenges distinct from steady-state enterprise workloads.
Telecommunications maintains the largest installed base, with manufacturing expanding most quickly.
Solution:
Software solutions capture margin concentration through recurring revenue models, while hardware procurement faces 18-month allocation queues for advanced AI accelerators.
- Software:Predictive analytics engines and unified control planes consolidate telemetry from Kubernetes clusters, serverless functions, and edge devices.
- Hardware:High-density computing environments require semiconductor-to-software portfolio integration, constrained by TSMC foundry allocation bottlenecks.
- Consulting:Site reliability engineering expertise concentrates in San Francisco, Seattle, and Bangalore, leaving secondary markets dependent on managed service intermediaries.
- Support Services:Outcome-based managed capacity services reshape vendor pricing architectures as telecommunications operators in Germany procure infrastructure elasticity as guaranteed SLA contracts.
Software dominates revenue contribution, with support services gaining share fastest.
Application:
Load balancing and capacity planning applications face divergent certification burdens under FCC network reliability guidelines and EU stress-testing mandates.
- Capacity Planning:Forecasts utilization thresholds 30-90 days forward through predictive analytics engines, now rewriting methodologies as AI inference burst patterns defy traditional linear projection models.
- Performance Monitoring:eBPF kernel instrumentation converges with zero-trust security policies to enable continuous resource telemetry without agent deployment overhead.
- Load Balancing:Sub-minute reallocation capabilities become table stakes for enterprise tenants in hyperscale corridors.
- Resource Allocation:Granular infrastructure provenance tracking emerges as an indirect mandate from EU AI Act risk classification documentation burdens on high-risk systems.
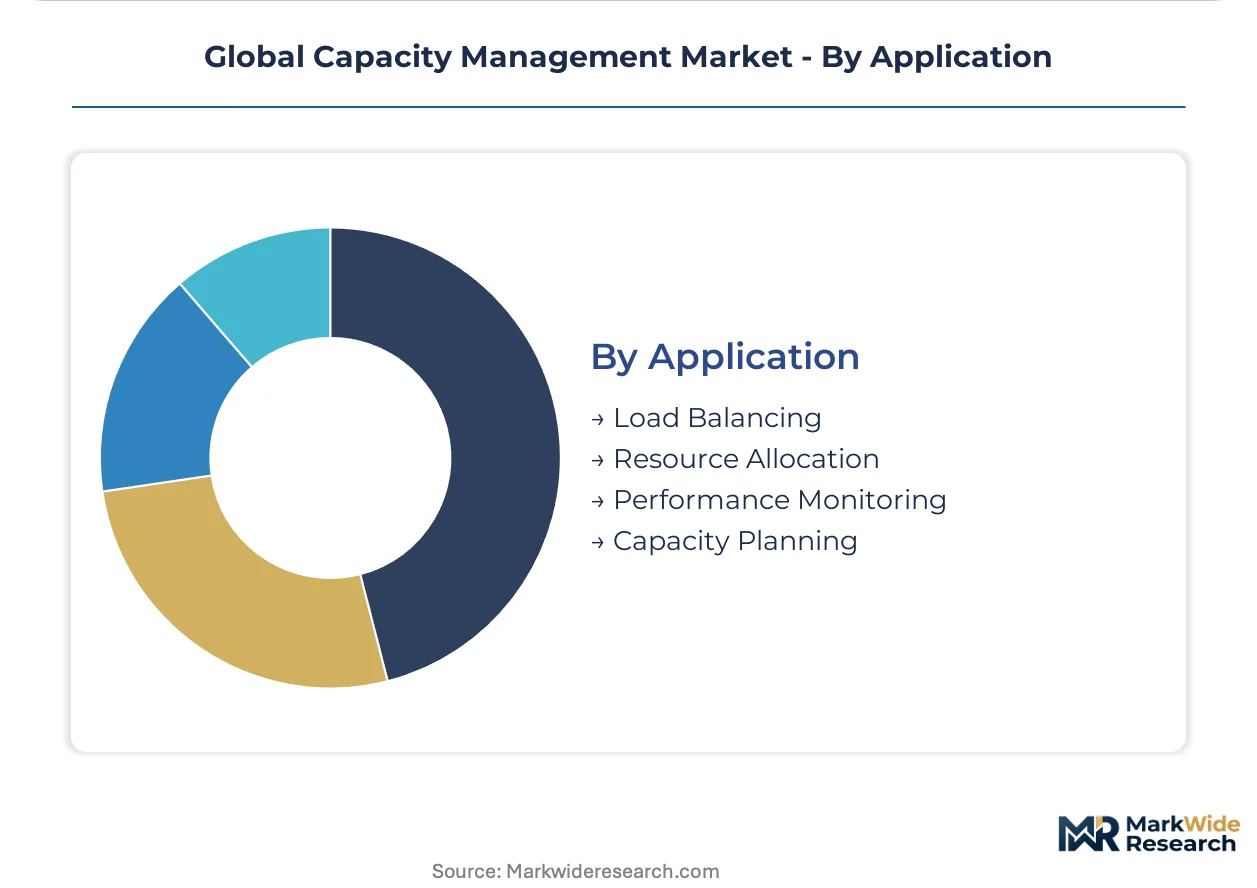
Capacity planning leads functional spending, with performance monitoring showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting capacity management procurement toward jurisdictions with clearer compliance pathways. The EU Digital Operational Resilience Act and India's TRAI mandates create cost-of-certainty advantages that accelerate vendor investment in certified delivery frameworks.
United States
Hyperscale data center construction in Northern Virginia's Ashburn-Loudoun corridor drives sub-minute capacity reallocation requirements. FCC network reliability guidelines impose baseline stress-testing obligations on telecommunications operators. Financial services firms in New York and Chicago are retiring 1990s-era mainframe planning tools in favor of cloud-native telemetry stacks.
Germany
Industrial automation and automotive manufacturing generate sophisticated capacity planning demand across Bavaria and Baden-Württemberg. The EU AI Act's risk classification framework mandates granular infrastructure provenance tracking for high-risk AI systems. Siemens and automotive consortiums in Stuttgart embed predictive resource models directly into manufacturing execution systems.
India
Telecommunications quality mandates from TRAI compel operators to maintain granular resource visibility across 5G network slices. Site reliability engineering expertise concentrates in Bangalore, leaving secondary markets dependent on managed service intermediaries. Mumbai-based financial institutions are accelerating cloud migration to streamline compliance with periodic quality-of-service reporting requirements.
South Korea
Telecommunications operators are disintermediating traditional OSS/BSS procurement channels to establish direct relationships with cloud-native observability vendors. SK Telecom has issued RFPs specifying open API-first architectures that exclude legacy vendor stacks. Seoul's fintech sector adopts eBPF kernel instrumentation within compressed 12-month refresh cycles.
Indonesia
Government data localization requirements for financial services create greenfield demand for sovereign cloud capacity orchestration. The central bank's digital infrastructure push attracts hyperscale provider investment in Jakarta and Surabaya. Domestic enterprises are bypassing on-premises hardware procurement in favor of consumption-modeled alternatives.
Global Capacity Management Market Vendor Landscape
United States producers anchor the premium software tier; European specialists hold compliance-adjacent positioning. The vendor base organizes around three strategic archetypes: semiconductor-to-software portfolio integrators, hybrid cloud orchestration platforms, and multi-cloud workload placement specialists. Consolidation pressures intensify as point-solution alternatives lose procurement viability against unified control planes. Dominant competitive moves include strategic partnerships with hyperscale infrastructure providers and vertical integration into predictive analytics engines.
Within the portfolio-integrator tier, Broadcom exemplifies the semiconductor-to-software convergence that high-density computing environments demand. IBM Corporation occupies a position bridging mainframe legacy systems with distributed cloud architectures. VMware represents the multi-cloud workload placement archetype as enterprises diversify beyond single-vendor technology stacks. These three anchors illustrate how vendor consolidation timelines compress when integrated platforms displace specialized forecasting tools.
| Leading Market Players |
|---|
| Broadcom |
| ServiceNow |
| IBM Corporation |
| Cisco Systems |
| Oracle Corporation |
| BMC Software |
| VMware |
| NetApp |
| Hewlett Packard Enterprise |
| Others |
Supply Flow & Price Mechanics
German telecommunications operators procuring infrastructure elasticity as guaranteed SLA contracts anchor pricing power for cloud-native capacity management vendors, compressing traditional licensing models into consumption-metered alternatives. This buyer concentration forces vendors to absorb hardware certification costs while competing on outcome-based guarantees rather than feature differentiation.
Pricing Analysis
Distributor margins for on-premises capacity planning tools have collapsed as direct SaaS relationships displace channel intermediaries. Pricing stratifies across premium compliance-certified tiers, standard cloud-native subscriptions, and economy managed-service bundles. Cost compression in the standard tier intensifies because hyperscale providers bundle basic forecasting into infrastructure contracts. Small and mid-sized manufacturers exhibit highest price sensitivity, while EU-regulated financial institutions accept premium pricing for automated stress-testing capabilities.
Supply Chain Analysis
Site reliability engineering talent shortages in Bangalore and secondary Indian markets constrain delivery capacity for implementation services. Hardware supply draws from Taiwan's TSMC foundries for AI accelerators, Germany's industrial automation component base, and US-based semiconductor design houses. Single-source vulnerability around advanced GPU allocation creates 18-month procurement queues for on-premises predictive analytics deployments. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams, bypassing traditional value-added resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
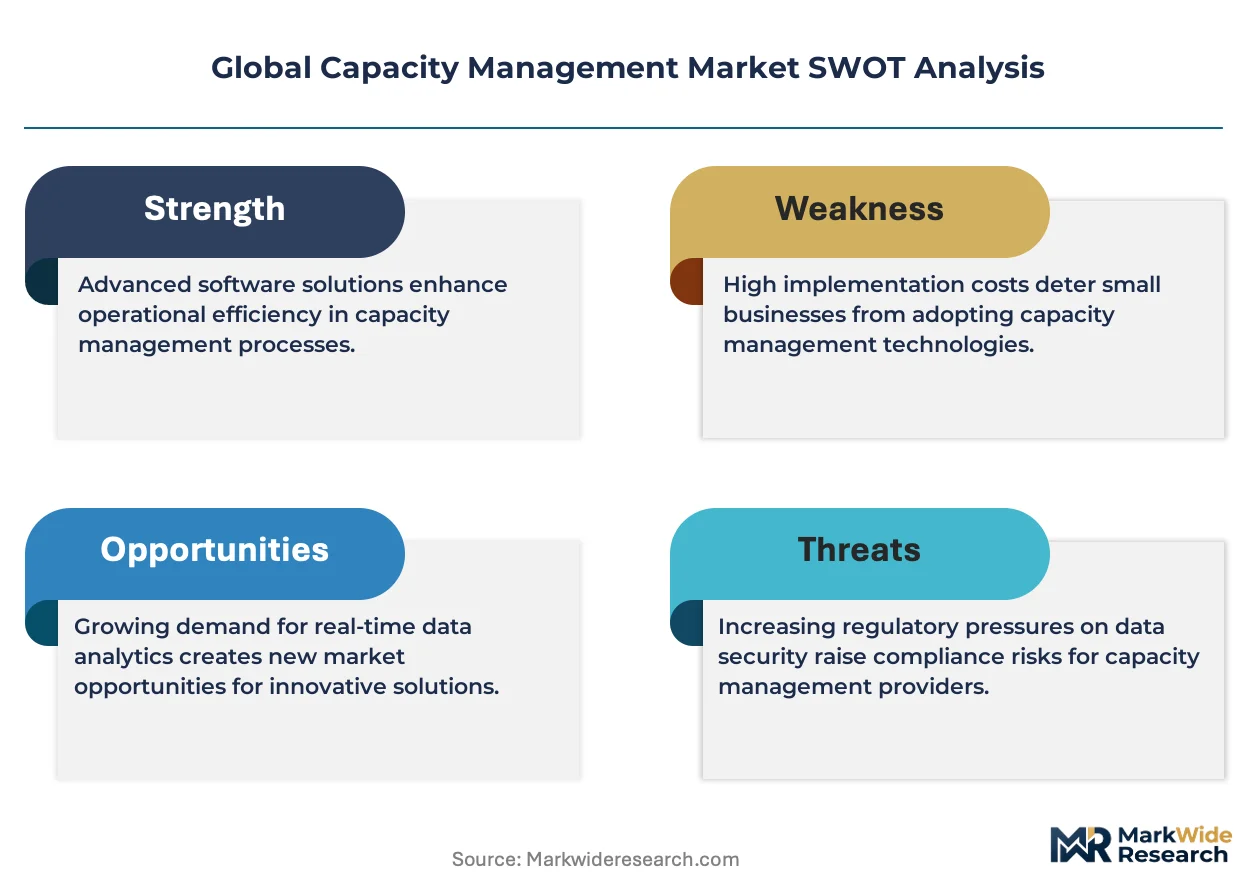
Margin expansion in capacity management hinges on cloud-native delivery models eliminating hardware certification overhead, while premium-tier demand from EU-regulated financial services sustains pricing power for compliance-integrated platforms.
For Market Incumbents: Deploy API-first architecture investments to defend against telecommunications operators disintermediating traditional OSS/BSS procurement channels. Incumbents must accelerate backward integration into eBPF kernel instrumentation to match cloud-native observability vendors, while consolidating point-solution competitors before unified control planes eliminate standalone forecasting tools. The threat of hyperscale providers bundling basic capacity management threatens mid-market revenue streams. For New Entrants and Emerging Players: Enter via Indonesia's sovereign cloud orchestration greenfield created by data localization mandates for financial services. New entrants should target manufacturing verticals in Germany where Industry 4.0 sensor density outpaces legacy IT tool adoption, and pursue outcome-based SLA positioning that incumbent vendors cannot match without restructuring pricing architectures. For Investors and Strategic Acquirers: Hyperscale infrastructure providers are the most active acquirer in this space, seeking vertical integration into predictive analytics engines. Long-term viability favors platform vendors with mainframe-to-cloud orchestration capabilities over specialized forecasting tools facing consolidation pressure. Monitor EU AI Act enforcement intensity as the inflection signal for compliance-integrated platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies telemetry from Kubernetes clusters and serverless functions into single control planes, displacing point solutions. |
| Strategic Partnership | Hyperscale data center operators in Northern Virginia demand sub-minute reallocation capabilities from vendor alliances. |
| Acquisition of Specialist Firm | Consolidates eBPF instrumentation expertise as cloud-native observability becomes procurement baseline. |
| Geographic Expansion | Indonesia's data localization requirements create sovereign cloud capacity orchestration demand without incumbent competition. |
| Product Launch | EU Digital Operational Resilience Act mandates automated stress-testing tools for financial institutions by 2025. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with cloud infrastructure architects, telecommunications network planners, financial services IT risk officers, and manufacturing automation engineers informed demand-side assumptions. Secondary sources include hyperscaler capex disclosures, FCC reliability filings, EU regulatory impact assessments, and TRAI quality-of-service reports. Bottom-up deployment modeling and top-down market sizing were triangulated against vendor revenue disclosures.
Granularity-level modeling operated at deployment-mode, end-user-vertical, and regional-regulatory-cluster dimensions across the analysis window. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EU AI Act implementation timelines, 5G network slice orchestration roadmaps, and industrial automation sensor deployment curves from German automotive manufacturers.
Inputs from regulatory filings and hyperscaler infrastructure disclosures were available through the study window; gaps in private company financial data introduce uncertainty bands around emerging vendor market share estimates. Forecasts reflect documented assumptions regarding compliance enforcement intensity and cloud migration velocity. Material deviation in EU Digital Operational Resilience Act penalty structures or TSMC foundry allocation policies warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Smart Government Market
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
Global Digital Business Card Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market
Digital Solutions
Marketing Automation Market
Digital Solutions
Product As a Service Market
Digital Solutions
Cannabis POS System Market
Digital Solutions
Demand Signal Repository Solutions Market
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Manufacturing Operations Management Solutions Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Telecom Site Management Software Market
Digital Solutions
Asia-Pacific Desktop Virtualization Market
Digital Solutions
Business As a Service Market
Digital Solutions
Online Dating Market