
 AI Marketing Tool Market | 2026-2036
AI Marketing Tool Market Size, Share, and Industry Trends Forecast 2026-2036
AI Marketing Tool Market Insights
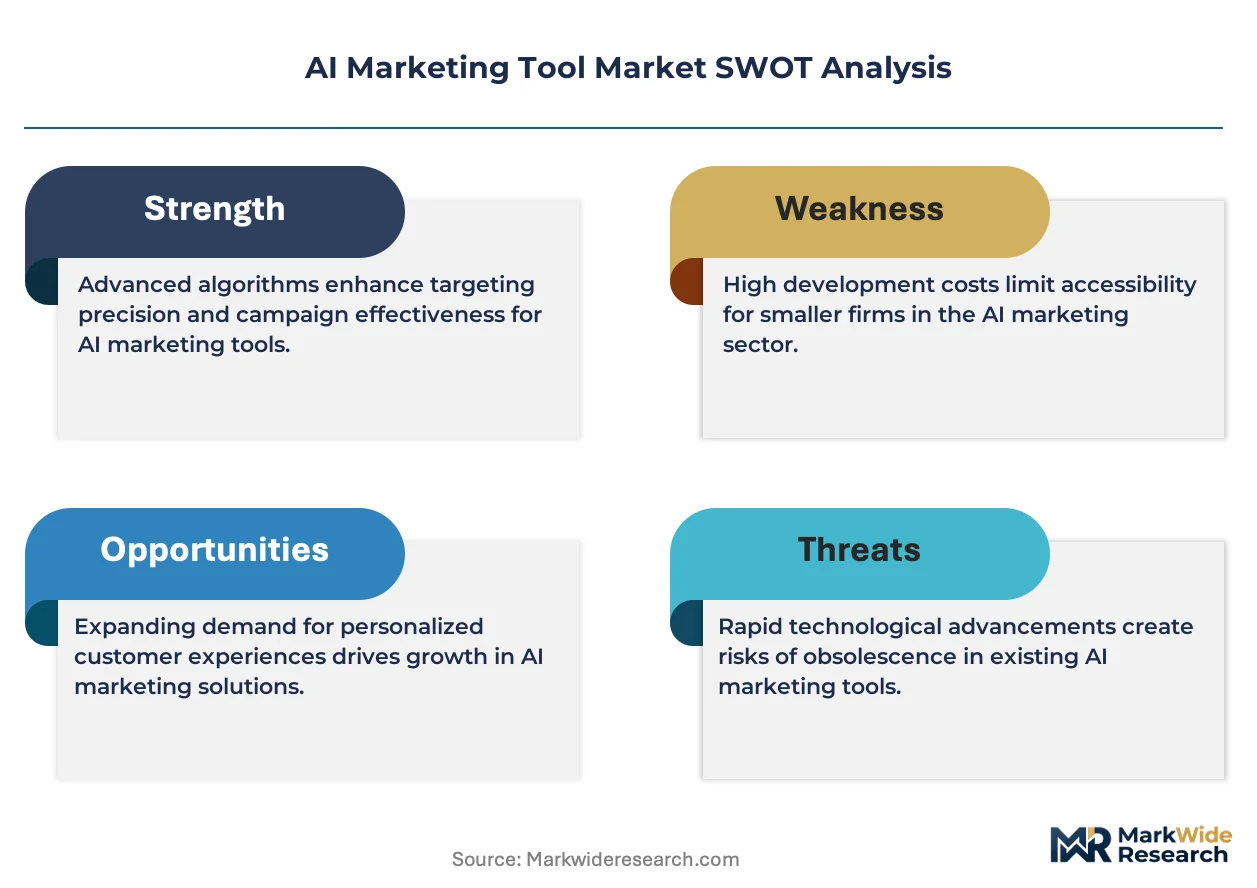
The AI marketing tool category is rebalancing between premium enterprise suites and commodity point solutions as buyers separate workflow orchestration from standalone generation utilities. Adobe leverages deep creative cloud integration to anchor high-margin subscriptions for content generation workflows. Salesforce sustains competitive positioning through its customer data platform architecture that unifies identity graphs across B2B and B2C environments. HubSpot navigates the mid-market by specializing in campaign management tools with native CRM connectivity.
AI marketing tools encompass software systems that apply machine learning models, natural language processing, and predictive algorithms to automate or augment audience targeting, content creation, performance measurement, and budget allocation across digital channels; these systems typically process structured and unstructured data at latency thresholds under 100 milliseconds for real-time bidding and personalization decisions. Cloud-based deployment dominates solution delivery, with SaaS architectures capturing the majority of new customer acquisitions due to lower upfront infrastructure commitments and faster implementation cycles. Predictive analytics and content generation represent the fastest-expanding solution types, as financial institutions and telecom providers prioritize lead-scoring accuracy and dynamic creative assembly over legacy rule-based campaign management.
The EU AI Act, GDPR, and the US FTC's guidance on algorithmic fairness collectively reshape product development priorities, forcing vendors to embed explainability dashboards and consent-management APIs directly into platform architectures. The US FDA does not regulate marketing software, but the SEC's disclosure requirements for publicly traded companies influence how financial institutions evaluate vendor risk profiles. Stakeholders must monitor evolving cross-border data localization mandates and decide whether to architect region-specific instances or pursue unified global stacks with modular compliance layers.
Market Dynamics
Real-time bidding latency requirements below 100 milliseconds are compressing vendor margins while forcing cloud infrastructure consolidation among enterprise marketing departments.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision-making systems must embed explainability dashboards, creating pull for compliant platform architectures across European retail chains.
- Predictive analytics adoption:Inventory-linked campaign orchestration by North American retail chains is expanding demand for demand-forecasting modules.
- Cloud infrastructure spending:United States enterprise marketing departments continue outspending other national markets on SaaS deployment models.
Market Restraints
- Cross-border data localization:Modular compliance layer requirements fragment architecture decisions for vendors pursuing unified global stacks.
- Algorithmic fairness enforcement:US FTC guidance forces additional development cycles for consent-management API integration.
- Latency threshold compression:Sub-100 millisecond processing requirements strain edge computing infrastructure budgets for real-time personalization.
Strategic Opportunities
- GDPR consent automation:Regulatory tailwinds in Europe favor vendors embedding granular preference management into customer data platforms.
- Dynamic creative assembly:Telecom providers and financial institutions are prioritizing automated content generation over legacy rule-based systems.
- Identity graph unification:Convergence of B2B and B2C data architectures creates white space for cross-environment campaign orchestration tools.
Industry Challenges
- MLOps talent scarcity:Pipeline engineering for sub-100 millisecond inference requires specialized skill sets concentrated among cloud-native vendors.
- Legacy CRM integration:Mid-market buyers demand native connectivity with existing customer databases, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Marketing Tool Market |
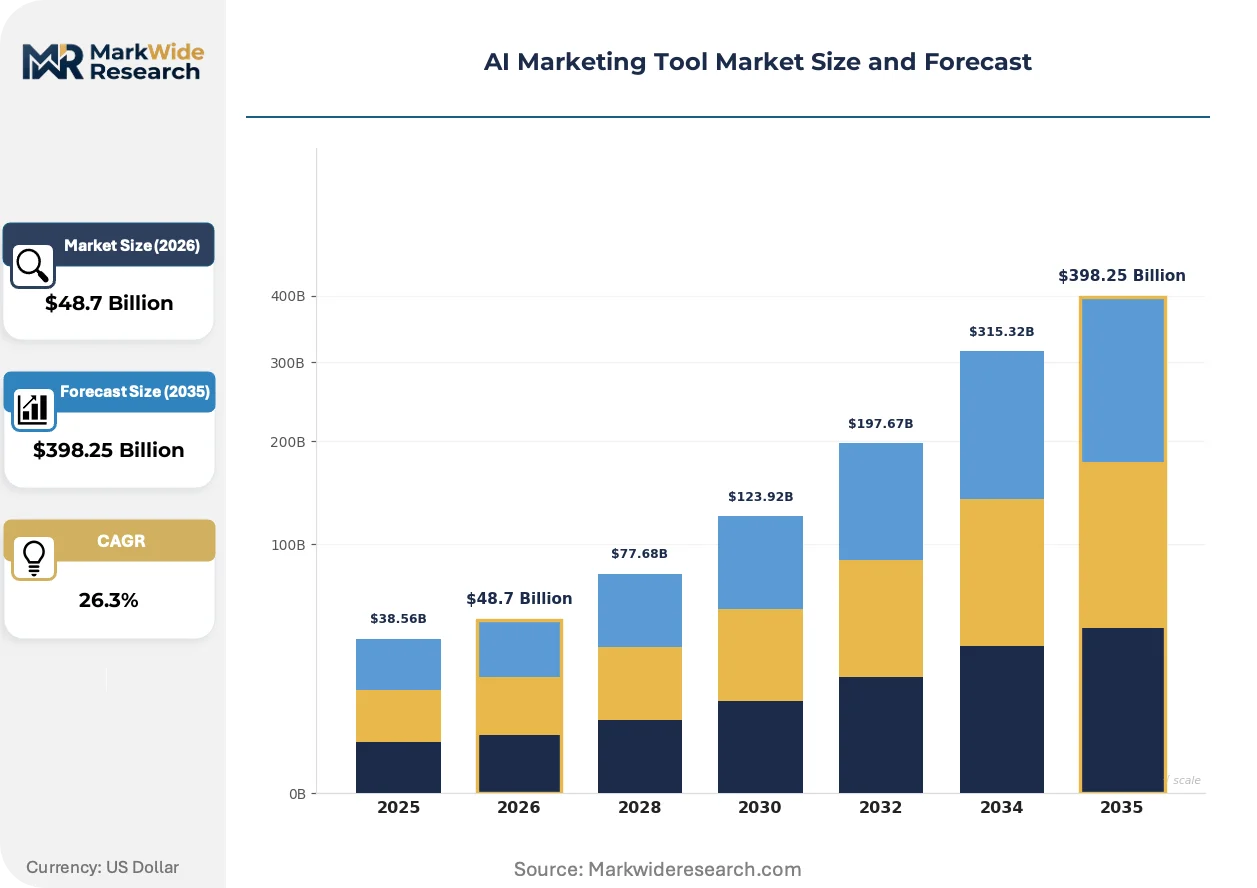
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $398.25 Billion |
| CAGR (2026 – 2036) | 26.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Edge Computing Solution Type: Customer Data Platform, Predictive Analytics, Content Generation, Chatbots, Programmatic Advertising Use Case: Lead Scoring, Campaign Management, Social Media Optimization, Customer Segmentation, Personalized Messaging End User Industry: Retail Chains, Digital Agencies, Telecom Providers, Financial Institutions, Hospitality Networks |
| Companies Covered | Adobe, Salesforce, Google, Microsoft, Amazon Web Services, Oracle, HubSpot, ActiveCampaign, Meta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Marketing Tool Market Trends and Innovations
Federated learning architectures are redistributing computational workloads while regulatory pressure on algorithmic transparency accelerates vendor investment in interpretable model structures.
Edge-deployed inference engines are decentralizing real-time personalization decisions away from centralized cloud regions. Retail chains with distributed storefront footprints are adopting these architectures fastest to reduce round-trip latency for in-aisle targeting. This shift is decentralizing competitive advantage toward vendors with lightweight model compression capabilities.
The EU AI Act's risk-tier classification system imposes documentation burdens on high-stakes automated decision systems used in consumer credit and insurance marketing. Vendors must now maintain technical files and human oversight protocols for systems affecting legal or similarly significant effects. Financial services marketing teams across Germany, France, and Italy are restructuring procurement criteria to prioritize vendors with established conformity assessment procedures.
Buyer concentration among Fortune 500 marketing departments is compressing vendor sales cycles while elevating procurement sophistication. Enterprise RFPs now mandate API-first architectures and granular data residency controls, displacing bundled suite offerings. This pattern is most visible in United States technology and telecommunications verticals where procurement teams have consolidated martech evaluation authority.
AI Marketing Tool Market Segmentation
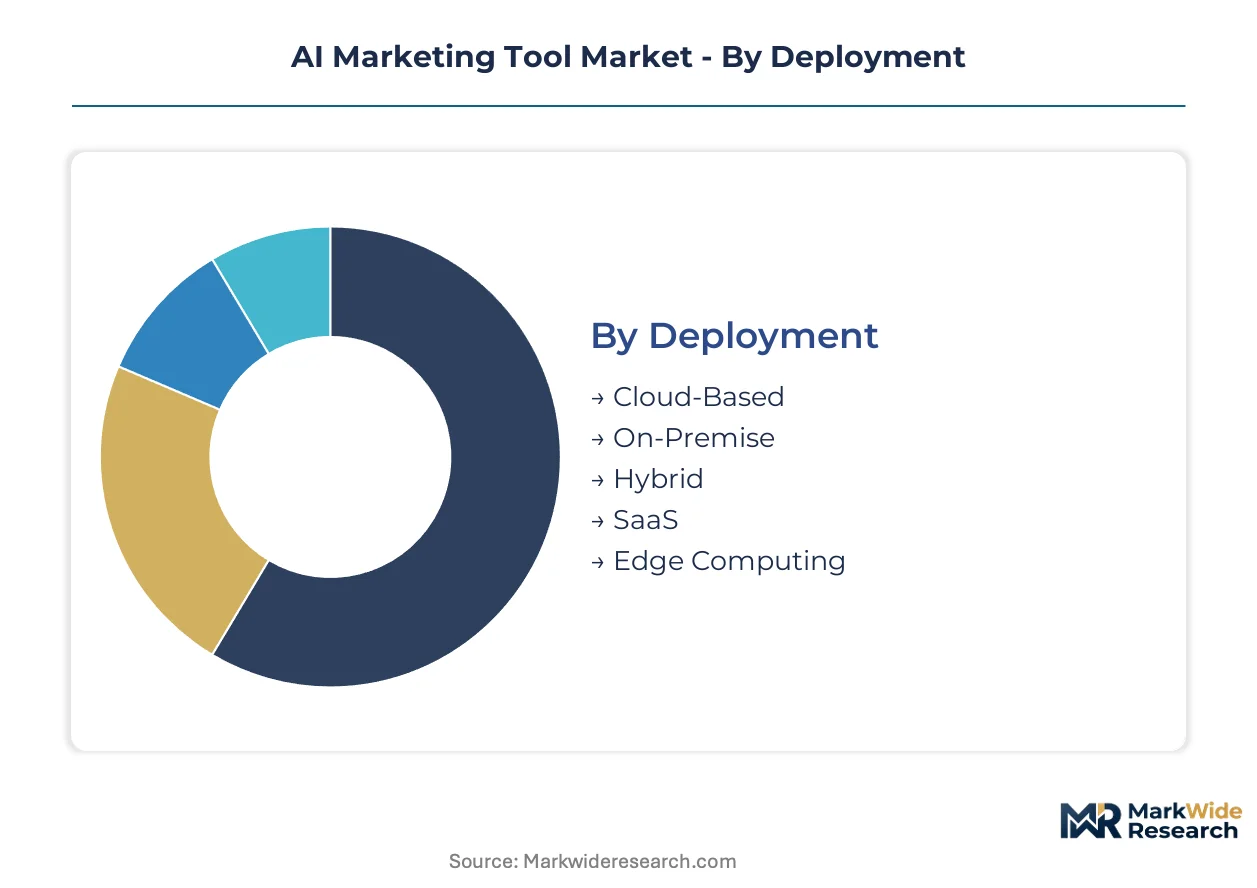
AI marketing tool segmentation reveals divergent infrastructure requirements across deployment modes, with latency-sensitive applications demanding specialized architectures. Buyers prioritize solution types based on data sovereignty constraints and creative automation maturity.
Deployment:
Capital intensity varies sharply across deployment modes, with edge computing requiring distributed hardware investment while SaaS minimizes upfront infrastructure commitment.
- Cloud-Based:Centralized processing architectures leverage hyperscaler infrastructure for elastic compute scaling. Retail chains in the United States concentrate demand here, driven by preference for operational expenditure models over capital deployment.
- Edge Computing:Lightweight inference engines deploy directly at retail storefronts or branch locations to achieve sub-100 millisecond personalization latency. This segment demands the highest capital intensity due to hardware proliferation across distributed footprints.
- On-Premise:Self-managed data centers serve financial institutions with stringent data residency mandates.
- Hybrid:Split workloads balance sensitive data processing on-premise with burst compute in cloud regions.
- SaaS:Fully managed software delivery captures mid-market digital agencies seeking rapid implementation without infrastructure ownership.
Cloud-Based deployments absorb the bulk of installed capacity; Edge Computing is expanding most quickly.
Solution Type:
Margin profiles diverge based on integration depth, with unified customer data platforms commanding premium pricing against standalone point solutions.
- Predictive Analytics:Machine learning pipelines process historical transaction data to forecast demand patterns and optimize inventory-linked campaign timing. Telecom providers in Germany and France prioritize these modules for churn prediction and upsell targeting.
- Customer Data Platform:Unified identity graphs consolidate fragmented customer records across B2B and B2C touchpoints. Financial institutions concentrate demand here, compelled by SEC disclosure requirements to maintain auditable data lineage.
- Content Generation:Natural language and image synthesis tools automate creative assembly for dynamic advertising.
- Chatbots:Conversational interfaces handle qualification and support queries across messaging channels.
- Programmatic Advertising:Real-time bidding systems execute media purchases across digital inventory exchanges.
Customer Data Platform deployments dominate enterprise spending; Predictive Analytics is gaining share fastest among regulated verticals.
Use Case:
Application maturity separates workflow-embedded tools from experimental pilots, with lead scoring achieving production scale while personalized messaging remains architecturally complex.
- Lead Scoring:Algorithmic ranking of prospect conversion probability integrates with CRM systems to prioritize sales outreach. Financial institutions in the United States drive demand, requiring explainable models to satisfy FTC algorithmic fairness guidance.
- Campaign Management:End-to-end orchestration of multi-channel marketing programs with budget allocation and performance tracking. Digital agencies concentrate adoption here, seeking unified workflow consolidation.
- Social Media Optimization:Automated scheduling, sentiment analysis, and influencer identification for platform-native engagement.
- Customer Segmentation:Clustering algorithms partition audiences by behavioral and demographic attributes.
- Personalized Messaging:Real-time content adaptation based on individual user context and historical interaction patterns.
Campaign Management anchors current deployment volume; Lead Scoring shows the steepest expansion trajectory among compliance-conscious buyers.
End User Industry:
Customer concentration patterns reflect vertical data maturity, with retail chains and financial institutions leading adoption while hospitality networks lag in infrastructure readiness.
- Retail Chains:Inventory-linked campaign systems synchronize promotional timing with stock levels and demand forecasts. United States and United Kingdom retailers dominate procurement, pressured by margin compression to automate previously manual coordination.
- Financial Institutions:Risk-aware marketing architectures balance customer acquisition with regulatory compliance. German and Italian banks prioritize vendors with EU AI Act conformity assessment procedures for credit and insurance targeting.
- Digital Agencies:Service providers deploy tools across client portfolios with multi-tenant isolation requirements.
- Telecom Providers:Subscription-based businesses leverage predictive models for retention and upgrade campaigns.
- Hospitality Networks:Property and experience marketers adopt personalization for booking conversion and loyalty program optimization.
Retail Chains command the largest installed base; Financial Institutions are climbing the fastest as regulatory clarity emerges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors AI marketing tool development, hosting hyperscaler headquarters and venture capital corridors that channel cloud infrastructure investment into enterprise marketing departments.
United States
Enterprise marketing departments in New York and Chicago drive cloud-based deployment demand for real-time bidding systems. The FTC's algorithmic fairness guidance forces vendors to embed explainability dashboards into customer data platforms. Seattle-based cloud providers concentrate infrastructure investment to serve latency-sensitive personalization workloads.
Germany
Financial institutions in Frankfurt prioritize EU AI Act conformity assessment procedures for credit-targeting algorithms. The country's national data protection authority enforces granular consent management requirements across marketing automation stacks. Munich's automotive marketing clusters adopt predictive analytics for inventory-linked campaign orchestration.
United Kingdom
London's digital agency ecosystem concentrates demand for SaaS campaign management tools with native CRM connectivity. The Information Commissioner's Office mandates documentation burdens for high-stakes automated decision systems. Retail chains in Manchester deploy edge computing architectures for in-aisle personalization at sub-100 millisecond thresholds.
France
Telecom providers in Paris leverage predictive models for churn prediction and upsell targeting across subscription bases. The country's national data regulator imposes transparency obligations on consumer-facing algorithmic systems. Lyon's banking sector restructures procurement criteria to prioritize vendors with established technical file maintenance protocols.
Japan
Enterprise marketing teams in Tokyo prioritize identity graph unification across B2B and B2C data architectures. The Ministry of Economy, Trade and Industry promotes interpretable model structures through industry guidance on AI system documentation. Osaka's retail networks adopt federated learning architectures to redistribute computational workloads across distributed storefront footprints.
AI Marketing Tool Market Competitive Landscape
Capital-heavy hyperscalers compete with asset-light SaaS specialists for enterprise marketing budgets, creating a tiered structure where infrastructure ownership separates pricing power. The vendor base concentrates around three strategic archetypes: creative cloud integrators anchoring content generation workflows, customer data platform architects unifying identity graphs, and campaign management specialists serving mid-market digital agencies. Dominant competitive moves include API-first architecture development to satisfy Fortune 500 procurement mandates and edge computing infrastructure expansion to achieve sub-100 millisecond personalization latency.
Within the creative cloud integrator tier, Adobe represents deep workflow embedding for high-margin content generation subscriptions. Salesforce occupies a position anchoring customer data platform architectures that unify B2B and B2C identity graphs across enterprise environments. HubSpot exemplifies the mid-market campaign management specialist archetype with native CRM connectivity.
| Leading Market Players |
|---|
| Adobe |
| Salesforce |
| Microsoft |
| Amazon Web Services |
| Oracle |
| HubSpot |
| ActiveCampaign |
| Meta |
| Others |
Pricing and Supply Chain Analysis
Edge-deployed inference engine proliferation simultaneously compresses cloud infrastructure cost economics and redistributes supply concentration toward vendors with lightweight model compression capabilities. The shift from centralized hyperscaler regions to distributed storefront footprints forces buyers to trade capital intensity against latency performance.
Pricing Analysis
Outcome-based pricing anchored to campaign conversion lift dominates enterprise procurement, with subscription tiers scaling by inference volume and explainability dashboard depth. Price differentiation hinges on EU AI Act conformity certification and sub-100 millisecond latency guarantees. Pricing pressure intensifies in the mid-market SaaS tier as commodity point solutions proliferate. Fortune 500 marketing departments show lowest price sensitivity; digital agencies exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based GPU foundries and United States hyperscaler cloud regions for training infrastructure. The supply chain draws from South Korean memory components, Chinese edge hardware assemblies, and German industrial sensor suppliers. Tariff exposure on semiconductor imports presents structural risk. Distribution runs through direct enterprise sales with embedded professional services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI marketing tool market functions as a cost-of-compliance story where the EU AI Act's risk-tier classification system erects barrier-to-entry moats favoring vendors with established conformity assessment procedures.
For Market Incumbents: Deepen vertical integration into edge computing hardware to defend latency positioning against cloud-native challengers. Expand conformity assessment documentation for EU AI Act high-stakes systems to preempt regulatory displacement. Prioritize MLOps talent retention as pipeline engineering scarcity intensifies. For New Entrants and Emerging Players: GDPR consent automation in Germany and France opens a window for mid-market customer data platforms with native preference management APIs. Target digital agencies in the United Kingdom seeking rapid SaaS implementation without infrastructure ownership. Lead with API-first architectures to satisfy Fortune 500 procurement mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of edge inference specialists and private equity rollup of mid-market campaign management tools. Long-term viability favors vendors with unified identity graph architectures spanning B2B and B2C environments. Watch for FTC algorithmic fairness enforcement intensity as inflection indicator for explainability platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Adobe's creative cloud embedding anchors high-margin content generation subscriptions. |
| Acquisition of Specialist Firm | Salesforce's customer data platform architecture unifies identity graphs across B2B and B2C environments. |
| Geographic Expansion | HubSpot navigates mid-market campaign management with native CRM connectivity in United States and United Kingdom. |
| Product Launch | Edge-deployed inference engines decentralize real-time personalization for retail chains with distributed footprints. |
| Strategic Partnership | Federated learning architectures redistribute computational workloads for Japanese retail networks. |
Research Methodology
Multi-period observation of cloud infrastructure spending patterns, regulatory enforcement timelines, and latency threshold compression anchored the trend analysis, supplemented by interviews with CTOs at enterprise marketing departments, platform engineers at hyperscaler vendors, integration specialists at digital agencies, and procurement officers at financial institutions. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU AI Act implementation guidance, and FTC algorithmic fairness documentation. Bottom-up deployment mode sizing and top-down solution type aggregation enabled triangulation.
The input-output matrix framed demand forecasts across deployment mode, solution type, use case, and end user industry dimensions, with regional adoption patterns as a cross-cutting variable. CAGRs derived from elasticity modeling of cloud spending growth against regulatory compliance cost curves. Forecast inputs included MLOps talent availability indices and edge hardware cost decline trajectories.
The model assumes a particular technology adoption path; alternative pathways for federated learning architectures would alter the outlook. Forecasts embed assumptions regarding EU AI Act enforcement consistency and cross-border data localization trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Platform Architecture Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Global Autonomous Data Platform Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Product Information Management Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
Global Media (Video) Processing Solutions Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
G2P Systems Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Decision Support System Market
Digital Solutions
Webrtc Market