
 Digital Video Advertising Market | 2026-2036
Digital Video Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Video Advertising Market Intelligence
Programmatic guaranteed inventory is unwinding legacy reservation-based media buying across premium video publishers. The Trade Desk leverages its unified ID framework to sustain cross-platform measurement capabilities. Google LLC anchors demand through YouTube's integration with Google Ads, while ByteDance Ltd. competes via TikTok's full-screen vertical format and algorithmic content graph.
Digital video advertising encompasses the planning, creation, targeting, delivery, and measurement of promotional content through internet-connected video channels, typically operating via real-time bidding protocols and impression-level attribution. Its primary commercial purpose is to capture viewer attention during entertainment consumption and convert engagement into measurable brand outcomes or direct response actions. OTT platforms and social media environments lead structural allocation, with programmatic buying technology capturing the fastest expansion as automation displaces manual insertion orders. Interactive ad formats concentrate emerging margin pools where engagement metrics justify premium CPMs.
The Federal Trade Commission scrutinizes data practices in behavioral targeting, while the Federal Communications Commission oversees broadband infrastructure enabling streaming delivery. The California Consumer Privacy Act and emerging state-level frameworks compel advertisers to rebuild audience graphs on consented first-party data. Stakeholders must monitor regulatory fragmentation across state jurisdictions and decide whether to centralize compliance operations or federate adaptation by platform.
Market Dynamics
Programmatic guaranteed inventory is unwinding legacy reservation-based media buying across premium video publishers, while retail media networks accelerate advertiser migration from traditional television budgets. This structural reconfiguration concentrates decision-making power with platforms possessing unified identity frameworks and first-party data assets.
Growth Catalysts
- Connected TV Penetration:United States households are abandoning linear broadcast in favor of streaming platforms, creating addressable inventory pools that command measurable attribution.
- California Consumer Privacy Act:Advertisers are rebuilding audience graphs on consented first-party data, favoring platforms with authenticated user relationships over cookie-dependent intermediaries.
- AI-Driven Targeting Engines:Machine learning models optimize impression-level bidding decisions in real time, compressing the gap between ad exposure and conversion events.
Market Restraints
- Regulatory Fragmentation:Emerging state-level privacy frameworks beyond California compel advertisers to maintain parallel compliance operations, elevating overhead costs.
- Brand Safety Technology:Advertisers demand pre-bid verification of content adjacency, requiring investments in contextual analysis tools that inflate effective CPMs.
- Measurement Standardization:Cross-platform attribution lacks unified currency, forcing buyers to reconcile disparate metrics from walled-garden platforms.
Strategic Opportunities
- Retail Media Networks:Closed-loop measurement linking ad exposure to purchase data is attracting CPG budgets previously allocated to linear television.
- Interactive Ad Formats:Shoppable video units and gamified creative templates justify premium pricing through engagement metrics that outperform standard pre-roll.
- Programmatic Guaranteed:Automation of direct-sold inventory preserves publisher yield while delivering advertiser guarantees on reach and frequency.
Industry Challenges
- Identity Resolution:Deprecation of third-party cookies is forcing technical teams to implement probabilistic matching and clean-room architectures.
- Cross-Platform Measurement:Reconciling viewability standards across mobile, desktop, and CTV environments requires specialized engineering resources.
- Creative Adaptation:Vertical video production for short-form platforms demands new talent pools and production workflows alien to traditional agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Video Advertising Market |
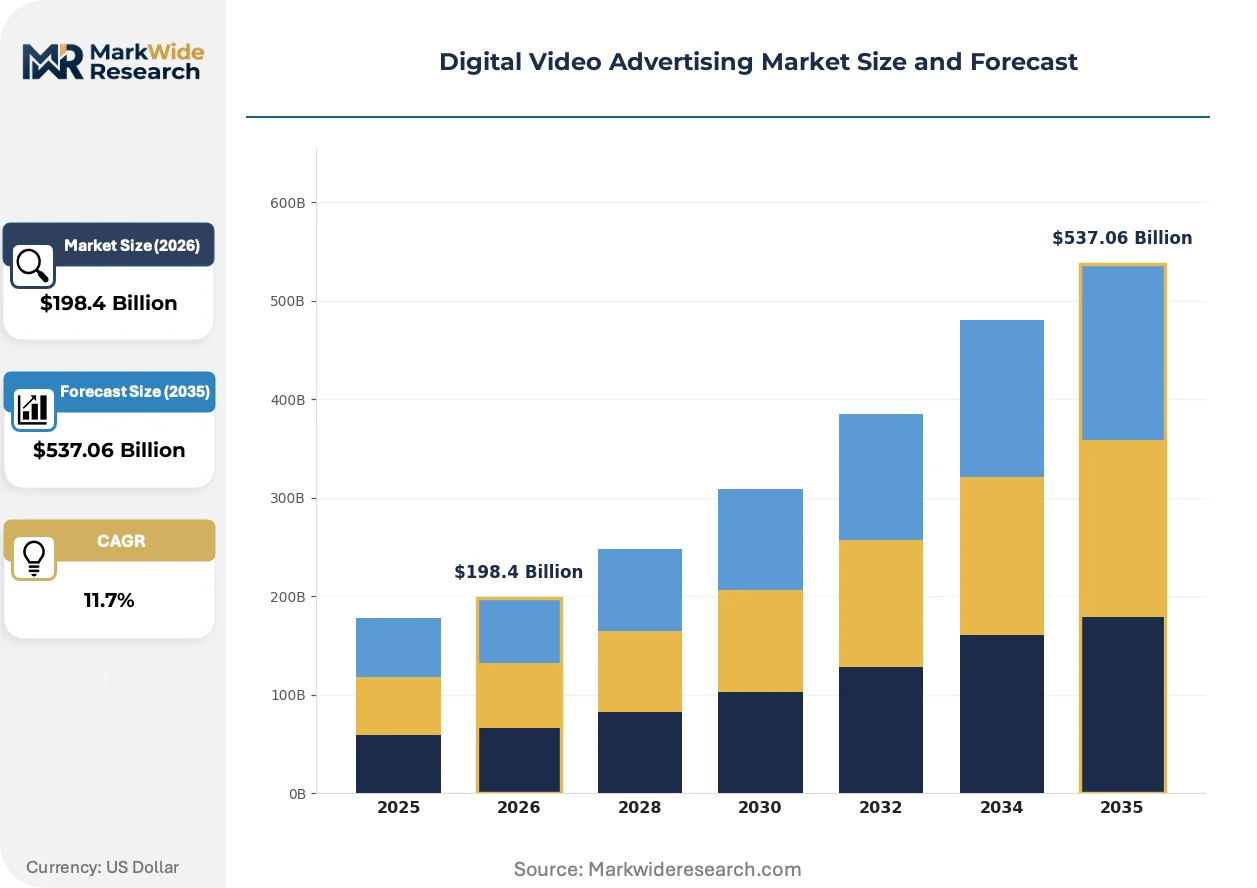
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $537.06 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Social Media, Over-the-Top (OTT), Video-on-Demand, Mobile Apps Ad Format: In-stream Ads, Out-stream Ads, Bumper Ads, Interactive Ads Target Audience: Millennials, Gen Z, Parents, Professionals Technological Integration: AI Algorithms, Programmatic Buying, Augmented Reality, Data Analytics |
| Companies Covered | The Trade Desk, PubMatic, Inc., Tremor International Ltd., Innovid, Viant Technology LLC, Google LLC, Meta Platforms, Inc., Amazon.com, Inc., ByteDance Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Video Advertising Market Strategic Shifts & Innovations
Real-time bidding infrastructure is absorbing functions previously performed by manual insertion orders, while artificial intelligence compresses the cycle between creative testing and budget reallocation. These forces are redistributing margin from media agencies to technology platforms.
Server-side ad insertion is displacing client-side SDK implementations that introduced latency and blocking vulnerabilities. Premium publishers including broadcasters and sports leagues are adopting SSAI to preserve quality-of-service metrics during high-concurrency events. This migration is displacing legacy waterfall mediation stacks and consolidating technical vendor relationships.
The Federal Trade Commission is scrutinizing data practices in behavioral targeting, elevating consent documentation requirements for audience segmentation. Advertisers must now maintain audit trails demonstrating lawful basis for processing. This enforcement pattern is most pronounced in the United States, where class-action exposure has prompted legal teams to pre-approve data-sharing arrangements with platform partners.
Brand marketers are consolidating planning authority within in-house programmatic trading desks, bypassing traditional media agency retainers. This concentration of buying power is compressing fee structures and demanding direct platform relationships. The shift is most visible among Fortune 500 advertisers in North America and Western Europe, where procurement teams have mandated transparency on auction dynamics and supply-path optimization.
Digital Video Advertising Market Segmentation
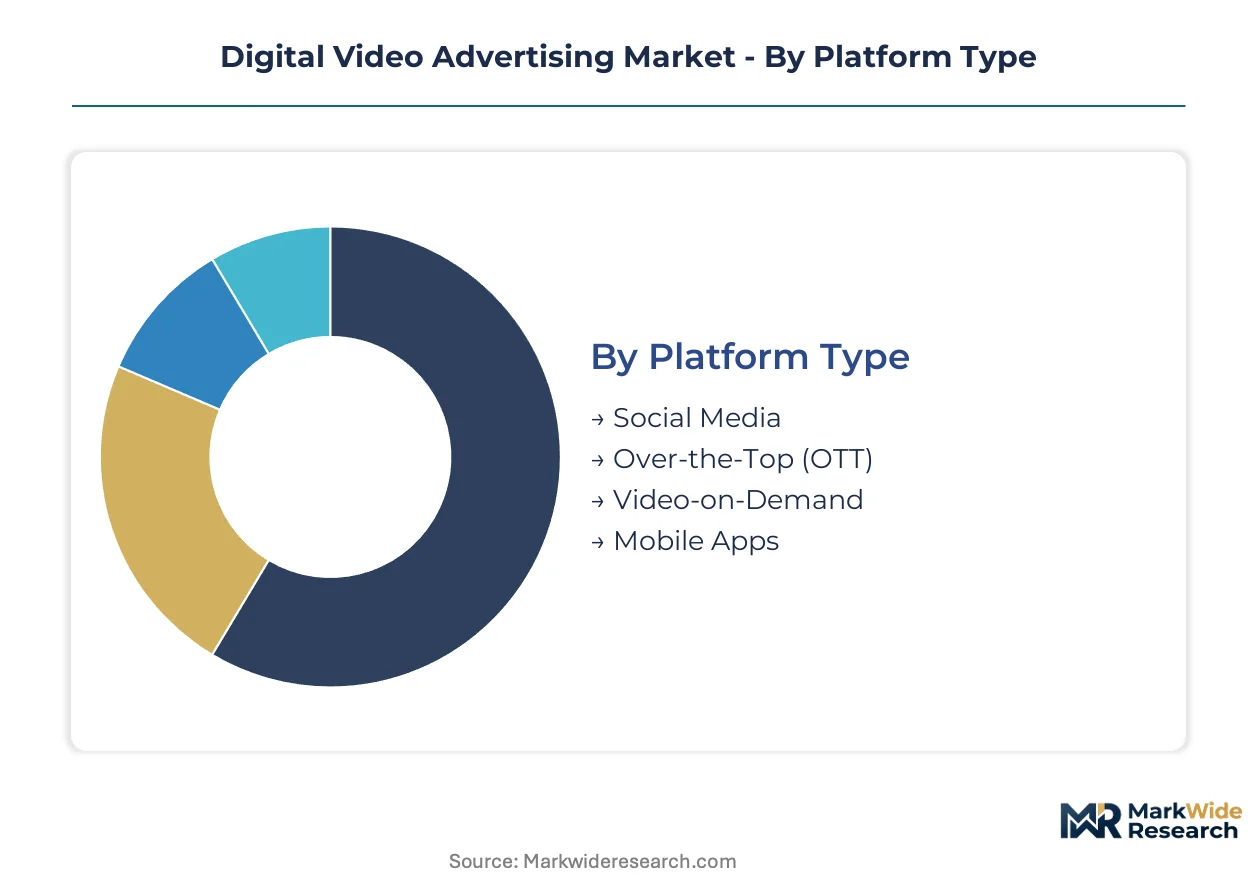
Platform fragmentation and format innovation are reshaping how advertisers allocate budgets across video inventory. Understanding segment-level substitution dynamics reveals which channels face displacement pressure from emerging alternatives.
Platform Type:
Social Media faces the strongest substitution threat as short-form vertical formats cannibalize traditional display and pre-roll placements.
- Social Media:Algorithmic content graphs on TikTok and Instagram Reels deliver full-screen immersive experiences. Demand concentrates among Gen Z demographics in the United States, where attention spans favor sub-60-second creative units over conventional storytelling formats.
- Over-the-Top (OTT):Connected TV platforms like Roku and Amazon Fire TV enable addressable advertising during premium long-form content. Brand safety requirements from Fortune 500 advertisers in the United States favor OTT's controlled content environments over user-generated alternatives.
- Video-on-Demand:Subscription-supported and ad-supported tiers on Netflix, Disney+, and Hulu create differentiated inventory pools.
- Mobile Apps:In-app rewarded video and interstitial placements monetize gaming and utility applications.
OTT retains volume leadership; Social Media holds the steepest expansion curve.
Ad Format:
Cost tier differentiation separates premium guaranteed placements from auction-traded remnant inventory.
- In-stream Ads:Pre-roll, mid-roll, and post-roll placements inserted before or during video content command measurable viewability rates. Advertisers in the United States prioritize in-stream for brand awareness campaigns requiring completed view metrics.
- Interactive Ads:Shoppable units and gamified templates enable direct response actions within the video frame. Retail media networks leverage interactive formats to close the loop between exposure and purchase verification.
- Out-stream Ads:Autoplay video units embedded in article feeds and social timelines expand inventory supply beyond video-native publishers.
- Bumper Ads:Six-second non-skippable units on YouTube and similar platforms force creative compression for attention capture.
In-stream commands the pricing premium; Interactive formats are climbing fastest on engagement-based valuation models.
Target Audience:
Application-specific messaging requirements drive format and platform selection across demographic cohorts.
- Gen Z:Digital-native consumers aged 18-26 demonstrate highest receptivity to influencer-integrated and user-generated content formats. Platforms prioritize authenticated identity graphs to reach this privacy-conscious segment.
- Millennials:Streaming-first households with established purchasing power respond to connected TV placements during live sports and scripted programming.
- Parents:Household decision-makers for CPG and family-oriented brands concentrate on YouTube Kids and family-friendly OTT content.
- Professionals:B2B advertisers target LinkedIn video and premium publisher environments during business hours.
Millennials retain volume leadership; Gen Z holds the steepest expansion curve.
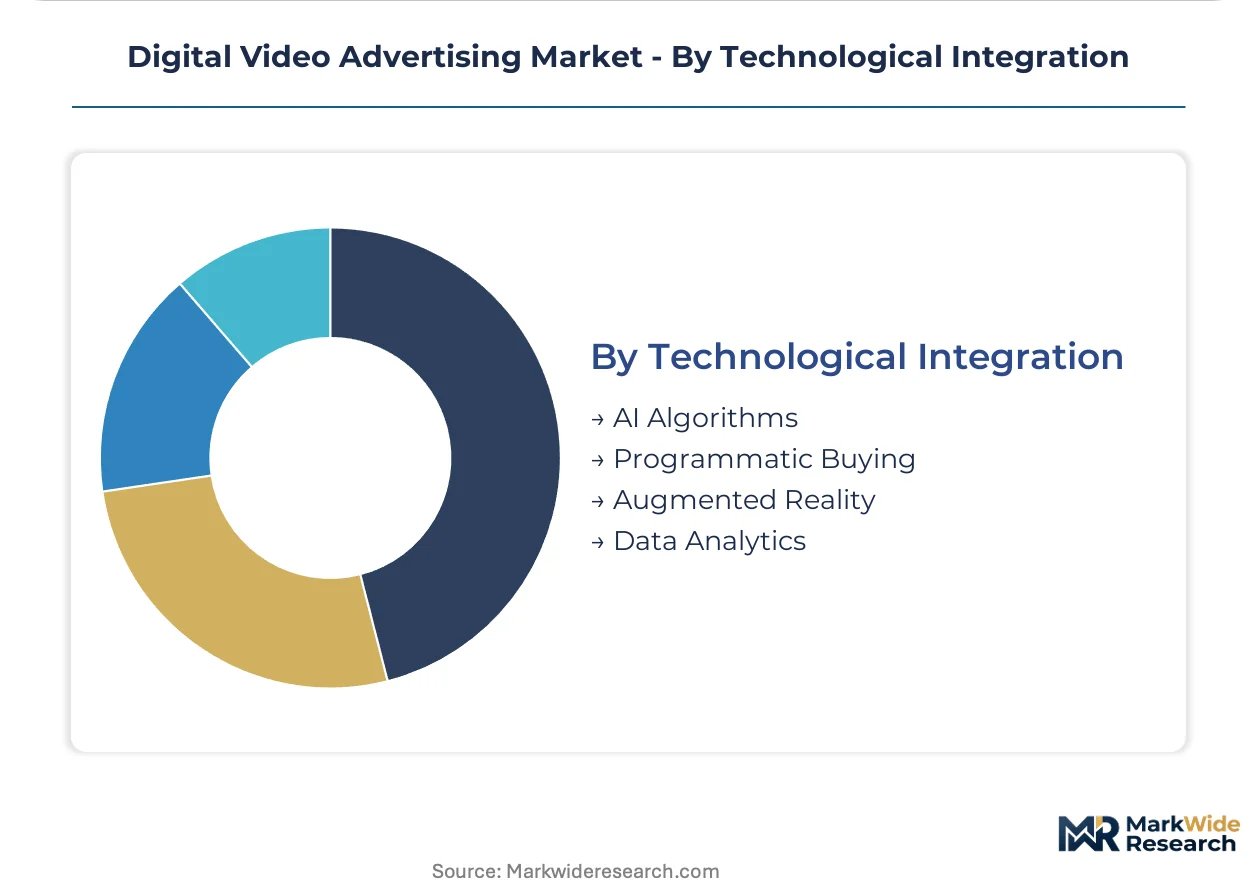
Technological Integration:
Supply concentration among platforms with proprietary data assets determines competitive positioning in targeting capabilities.
- AI Algorithms:Machine learning models optimize creative selection and bid pricing in real-time auction environments. The Trade Desk and similar demand-side platforms deploy AI to compress the gap between impression and conversion.
- Programmatic Buying:Automated transaction protocols displace manual insertion orders across premium publisher inventory. Real-time bidding infrastructure enables impression-level targeting that legacy reservation systems cannot match.
- Data Analytics:Clean-room architectures and probabilistic matching techniques rebuild audience graphs after third-party cookie deprecation.
- Augmented Reality:Camera-enabled ad units on Snapchat and Instagram overlay branded content onto physical environments.
Programmatic Buying retains volume leadership; AI Algorithms hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertisers in the United States tolerate premium CPMs for addressable inventory, while price-sensitive buyers in emerging markets prioritize reach over precision targeting. This elasticity gap shapes platform investment patterns and technology adoption timelines.
United States
Connected TV penetration and brand safety requirements drive demand concentration. The Federal Trade Commission enforces consent documentation for behavioral targeting, elevating compliance costs. Los Angeles and New York media clusters host the largest in-house programmatic trading desks among Fortune 500 advertisers.
China
Short-form vertical video and live-stream commerce attract mobile-first advertising budgets. The Ministry of Industry and Information Technology oversees data localization requirements under national cybersecurity frameworks. Shenzhen and Hangzhou technology corridors concentrate platform engineering talent for algorithmic content distribution.
Germany
Privacy-conscious advertisers favor contextual targeting over behavioral methods. GDPR enforcement through state data protection authorities mandates explicit consent for audience segmentation. Berlin and Munich advertising hubs specialize in first-party data strategies for automotive and industrial clients.
United Kingdom
Streaming platforms and broadcaster video-on-demand capture linear television migration. The Information Commissioner's Office scrutinizes real-time bidding data flows under UK GDPR post-Brexit adaptations. London's Soho district clusters independent production studios creating vertical video assets for platform-native campaigns.
India
Mobile-first video consumption on affordable data plans expands addressable audiences. The Telecom Regulatory Authority of India mandates transparency in tariff disclosures for digital advertising services. Mumbai and Bangalore media markets concentrate influencer marketing agencies serving regional language content creators.
Digital Video Advertising Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Demand-side platforms with unified identity frameworks command premium positioning, while supply-side platforms compete on inventory access and yield optimization. The market organizes around three archetypes: walled-garden platforms with proprietary data assets, independent programmatic specialists, and retail media networks with closed-loop measurement. Competitive moves concentrate on strategic partnerships for identity resolution and vertical integration into first-party data infrastructure.
Among demand-side specialists, The Trade Desk and PubMatic occupy positions exemplifying independent programmatic infrastructure. Google LLC anchors the walled-garden archetype through integrated video and search advertising systems. ByteDance Ltd. represents the short-form vertical format specialist competing on algorithmic content distribution.
| Leading Market Players |
|---|
| The Trade Desk |
| PubMatic, Inc. |
| Tremor International Ltd. |
| Innovid |
| Viant Technology LLC |
| Google LLC |
| Meta Platforms, Inc. |
| Amazon.com, Inc. |
| ByteDance Ltd. |
| Others |
Cost & Logistics Intelligence
Forty-five-day inventory cycles for programmatic ad tech infrastructure concentrate purchasing power with platforms holding unified identity frameworks, compressing margins for intermediaries lacking direct publisher relationships. This lead-time compression reinforces pricing power asymmetries between walled-garden platforms and independent demand-side specialists.
Pricing Analysis
After-sales revenue from data management platform subscriptions and attribution analytics contracts drives lifetime value for ad tech vendors. Three-tier pricing structure across premium guaranteed inventory, programmatic private marketplace, and open auction remnant separates Fortune 500 advertisers from mid-market buyers from performance marketers. Cost compression in open auction tiers intensifies because supply path optimization tools expose hidden fees. Mid-market advertisers exhibit highest price sensitivity; premium publishers command least elasticity through scarcity of brand-safe video inventory.
Supply Chain Analysis
Inventory lead-times for connected TV ad slots compress to near-zero through real-time bidding infrastructure, eliminating traditional reservation buffers. Engineering talent concentrates in the United States, China, and Israel; server-side ad insertion hardware sources from Taiwan and South Korea. The supply chain draws from cloud compute providers, data center operators, and specialized video encoding chip vendors. Single-source vulnerability rests on hyperscaler cloud dependencies for auction processing. Distribution runs through direct platform integrations and agency trading desk relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation across walled-garden, independent programmatic, and retail media archetypes creates multiple specialization niches. Advertiser migration from linear television to addressable video formats generates entry points for focused technology providers.
For Market Incumbents: Consolidate yield optimization capabilities through direct publisher integrations, neutralizing supply-side platform disintermediation threats. Prioritize first-party data infrastructure investments in California and New York media clusters to maintain targeting precision under CCPA enforcement. Secure certification for clean-room architectures ahead of third-party cookie deprecation deadlines.
For New Entrants and Emerging Players: Anchor in shoppable video and interactive ad format development, where engagement-based pricing models remain underdeveloped. Target mid-tier retail media networks lacking closed-loop measurement capabilities. Pursue vertical-specific agency partnerships as primary go-to-market channel rather than direct enterprise sales.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because programmatic infrastructure exhibits natural economies of scale in identity resolution and auction processing. Prioritize acquisition targets with authenticated user graphs and direct publisher integrations. Monitor FTC consent order patterns as signal for regulatory risk inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Unified ID Infrastructure Investment | Establishes persistent cross-platform measurement capabilities as third-party cookies deprecate. |
| Server-Side Ad Insertion Migration | Eliminates client-side latency vulnerabilities during high-concurrency sporting events for broadcasters. |
| Retail Media Network Partnership | Captures closed-loop attribution budgets migrating from linear television among CPG advertisers. |
| Clean-Room Architecture Certification | Enables privacy-compliant audience matching under CCPA and emerging state framework requirements. |
| Interactive Format Development | Commands premium CPMs through shoppable and gamified creative units outperforming standard pre-roll. |
Research Approach
A standing panel of programmatic trading desk directors, publisher yield managers, ad tech platform engineers, and brand marketing procurement leads provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings of publicly traded ad tech companies, FTC consent decrees and enforcement actions, IAB technical specifications, and hyperscaler cloud infrastructure disclosures. Bottom-up segment sizing triangulated against top-down advertising spend allocation surveys.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including platform type, ad format, target audience demographic, and technological integration depth. CAGRs derived from fitted growth curves applied to base-year observations, incorporating connected TV penetration trajectories and retail media network expansion rates as industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of sustained connected TV adoption and stable regulatory enforcement intensity; material deviation in privacy legislation timing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Global Animation Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
Secondary Ticket Market
Digital Media
Online Entertainment Market
Digital Media
Europe Online Gambling Market
Digital Media
Anime Derivatives Market
Digital Media
Japan Webtoons Market
Digital Media
Digital Media Market
Digital Media
North America Webtoons Market
Digital Media
Digital Music Services Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
Global Virtual Goods Market
Digital Media
United States Online Gambling Market
Digital Media
Global Streaming Media Device Market
Digital Media
North America Photographic Services Market
Digital Media
Africa Animation Market