
 Anime Derivatives Market | 2026-2036
Anime Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Anime Derivatives Market Insights
Japan's revised Copyright Act is hardening the cost-of-entry calculus for unlicensed manufacturers and grey-market importers. Bandai Namco Holdings leverages its captive supply of injection-mold tooling across domestic plants to dominate high-volume figure production. Good Smile Company specializes in artisan-grade polystone and PVC collectibles that command sustained price premiums in direct-to-consumer channels.
Anime derivatives encompass licensed consumer goods—figures, apparel, accessories, and art books—fabricated through rotocasting, injection molding, or textile sublimation to commemorate specific intellectual properties. Collectors drive margin concentration in limited-edition resin figures with numbered certificates, while casual fans populate volume tiers through mass-market apparel and accessories distributed via online retail platforms.
Japan's METI monitors export licensing frameworks, while the US CBP enforces customs IP border controls that block counterfeit shipments. China's SAMR administers mandatory GB 6675 toy safety testing that adds certification lead time for figure imports. Stakeholders must weigh royalty obligations against manufacturing jurisdiction to preserve margin structure as enforcement intensifies across major consumption markets.
Market Dynamics
Japan's revised Copyright Act enforcement is hardening penalties for unauthorized replica production, reshaping cost structures for grey-market importers while channeling volume toward licensed manufacturers with captive tooling infrastructure.
Growth Catalysts
- Collector-grade resin casting:Adult hobbyists in North America and Europe are intensifying demand for artisan-grade polystone figures with numbered certificates, creating sustained price premiums in direct-to-consumer channels.
- China's GB 6675 toy safety framework:Mandatory testing protocols administered by SAMR are consolidating manufacturing toward certified facilities capable of absorbing compliance lead times.
- Seasonal broadcast synchronization:Premium limited-edition releases timed to anime broadcast schedules are compressing purchase windows and amplifying scarcity-driven pre-order velocity.
Market Restraints
- Petroleum-based PVC feedstock volatility:Injection-mold figure production remains exposed to resin price swings that compress margin buffers at mass-market tiers.
- Guangdong province tooling concentration:Rotocasting and mold fabrication capacity clusters in China's Pearl River Delta, creating geographic supply vulnerability.
- Artisan polystone curing limitations:Extended production cycles for hand-finished collectibles constrain volume scalability regardless of demand intensity.
Strategic Opportunities
- India's emerging licensed merchandise channel:Streaming platform penetration is cultivating first-generation collector bases in Mumbai and Bangalore underserved by direct distribution.
- Textile sublimation convergence with on-demand printing:Apparel derivatives are shifting toward zero-inventory production models that reduce forecast risk for seasonal designs.
- EU Green Deal circularity mandates:Packaging reduction requirements are favoring domestic European fulfillment centers capable of reusable container logistics.
Industry Challenges
- Master sculptor talent scarcity:Artisan-grade figure design requires specialized digital sculpting and traditional clay modeling competencies concentrated in Japan's Kanto region.
- IP licensing timeline fragmentation:Multi-territory rights negotiations for seasonal anime properties create coordination complexity between Japanese rights-holders and regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anime Derivatives Market |
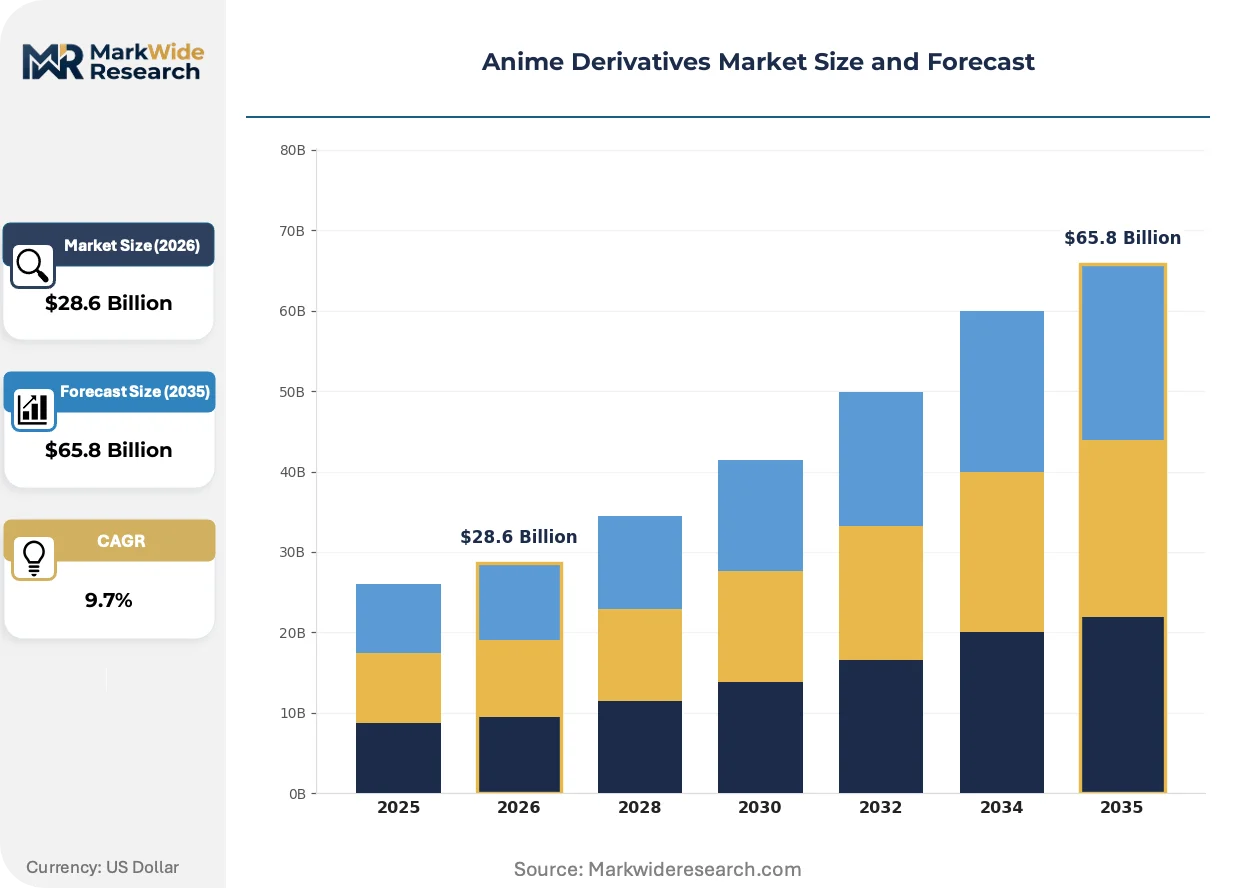
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $65.8 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Figures, Apparel, Accessories, Art Books Distribution Channel: Online Retail, Physical Stores, Convention Sales, Direct Sales Customer Type: Collectors, Casual Fans, Cosplayers, Merchandisers Licensing Type: Exclusive, Royalty-Free, Limited Edition, Open License |
| Companies Covered | Toei Animation, Aniplex, The Walt Disney Company, Production I.G., Guangdong Aofei Animation Culture, Bandai Namco Holdings, Good Smile Company, Hot Topic, Hasbro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anime Derivatives Market Trends and Innovations
Digital sculpting workflows and automated finishing systems are compressing prototype-to-production timelines, while regulatory enforcement and collector behavior shifts are redrawing competitive boundaries.
Photopolymer resin 3D printing is electrifying rapid prototyping for limited-run garage kit producers, enabling independent sculptors in Osaka and Tokyo to bypass traditional mold fabrication. Adult collectors seeking hyper-detailed unpainted kits are absorbing price premiums for direct-from-artist distribution. This technology is compressing the barrier between amateur production and commercial-grade output, forcing licensed manufacturers to accelerate release cadences.
REACH chemical restrictions on phthalate plasticizers are compelling PVC reformulation across EU-bound figure shipments, with ECHA compliance documentation now mandatory for all polymer imports. Manufacturers with in-house polymer chemistry capabilities are internalizing testing costs while smaller exporters face third-party certification bottlenecks. The premium resin figure segment is most affected, with collectors absorbing modest price adjustments for CE-marked products.
Direct-to-consumer pre-order platforms are displacing traditional wholesale distribution for limited-edition releases, with seasonal anime fans shifting purchase behavior toward crowdfunding-style commitment models. Specialty retailers in Los Angeles and London are responding by curating experiential showroom formats that justify physical presence. This channel rotation is most visible in North America, where collector community density supports dedicated convention circuits.
Anime Derivatives Market Segmentation
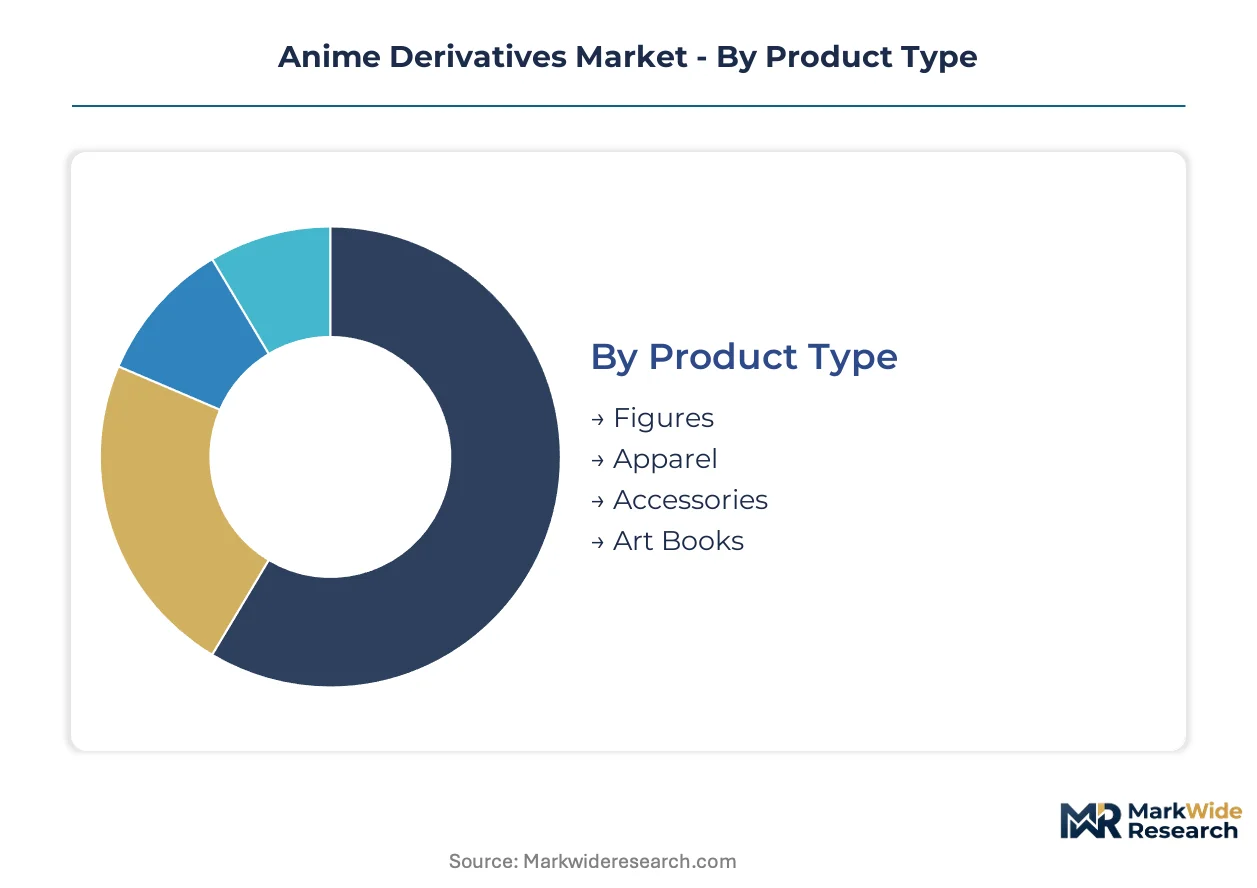
Anime derivatives fragment sharply across product tiers and purchase occasions, with collector-grade releases commanding margins that subsidize volume apparel operations. Licensing structures and channel economics create distinct competitive arenas where premium scarcity and mass accessibility coexist.
Product Type:
Integration depth separates standalone display pieces from wearable or consumable derivatives, with embedded collectibility driving pricing architecture.
- Figures:Artisan-grade polystone and PVC collectibles fabricated through rotocasting or injection molding, numbered certificates authenticate limited production runs. Collector demand concentrates in Japan's Kanto region and California's Los Angeles basin, where dedicated display infrastructure and convention circuits sustain premium price absorption.
- Apparel:Textile sublimation and screen-printed garments ranging from mass-market graphic tees to premium collaborative drops with named fashion labels. Casual fan bases in Germany and France drive volume through seasonal anime broadcast synchronization, though inventory risk from forecast error compresses margins at entry tiers.
- Accessories:Pins, keychains, and lifestyle objects bridging display and utility functions.
- Art Books:Production materials and illustration compilations targeting dedicated franchise followers.
Figures lead volumes today; art books are gaining share fastest.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth, with direct models displacing wholesale intermediaries in premium tiers.
- Online Retail:Crowdfunding-style pre-order platforms with zero-inventory commitment models compressing working capital requirements. North American collector density supports specialized marketplace infrastructure, though shipping complexity for fragile resin pieces elevates return rates.
- Physical Stores:Experiential showroom formats in London and Los Angeles curating display environments that justify premium pricing through tactile inspection.
- Convention Sales:Temporary high-velocity release windows tied to seasonal broadcast peaks, creating scarcity-driven purchase urgency.
- Direct Sales:Artist-to-collector channels for unpainted garage kits bypassing licensed manufacturing entirely.
Online retail dominates transaction volume; direct sales channels show steepest expansion trajectory.
Customer Type:
Purchase behavior and price elasticity diverge across engagement depth, from transactional fandom to investment-grade collecting.
- Collectors:Adult hobbyists acquiring numbered limited editions as alternative assets, with display infrastructure investments creating switching costs and brand loyalty. Japan's revised Copyright Act enforcement channels demand toward licensed channels with authenticity verification.
- Casual Fans:Broadcast-driven purchasers of mass-market apparel and accessories, price-sensitive and seasonally episodic in engagement patterns.
- Cosplayers:Performance-oriented buyers seeking costume-grade materials and prop replicas, with China's GB 6675 safety standards constraining import options for wearable items.
- Merchandisers:Commercial resellers and corporate gift purchasers operating under different procurement timelines and volume thresholds.
Collectors anchor revenue concentration; cosplayers represent the most price-elastic demand pool.
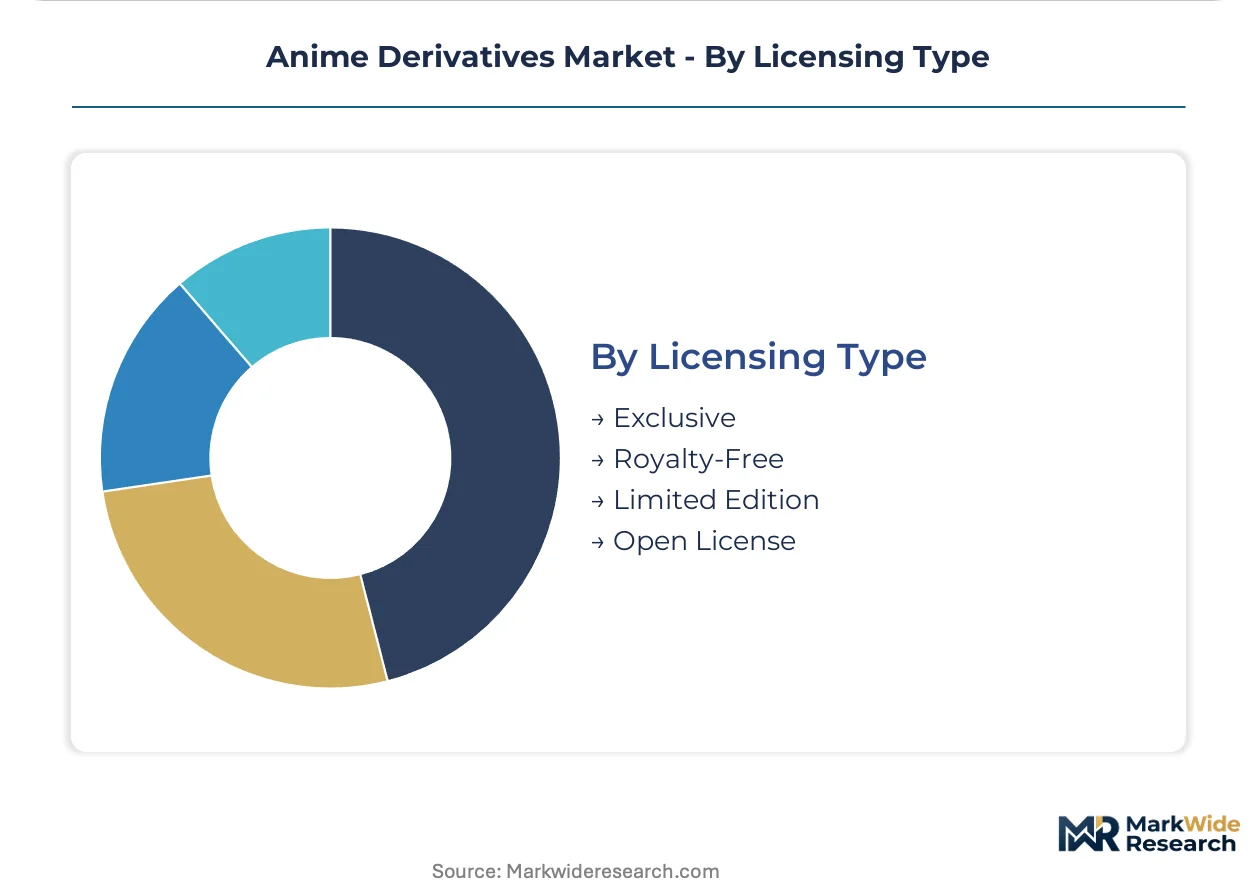
Licensing Type:
Rights architecture determines geographic reach, production timeline flexibility, and royalty burden distribution across the value chain.
- Exclusive:Single-territory or single-channel rights with highest royalty obligations but protected competitive positioning. METI export licensing frameworks in Japan create compliance lead times that advantage established distributors with regulatory relationships.
- Limited Edition:Time-bound or quantity-capped releases generating scarcity premiums and secondary market price appreciation.
- Royalty-Free:Flat-fee arrangements reducing per-unit cost variability for high-volume apparel production.
- Open License:Broad rights distribution enabling rapid market saturation but compressing margin through competitive replication.
Exclusive licenses dominate collector-tier revenue; limited edition structures are climbing the fastest in new release adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's post-war animation studios pioneered character merchandising as a revenue pillar, establishing licensing frameworks that now govern derivative production across Asia-Pacific and North American markets.
Japan
Adult collectors in Tokyo and Osaka sustain premium absorption for artisan-grade polystone figures with numbered certificates. METI export licensing frameworks create compliance lead times that advantage established distributors with regulatory relationships. Kanto region clusters around Saitama and Chiba prefectures concentrate master sculptor talent and injection-mold tooling infrastructure.
United States
Los Angeles and New York Metro harbor dense collector communities that support dedicated convention circuits and experiential showroom formats. US CBP enforces customs IP border controls that block counterfeit shipments at entry ports. Southern California's logistics hubs increasingly specialize in fragile resin figure fulfillment with damage-mitigation packaging protocols.
China
Streaming platform penetration in Shanghai and Beijing cultivates first-generation collector bases underserved by direct distribution. SAMR administers mandatory GB 6675 toy safety testing that adds certification lead time for figure imports. Guangdong province's Pearl River Delta clusters rotocasting and mold fabrication capacity, creating geographic supply concentration.
Germany
Casual fan bases in Berlin and Munich drive volume through seasonal anime broadcast synchronization for mass-market apparel. ECHA REACH chemical restrictions on phthalate plasticizers compel PVC reformulation for EU-bound figure shipments. Bavaria's textile sublimation facilities are adapting to on-demand production models that reduce inventory risk.
United Kingdom
London's specialty retailers curate experiential showroom formats that justify physical presence against direct-to-consumer pre-order platforms. EU Green Deal circularity mandates favor domestic fulfillment centers capable of reusable container logistics. Greater Manchester's distribution infrastructure is retooling for reduced packaging requirements.
Anime Derivatives Market Competitive Landscape
The competitive structure tilts toward diversified entertainment conglomerates with captive IP libraries and specialized collectible fabricators with artisan-grade production capabilities. Licensed manufacturers with in-house polymer chemistry and injection-mold tooling dominate high-volume tiers, while independent sculptors exploit photopolymer resin 3D printing for limited-run garage kits. Consolidation pressures intensify as copyright enforcement hardens cost-of-entry calculus for unlicensed operators. Dominant competitive moves include strategic partnerships between Japanese rights-holders and regional distributors, plus portfolio diversification into direct-to-consumer pre-order platforms.
Within the diversified entertainment tier, The Walt Disney Company and Hasbro exemplify conglomerate-scale licensing operations spanning multiple character portfolios and merchandise categories. Among specialized collectible fabricators, Good Smile Company and Bandai Namco Holdings occupy positions representing contrasting production philosophies—artisan-grade polystone craftsmanship versus high-volume injection-mold efficiency. Guangdong Aofei Animation Culture anchors Chinese domestic market presence. These archetypes illustrate how competitive positioning fragments across IP ownership depth, manufacturing sophistication, and channel control intensity.
| Leading Market Players |
|---|
| Toei Animation |
| Aniplex |
| The Walt Disney Company |
| Production I.G. |
| Guangdong Aofei Animation Culture |
| Bandai Namco Holdings |
| Good Smile Company |
| Hot Topic |
| Hasbro |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal circularity mandates are gating qualified supply and premium-tier pricing access, as reusable container logistics and packaging reduction requirements favor domestic European fulfillment centers capable of absorbing compliance costs while commanding scarcity premiums for certified sustainable releases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates numbered certificate polystone collectibles from mass-market PVC figures and entry apparel. Price differentiation hinges on artisan-grade hand-finishing and CE marking under ECHA REACH chemical restrictions. Cost compression in mass-market tiers is intensifying because petroleum-based PVC feedstock volatility erodes margin buffers. Casual fans exhibit highest price sensitivity, while adult collectors absorb sustained premiums for limited-edition resin releases.
Supply Chain Analysis
Master sculptor talent scarcity in Japan's Kanto region and injection-mold tooling concentration in Guangdong province are anchoring production geography. Raw material dependencies draw from petroleum-based PVC resin, photopolymer resins for prototyping, and polystone mineral composites. Single-source vulnerability concentrates in Guangdong's Pearl River Delta rotocasting clusters. Distribution runs through direct-to-consumer pre-order platforms displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anime derivatives market reads as a late-cycle quality story, with adult collectors shifting purchase behavior toward investment-grade numbered editions that justify sustained price premiums.
For Market Incumbents: To counter photopolymer resin 3D printing disruption from independent garage kit producers, Bandai Namco Holdings and Good Smile Company should accelerate release cadences through digital sculpting workflow compression. Captive injection-mold tooling across domestic plants preserves margin structure against unlicensed replica competition.
For New Entrants and Emerging Players: First-generation collectors in India's Mumbai and Bangalore represent underserved buyer archetype penetration opportunity. Streaming platform cultivation of anime fandom creates white-space for direct distribution partnerships bypassing established regional intermediaries. Crowdfunding-style pre-order platforms offer lowest-friction go-to-market entry.
For Investors and Strategic Acquirers: Roll-up economics work for specialized collectible fabricators with artisan-grade production capabilities because copyright enforcement hardening is eliminating unlicensed competitor supply. Long-term viability centers on IP licensing relationship depth with Japanese rights-holders. Watch for METI export licensing framework expansion as inflection signal for compliance-advantaged distributor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Sculpting Workflow Integration | Compresses prototype-to-production timelines for seasonal anime broadcast synchronization. |
| Direct-to-Consumer Pre-Order Platform Launch | Displaces wholesale intermediaries and captures scarcity-driven pre-order velocity. |
| CE Marking Investment for EU Compliance | ECHA REACH reformulation capabilities internalize testing costs for premium resin figures. |
| India Distribution Partnership | Streaming platform penetration in Mumbai cultivates first-generation collector base access. |
| Reusable Container Logistics Implementation | EU Green Deal packaging mandates favor domestic fulfillment centers in Greater Manchester. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with licensing executives at Japanese rights-holders, procurement leads at Guangdong manufacturing facilities, and category buyers at North American specialty retailers. Secondary validation drew from customs IP seizure records, METI export licensing disclosures, SAMR GB 6675 certification databases, and ECHA REACH compliance documentation. Bottom-up figure shipment tracking and top-down entertainment revenue triangulation anchored value estimates.
Historical reference periods spanning the analysis window established baseline growth trajectories for projection modeling. Segmentation dimensions included product type integration depth, distribution channel control intensity, customer engagement tier, and licensing rights architecture. CAGRs were derived from curve-fitting across observed volume and value patterns, with seasonal broadcast synchronization cycles and resin feedstock price indices incorporated as industry-specific forecast inputs.
Underlying measurement precision varies by segment; collector-grade figure volumes carry tighter precision than casual fan apparel forecasts due to direct-to-consumer pre-order platform data availability. Projections reflect assumptions regarding copyright enforcement trajectory, streaming platform penetration rates, and resin price volatility. Material deviation in Japan's Copyright Act penalty implementation or ECHA REACH restriction expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Anime Streaming Tool Market
Digital Media
Europe Online Gambling Market
Digital Media
Europe Online Video Platform Market
Digital Media
Europe Location-Based Entertainment Market
Digital Media
Global ACGN Market
Digital Media
Media Coding Service Market
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Anime Merchandising Market
Digital Media
Multichannel Network Market
Digital Media
US Animation, Vfx and Post Production Market
Digital Media
Digital Rights Management in Media and Entertainment Market
Digital Media
Art App Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
Sound Effects Services Market