
 Global Streaming Media Device Market | 2026-2036
Global Streaming Media Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Streaming Media Device Market Foresight
Southeast Asia's electronics manufacturing corridor is reshaping component sourcing for streaming hardware. Amazon leverages captive logistics to control fulfillment costs across North American and European markets. Apple anchors premium positioning through proprietary silicon integration in its set-top ecosystem. Xiaomi competes aggressively on cost-engineered streaming sticks targeting price-sensitive Asian and Latin American consumers.
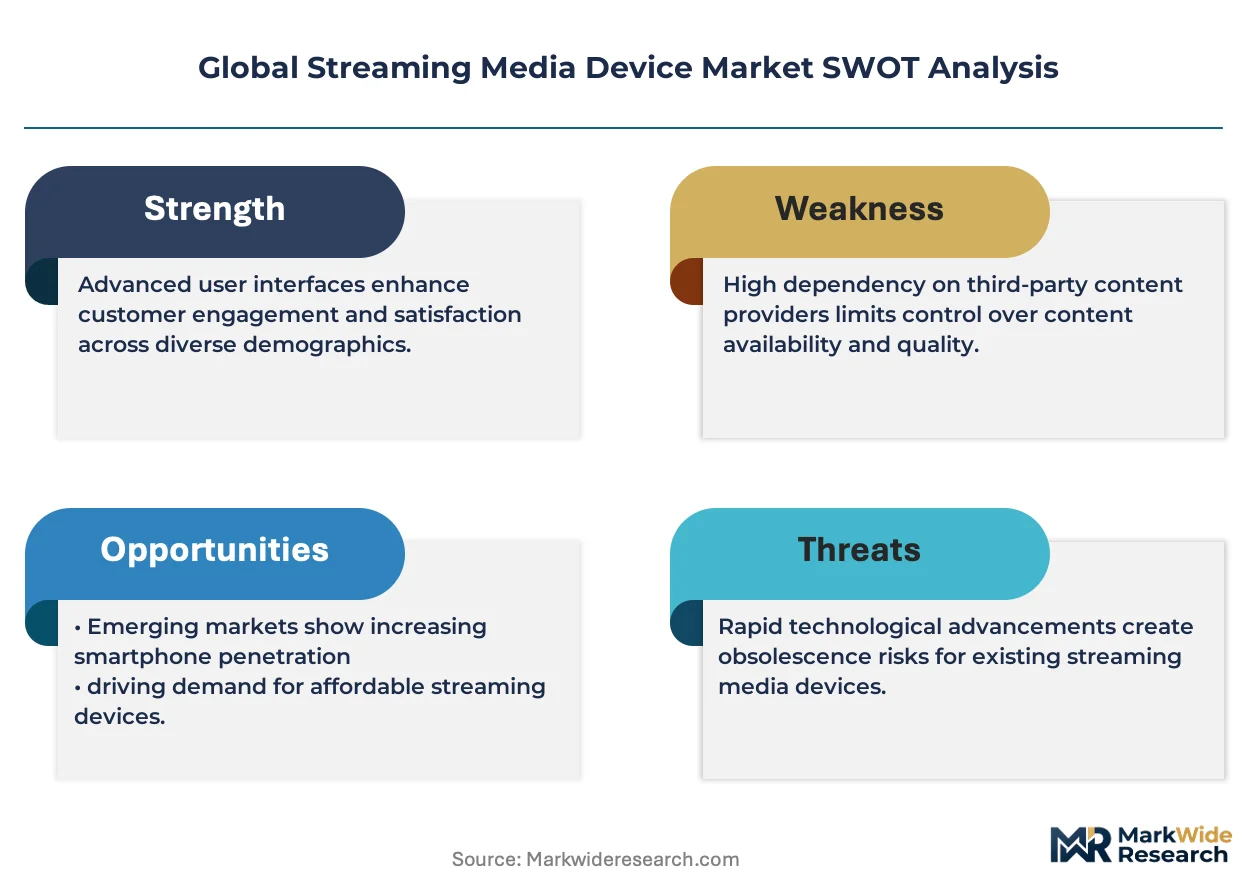
A streaming media device is a dedicated hardware unit that decodes digital video and audio streams, typically featuring ARM-based processors, HDMI output interfaces, and dual-band Wi-Fi connectivity to deliver over-the-top content to display screens. Smart TVs capture the largest installed base among product types, though streaming sticks generate higher replacement frequency and attach rates for subscription services. Wi-Fi technology dominates connectivity specifications, while Ethernet retains share in commercial establishments where bandwidth stability governs quality of service. The hospitality sector represents an underdeveloped end-user segment with concentrated procurement volumes from multinational hotel chains.
The FCC governs wireless spectrum allocation affecting streaming device radio performance in the United States, while the EU AI Act imposes transparency requirements on content recommendation algorithms embedded in smart platforms. India's BIS mandates safety and electromagnetic compatibility certification for imported electronics, directly influencing market access timelines for foreign manufacturers. Stakeholders must monitor evolving interoperability standards between proprietary operating systems and third-party streaming applications as platform fragmentation intensifies.
Market Dynamics
Broadband infrastructure buildouts and the FCC's net neutrality framework are compressing content delivery costs while fragmenting platform control across proprietary operating systems and third-party applications.
Growth Catalysts
- FCC Spectrum Allocation:Wireless spectrum reforms in the United States expand device radio performance and reduce interference for dual-band Wi-Fi streaming hardware.
- India BIS Certification:Standardized safety and electromagnetic compatibility requirements accelerate formal channel penetration for affordable streaming sticks in price-sensitive segments.
- Hospitality Sector Procurement:Multinational hotel chains consolidate connected room deployments, creating concentrated volume demand for commercial-grade Ethernet-enabled devices.
Market Restraints
- ARM Processor Supply Concentration:Foundry capacity constraints in Taiwan and South Korea create input bottlenecks for decoder chip fabrication.
- EU AI Act Compliance Burden:Transparency mandates for content recommendation algorithms extend firmware development timelines and raise certification costs for smart platform operators.
- Smart TV Substitution:Integrated display-streaming convergence in television manufacturing reduces standalone device attach rates in mature broadband markets.
Strategic Opportunities
- Latin American Broadband Expansion:Fiber-to-the-home rollouts in Brazil and Mexico create first-time streaming hardware demand among previously unconnected households.
- EU Green Deal Incentives:Energy efficiency labeling requirements favor low-power ARM-based architectures over legacy x86 streaming solutions.
- Voice-Remote Convergence:Integration of far-field microphone arrays with HDMI-CEC control protocols opens premium positioning in smart home ecosystems.
Industry Challenges
- Firmware Security Talent Scarcity:Shortage of embedded systems engineers with OTA update architecture expertise delays patch deployment cycles.
- Interoperability Certification Complexity:Fragmented DRM licensing across Widevine, PlayReady, and FairPlay forces redundant validation testing per platform.
- Legacy Hotel Infrastructure Integration:Coaxial-based property management systems in older hospitality assets require costly gateway retrofits for IP streaming compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Streaming Media Device Market |
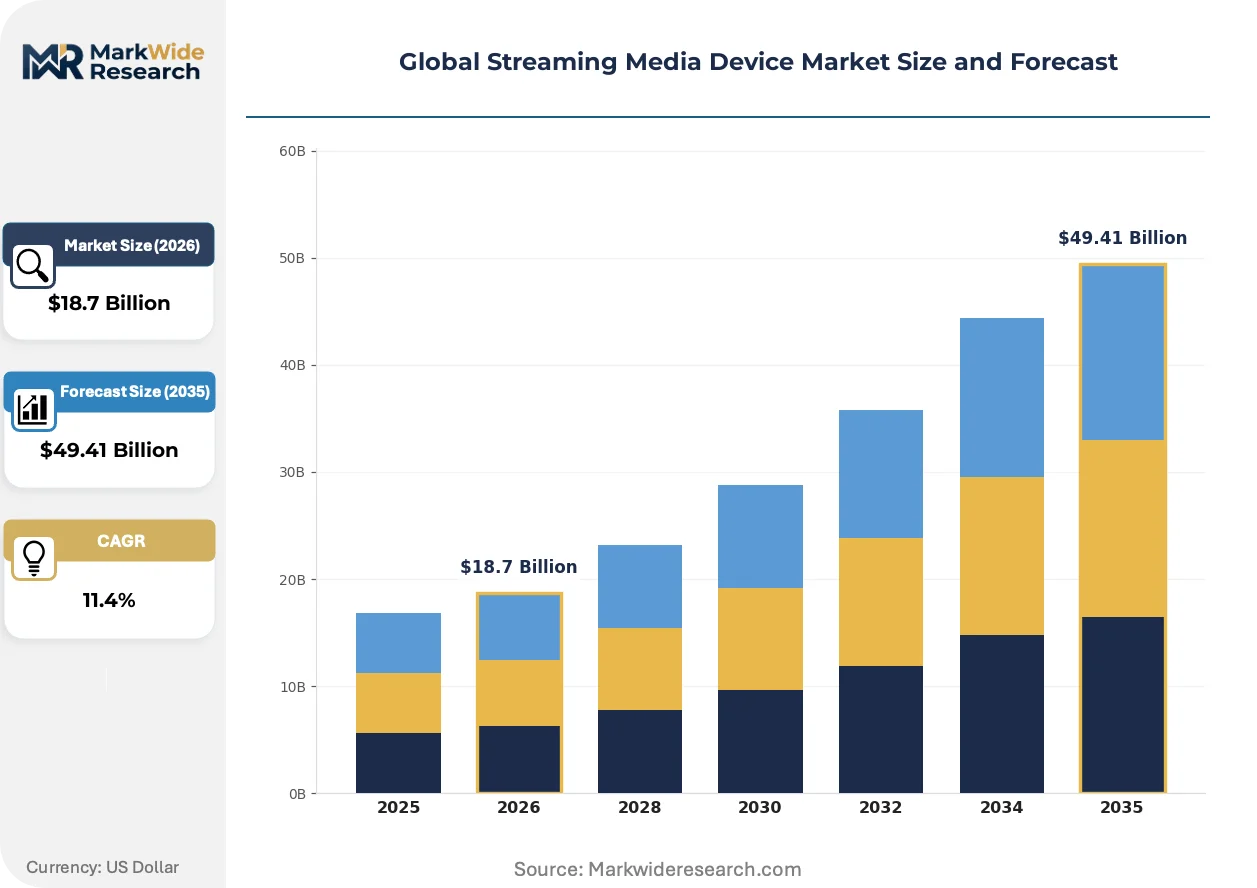
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart TVs, Streaming Sticks, Set-Top Boxes, Game Consoles Technology: HDMI, Wi-Fi, Ethernet, Bluetooth End User: Home Users, Educational Institutions, Commercial Establishments, Hospitality Sector Distribution Channel: Online Retailers, Direct Sales, Electronics Stores, Wholesalers |
| Companies Covered | Amazon, Apple, Google, Roku, Sony, Microsoft, Xiaomi, Samsung, Nvidia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Streaming Media Device Market Shifts & Advancements
Cloud-native streaming architectures are compressing hardware decoder requirements while elevating software-defined feature delivery as the primary competitive vector.
Edge computing offload is virtualizing traditional set-top box functions. Hospitality chains and multi-dwelling unit operators deploy thin-client streaming endpoints that render content via remote GPU instances. This architecture reduces per-room hardware capex while centralizing content licensing compliance.
The EU AI Act imposes algorithmic transparency obligations on content recommendation engines. Streaming platform operators must document training data provenance and inference logic for regulatory audit. Smart TV manufacturers integrating third-party operating systems face downstream liability exposure from embedded recommendation modules.
Direct-to-consumer hardware subscriptions are displacing retail channel dependency. Original equipment manufacturers in Shenzhen and Taipei bypass distributor markups through crowdfunding pre-orders and owned-commerce fulfillment. This model concentrates customer relationship data while compressing working capital requirements for new product launches.
Global Streaming Media Device Market Segmentation
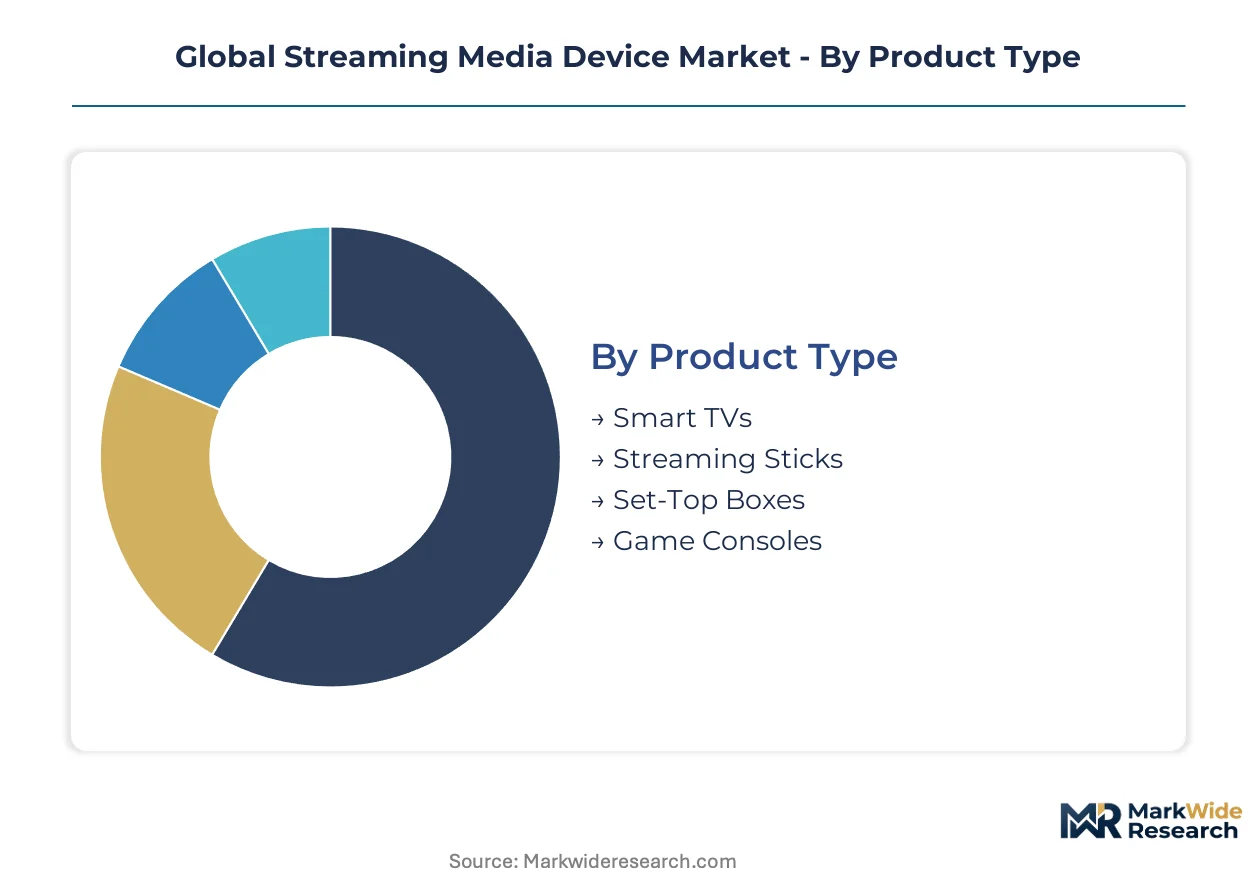
Streaming media device segmentation reveals divergent hardware specifications across connectivity environments and procurement contexts. Product architecture, interface standards, and channel economics each create distinct competitive battlegrounds with unique margin profiles and replacement cycles.
Product Type:
Mature display-integrated categories coexist with emerging modular form factors as broadband penetration reshapes replacement behavior.
- Smart TVs:Integrated 4K and 8K display panels with embedded ARM-based decoding chipsets and proprietary smart operating systems. Demand concentrates in North American and European households upgrading aging LCD installations, constrained by extended replacement cycles exceeding seven years.
- Streaming Sticks:Compact HDMI-dongle form factors with low-power SoC architectures and minimal onboard storage. Growth accelerates in Indian and Southeast Asian price-sensitive segments where consumers add streaming capability to existing display assets without full television replacement.
- Set-Top Boxes:Standalone decoder units with advanced thermal management and expandable storage options. Pay-TV operators in Latin America deploy these for hybrid broadcast-IP service delivery.
- Game Consoles:Multi-function entertainment systems with high-performance GPU architectures and proprietary content ecosystems. Sony and Microsoft hardware anchors premium living-room positioning through exclusive streaming application partnerships.
Smart TVs retain volume leadership; streaming sticks hold the steepest expansion curve.
Technology:
Cost tier differentiation separates legacy copper interfaces from premium wireless implementations requiring RF engineering investment.
- HDMI:High-bandwidth digital content protection-enabled video interface standardizing 4K HDR signal transmission. Consumer electronics manufacturers in Shenzhen prioritize HDMI 2.1 certification for premium product differentiation.
- Wi-Fi:Dual-band 802.11ac and Wi-Fi 6 radio implementations with beamforming antenna arrays. Residential demand in suburban United States markets depends on mesh network compatibility for whole-home streaming coverage.
- Ethernet:Gigabit wired connectivity ensuring jitter-free 4K streaming in bandwidth-constrained environments. Commercial establishments and hospitality properties mandate Ethernet for quality-of-service guarantees.
- Bluetooth:Low-energy peripheral pairing protocol enabling wireless audio output and voice remote integration. Premium device tiers leverage Bluetooth 5.0 for multi-room audio synchronization.
Wi-Fi dominates unit shipments; Ethernet commands premium pricing in commercial applications.
End User:
Application context dictates durability specifications, with consumer-grade plastics giving way to hardened enclosures in institutional deployments.
- Home Users:Individual residential purchasers prioritizing ease-of-setup and streaming service compatibility. North American households drive replacement demand as legacy 1080p devices face application performance degradation.
- Educational Institutions:K-12 and university procurement of classroom presentation systems with centralized device management. Indian government digital education initiatives are expanding hardware tenders for connected classroom infrastructure.
- Commercial Establishments:Corporate digital signage and meeting room streaming endpoints requiring enterprise security certification. Multi-tenant office buildings in Germany specify GDPR-compliant firmware configurations.
- Hospitality Sector:Hotel guest room entertainment systems with property management system integration and guest privacy controls. Marriott and Hilton procurement standards are consolidating around IP-based streaming architectures.
Home users generate absolute volume; hospitality procurement offers concentrated contract value.
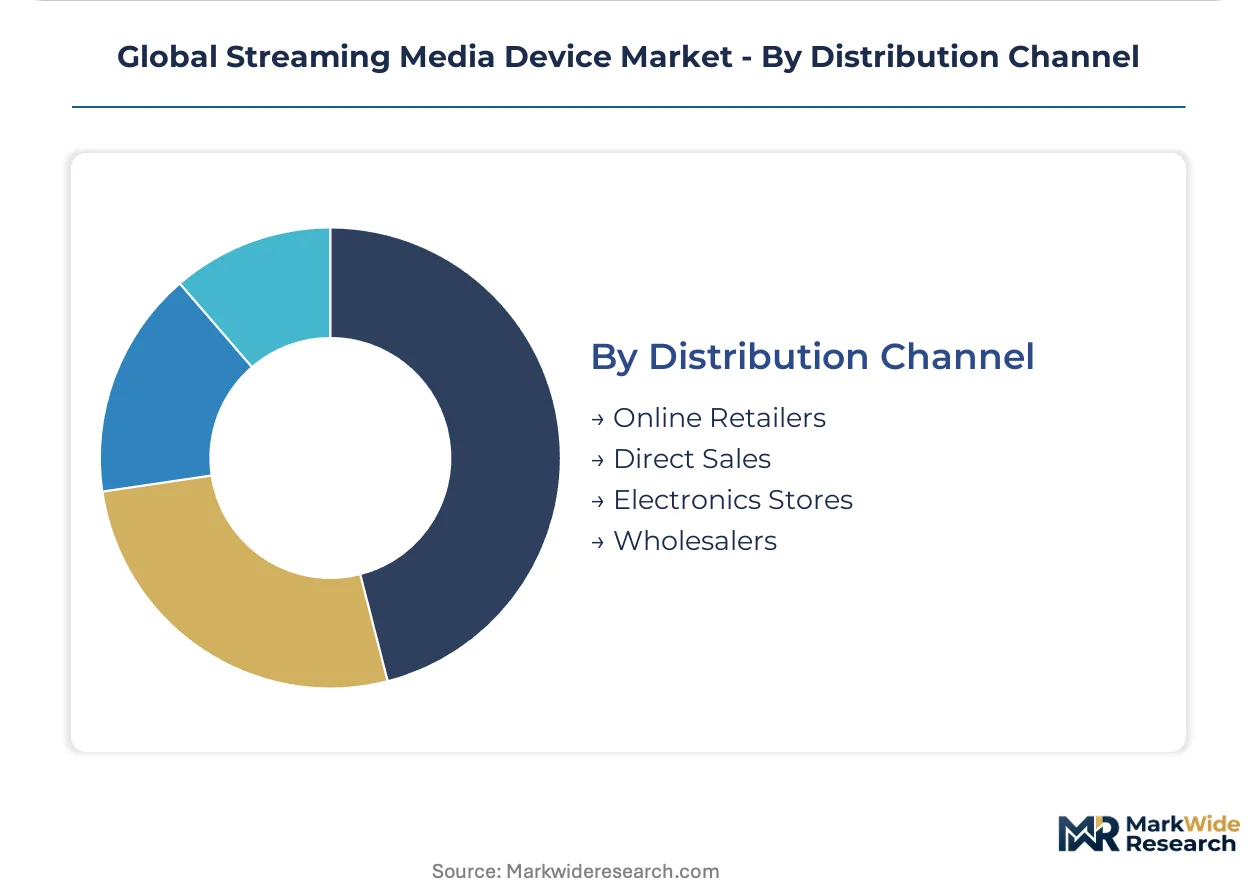
Distribution Channel:
Customer type separates self-directed online purchasers from relationship-dependent institutional buyers.
- Online Retailers:Amazon and regional e-commerce platforms capturing consumer convenience preference with comparison shopping tools. Indian marketplaces Flipkart and Amazon India dominate affordable streaming stick volume.
- Direct Sales:Manufacturer-owned storefronts and crowdfunding pre-order campaigns capturing early-adopter segments. Shenzhen OEMs bypass distributor markups through owned-commerce fulfillment.
- Electronics Stores:Brick-and-mortar retail with in-person demonstration and immediate availability. Brazilian consumer electronics chains anchor middle-class purchasing in São Paulo and Rio de Janeiro metro areas.
- Wholesalers:B2B volume distributors serving hospitality and commercial integrators with project-based pricing. European AV integrators source through specialized distribution for multi-property hotel deployments.
Online retailers capture consumer volume; wholesalers dominate hospitality and commercial contract flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication concentrates in Taiwan and South Korea, while final assembly clusters in Shenzhen and Vietnam. Demand generation splits across mature broadband markets and emerging connectivity zones. Regulatory frameworks in the United States, European Union, and India are reshaping certification timelines and market access conditions.
United States
FCC spectrum reforms are expanding dual-band Wi-Fi capacity for residential streaming hardware. The net neutrality framework shapes infrastructure investment patterns across content delivery networks. Silicon Valley engineering clusters dominate cloud-native streaming architecture development.
Germany
EU AI Act compliance requirements are extending firmware development cycles for smart platform operators. The Green Deal energy efficiency labeling favors low-power ARM-based decoder architectures. Bavarian industrial automation firms supply precision manufacturing equipment to Asian assembly partners.
India
BIS certification mandates are accelerating formal channel penetration for affordable streaming sticks. Government digital education initiatives are expanding hardware tenders for connected classroom infrastructure. Tamil Nadu electronics manufacturing zones attract component sourcing for export-oriented OEMs.
Brazil
Fiber-to-the-home rollouts in São Paulo and Rio de Janeiro are creating first-time streaming hardware demand. ANVISA-equivalent electromagnetic compatibility standards govern import certification timelines. Consumer electronics chains in southeastern metro areas anchor middle-class purchasing patterns.
Japan
METI technology roadmaps are guiding 8K display-integrated streaming system development. JIS standards interoperability requirements influence regional firmware customization. Kanto region semiconductor fabs supply specialized decoder chips for premium television integration.
Global Streaming Media Device Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in silicon and display supply. The vendor base spans vertically integrated consumer electronics conglomerates, cloud-native service operators, and contract manufacturing specialists. Three archetypes dominate: ecosystem architects controlling proprietary operating systems, cost-engineered hardware specialists, and hospitality-focused commercial integrators. Capacity expansion in Vietnam and Mexico is accelerating, while strategic partnerships between content platforms and OEMs are displacing traditional retail channel dependency.
Among ecosystem architects, Amazon and Apple exemplify divergent positioning strategies. Amazon leverages captive logistics infrastructure and cloud service integration to compress fulfillment economics across North American and European markets. Apple anchors premium positioning through proprietary silicon integration and vertical control over hardware-software interfaces. Xiaomi occupies a cost-engineered specialist position, targeting price-sensitive demand concentrations in Asian and Latin American segments through Shenzhen-based supply chain proximity.
| Leading Market Players |
|---|
| Amazon |
| Apple |
| Roku |
| Sony |
| Microsoft |
| Xiaomi |
| Samsung |
| Nvidia |
| Others |
Supply & Pricing Matrix
The Shenzhen-Hong Kong freight corridor compresses logistics costs for ARM-based decoder chipsets while amplifying price differentiation between premium silicon-integrated devices and cost-engineered streaming sticks. Supply concentration in Taiwanese foundries and Vietnamese assembly plants creates tiered procurement economics where captive logistics networks command margin advantages over distributor-dependent competitors.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across smart platform operators, separating GDPR-compliant firmware configurations from standard consumer-grade deployments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the economy tier intensifies as Xiaomi and Shenzhen OEMs crowd the sub-$30 streaming stick segment. Hospitality procurement demonstrates the lowest price sensitivity due to property management system integration requirements, while Indian household consumers exhibit the highest elasticity.
Supply Chain Analysis
Silicon wafer supply draws from Taiwan, South Korea, and Japan, with ARM processor tape-outs concentrating in Hsinchu Science Park facilities. Component dependencies span DRAM modules from SK Hynix and Micron, HDMI controller ICs from Realtek and MediaTek, and passive components from Murata and TDK. Single-source vulnerability in advanced node foundry capacity creates procurement risk during demand spikes. Distribution runs through Amazon's captive fulfillment network for North American consumer volume and specialized AV integrators for hospitality contract flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where proprietary operating system ecosystems generate switching costs that lock consumers into content platform bundles. Regulatory entrenchment through BIS, FCC, and EU AI Act compliance requirements raises barriers for unlicensed entrants.
For Market Incumbents: Pre-empt hospitality sector consolidation by embedding property management system compatibility into firmware architectures before Marriott and Hilton procurement standards solidify. Accelerate backward integration into ARM-based silicon design to reduce foundry dependency exposure. Channel control through direct-to-consumer crowdfunding platforms compresses working capital requirements while capturing customer relationship data.
For New Entrants and Emerging Players: Establish a beachhead in Latin American fiber-to-the-home expansion zones where first-time streaming hardware demand outpaces incumbent logistics coverage. White-space targets include Brazilian middle-class households in São Paulo metro areas and Mexican residential developments bypassing traditional pay-TV infrastructure. Go-to-market through regional e-commerce platforms with local language interface customization outperforms retail channel dependency.
For Investors and Strategic Acquirers: Carve-out targets emerge from consumer electronics conglomerates divesting non-core streaming hardware divisions to focus on display panel manufacturing. Long-term viability hinges on cloud-native architecture transition enabling thin-client endpoint deployment. Monitor hospitality procurement standard consolidation around IP-based streaming architectures as the inflection signal for commercial-grade device demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Silicon Development | Apple's A-series chip integration reduces decoder dependency on MediaTek and Amlogic supply. |
| Hospitality PMS Integration | Marriott's IP-based room architecture mandates Ethernet-enabled devices with guest privacy controls. |
| Direct-to-Consumer Crowdfunding | Shenzhen OEMs bypass Flipkart and Amazon India distributor markups through owned-commerce pre-orders. |
| EU AI Act Compliance Investment | Algorithmic transparency documentation extends firmware development timelines for Roku and Google platforms. |
| Cloud-Native Architecture Transition | Remote GPU rendering reduces per-room hardware capex for Hilton and Hyatt multi-property deployments. |
Research Methodology
Operator-level perspectives from streaming platform engineering directors, hospitality procurement managers, semiconductor supply chain planners, and FCC regulatory affairs specialists anchored the qualitative base. Primary interview data combined with secondary validation from SEC filings of Amazon and Roku, BIS certification registries, EU AI Act implementation guidance documents, and Indian digital education initiative tender announcements. Bottom-up unit shipment modeling triangulated against top-down broadband penetration forecasts across the analysis window.
Scenario-bracketing framed volume and value outputs across product type, connectivity technology, end-user application, and regional regulatory cluster dimensions. CAGRs derived from installed base replacement cycle analysis and subscription service attach rate elasticity modeling. Industry-specific inputs included ARM foundry capacity utilization rates and hospitality property management system integration complexity indices.
Sensitivities concentrate around FCC spectrum reallocation timing, Taiwan semiconductor foundry capacity constraints, and EU AI Act enforcement intensity variations. Forecasts reflect documented assumptions regarding broadband infrastructure buildout pace and streaming service pricing evolution. Cross-checking against Ookla broadband speed test deployment data and Netflix subscriber regional breakdowns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Indonesia Digital Media Market
Digital Media
Cognitive Media Market
Digital Media
In Flight Entertainment Market
Digital Media
APAC Media and Entertainment Market
Digital Media
South Korea Webtoons Market
Digital Media
Webtoons Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Professional Dubbing Services Market
Digital Media
Anime Merchandising Market
Digital Media
US Automatic Content Recognition Market
Digital Media
4K Content Market
Digital Media
Manga Market
Digital Media
Stock Photography Market
Digital Media
Volumetric Video Market
Digital Media
Mobile Entertainment Market
Digital Media
Wedding Photography Market