
 Asia-Pacific (APAC) Media and Entertainment Market | 2026-2036
Asia-Pacific (APAC) Media and Entertainment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific (APAC) Media and Entertainment Market Outlook
Cloud-native content delivery is fragmenting legacy broadcast architectures across APAC. Tencent Holdings Ltd. anchors massive multiplayer infrastructure and in-house production pipelines. Netflix Inc. competes through localized original content slates and regional licensing flexibility. Sony Group Corporation dominates premium gaming hardware and IP-driven transmedia franchises spanning film, music, and interactive entertainment.
Asia-Pacific media and entertainment encompasses the creation, aggregation, and monetization of audiovisual content through digital platforms, broadcast networks, and live experiences, with streaming bitrates now routinely exceeding 25 Mbps for 4K HDR delivery and sub-50ms latency requirements defining cloud gaming service tiers. Streaming Services command the largest revenue pool as broadband penetration and 5G rollout deepen addressable audiences, while AI-driven Content represents the fastest-expanding technology segment as automated localization, generative production tools, and algorithmic recommendation engines reduce marginal content costs. Video Games sustain outsized growth through free-to-play monetization models and esports tournament ecosystems that convert engagement into advertising and sponsorship inventory.
TRAI in India mandates content certification and interconnection transparency for OTT platforms, while MIIT in China enforces data localization and real-name verification for interactive services. EMA-equivalent frameworks across Southeast Asian jurisdictions are harmonizing cross-border content licensing standards. Stakeholders must monitor regulatory divergence between data sovereignty regimes and emerging AI content disclosure requirements as they allocate capital across production, distribution, and technology layers.
Market Dynamics
Cloud gaming infrastructure is collapsing the distinction between content production and distribution in APAC, forcing studios to rebuild workflows around sub-50ms latency requirements and real-time rendering pipelines rather than traditional post-production timelines.
Growth Catalysts
- 5G network densification:South Korea's three mobile carriers have deployed over 200,000 base stations, enabling 4K HDR streaming at 25 Mbps without buffering. This infrastructure pull is expanding addressable audiences for interactive entertainment.
- TRAI's OTT certification framework:India's interconnection transparency mandates reduce friction between platforms and ISPs, lowering distribution costs for regional content aggregators entering tier-2 and tier-3 cities.
- Webtoon-to-drama adaptation pipelines:South Korean studios now monetize IP across six format layers simultaneously, from vertical-scroll mobile comics to theatrical releases and merchandise licensing.
Market Restraints
- Graphics processing unit supply concentration:Cloud gaming datacenter expansion depends on TSMC's 4nm and 3nm foundry allocation, creating 18-24 month deployment lags for regional operators.
- MIIT data localization requirements:China's real-name verification and cross-border data transfer restrictions force foreign platforms to maintain entirely separate technical stacks, doubling infrastructure capex.
- Free-to-play monetization ceiling:Southeast Asian markets exhibit lower average revenue per user than Northeast Asian benchmarks, compressing margin recovery timelines for Western publishers.
Strategic Opportunities
- Vietnam's underpenetrated esports ecosystem:Mobile Legends and PUBG Mobile tournaments draw 40 million monthly active players without dedicated arena infrastructure, creating venue development white space.
- AI-driven automated dubbing:Lip-sync neural networks reduce localization costs for Japanese anime exports into Bahasa Indonesia and Thai, opening catalog monetization for backlist titles.
- India's PLI scheme for animation and VFX:Production-linked incentives covering 30% of eligible expenditure are attracting international co-productions to Mumbai and Hyderabad studios.
Industry Challenges
- Real-time engine programming talent scarcity:Unreal Engine 5 and Unity expertise concentrates in Tokyo, Seoul, and Shanghai, forcing regional studios to compete for the same limited contractor pool.
- Cross-border IP licensing complexity:Music synchronization rights for user-generated content platforms require separate negotiations across ten-plus APAC jurisdictions, delaying product launches.
- Legacy broadcast integration friction:Indonesian and Philippine free-to-air networks still rely on satellite distribution, creating technical mismatches with cloud-native ad insertion and dynamic content substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific (APAC) Media and Entertainment Market |
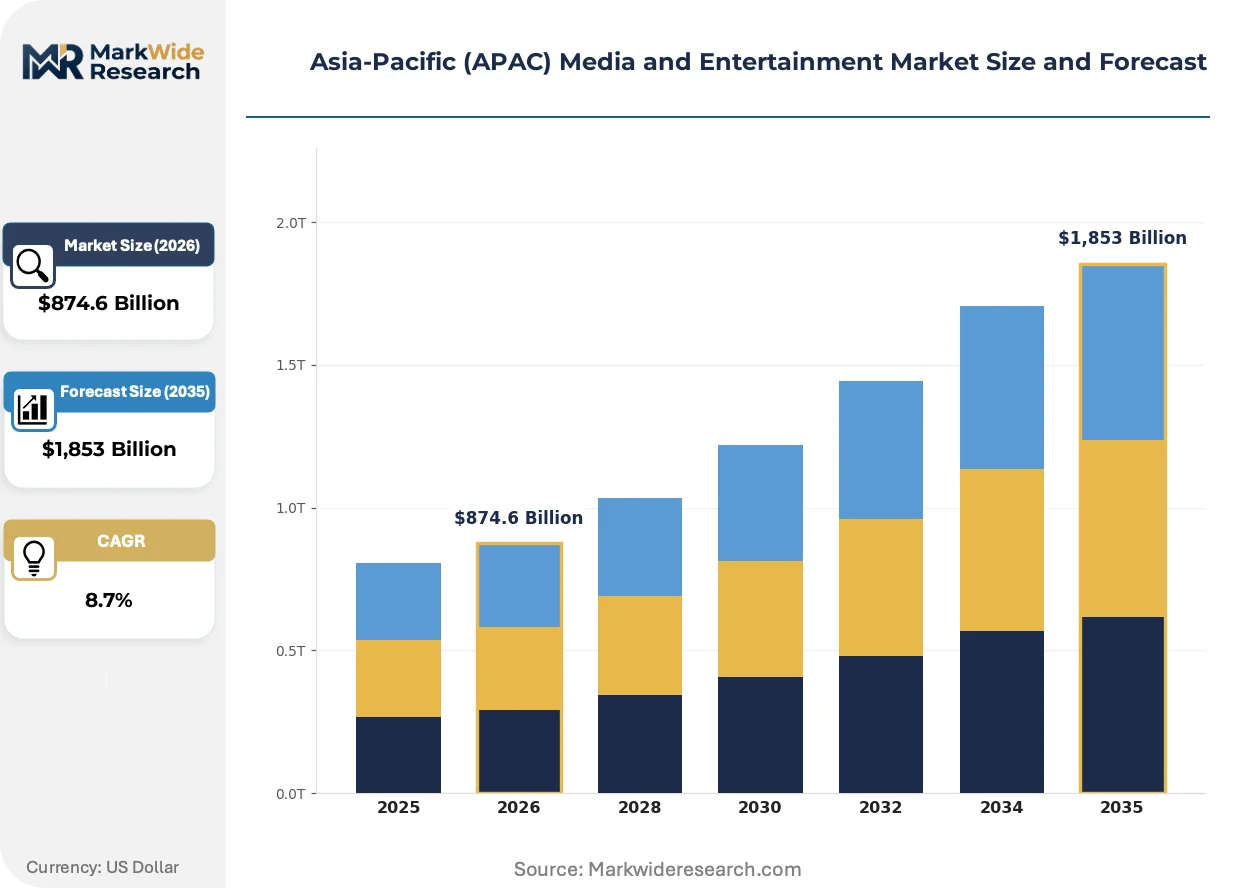
| Market Size in 2026 | $874.6 Billion |
| Market Size in 2035 | $1,853 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaming Services, Video Games, Music Production, Digital Advertising Technology: Virtual Reality, Augmented Reality, Blockchain, AI-driven Content End User: Consumers, Advertisers, Content Creators, Media Companies Distribution Channel: Online Platforms, Mobile Apps, Cable Services, Cinemas |
| Companies Covered | Alibaba Group Holding Ltd., Netflix Inc., Tencent Holdings Ltd., China Central Television (CCTV), Zee Entertainment Enterprises Limited, Sony Group Corporation, CJ ENM Co. Ltd., Kakao Entertainment Corp., The Walt Disney Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific (APAC) Media and Entertainment Market Strategic Shifts
Generative production tools are compressing content creation cycles across APAC, enabling studios to produce localized variants from single master assets rather than parallel production runs.
Edge computing nodes deployed at 5G base stations are collapsing the distance between rendering hardware and end-user devices. Mobile-first publishers in Jakarta and Manila now stream console-quality graphics to mid-tier smartphones without local processing overhead. This architecture shift eliminates the hardware upgrade cycle as a growth constraint, expanding addressable audiences to 3G-to-4G transition markets previously excluded from premium gaming.
MIIT's cloud gaming infrastructure standards mandate interoperability between domestic platforms, preventing vendor lock-in through proprietary streaming protocols. The regulation forces Tencent, NetEase, and emerging competitors to adopt common latency measurement methodologies and cross-platform save state formats. Smaller studios benefit from reduced porting costs, while consumers gain subscription portability previously blocked by technical fragmentation.
Subscription fatigue among urban millennials is fragmenting entertainment budgets across five-plus specialized services rather than two or three generalist platforms. Korean consumers now maintain separate memberships for webtoons, music streaming, drama platforms, and esports content, each priced below 10,000 won monthly. This unbundling pressures aggregators to deepen vertical expertise rather than compete through catalog breadth alone.
Asia-Pacific (APAC) Media and Entertainment Market Segmentation
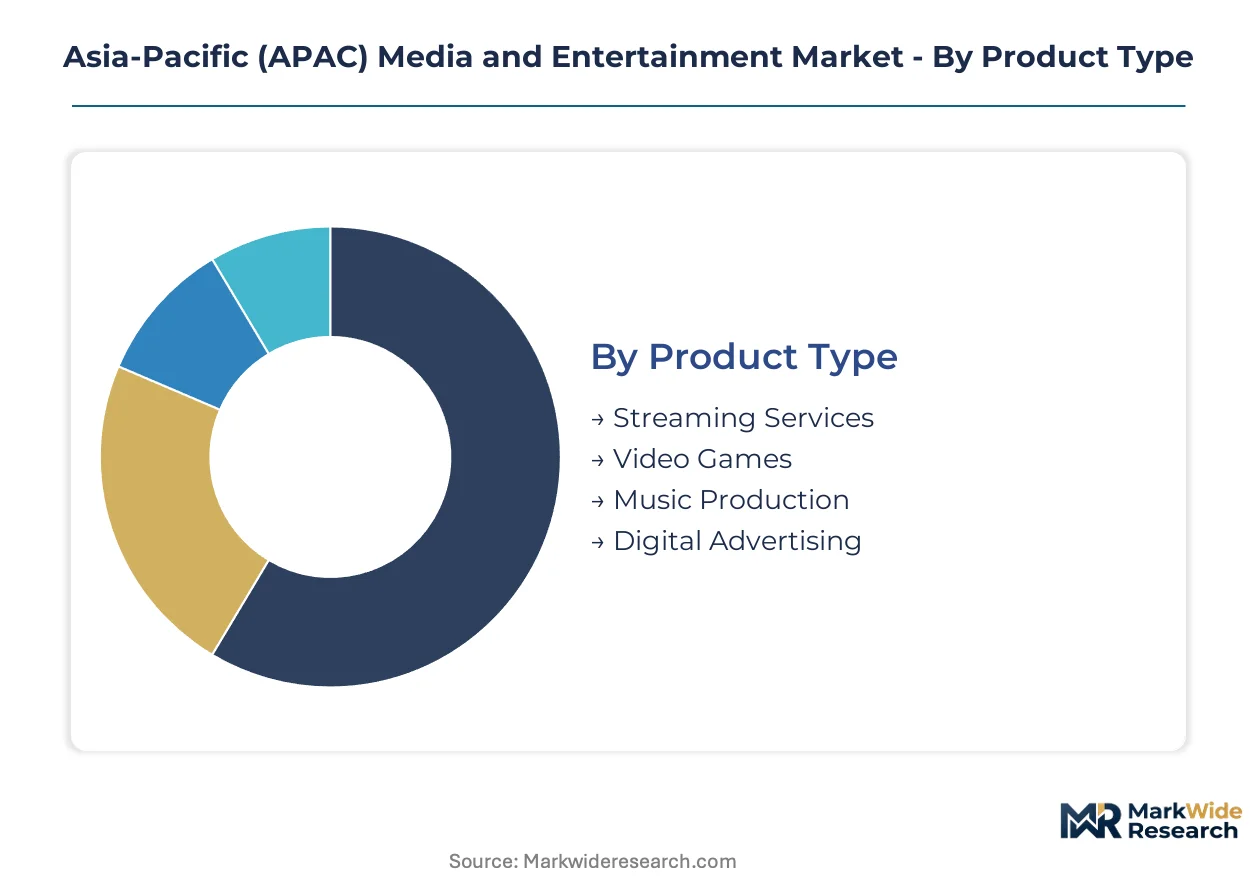
APAC media and entertainment segmentation reveals how technology adoption curves diverge across consumer bases and distribution architectures. Product type splits expose monetization model preferences, while technology layers distinguish infrastructure-dependent from content-native revenue streams.
Product Type:
Cost tier stratification separates subscription-heavy formats from transaction-driven and advertising-supported alternatives across the region.
- Streaming Services:Subscription video-on-demand platforms deliver 4K HDR content at 25 Mbps through broadband and 5G networks. South Korean and Australian markets concentrate demand for premium tier offerings with simultaneous theatrical windowing.
- Video Games:Free-to-play mobile titles dominate Southeast Asian engagement, converting user attention into advertising and in-app purchase revenue through gacha mechanics and battle pass systems.
- Music Production:Streaming royalties and sync licensing for K-pop and J-pop exports drive revenue concentration in Seoul and Tokyo production clusters.
- Digital Advertising:Programmatic insertion across connected TV and mobile video inventory captures brand budgets shifting from linear broadcast in India and Indonesia.
Streaming Services commands the established base. The steepest expansion runs through Video Games.
Technology:
Maturity gradients separate proven deployment layers from emerging infrastructure still seeking scaled commercial application.
- Virtual Reality:Location-based entertainment venues in Tokyo and Shanghai deploy tethered headsets for immersive cinema and gaming experiences requiring dedicated physical footprints.
- Augmented Reality:Mobile AR filters and interactive advertising overlays leverage existing smartphone penetration without hardware upgrade cycles.
- Blockchain:Non-fungible token marketplaces for digital collectibles and virtual real estate face regulatory uncertainty under China's SAMR and India's RBI frameworks.
- AI-driven Content:Automated localization pipelines reduce dubbing costs for anime and drama exports into Bahasa Indonesia and Thai, compressing production timelines from months to weeks.
AI-driven Content anchors near-term investment flows. Virtual Reality presents the longest path to mass adoption.
End User:
Customer type diversity shapes platform design requirements and monetization architecture decisions.
- Consumers:Individual subscribers and gamers generate recurring revenue through monthly membership fees and microtransaction spending across mobile and console platforms.
- Advertisers:Brand marketers and performance advertisers purchase inventory through programmatic exchanges and direct publisher deals, targeting demographic segments with addressable precision.
- Content Creators:Independent producers and influencer networks distribute through algorithmic recommendation systems, earning revenue shares from platform monetization programs.
- Media Companies:Traditional broadcasters and studio conglomerates license IP across windowing tiers, managing rights portfolios across theatrical, streaming, and merchandise exploitation.
Consumers provide the volume foundation. Content Creators exhibit the fastest user base expansion.
Distribution Channel:
Geographic penetration patterns determine which channels dominate specific national markets based on infrastructure maturity.
- Online Platforms:Browser-based streaming and gaming services reach desktop users in broadband-saturated markets like South Korea and Japan with minimal friction.
- Mobile Apps:Native iOS and Android applications capture Southeast Asian audiences where smartphones serve as primary internet access devices.
- Cable Services:Legacy pay-TV operators in Australia and Singapore retain sports rights bundles that streaming competitors have not fully displaced.
- Cinemas:Theatrical exhibition concentrates in urban India and China's tier-1 cities, with premium formats commanding ticket price premiums for franchise releases.
Mobile Apps dominate addressable reach. Online Platforms capture the highest revenue per user.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean content exports to Southeast Asian streaming platforms now constitute the dominant trade-flow corridor in APAC media consumption. Japanese anime licensing to Indian OTT platforms represents a secondary but expanding channel. Australian sports rights feed into regional betting and fantasy gaming ecosystems.
South Korea
Seoul-based CJ ENM and Kakao Entertainment drive webtoon-to-drama adaptation pipelines across six format layers simultaneously. The Korea Communications Commission enforces platform transparency mandates for content recommendation algorithms. Busan's film production clusters now handle international co-productions leveraging the country's 30% cash rebate scheme.
China
MIIT cloud gaming infrastructure standards force interoperability between Tencent, NetEase, and emerging domestic platforms. Real-name verification and data localization requirements double infrastructure capex for foreign entrants. Shanghai's Yangpu District anchors the country's largest esports tournament venue cluster with dedicated 5G edge computing nodes.
India
TRAI's OTT certification framework reduces interconnection friction between platforms and ISPs, enabling tier-2 and tier-3 city expansion. The PLI scheme for animation and VFX covers 30% of eligible expenditure, attracting international co-productions to Mumbai and Hyderabad studios. Zee Entertainment's domestic content aggregation dominates regional language markets.
Japan
Tokyo's anime production houses license backlist catalogs into Bahasa Indonesia and Thai through AI-driven automated dubbing pipelines. METI supports content export through JETRO trade facilitation programs. Osaka's gaming development clusters concentrate Unreal Engine 5 expertise for regional publishers seeking technical partnerships.
Australia
Legacy pay-TV operators retain sports rights bundles that streaming competitors have not fully displaced. The Australian Competition and Consumer Commission monitors platform market power in digital advertising. Sydney's production infrastructure serves as a regional hub for international streaming original slates targeting English-language APAC audiences.
Asia-Pacific (APAC) Media and Entertainment Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent monetization architectures. The market structure fragments vertically, with platform aggregators, IP originators, and infrastructure operators occupying non-overlapping competitive spaces. Three archetypes dominate: state-affiliated broadcasters with regulatory capture advantages, technology conglomerates with captive cloud infrastructure, and content studios with transmedia IP pipelines. Competitive moves concentrate on exclusive licensing windows and regional production facility expansion.
Within the technology conglomerate tier, Tencent Holdings Ltd. and Alibaba Group Holding Ltd. exemplify platform-scale operators with integrated cloud gaming and content distribution stacks. Sony Group Corporation occupies a position bridging premium hardware manufacturing and IP-driven entertainment franchises. Netflix Inc. and The Walt Disney Company represent foreign entrants competing through localized original content slates and regional licensing flexibility rather than infrastructure ownership.
| Leading Market Players |
|---|
| Alibaba Group Holding Ltd. |
| Netflix Inc. |
| Tencent Holdings Ltd. |
| China Central Television (CCTV) |
| Zee Entertainment Enterprises Limited |
| Sony Group Corporation |
| CJ ENM Co. Ltd. |
| Kakao Entertainment Corp. |
| The Walt Disney Company |
| Others |
Value Chain & Pricing Dynamics
Seoul's esports production clusters and cloud rendering farms concentrate capacity for real-time content delivery, granting South Korean operators pricing power over Southeast Asian distributors seeking low-latency tournament feeds and localized drama adaptations. This geographic concentration lets domestic studios command premium licensing terms while tier-2 cities in Vietnam and Indonesia absorb cost-plus markups for infrastructure-dependent services.
Pricing Analysis
Current-generation 4K HDR streaming at 25 Mbps commands subscription premiums over prior-generation HD tiers, while next-generation cloud gaming services with sub-50ms latency are testing usage-based metering. Three-tier pricing structure across premium, standard, and economy levels separates simultaneous theatrical windowing from delayed streaming and ad-supported catalogs. Pricing pressure stems from free-to-play monetization ceilings in Southeast Asian markets where average revenue per user trails Northeast Asian benchmarks. Mobile-first gamers in Jakarta and Manila exhibit highest price sensitivity, while South Korean drama enthusiasts maintain lowest sensitivity due to webtoon-to-drama franchise loyalty.
Supply Chain Analysis
Upstream semiconductor feedstock for graphics rendering and edge computing hardware draws from Taiwan, South Korea, and Japan, with TSMC's 4nm and 3nm foundry allocation serving as the critical chokepoint for cloud gaming datacenter expansion. Content production pipelines hinge on specialized inputs including motion capture systems, AI-driven dubbing software, and real-time engine licenses from Unreal Engine and Unity developers. Single-source vulnerability concentrates in TSMC's advanced node capacity, creating 18-24 month deployment lags for regional operators. Distribution runs through mobile app stores and direct-to-consumer platforms, bypassing legacy satellite and cable intermediaries in broadband-saturated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific media and entertainment functions as a service-attach opportunity where cloud gaming subscriptions, automated localization services, and esports tournament management layers expand faster than hardware sales. Recurring revenue from algorithmic content recommendation and dynamic ad insertion outpaces growth in physical production equipment.
For Market Incumbents: Insulate premium IP pipelines through exclusive webtoon-to-drama adaptation rights and captive cloud infrastructure investments in Seoul and Shanghai. Defensive consolidation should target AI-driven dubbing specialists in Tokyo to lock automated localization capabilities before regulatory disclosure requirements fragment technical standards. Threat vectors include MIIT interoperability mandates eroding proprietary protocol advantages and emerging Vietnamese studios undercutting regional production costs. For New Entrants and Emerging Players: Mid-market esports venue development in Ho Chi Minh City and Manila represents the most penetrable entry point, given 40 million monthly active mobile tournament players without dedicated arena infrastructure. White-space targets include AI-powered lip-sync neural networks for Bahasa Indonesia and Thai anime localization, plus India's PLI-subsidized animation co-productions in Mumbai and Hyderabad. Go-to-market positioning should emphasize subscription portability under MIIT's cross-platform save state requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory arbitrage play because data sovereignty regimes and AI content disclosure requirements are fragmenting technical stacks faster than incumbents can consolidate. Acquisition targets should concentrate on studios with transmedia IP pipelines spanning six format layers and established regulatory compliance in multiple APAC jurisdictions. The signal to watch is TRAI's expansion of OTT certification mandates into tier-2 and tier-3 Indian cities, which would validate infrastructure-light distribution models.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Gaming Infrastructure Partnership | MIIT interoperability standards force Tencent and NetEase into shared latency protocols, reducing vendor lock-in. |
| AI-Driven Localization Acquisition | Tokyo-based lip-sync neural networks cut anime dubbing timelines from months to weeks for Southeast Asian markets. |
| Esports Venue Development | Vietnam's 40 million mobile tournament players lack dedicated arena infrastructure, creating first-mover advantages. |
| PLI-Subsidized Co-Production | India's 30% animation and VFX incentives attract international studios to Mumbai and Hyderabad clusters. |
| Webtoon IP Pipeline Expansion | CJ ENM and Kakao Entertainment monetize vertical-scroll comics across six simultaneous format layers. |
Study Parameters
Cross-validation between platform subscriber disclosures and regulatory filing data anchors the qualitative findings across the analysis window. Primary interviews with content licensing directors, cloud infrastructure engineers, TRAI and MIIT regulatory affairs leads, and esports tournament operators combined with secondary validation from SEC filings, Korean Communications Commission transparency reports, and JETRO trade facilitation databases. Bottom-up subscriber and revenue modeling triangulates against top-down addressable market calculations for broadband and 5G penetration tiers.
Calibration against historical adoption curves for streaming services and free-to-play gaming monetization shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology layer, end user archetype, and distribution channel, with additional granularity on regulatory framework clusters distinguishing data sovereignty regimes. CAGRs derive from fitted growth curves adjusted for infrastructure deployment timelines and content localization velocity. Industry-specific inputs encompass 5G base station densification rates and PLI scheme uptake in Indian animation production.
Macroeconomic conditions sit as an overlay; deviation in regional currency volatility, semiconductor foundry allocation cycles, or cross-border data transfer restrictions would shift the trajectory. Forecasts reflect documented assumptions about infrastructure buildout pace and regulatory harmonization progress. Cross-checking against IEA broadband penetration benchmarks and GSMA mobile connectivity data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Webtoons Market
Digital Media
Stock Music Software Market
Digital Media
Entertainment Market
Digital Media
Europe Anime Merchandising Market
Digital Media
Asia-Pacific Animation Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
Drone Wedding Photography Market
Digital Media
Digital Content Creation Market
Digital Media
Playout Solutions Market
Digital Media
United States Sports Betting Market
Digital Media
Social TV Market
Digital Media
Adult Entertainment Market
Digital Media
Indonesia Digital Media Market
Digital Media
APAC DOOH Market
Digital Media
Online Entertainment Market