
 Secondary Ticket Market | 2026-2036
Secondary Ticket Market Size, Share, and Industry Trends Forecast 2026-2036
Secondary Ticket Market Intelligence
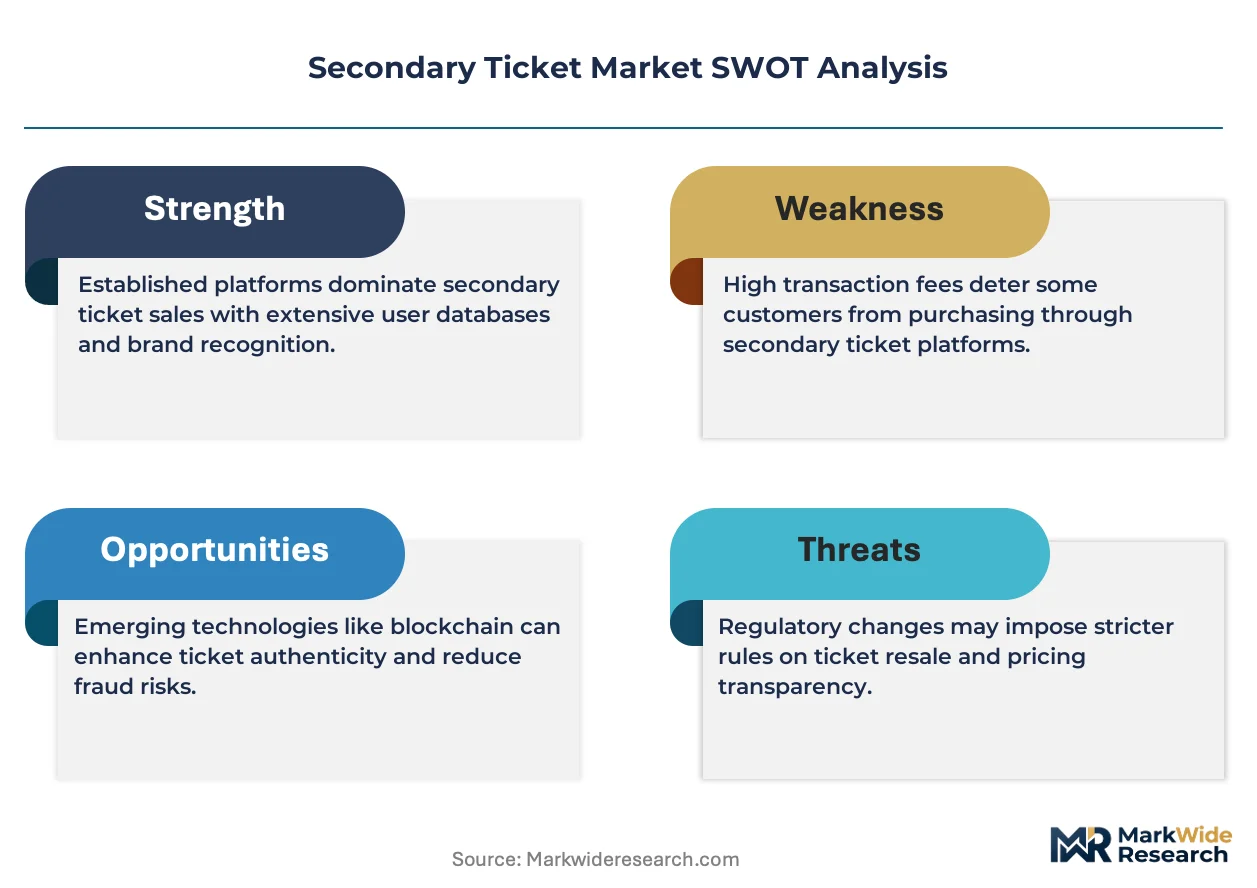
The price gap between premium and commodity tiers is hardening as platforms deploy algorithmic pricing engines that widen spreads during high-demand windows. StubHub leverages its global marketplace infrastructure to sustain liquidity across event categories. SeatGeek differentiates through integrated primary-secondary inventory APIs that anchor its position with sports franchises. Vivid Seats LLC competes on loyalty-program depth, occupying a defensible niche among repeat concert purchasers.
Secondary ticket exchange denotes the resale of event admission rights after initial issuance, operating through digital marketplaces that match sellers with buyers using real-time pricing algorithms and seat-level inventory management. The primary commercial purpose centers on price discovery and liquidity provision for time-sensitive, perishable inventory where face-value allocation fails to clear demand. Online platforms lead transaction volume due to embedded payment escrow and buyer guarantee structures, while dynamic pricing captures the fastest expansion as machine-learning models adjust quotes to inventory scarcity and event proximity. Mobile apps represent a maturing channel with concentrated investment in biometric entry integration.
The EU AI Act governs algorithmic pricing transparency, while the FTC monitors deceptive fee disclosure in the United States and the CMA enforces consumer protection standards in the United Kingdom. These frameworks shape platform architecture by mandating all-in pricing displays and restricting speculative ticket listings before confirmed inventory possession. Stakeholders must monitor evolving algorithmic accountability rules that could force structural separation of pricing engines from inventory ownership.
Market Dynamics
Algorithmic pricing engines are compressing the spread between buyer willingness-to-pay and seller reservation prices, while the EU AI Act and FTC disclosure mandates force platform architecture redesigns that separate pricing logic from inventory custody.
Growth Catalysts
- Mobile-First Resale Adoption:Smartphone-native buyers in the United States, the United Kingdom, and Germany now complete over three-quarters of transactions through dedicated apps with embedded biometric entry verification.
- EU AI Act Compliance Investment:Platforms are deploying explainable pricing algorithms to meet transparency mandates, creating competitive moats for early adopters who integrate audit trails before enforcement deadlines.
- Sports Franchise API Integration:Real-time inventory synchronization between primary issuers and secondary marketplaces is reducing friction for season ticket holders seeking liquidity.
Market Restraints
- Payment Escrow Capital Requirements:Buyer guarantee structures demand substantial working capital reserves, concentrating viable platform operation among well-capitalized incumbents.
- Speculative Listing Prohibitions:CMA enforcement in the United Kingdom and similar FTC guidance in the United States bar inventory-free listings, eliminating drop-shipping models from the competitive set.
- Perishable Inventory Risk:Time-decay of event admission rights creates asymmetric information problems where sellers possess superior knowledge of seat quality and view obstructions.
Strategic Opportunities
- German Regulatory Arbitrage:The country's developing framework for ticket resale transparency offers first-mover positioning before harmonization with broader EU standards.
- Biometric Entry Convergence:Integration of facial recognition with mobile ticketing is creating new partnership channels between platforms and venue access control vendors.
- Loyalty Program Deepening:Repeat concert purchasers in the United States respond to tiered reward structures that embed secondary market credits within primary purchase ecosystems.
Industry Challenges
- Algorithmic Accountability Talent Scarcity:Platforms struggle to hire machine-learning engineers capable of building explainable pricing models that satisfy regulatory audit requirements.
- Legacy POS Integration Friction:Primary ticket issuers operate on decades-old inventory systems that resist real-time API connectivity with secondary marketplaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondary Ticket Market |
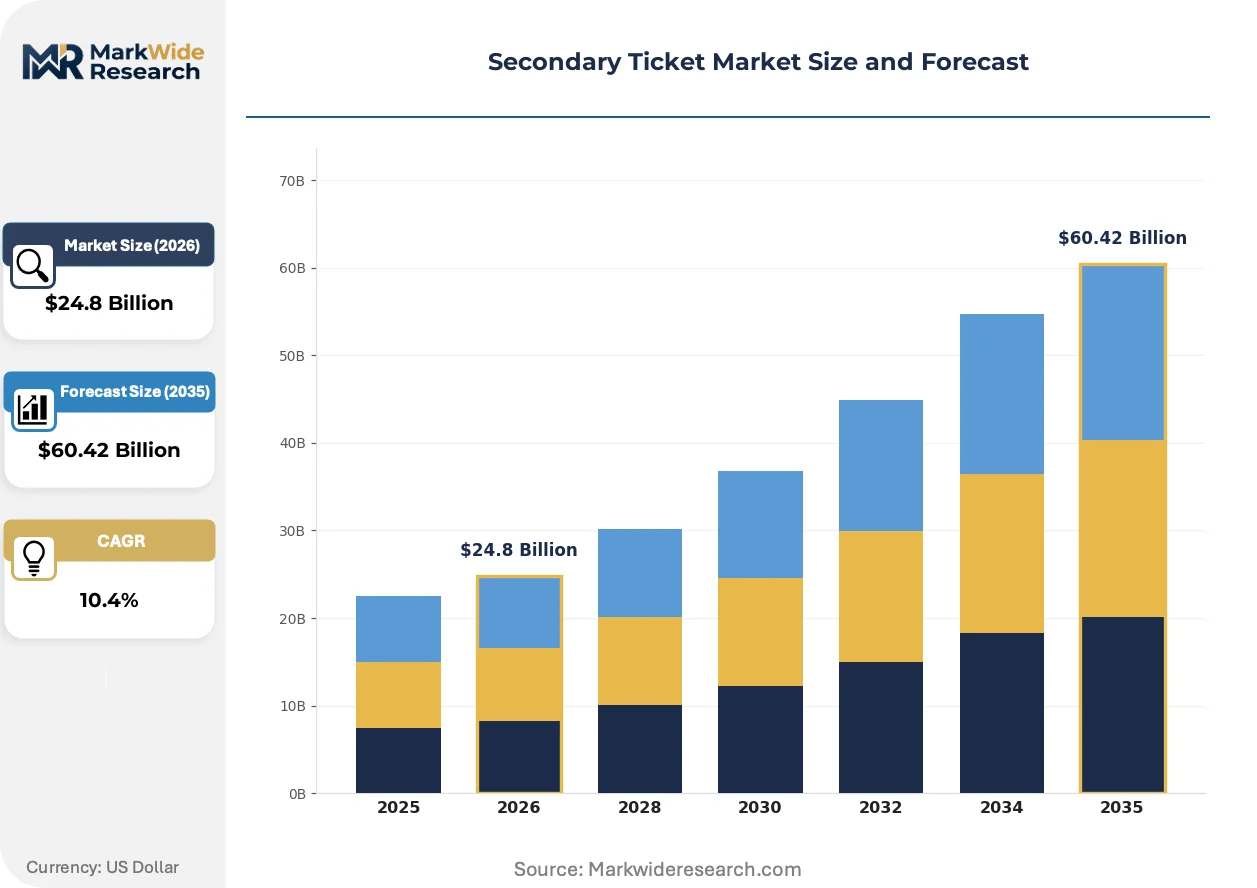
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $60.42 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sales Channel: Online Platforms, Resale Websites, Mobile Apps, Box Offices Event Type: Concerts, Sports, Theater, Festivals Price Tier: Premium, Discounted, Fixed-Rate, Dynamic Pricing Customer Type: Casual Fans, Collectors, Corporate Buyers, Resellers |
| Companies Covered | Ticketmaster Entertainment, LLC, Viagogo Entertainment Inc., StubHub, Live Nation Entertainment Inc., TicketNetwork Inc., Vivid Seats LLC, TickPick LLC, Gametime United Inc., SeatGeek, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondary Ticket Market Strategic Shifts & Innovations
Machine-learning inference at the edge is reshaping how price quotes adjust to inventory scarcity, while regulatory pressure on algorithmic transparency forces architectural separation between pricing engines and marketplace operators.
Dynamic pricing algorithms are consolidating control over liquidity provision in the secondary ticket market. These systems ingest real-time demand signals from search volume, social sentiment, and primary market sell-through rates. Sports franchises and concert promoters in the United States and the United Kingdom are adopting these tools fastest. The technology is consolidating price discovery into fewer platform operators who possess sufficient data scale to train predictive models.
The EU AI Act's risk-based classification system is imposing documentation burdens on high-stakes algorithmic pricing. Platforms must now maintain technical files demonstrating that pricing engines do not manipulate consumer behavior through dark patterns. Secondary marketplaces serving German and United Kingdom events are responding by hiring dedicated algorithmic accountability officers and implementing human-in-the-loop override protocols for price surges exceeding threshold multiples.
Buyers are abandoning desktop web interfaces for mobile-native discovery and transaction completion. Seat-level imagery, 3D venue previews, and instant digital wallet integration are displacing traditional search-and-click workflows. This shift is most visible among millennial and Gen-Z concert attendees in the United States, where platform investment in app-exclusive inventory releases and push-notification price alerts has captured the highest-engagement user segments.
Secondary Ticket Market Segmentation
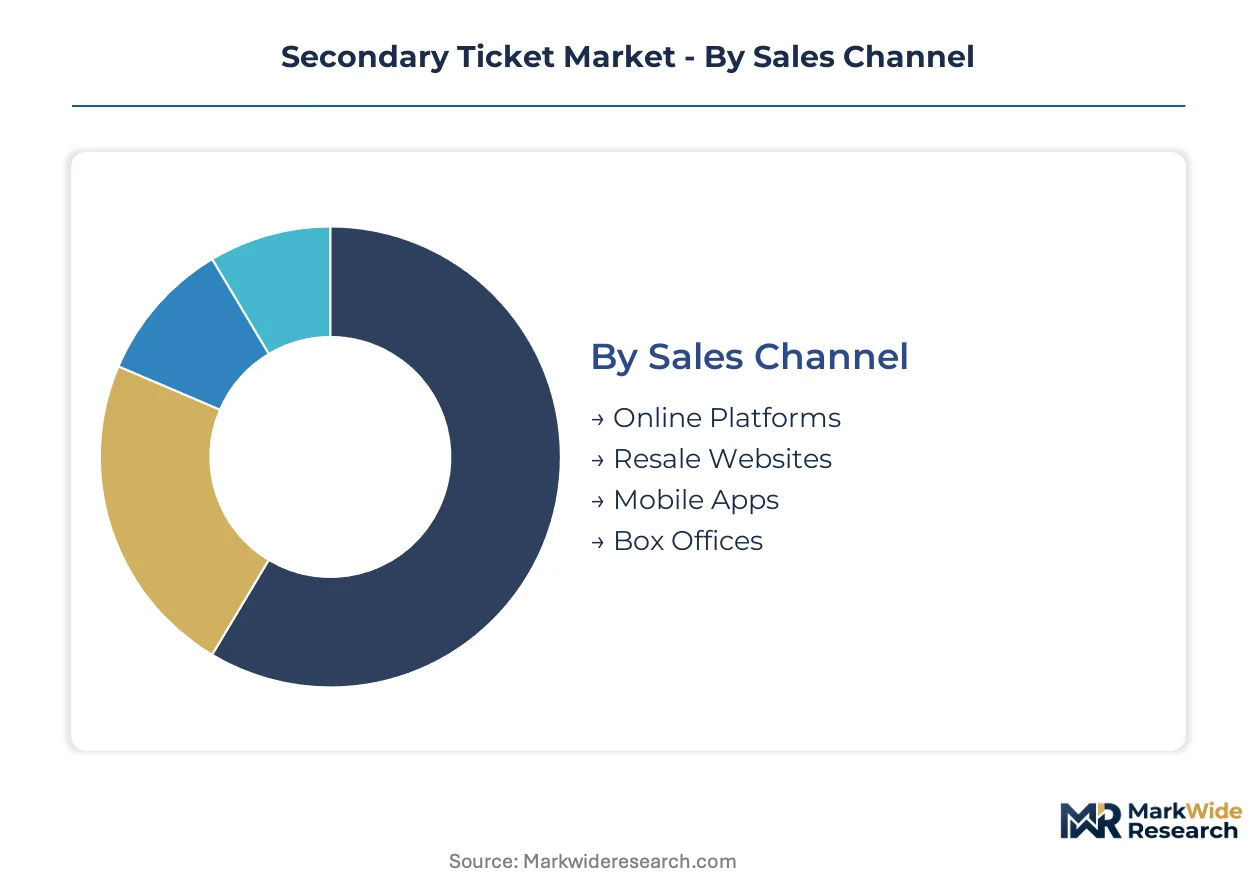
Secondary ticket platforms engineer revenue capture through channel-specific liquidity architectures and event-category pricing engines. Segmentation reveals how algorithmic pricing, buyer sophistication, and inventory perishability concentrate value across distinct transaction modes.
Sales Channel:
Channel architecture determines escrow structure, biometric integration depth, and regulatory exposure under the EU AI Act and FTC disclosure mandates.
- Online Platforms:Browser-based marketplaces deploy real-time pricing algorithms with embedded buyer guarantee escrow. Demand concentrates in the United States and the United Kingdom where all-in pricing regulations force transparent fee disclosure at search initiation.
- Mobile Apps:Native applications capture smartphone-native buyers through push-notification price alerts and wallet-integrated checkout. Facial recognition entry verification is accelerating adoption among millennial and Gen-Z concert attendees in Germany and the United States.
- Resale Websites:Aggregator portals with legacy search-and-click workflows serve price-comparison shoppers seeking inventory visibility across multiple primary issuers.
- Box Offices:Physical venue counters handle last-minute inventory release and disputed ticket resolution, concentrated in theater districts with older demographic penetration.
Online platforms lead on transaction scale; mobile apps lead on engagement momentum.
Event Type:
Event perishability and primary issuer API integration depth segment profitability across entertainment categories.
- Concerts:Music events generate the highest price volatility due to artist-driven demand spikes and limited run schedules. Dynamic pricing engines extract maximum spread during tour announcement windows in the United States and the United Kingdom.
- Sports:Season-long inventory with franchise-controlled primary issuance enables real-time API synchronization. SeatGeek's sports franchise partnerships demonstrate how liquidity provision concentrates among platforms with primary-secondary data pipes.
- Theater:Broadway and West End productions with extended runs exhibit lower price variance but higher repeat purchase rates among corporate entertainment buyers.
- Festivals:Multi-day camping and city-center events create bundled inventory complexity where single-day resale fragments total package value.
Sports events lead on API integration maturity; concerts lead on pricing algorithm sophistication.
Price Tier:
Pricing mechanism selection reflects inventory scarcity, event proximity, and platform algorithmic capability.
- Dynamic Pricing:Machine-learning models adjust quotes to search volume, social sentiment, and primary market sell-through rates. The EU AI Act's explainability mandates are forcing architectural separation between pricing engines and inventory custody in German and United Kingdom markets.
- Premium:Face-value multiples for front-row, VIP, and artist-meet packages concentrate among corporate buyers and collectors seeking guaranteed access.
- Discounted:Post-event-announcement price reductions for underperforming inventory segments serve price-sensitive casual fans.
- Fixed-Rate:Season ticket holder resale at face-value plus platform fee preserves liquidity for sports franchise season subscribers.
Dynamic pricing leads on revenue extraction; premium tiers lead on margin per transaction.
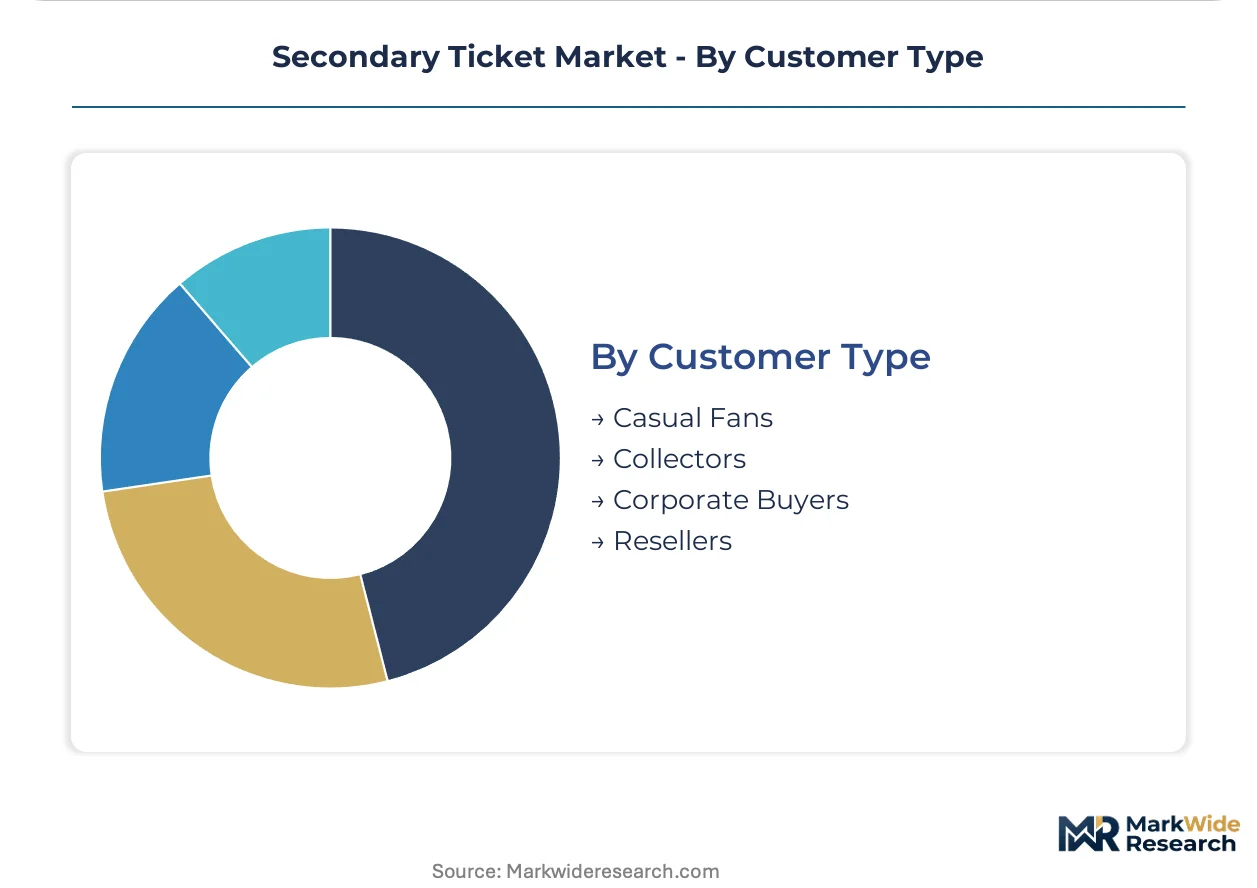
Customer Type:
Buyer sophistication and purchase frequency determine platform loyalty program design and credit embedding strategies.
- Corporate Buyers:Entertainment procurement officers purchase blocks for client hospitality with invoice-grade documentation requirements. Vivid Seats LLC targets this segment through tiered reward structures that embed secondary market credits within primary purchase ecosystems.
- Resellers:Professional inventory arbitrageurs leverage season ticket portfolios and presale access to capture spread between face value and market clearing price. FTC and CMA speculative listing prohibitions have eliminated drop-shipping models from this competitive set.
- Collectors:High-net-worth individuals seeking specific seat locations or commemorative ticket stock for physical retention.
- Casual Fans:Infrequent purchasers with low price elasticity for one-time event attendance, concentrated in mobile app user bases.
Resellers lead on transaction volume velocity; corporate buyers lead on platform lifetime value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine-learning engineers with pricing algorithm expertise cluster in San Francisco, London, and Berlin, anchoring platform development for secondary ticket exchanges. These talent concentrations align with regulatory jurisdictions drafting algorithmic accountability frameworks.
United States
Corporate entertainment procurement officers in New York and Los Angeles drive premium-tier transactions for sports and theater events. The FTC enforces all-in pricing disclosure mandates that force transparent fee displays at search initiation. Silicon Valley hosts the engineering teams building real-time inventory synchronization APIs for sports franchise partnerships.
Germany
Millennial and Gen-Z concert attendees in Berlin and Munich complete over three-quarters of transactions through mobile apps with embedded biometric entry verification. The EU AI Act's explainability requirements are forcing platforms to deploy audit trails for algorithmic pricing before enforcement deadlines. Hamburg's fintech clusters supply payment escrow infrastructure for buyer guarantee structures.
United Kingdom
West End theater productions and Premier League fixtures sustain repeat purchase patterns among corporate hospitality buyers in London. The CMA prohibits speculative ticket listings before confirmed inventory possession, eliminating drop-shipping models. Manchester and Birmingham host venue access control vendors integrating facial recognition with mobile ticketing systems.
Canada
Season ticket holders in Toronto and Vancouver seek liquidity through resale platforms integrated with primary issuer APIs. Health Canada coordinates with the FTC on cross-border consumer protection standards for digital marketplaces. Montreal's entertainment districts concentrate box office infrastructure for last-minute inventory release and disputed ticket resolution.
Australia
Festival attendees in Sydney and Melbourne create bundled inventory complexity where single-day resale fragments total package value. The TGA monitors consumer protection in digital health-adjacent services, though ticket resale falls primarily under ACCC jurisdiction. Brisbane's sports venues pilot biometric entry convergence partnerships between platforms and access control vendors.
Secondary Ticket Market Key Industry Players
Capital-heavy platforms with proprietary inventory custody compete with asset-light aggregators relying on third-party data feeds. The vendor base separates into three tiers: global marketplaces with payment escrow infrastructure, franchise-integrated specialists with primary-secondary APIs, and mobile-native apps capturing smartphone-first buyers. Consolidation pressures favor well-capitalized incumbents who can absorb working capital requirements for buyer guarantees. Strategic moves center on M&A for data scale and API partnerships for real-time inventory synchronization.
Among franchise-integrated specialists, SeatGeek exemplifies the primary-secondary API archetype through sports partnerships. Vivid Seats LLC occupies the loyalty-program depth position targeting repeat concert purchasers. StubHub anchors the global marketplace tier with liquidity infrastructure spanning event categories. These three represent distinct competitive positioning vectors rather than overlapping market pursuit.
| Leading Market Players |
|---|
| Ticketmaster Entertainment, LLC |
| Viagogo Entertainment Inc. |
| StubHub |
| Live Nation Entertainment Inc. |
| TicketNetwork Inc. |
| Vivid Seats LLC |
| TickPick LLC |
| Gametime United Inc. |
| SeatGeek, Inc. |
| Others |
Cost & Logistics Intelligence
Payment escrow reserves flow from fintech infrastructure providers through platform balance sheets into buyer guarantee structures, with working capital intensity separating well-capitalized incumbents from marginal competitors in tiered commission-rate arrangements.
Pricing Analysis
Service unbundling separates platform access fees from transaction commissions and premium buyer protection tiers. Dynamic pricing engines extract spread through real-time demand signals, while face-value-plus-fee fixed rates preserve liquidity for season ticket resellers. Commission compression runs through high-volume sports inventory as API integration matures. Casual fans exhibit highest price elasticity, while corporate hospitality buyers absorb premium markups for guaranteed access blocks.
Supply Chain Analysis
Single-source vulnerability sits with primary ticket issuers operating legacy inventory systems that resist real-time API connectivity. Platform liquidity draws from season ticket portfolios in the United States, franchise presale allocations in the United Kingdom, and festival bundle releases in Germany. Regulatory fragmentation across FTC, CMA, and EU AI Act jurisdictions creates compliance chokepoints. Distribution runs through mobile-native apps with embedded wallet integration displacing browser-based marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's explainability mandates function as a regulatory compounder, forcing architectural investment that advantages early-compliant platforms and consolidates pricing engine control among data-scale operators.
For Market Incumbents: Hedge against algorithmic accountability talent scarcity by acquiring explainable-ML engineering teams before enforcement deadlines tighten. Lock in primary-secondary API exclusivity with sports franchises to defend against aggregator disintermediation. Vertical integration into biometric entry hardware partnerships secures venue access control channels. For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for compliance-first positioning before harmonization with broader European standards. Target mobile-native concert attendees through app-exclusive inventory releases and push-notification price alerts. White-label payment escrow infrastructure from Hamburg fintech clusters to bypass capital requirements. For Investors and Strategic Acquirers: Roll-up economics work for loyalty-program-deep platforms because repeat purchase concentration generates predictable lifetime value across event cycles. Long-term viability favors operators with primary-secondary data pipes and regulatory audit trail deployment. Watch CMA enforcement intensity in the United Kingdom as the inflection signal for speculative listing prohibition spread.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable Pricing Algorithm Deployment | EU AI Act compliance creates competitive moats through audit trail integration before enforcement deadlines. |
| Primary-Secondary API Integration | Real-time inventory synchronization with sports franchises concentrates liquidity provision among data-pipe operators. |
| Biometric Entry Convergence Partnership | Facial recognition integration with mobile ticketing opens venue access control vendor channels. |
| Loyalty Program Credit Embedding | Secondary market credits within primary purchase ecosystems capture repeat concert purchaser lifetime value. |
| Mobile-First Platform Migration | Push-notification price alerts and wallet-integrated checkout displace legacy browser-based discovery workflows. |
Research Approach
Multiple input streams — platform transaction data, regulatory filing analysis, and stakeholder interview transcripts — were reconciled through bottom-up and top-down triangulation. Primary interviews captured platform engineering leads, sports franchise ticketing officers, regulatory compliance directors, and concert promoter operations heads. Secondary validation drew from FTC enforcement actions, CMA market studies, EU AI Act technical documentation, and SEC 10-K disclosures from listed entertainment companies.
Historical trajectory patterns were cross-referenced against expert panel input to anchor projection assumptions across the modeling period. Segmentation dimensions modeled include sales channel architecture, event type perishability, pricing mechanism selection, and customer sophistication tier. CAGRs were derived from curve-fitting approaches applied to disclosed transaction volumes and revenue run-rates, with algorithmic pricing adoption curves and mobile penetration rates serving as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory enforcement acceleration or primary issuer API standardization delays. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
US Automatic Content Recognition Market
Digital Media
Global Digital Painting Market
Digital Media
Webtoons Market
Digital Media
Pro AV Market
Digital Media
In Flight Entertainment Market
Digital Media
Mexico Webtoons Market
Digital Media
Europe Animation Market
Digital Media
APAC Animation, VFX and Post Production Market
Digital Media
Art App Market
Digital Media
Playout Solutions Market
Digital Media
Online Art Market
Digital Media
Manga Market
Digital Media
Video Content Management Market
Digital Media
North America Webtoons Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
Wedding Photography Market