
 Global Virtual Goods Market | 2026-2036
Global Virtual Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Goods Market Outlook
The EU Digital Services Act is restructuring cost-of-entry calculus for virtual goods platforms operating across European jurisdictions. Tencent Holdings Ltd. leverages its super-app ecosystem to anchor virtual item commerce across multiple entertainment verticals. Epic Games Inc. competes through its Unreal Engine marketplace by controlling creator revenue splits and in-game asset distribution. Valve Corporation dominates PC-based virtual goods via Steam Workshop's entrenched modding economy.
Virtual goods comprise digital assets—skins, in-game currency, non-fungible tokens, and cosmetic items—delivered through server-side rendering and blockchain-verified ownership protocols, serving primarily as monetization layers for interactive entertainment and social platforms. Mobile platforms lead transaction volume due to frictionless payment integration and always-on connectivity, while NFT segments face structural compression from speculative cooldowns and energy-use scrutiny. Freemium monetization captures the widest user base, though subscription models sustain higher per-customer lifetime value in developer and corporate customer tiers.
The EU AI Act and GDPR impose algorithmic transparency and data minimization requirements on recommendation engines that surface virtual goods to users. China's SAMR enforces anti-addiction and spending cap rules for minor-accessible virtual item transactions. South Korea's GRAC maintains age-rating systems that gate certain cosmetic and currency item sales. Stakeholders must monitor evolving cross-border digital asset taxation frameworks and platform liability designations that could fragment unified marketplace operations.
Market Dynamics
Freemium monetization architectures are restructuring value capture across interactive entertainment platforms, embedding microtransaction layers into core gameplay loops and social interaction frameworks.
Growth Catalysts
- Mobile Payment Integration:Frictionless one-tap purchasing systems embedded in smartphone operating systems reduce transaction abandonment rates and expand addressable user bases across emerging markets.
- EU Digital Services Act:Platform liability clarifications create compliance moats that favor established marketplaces with legal infrastructure to absorb regulatory overhead.
- Blockchain Verification Protocols:Distributed ledger technologies enable provable scarcity and cross-platform asset portability, unlocking secondary market liquidity for digital collectibles.
Market Restraints
- Energy-Use Scrutiny:Proof-of-work consensus mechanisms face operational restrictions under EU sustainability frameworks and voluntary platform bans.
- China SAMR Anti-Addiction Rules:Mandatory spending caps and play-time limits for minors compress revenue per user in the world's largest gaming market.
- Input Cost Volatility:Cloud rendering infrastructure and GPU compute pricing fluctuate with semiconductor supply constraints and energy market shocks.
Strategic Opportunities
- India's Digital Payment Rails:UPI infrastructure and localized pricing models open mass-market penetration for cosmetic and currency microtransactions.
- AI-Generated Asset Pipelines:Generative models reduce production costs for personalized skins and dynamic cosmetic items at scale.
- Cross-Reality Commerce:AR-enabled virtual try-on and spatial computing platforms bridge physical retail with digital goods discovery.
Industry Challenges
- Taxonomy Fragmentation:Divergent national classifications of virtual goods as property, currency, or securities create compliance complexity for unified platform operations.
- Skill Scarcity in Live Operations:Shortage of data scientists and economy designers capable of balancing player satisfaction with monetization optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Goods Market |
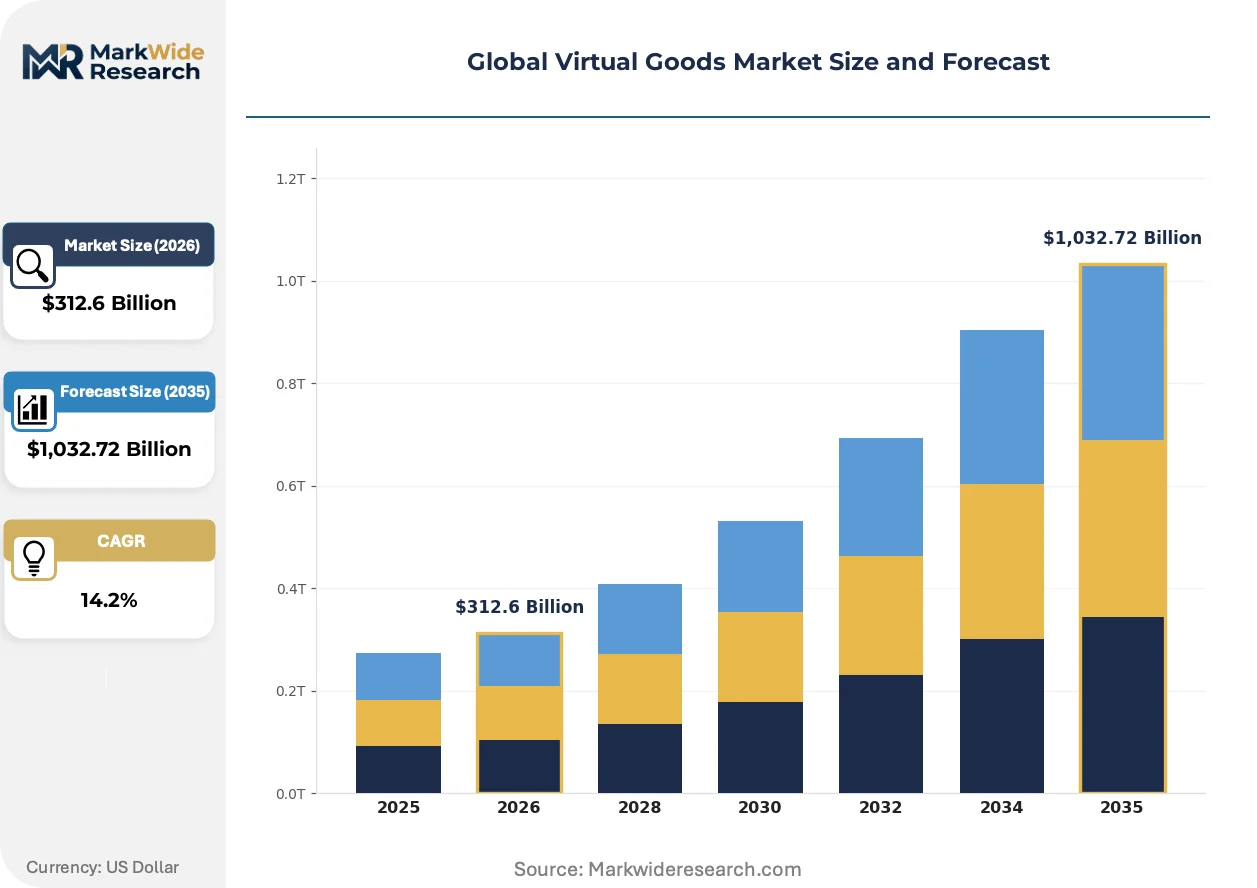
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $1,032.72 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Game Currency, Virtual Items, Skins, NFTs Platform: Mobile, PC, Console, Web Customer Type: Individual Users, Gaming Companies, Developers, Corporates Monetization Model: Freemium, Pay-to-Play, Subscription, Advertising |
| Companies Covered | Tencent Holdings Ltd., Roblox Corporation, Meta Platforms Inc., Epic Games Inc., Valve Corporation, Sony Group Corporation, Microsoft Corporation, NetEase, Inc., Nintendo Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Goods Market Strategic Shifts
Ownership verification mechanisms and algorithmic content generation are redrawing competitive boundaries between centralized platforms and creator-driven marketplaces.
Blockchain-based asset registries are decentralizing provenance tracking and secondary market governance away from platform-controlled databases. Mid-sized studios and independent creators adopt these protocols fastest to bypass revenue-sharing constraints imposed by dominant distribution channels. This architecture is decentralizing control over virtual item economies, compressing margins for intermediaries that previously captured transaction fees and resale commissions.
China's SAMR enforcement of minor protection rules and spending verification systems imposes technical and operational burdens on platform operators. Real-name authentication and parental consent workflows now gate transaction flows, increasing compliance costs but creating barriers to unlicensed competitors. Mobile-first publishers targeting domestic Chinese markets allocate engineering resources toward regulatory infrastructure rather than feature development.
Creator economy participation is shifting procurement of virtual goods from platform-curated storefronts toward direct-to-consumer channels and social commerce integrations. Influencer-driven drops and limited-edition collaborations bypass traditional discovery algorithms, concentrating demand spikes around personality-led releases. South Korean and Japanese markets exhibit this pattern most acutely, where idol and streamer-affiliated cosmetic items command premium pricing through scarcity marketing and community identity signaling.
Global Virtual Goods Market Segmentation
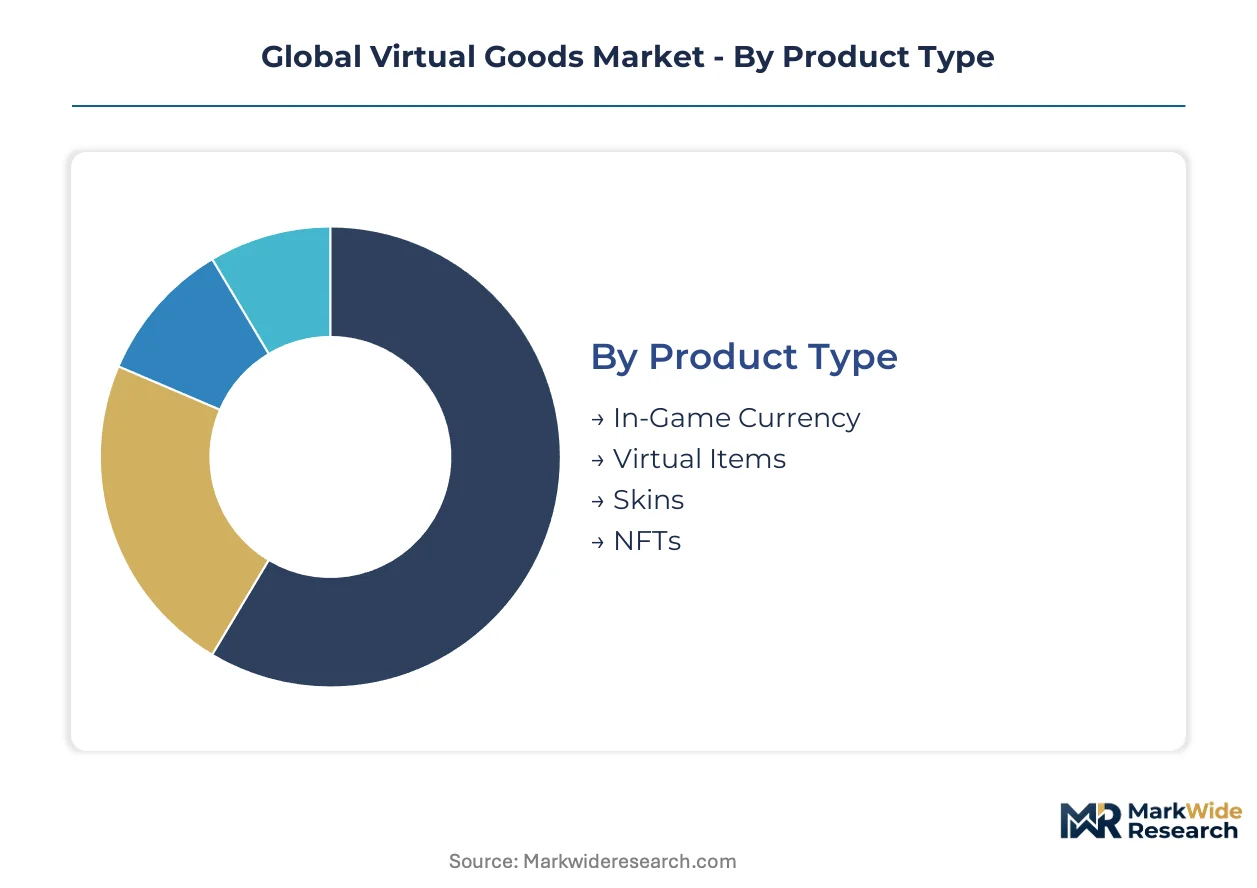
Segmentation in virtual goods markets reveals how payment friction, platform control, and creator economics reshape purchasing behavior across user cohorts. Distinct monetization architectures and platform ecosystems create divergent margin profiles and regulatory exposure that demand targeted strategy.
Product Type:
Buyer decisions hinge on liquidity utility versus aesthetic expression, with fungibility and tradeability determining repeat purchase rates.
- In-Game Currency:Server-issued tokens with fixed exchange rates to fiat, functioning as closed-loop payment rails within single publisher ecosystems. Demand concentrates in mobile titles across South Korea and Japan, where frictionless top-up flows and gacha mechanics drive high-velocity microtransactions.
- Virtual Items:Functional or cosmetic digital assets including weapons, vehicles, and emotes that modify gameplay or social signaling. Developers in the United States prioritize these for seasonal battle passes and limited-time events that sustain engagement loops.
- Skins:Purely aesthetic character and equipment customizations with no mechanical advantage. China's SAMR anti-addiction rules restrict minor access to certain cosmetic tiers, compressing addressable audience for premium vanity items.
- NFTs:Blockchain-verified collectibles enabling cross-platform ownership and secondary market trading. Speculative cooldowns and EU energy-use scrutiny have shifted development focus toward utility-bearing assets rather than pure collectibles.
In-Game Currency leads on scale; NFTs lead on momentum despite regulatory headwinds.
Platform:
Distribution economics vary sharply by hardware control and payment integration depth, with platform owners capturing 15-30% of gross transaction value.
- Mobile:Dominant transaction volume through iOS and Android native billing systems with one-tap authentication. India's UPI infrastructure and localized pricing models are opening mass-market penetration for cosmetic microtransactions.
- PC:Steam Workshop and Epic Games Store anchor modding economies with creator revenue splits. Open distribution allows direct-to-consumer sales that bypass platform fees, attracting mid-sized studios seeking margin preservation.
- Console:Closed ecosystems with strict certification and proprietary payment rails. Japan's Nintendo and Sony marketplaces maintain premium pricing power through hardware-software integration and demographic loyalty.
- Web:Browser-based experiences with wallet-based payments and lower platform taxation. Social commerce integrations and influencer-driven drops are gaining traction in South Korean and Japanese markets.
Mobile commands absolute transaction volume; Web platforms are climbing the fastest as social commerce infrastructure matures.
Customer Type:
Lifetime value calculations diverge by procurement sophistication, with institutional buyers negotiating enterprise licensing against per-seat consumer pricing.
- Individual Users:Discretionary purchasers driven by social signaling and gameplay progression. Freemium models capture the widest base, though per-customer spend remains modest outside whale cohorts.
- Gaming Companies:Publishers and studios procuring asset packs, middleware, and licensed IP for title development. These buyers prioritize pipeline efficiency and rights clearance speed over unit cost.
- Developers:Independent creators and mid-sized studios sourcing modular assets and tool subscriptions. AI-generated asset pipelines are reducing production costs for personalized content at scale.
- Corporates:Brands and enterprises acquiring virtual goods for marketing activations, employee engagement, and metaverse presence. B2B procurement cycles emphasize compliance documentation and SLA guarantees.
Individual Users generate the steepest expansion trajectory; Corporates are gaining share fastest as brand marketing budgets migrate to virtual environments.
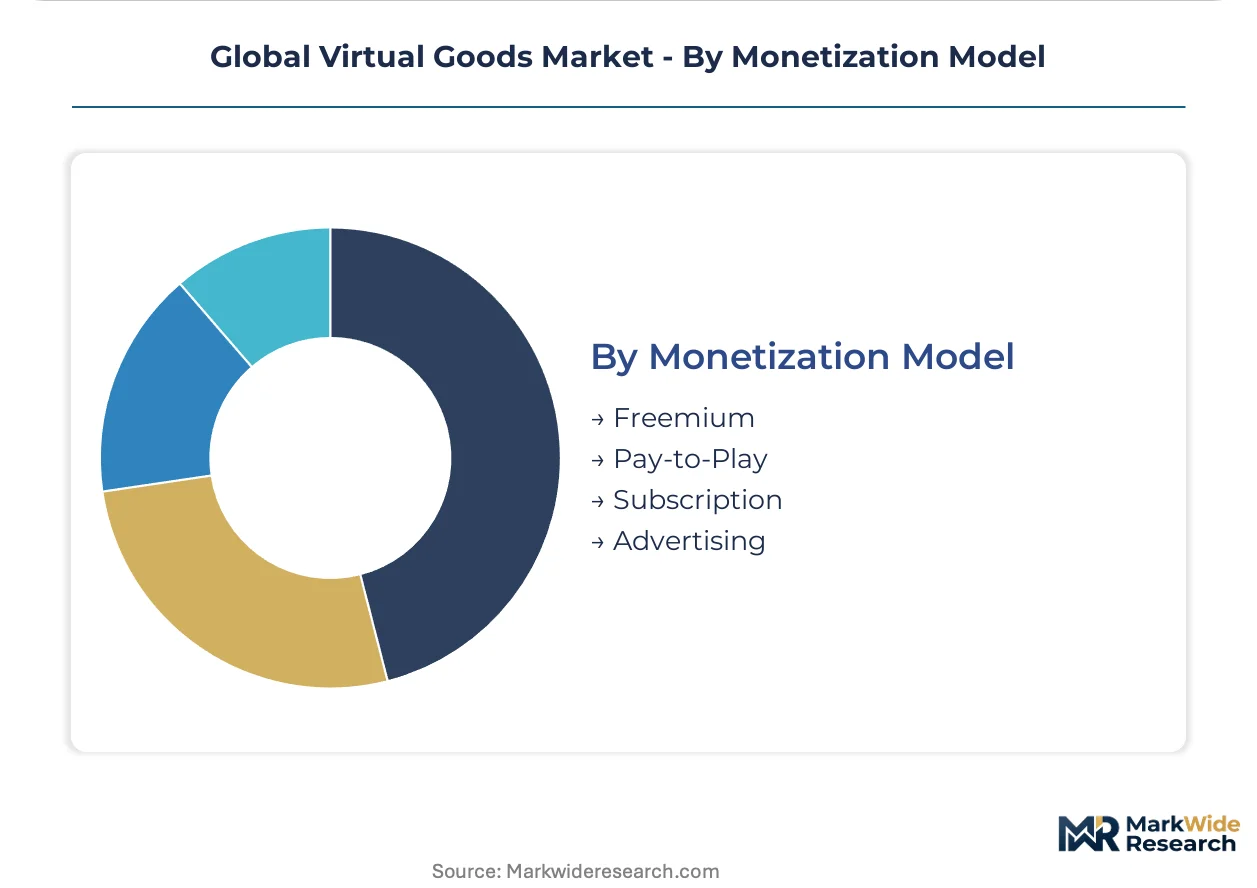
Monetization Model:
Revenue predictability versus user acquisition efficiency shapes model selection, with hybrid architectures increasingly common across successful platforms.
- Freemium:Zero entry price with layered microtransaction gates for progression acceleration and cosmetic access. This model sustains the largest installed bases across emerging markets with mobile-first distribution.
- Pay-to-Play:Upfront purchase requirement with optional post-sale content. PC and console markets in the United States and Western Europe retain preference for this model among core gamer demographics.
- Subscription:Recurring revenue for bundled content libraries and battle pass structures. Higher per-customer lifetime value attracts developer and corporate customer tiers seeking predictable budgeting.
- Advertising:Rewarded video and playable ads that grant virtual currency or items. India's cost-sensitive mobile markets exhibit strongest adoption, with localized ad networks optimizing fill rates.
Freemium dominates addressable reach; Subscription models are expanding most quickly as service-oriented architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Game economy designers and live operations specialists cluster in Seoul, Shenzhen, and San Francisco, anchoring regional innovation in virtual goods monetization. Their expertise concentrates near dominant platform operators and high-velocity payment infrastructure.
China
MIIT and SAMR enforcement of real-name authentication and minor spending caps reshape transaction architecture for domestic publishers. Shanghai and Shenzhen studios redirect engineering resources toward compliance infrastructure. Shenzhen's Tencent ecosystem anchors super-app commerce across entertainment verticals.
South Korea
GRAC age-rating systems gate cosmetic item sales while Seoul-based idol economy drives influencer-affiliated virtual goods. The Game Rating and Administration Commission mandates technical verification for gacha probability disclosure. Busan-Ulsan corridor hosts mid-sized studios adopting blockchain asset protocols.
United States
FTC scrutiny of dark patterns in microtransaction design elevates legal risk for freemium architects. Washington State and California concentrate PC platform operators and creator marketplace infrastructure. Epic Games' Unreal Engine marketplace in North Carolina exemplifies creator revenue split control.
Japan
METI guidelines on virtual currency classification intersect with Consumer Affairs Agency oversight of gacha mechanics. Tokyo and Osaka publishers prioritize seasonal collaboration events with anime and idol IP. Akihabara-to-Shibuya corridor sustains premium pricing for scarcity-driven cosmetic drops.
India
RBI oversight of prepaid payment instruments and UPI infrastructure enables frictionless microtransaction rails. Bengaluru and Hyderabad studios localize pricing models for cost-sensitive mobile markets. India's digital payment rails open mass-market penetration for cosmetic and currency transactions.
Global Virtual Goods Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across platform, engine, and marketplace layers. The structure tiers between infrastructure owners capturing distribution rents and creator-economy intermediaries seeking margin preservation. Three archetypes dominate: super-app ecosystems bundling virtual commerce, engine-integrated marketplaces controlling asset pipelines, and open-platform operators monetizing modding communities. Competitive moves center on revenue split renegotiation and cross-platform asset portability claims.
Within the super-app ecosystem tier, Tencent Holdings Ltd. and NetEase, Inc. exemplify platform consolidation across entertainment verticals. Epic Games Inc. occupies a position anchoring creator marketplace economics through engine-integrated distribution. Valve Corporation represents the open-platform archetype, monetizing user-generated content via entrenched PC community infrastructure.
| Leading Market Players |
|---|
| Tencent Holdings Ltd. |
| Roblox Corporation |
| Meta Platforms Inc. |
| Epic Games Inc. |
| Valve Corporation |
| Sony Group Corporation |
| Microsoft Corporation |
| NetEase, Inc. |
| Nintendo Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU energy-use scrutiny and China's dual carbon goals gate qualified supply for blockchain-verified virtual goods, restricting premium-tier pricing access to publishers with compliant server infrastructure and green hosting certifications. This environmental mandate compresses margins for high-fidelity asset rendering while rewarding platforms that absorb carbon-offset costs into subscription bundles.
Pricing Analysis
Bundled subscription services versus unbundled per-transaction microtransactions split the pricing architecture across platform tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by content exclusivity and cross-platform portability rights. Price differentiation hinges on creator revenue split terms and regional payment rail integration depth. Cost compression in the economy tier intensifies because India's UPI infrastructure enables sub-dollar transaction floors. Individual mobile users in emerging markets exhibit highest price sensitivity; corporate metaverse activations show lowest sensitivity due to brand marketing budget elasticity.
Supply Chain Analysis
Returns and account recovery flows for disputed virtual item transactions create reverse-logistics complexity distinct from physical goods, requiring automated rollback protocols and blockchain state reversion capabilities. Supply concentrates in China, South Korea, and the United States for cloud rendering infrastructure and GPU compute clusters. Raw material dependencies span semiconductor fabrication, data center energy contracts, and low-latency fiber connectivity. Single-source vulnerability around NVIDIA's AI-training silicon creates concentration risk for generative asset pipelines. Distribution runs through platform-native storefronts with 15-30% revenue sharing, though Web-based wallet payments bypass these tolls.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in virtual goods hinges on AI-generated asset pipelines collapsing production costs for personalized content, while premium-tier subscription bundles capture enterprise marketing budgets shifting from physical to virtual activations.
For Market Incumbents: Cement platform stickiness through exclusive IP collaborations and battle pass architectures that extend engagement loops. Deepen backward integration into proprietary rendering infrastructure to offset cloud compute volatility. Valve Corporation's Steam Workshop model demonstrates how creator revenue split control defends against blockchain-based disintermediation threats. For New Entrants and Emerging Players: Social commerce integrations offer the lowest-friction route to bypass established platform discovery algorithms. India's cost-sensitive mobile market presents the most penetrable geography, with UPI-native cosmetic microtransactions underserved by premium Western publishers. Target influencer-affiliated drops in South Korea and Japan where idol economy demand concentrates around scarcity-driven releases. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized creator marketplace platforms because fragmented studio tooling creates acquisition synergies around shared asset pipelines and cross-title economies. Five-to-ten year viability favors operators with regulatory infrastructure already deployed for China's SAMR minor-protection rules. Monitor EU Digital Services Act enforcement patterns as the signal for compliance-moat valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Generated Asset Pipeline Integration | Generative models from Midjourney and Stability AI collapse skin production costs for personalized cosmetics at scale. |
| Cross-Platform Asset Portability Protocol | Blockchain verification enables secondary market liquidity beyond Steam Workshop's closed ecosystem. |
| Regulatory Infrastructure Pre-Build | SAMR-compliant real-name authentication systems create barriers to unlicensed competitors in China. |
| Creator Revenue Split Renegotiation | Epic Games' Unreal Engine marketplace demonstrates margin preservation through engine-integrated distribution control. |
| Social Commerce Channel Expansion | Influencer-driven drops in Seoul and Tokyo bypass platform algorithms, concentrating demand around personality-led releases. |
Study Parameters
Direct dialogue with live operations directors, game economy designers, platform engineering leads, and regulatory compliance officers grounded the qualitative foundation. Secondary validation drew from SEC filings of publicly traded publishers, GRAC probability disclosure mandates, EU DSA implementation guidance, and UPI transaction volume reports from India's NPCI. Bottom-up triangulation across individual title monetization data and top-down reconciliation against platform-reported segment revenues ensured cross-verification.
Bottom-up modeling of transaction velocity by platform and monetization model anchored the analytical lens, with top-down constraint from aggregate publisher revenue disclosures. Segmentation dimensions spanned product type, platform ecosystem, customer archetype, and monetization architecture. CAGRs were derived from fitted growth curves across the projection horizon, with explicit modeling of China's minor spending cap impacts and India's payment infrastructure penetration curves.
The model assumes a particular technology adoption path; alternative pathways for generative AI asset generation would alter the outlook if diffusion outpaces regulatory frameworks for copyright and likeness rights. Forecasts reflect underlying assumptions about freemium conversion rates and platform fee stability. Practitioners should monitor EU AI Act enforcement timelines and China's SAMR rule evolution for early signals of compliance cost inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Global Animation Market
Digital Media
Europe Online Video Platform Market
Digital Media
Photography Services Market
Digital Media
Digital Content Creator Market
Digital Media
Sound Effects Services Market
Digital Media
Germany Animation, VFX and Post Production Market
Digital Media
Anime Derivatives Market
Digital Media
APAC Animation, VFX and Post Production Market
Digital Media
Global Online Movie Ticketing Services Market
Digital Media
Animation Services Market
Digital Media
Sports Graphics Market
Digital Media
Manga Market
Digital Media
In Flight Entertainment Market
Digital Media
Middle East and Africa Animation Market
Digital Media
Art App Market
Digital Media
Indonesia Digital Media Market