
 United States Online Gambling Market | 2026-2036
United States Online Gambling Market Size, Share, and Industry Trends Forecast 2026-2036
United States Online Gambling Market Intelligence
Asset-light platform licensing is rewriting competitive dynamics for new entrants lacking legacy casino infrastructure. DraftKings leverages its daily fantasy sports database to cross-sell casino products. BetMGM anchors its position through integrated resort brand recognition. Flutter Entertainment competes via its FanDuel unit's technology stack and market breadth.
United States online gambling encompasses digital wagering on casino games, sports events, and poker tournaments conducted through internet-connected devices, requiring geolocation verification, encryption protocols, and real-time odds engines to ensure regulatory compliance and fair play. Its primary commercial purpose is to capture entertainment expenditure from consumers seeking convenience and instant access outside physical casino premises. Slots and live dealer formats command disproportionate revenue share due to their immersive retention mechanics. Mobile platforms dominate session volume as native apps reduce friction for in-play betting. Cryptocurrency payment methods attract privacy-focused segments though regulatory scrutiny limits mainstream adoption.
The Department of Justice Wire Act interpretation, state gaming commission licensing regimes, and IRS reporting requirements collectively shape operator obligations and consumer protections across jurisdictions. New Jersey Division of Gaming Enforcement standards influence compliance benchmarks adopted by emerging state regulators. Stakeholders must monitor federal appellate rulings and state ballot initiatives that could abruptly expand or contract addressable market access.
Market Dynamics
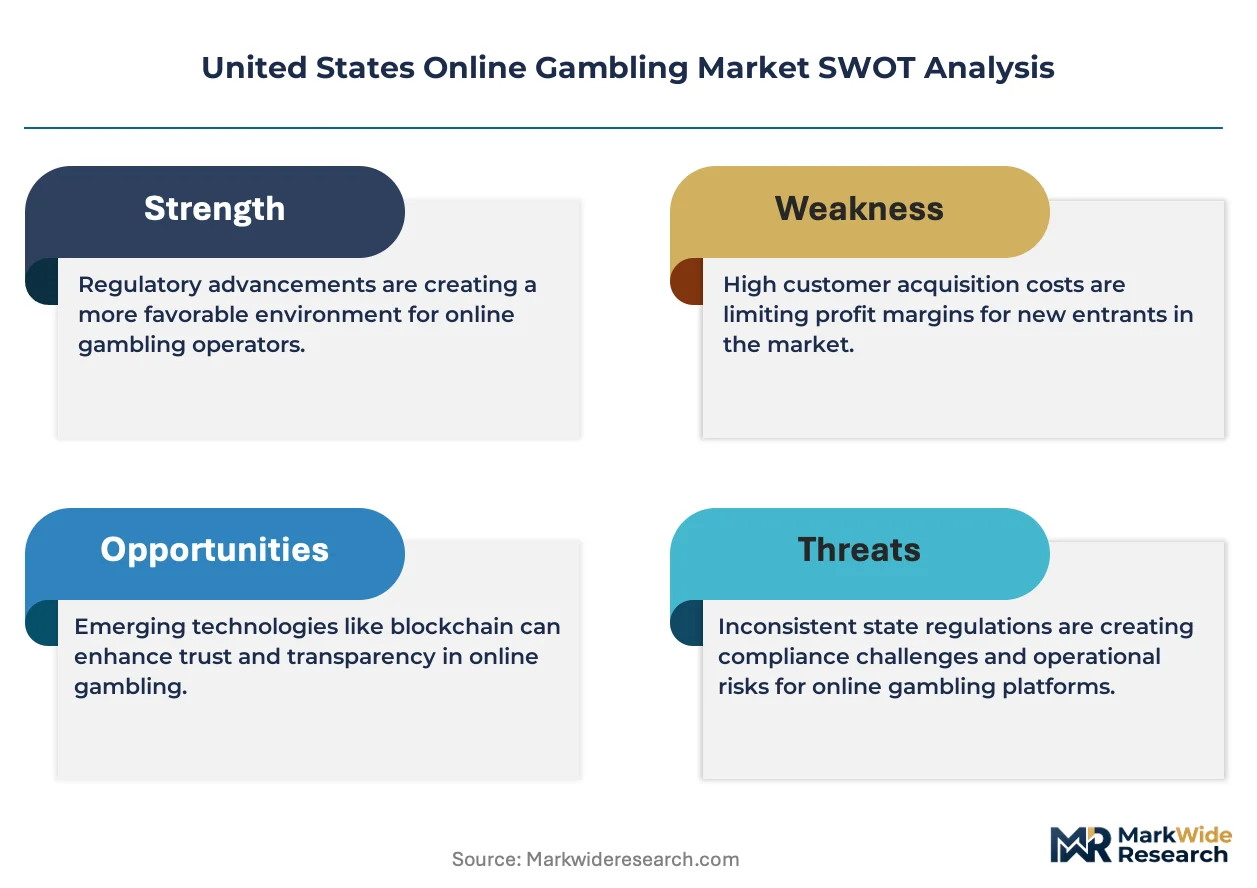
State-by-state legalization momentum generates patchwork regulatory terrain that fragments operator economics and forces platform providers to engineer jurisdiction-specific compliance stacks rather than uniform national deployments.
Growth Catalysts
- Mobile-native wagering interfaces:Native iOS and Android applications reduce friction for in-play betting, driving session frequency among 21-34 age demographics. Geolocation verification APIs enable real-time compliance with state boundary restrictions.
- Wire Act reinterpretation clarity:Federal appellate rulings limiting the Department of Justice's 2018 opinion scope permit interstate poker liquidity pooling and shared progressive jackpots across state lines.
- Mature licensing regimes:New Jersey Division of Gaming Enforcement standards provide regulatory templates adopted by Pennsylvania, Michigan, and emerging state commissions, accelerating operator market entry timelines.
Market Restraints
- Payment processor concentration:Visa and Mastercard dominate deposit flows, with chargeback liability concentrated among three national banks that impose reserve requirements on gambling merchants.
- Server infrastructure costs:Latency-sensitive live dealer streaming demands edge computing deployments within 50 miles of each regulated state population center.
- Cross-state tax arbitrage limits:Differential state tax rates on gross gaming revenue prevent pricing standardization, fragmenting promotional economics across jurisdictions.
Strategic Opportunities
- Underpenetrated Midwest markets:Ohio and Illinois legislative frameworks create addressable populations exceeding 25 million adults with established sports culture and disposable entertainment expenditure.
- Cryptocurrency payment rails:Bitcoin and stablecoin deposit methods attract privacy-focused segments in states with permissive digital asset frameworks, though federal banking scrutiny constrains mainstream rollout.
- Social casino convergence:Free-to-play slot mechanics on social platforms create acquisition funnels convertible to real-money wagering where legal, leveraging existing user engagement data.
Industry Challenges
- Compliance engineering talent scarcity:Full-stack developers with expertise in geofencing, KYC automation, and responsible gaming algorithm design command premium compensation in Boston and Denver tech corridors.
- Legacy casino system integration:Land-based operators migrating online must reconcile player reward databases, slot accounting systems, and property management platforms with cloud-native wagering architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Online Gambling Market |
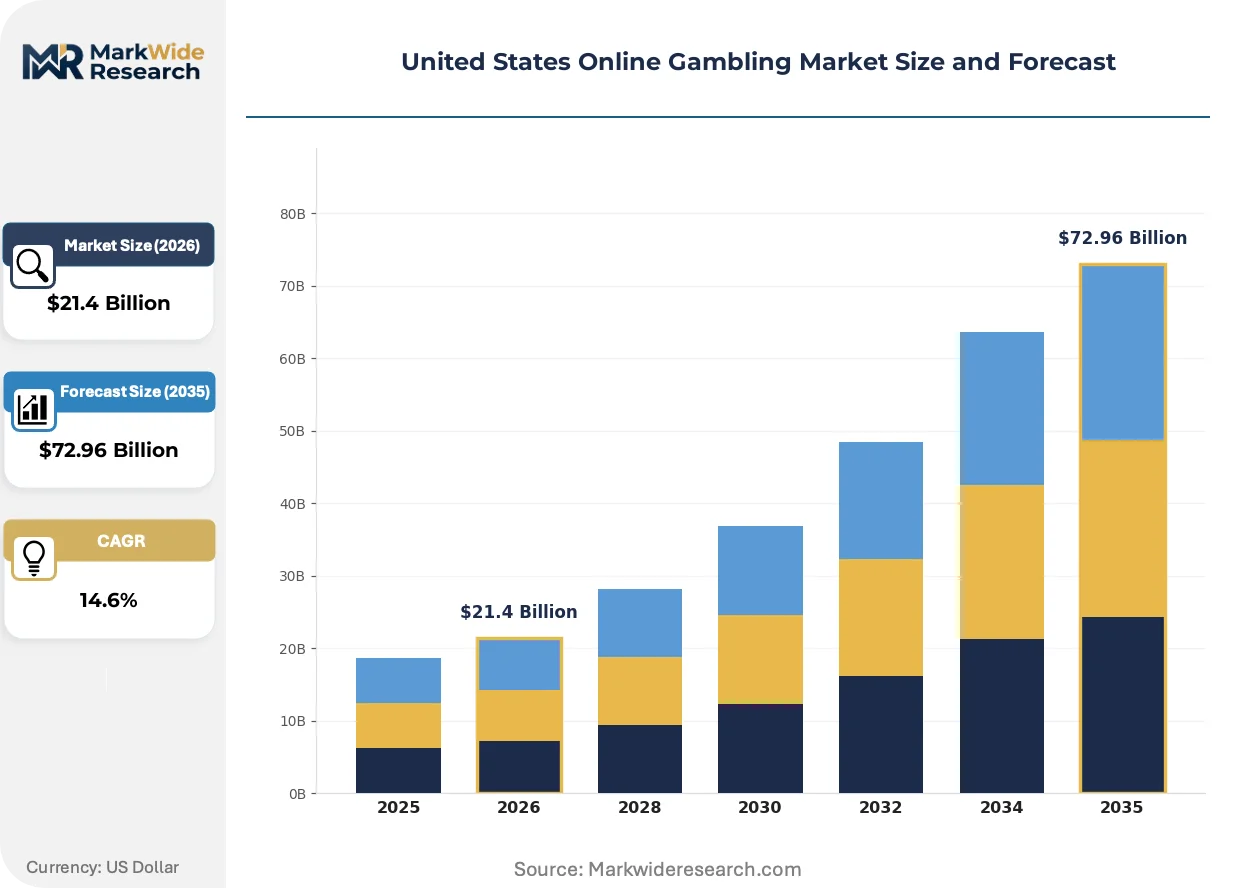
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $72.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Slots, Table Games, Poker, Live Dealer Customer Demographics: Millennials, Gen X, Baby Boomers, High Rollers Platform Type: Mobile, Desktop, Tablet, Hybrid Payment Method: Credit Card, E-Wallet, Cryptocurrency, Bank Transfer |
| Companies Covered | BetMGM, Caesars Digital, DraftKings, Hard Rock Digital, Penn Entertainment, Rush Street Interactive, Golden Nugget, Bet365, Flutter Entertainment, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Online Gambling Market Strategic Shifts & Innovations
Artificial intelligence personalization engines and blockchain-based provable fairness mechanisms are compressing operator margins while elevating consumer expectations for transparency and real-time engagement.
Machine learning recommendation systems analyze wagering patterns, session duration, and game preference vectors to dynamically adjust bonus offers and loss-limit interventions. Tier-one operators deploy these engines across 80% of active player accounts. Predictive churn modeling is rendering obsolete the legacy monthly promotional calendar based on fixed deposit-match percentages.
The Department of Justice Wire Act enforcement posture continues reshaping interstate operational architecture. The 2018 Office of Legal Policy memorandum reversal and subsequent circuit court litigation created uncertainty around multi-state poker liquidity. Poker tournament platforms in Nevada and Delaware maintain segregated player pools pending definitive federal resolution.
Younger demographics demonstrate preference for micro-betting markets—individual pitch outcomes, drive results, corner kicks—rather than traditional pre-game moneyline wagers. Sportsbook operators reconfigure odds engine latency to serve these markets, with sub-second price updates replacing the 15-second refresh cycles standard through 2020. This behavioral shift concentrates in New Jersey and Pennsylvania mobile app user bases.
United States Online Gambling Market Segmentation
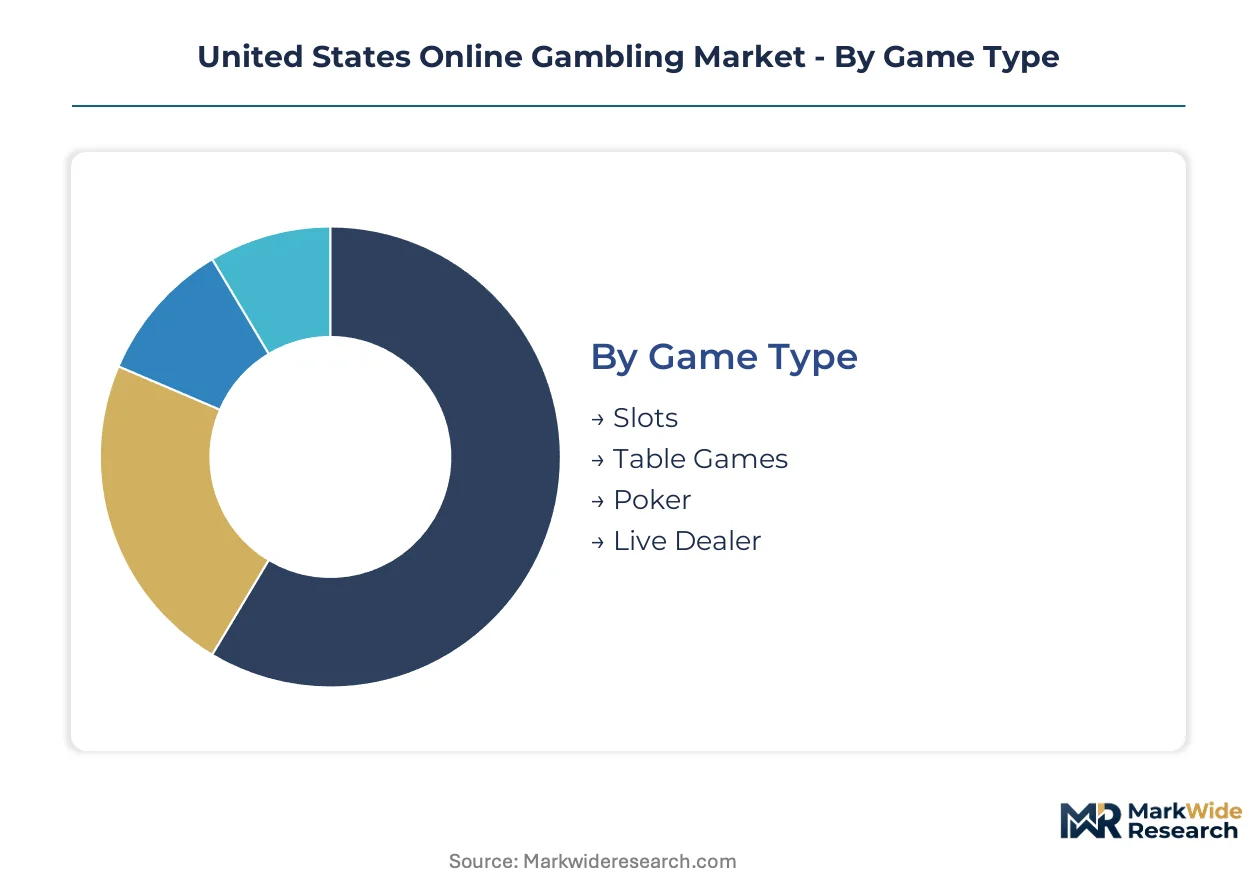
Segmentation in United States online gambling reveals how platform architecture and player behavior diverge across regulatory boundaries. Operators engineer distinct technology stacks and marketing approaches for each slice, driving margin structure variation that rewards specialized positioning.
Game Type:
After-sales service intensity runs highest where player lifetime value depends on continuous engagement mechanics and personalized retention interventions.
- Slots:Digital reel configurations with randomized outcome algorithms and progressive jackpot networking dominate revenue concentration. Demand clusters in New Jersey and Pennsylvania mobile apps, where rapid spin cycles and immersive audiovisual retention mechanics sustain session frequency among 21-34 age demographics. Bonus buy features and megaways mechanics accelerate player acquisition costs.
- Live Dealer:Real-time video streaming of human croupiers operating physical tables demands sub-200-millisecond latency infrastructure. Michigan and New Jersey operators deploy edge computing nodes within state boundaries to serve this format, where authenticity-seeking segments accept higher minimum wagers for social presence.
- Table Games:Digital blackjack, roulette, and baccarat variants with automated RNG outcomes.
- Poker:Peer-to-peer tournament and cash game formats constrained by segregated state liquidity pools.
By volume, Slots leads. By growth pace, Live Dealer is ahead.
Customer Demographics:
Cost tier stratification separates mass-market recreational players from whale economics that subsidize promotional spend across the player base.
- Millennials:Digital-native cohort aged 28-43 demonstrating preference for micro-betting markets and social sharing features. Concentrated in Pennsylvania and Michigan, this segment drives in-play wagering volume through native mobile interfaces.
- High Rollers:VIP players generating disproportionate gross gaming revenue through elevated table limits and personalized concierge service. New Jersey operators dedicate account management resources to this thin slice, where single-session losses can exceed median household monthly income.
- Gen X:Players aged 44-59 with established credit profiles and preference for traditional casino game formats.
- Baby Boomers:Older demographic segment migrating from land-based properties to simplified mobile interfaces.
By volume, Millennials lead. By value concentration, High Rollers is ahead.
Platform Type:
Application maturity separates native experiences from browser-dependent access modes that constrain real-time wagering functionality.
- Mobile:Native iOS and Android applications with geolocation verification, push notification delivery, and biometric authentication. Dominates session volume across all regulated states, with New Jersey Division of Gaming Enforcement mandating specific technical standards for app store distribution.
- Desktop:Browser-based access through responsive web design, retaining relevance for multi-table poker and extended research-intensive sports betting sessions.
- Tablet:Intermediate form factor capturing evening home-based leisure occasions with touch-optimized interfaces.
- Hybrid:Cross-platform account synchronization enabling seamless session handoff between devices.
By volume, Mobile leads. By revenue per session, Desktop is ahead.
Payment Method:
Processing cost tier and approval velocity differentiate deposit channels that directly impact conversion funnels and player acquisition economics.
- Credit Card:Visa and Mastercard networks dominate deposit flows despite elevated decline rates for gambling-coded transactions. Three national banks concentrate merchant processing risk, imposing reserve requirements that strain operator working capital.
- E-Wallet:PayPal, Venmo, and specialized gaming wallets provide intermediary abstraction that shields bank statements from gambling descriptors. Pennsylvania and New Jersey adoption rates exceed national averages due to early regulatory clarity.
- Cryptocurrency:Bitcoin and stablecoin rails attract privacy-focused segments in states with permissive digital asset frameworks.
- Bank Transfer:ACH and wire mechanisms preferred by high-value players seeking elevated deposit ceilings.
By volume, Credit Card leads. By growth pace, E-Wallet is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States online gambling market operates as a closed domestic system with minimal cross-border service flows, as federal and state regulations prohibit offshore operator participation and mandate intrastate platform deployment.
New Jersey
The New Jersey Division of Gaming Enforcement maintains the nation's most mature regulatory template, with Atlantic City casino licensees anchoring digital platform provision. Mobile wagering generates the majority of session volume, while geolocation verification APIs ensure strict intrastate boundary enforcement. The Meadowlands corridor hosts server infrastructure clusters serving the broader Mid-Atlantic region.
Pennsylvania
Pennsylvania Gaming Control Board licensing frameworks attract multi-state operators seeking scale economies, with Philadelphia and Pittsburgh metropolitan areas concentrating player acquisition spend. The state's 54% tax rate on online slots compresses operator margins while funding problem gambling programs. Mount Airy and Parx Casino anchor the land-based-to-digital migration pipeline.
Michigan
The Michigan Gaming Control Board's 2021 regulatory launch created immediate competitive density, with Detroit's three commercial casinos and tribal gaming compacts enabling rapid platform deployment. The state's 8.4 million adult population supports standalone operator economics without interstate liquidity pooling. Grand Rapids and Ann Arbor clusters drive secondary market penetration.
Illinois
Illinois Gaming Board regulations permit sports wagering through licensed casinos and racetracks, with Chicago's metropolitan density attracting platform provider investment. The state's delayed casino licensing timeline constrains full iGaming expansion. Rockford and Springfield sub-markets await regulatory clarity for comprehensive digital casino authorization.
Ohio
The Ohio Casino Control Commission's 2023 sports betting launch established regulatory infrastructure for future iGaming expansion, with Cleveland and Cincinnati urban centers demonstrating strong wagering propensity. The state's 11.7 million residents represent underpenetrated addressable demand. Columbus hosts compliance technology vendors serving emerging Midwest markets.
United States Online Gambling Market Key Industry Players
On the supply side, the industry is consolidating around platform providers with multi-state licensing scale and proprietary technology stacks. Three to five operators capture disproportionate revenue share in each regulated state, while smaller licensed properties rely on third-party platform provision. Strategic archetypes include daily fantasy sports crossovers, integrated resort digital extensions, and European multinational entrants. Dominant competitive moves encompass brand licensing partnerships with professional sports leagues and exclusive market access agreements with tribal gaming authorities.
Within the integrated resort digital extension tier, BetMGM and Caesars Digital exemplify operators leveraging physical casino brand recognition to anchor online player acquisition. DraftKings occupies a distinct position as a daily fantasy sports crossover archetype, translating its established user database into casino and sports wagering verticals. These three entities represent the primary competitive anchors shaping promotional intensity and technology investment benchmarks across state markets.
| Leading Market Players |
|---|
| BetMGM |
| Caesars Digital |
| DraftKings |
| Hard Rock Digital |
| Penn Entertainment |
| Rush Street Interactive |
| Golden Nugget |
| Bet365 |
| Flutter Entertainment |
| Others |
Cost & Logistics Intelligence
Atlantic City server clusters anchor platform infrastructure capacity for the Mid-Atlantic wagering corridor, concentrating compliance engineering talent and edge computing deployment costs that downstream operators pass through as platform licensing fees. New Jersey Division of Gaming Enforcement technical standards impose uniform security protocols that prevent price competition on baseline compliance, shifting differentiation toward player acquisition spend and retention algorithm sophistication.
Pricing Analysis
High-roller VIP segments anchor tiered revenue-share structures that subsidize mass-market promotional intensity. Pricing stratifies across premium concierge-managed accounts, standard automated loyalty tiers, and economy no-frills entry points. Cost compression in the standard tier is intensifying because Pennsylvania's 54% slots tax rate forces operators to recover margin through reduced bonus generosity. Recreational players demonstrate highest price sensitivity to deposit-match terms, while VIP accounts negotiate bespoke loss-back guarantees insulated from headline promotional erosion.
Supply Chain Analysis
Regulatory fragmentation between New Jersey, Pennsylvania, and Michigan dominates supply chain architecture, forcing redundant state-boundary server deployments rather than consolidated national infrastructure. Raw material dependencies center on geolocation verification APIs, real-time odds engines, and live dealer streaming codecs. Single-source vulnerability concentrates in Visa and Mastercard payment rails, where three national banks control merchant processing access. Distribution runs through native iOS and Android app stores subject to state-specific technical certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile-native wagering interfaces and state-by-state legalization momentum constitute a regulatory-technology inflection reshaping competitive economics. Platform providers must engineer jurisdiction-specific compliance stacks rather than uniform deployments, fragmenting capital allocation and rewarding specialized positioning.
For Market Incumbents: Entrench market position through exclusive tribal gaming compacts and professional sports league brand licensing that locks out later entrants. Deepen backward integration into proprietary geolocation verification technology to reduce third-party API dependency. Accelerate responsible gaming algorithm R&D to preempt federal compliance mandates that could disrupt promotional mechanics. For New Entrants and Emerging Players: Ohio and Illinois legislative frameworks offer addressable populations exceeding 25 million adults with established sports culture and minimal incumbent platform saturation. Target social casino convergence as the lowest-friction acquisition funnel, converting free-to-play engagement data into real-money wagering where regulatory authorization permits. Pursue white-label platform partnerships to bypass multi-year licensing timelines in mature markets. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because state-by-state licensing creates durable moats around early-mover platform providers. Target asset-light technology specialists with multi-state compliance automation and proprietary player databases. Monitor federal appellate Wire Act rulings as the critical inflection signal for interstate poker liquidity pooling economics.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-State Licensing Scale-Up | Pennsylvania Gaming Control Board templates accelerate entry into Ohio and Illinois regulatory frameworks. |
| Proprietary Geolocation Technology | In-house verification APIs reduce third-party dependency and improve compliance margin capture. |
| Tribal Gaming Compact Expansion | Michigan tribal compacts demonstrate pathway to immediate platform deployment without commercial casino anchor. |
| Social Casino Acquisition Funnel | Free-to-play slot mechanics convert existing user engagement data into real-money wagering pipelines. |
| Live Dealer Edge Infrastructure | Sub-200-millisecond latency nodes within state boundaries enable premium table minimums in Michigan and New Jersey. |
Research Approach
A standing panel of platform engineering directors, state gaming commission compliance officers, sportsbook product managers, and payment processor risk executives provided ongoing calibration across the research window. Primary fieldwork combined structured interviews with secondary validation against New Jersey Division of Gaming Enforcement licensing records, Pennsylvania Gaming Control Board revenue disclosures, Michigan Gaming Control Board operator filings, and SEC 10-K submissions from publicly traded platform providers. Bottom-up state-level revenue modeling and top-down national market sizing were triangulated against mobile app download analytics and geolocation verification traffic data.
Scenario-bracketing anchored the analytical framework, with high-growth and regulatory-constraint cases bounding the projection horizon. Segmentation dimensions modeled include game type, customer demographic cohort, platform access mode, and payment method preference. CAGRs were derived from historical state launch trajectories and comparable market maturation patterns. Industry-specific forecast inputs incorporated state legislative session calendars and tribal compact renegotiation timelines.
Practitioners should monitor federal Wire Act appellate rulings, state ballot initiative outcomes, and payment processor policy shifts for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Content Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
Secondary Ticket Market
Digital Media
Digital Music Content Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
Saudi Arabia Webtoons Market
Digital Media
Global Digital Painting Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
China Webtoons Market
Digital Media
Global ACGN Market
Digital Media
Media and Entertainment Market
Digital Media
India Webtoons Market
Digital Media
Digital Content Locker Market
Digital Media
Social TV Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Video Content Management Market